
 Silicone Oil Market | 2026-2036
Silicone Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Oil Market Intelligence
Modular formulation packs is rebalancing procurement patterns across the silicone oil value chain. Dow Inc. leverages its integrated siloxane backbone capacity to sustain cost advantages in industrial fluid grades. Shin-Etsu Chemical Co., Ltd. anchors its position through captive monomer supply and precision viscosity control. Wacker Chemie AG differentiates via specialty emulsions targeting European cosmetics manufacturers.
Silicone oil comprises linear polydimethylsiloxane chains with viscosities spanning 0.65 to 2,000,000 centistokes, synthesized through hydrolysis and equilibration of chlorosilanes. Its primary function spans thermal stability, lubricity, and surface tension modification across industrial and consumer systems. Fluids dominate volume throughput in industrial lubrication, where high-temperature endurance commands premium positioning. Emulsions capture accelerating share in cosmetics as water-dispersible formats displace neat oils in rinse-off applications. Gels occupy niche margin pools in pharmaceutical wound-care and topical delivery systems.
REACH registration requirements in Europe constrain unregistered silicone fluid imports while FDA 21 CFR oversight shapes medical-grade certification pathways in the United States. China's GB standards and evolving MEE environmental compliance protocols redirect local producers toward low-VOC emulsion technologies. Stakeholders must calibrate R&D allocation between high-purity pharmaceutical grades and cost-optimized textile processing fluids as regulatory divergence between jurisdictions widens formulation complexity.
Market Dynamics
REACH registration deadlines in Europe and FDA 21 CFR pathway revisions are fragmenting silicone oil formulation standards, forcing manufacturers to maintain parallel certification tracks for medical-grade and industrial-grade product lines.
Growth Catalysts
- Personal care emulsion demand:Cosmetics formulators in South Korea and France are substituting neat silicone oils with water-dispersible emulsion formats in rinse-off haircare and skincare products.
- REACH compliance deadlines:European ECHA registration requirements for low molecular weight siloxanes are redirecting import flows toward registered producers with full dossier submissions.
- Textile processing expansion:China's Zhejiang and Jiangsu province dyeing hubs are absorbing higher volumes of amino-functional silicone softeners for synthetic fabric finishing.
Market Restraints
- Chlorosilane feedstock volatility:Silicon metal price swings and energy costs at carbothermal reduction facilities in Norway and Brazil transmit directly to siloxane monomer economics.
- Substitution by bio-based alternatives:Plant-derived emollients and natural oils are capturing share in European clean-label cosmetics where silicone-free positioning commands retail shelf placement.
- Regulatory fragmentation:Divergent VOC limits between California's CARB standards, China's MEE protocols, and EU F-Gas Regulation force redundant reformulation cycles.
Strategic Opportunities
- Pharmaceutical-grade wound care:Hydrophobic silicone gel formulations for scar management and drug-eluting transdermal patches remain underpenetrated in India's hospital procurement channels.
- Dual carbon alignment in China:GB standard updates favoring low-emission emulsion technologies create first-mover positioning for producers with aqueous-phase process expertise.
- Precision viscosity customization:Convergence of computational fluid dynamics modeling with continuous reactor control enables lot-size-one production for specialty lubricant blenders.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in silicone polymerization, cosmetic regulatory science, and pharmaceutical cGMP documentation command premium compensation.
- Medical device certification timelines:FDA 510(k) pathway durations for novel silicone oil-based drug delivery systems extend development-to-revenue cycles beyond typical industrial fluid product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Oil Market |
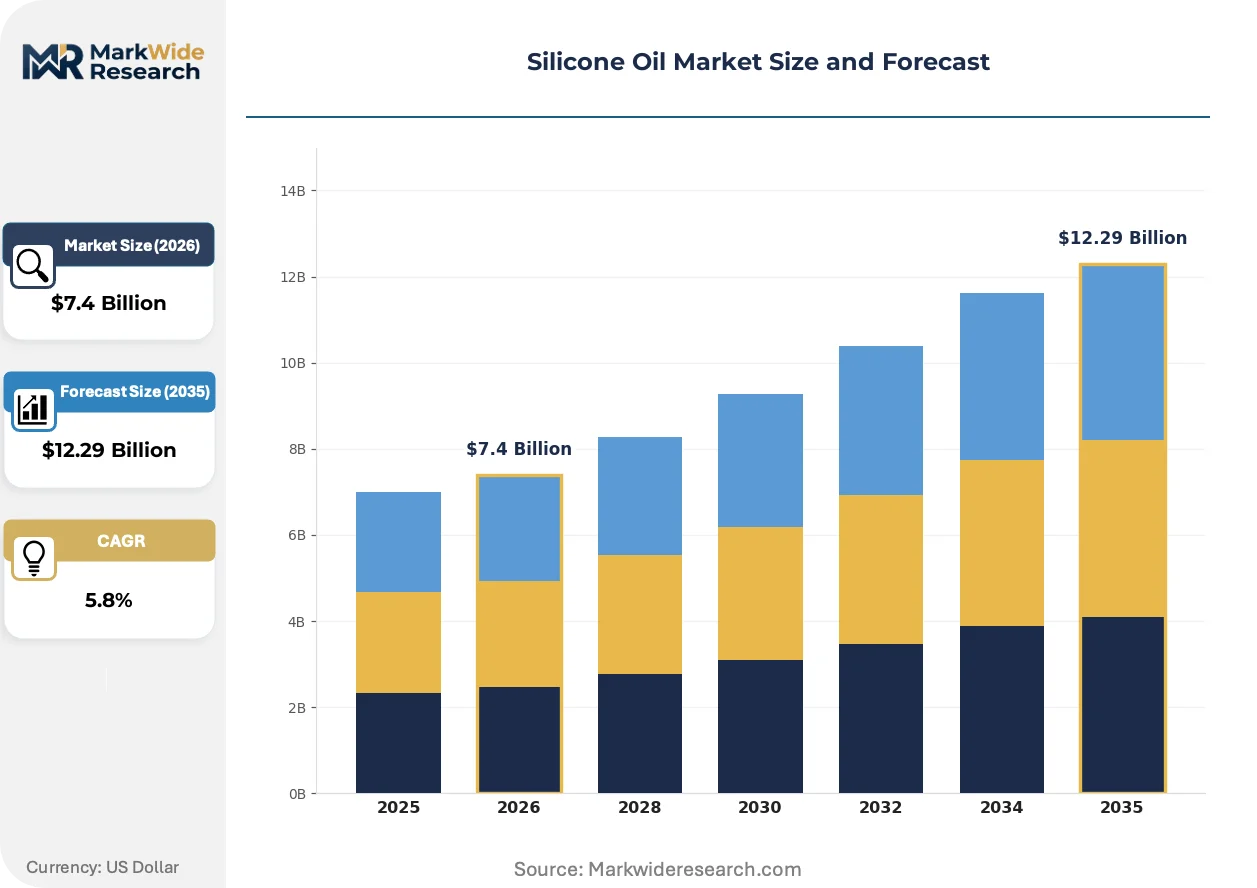
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Fluids, Gels, Compounds Application: Cosmetics, Pharmaceuticals, Textile Processing, Industrial Lubrication Form: Aerosol, Liquid, Paste, Concentrate End User: Manufacturers, Retailers, Distributors, Service Providers |
| Companies Covered | Wacker Chemie AG, Dow Inc., Shin-Etsu Chemical Co., Ltd., Elkem ASA, Momentive Performance Materials Inc., Evonik Industries AG, KCC Corporation, Clearco Products Co., Inc., BCD Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Oil Market Strategic Shifts & Innovations
Continuous flow reactor technology and AI-driven viscosity prediction models are compressing development cycles for specialty silicone grades while regulatory data requirements expand dossier complexity.
Continuous hydrolysis and equilibration reactor systems are automating the transition from batch siloxane production to steady-state polymerization with real-time molecular weight control. German and Japanese specialty chemical producers are retrofitting legacy batch assets with inline spectroscopic monitoring. This automation is compressing capital intensity per ton of high-viscosity fluid output while reducing off-specification material generation.
EU F-Gas Regulation amendments restricting fluorinated greenhouse gases are redirecting demand toward silicone-based heat transfer fluids in industrial refrigeration and HVAC systems. Equipment OEMs in Germany and Italy are qualifying polydimethylsiloxane alternatives for medium-temperature applications previously served by hydrofluorocarbon working fluids. Medical device manufacturers face parallel pressure as MDR technical documentation requirements expand biocompatibility testing scope for implantable silicone components.
Direct procurement relationships between personal care brand owners and silicone emulsion producers are displacing traditional distributor intermediaries in North American and Western European supply chains. Large cosmetics houses in France and the United States are negotiating multi-year offtake agreements with dedicated emulsion manufacturing assets. This channel consolidation is most visible in prestige skincare segments where formulation exclusivity and supply security outweigh spot-market price flexibility.
Silicone Oil Market Segmentation
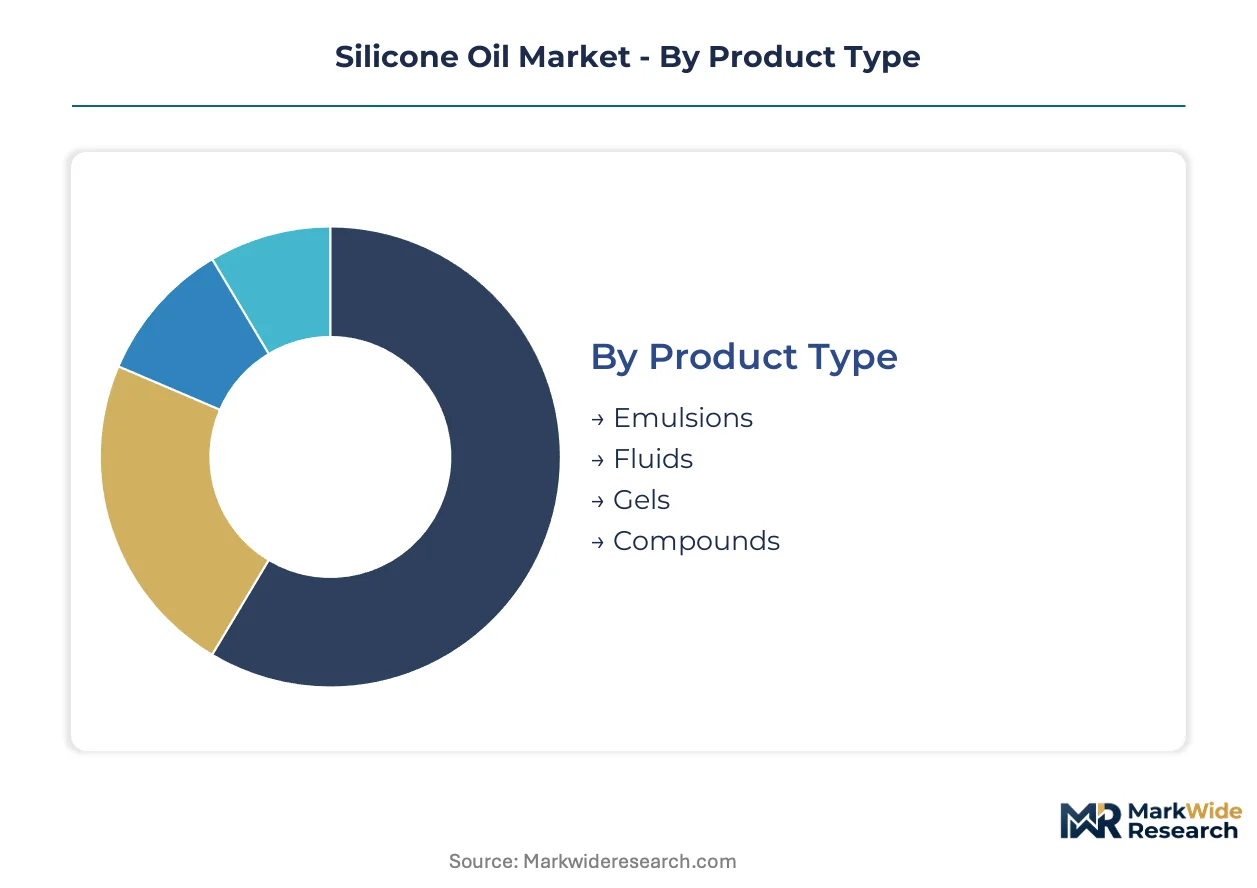
Silicone oil markets fragment along viscosity specifications, regulatory certification tiers, and formulation chemistry requirements. Procurement patterns diverge sharply between bulk industrial fluid buyers and specialty pharmaceutical formulators. Each segmentation axis carries distinct margin profiles and capital intensity thresholds.
Product Type:
Capital intensity escalates from commodity fluid distillation through pharmaceutical-grade gel purification systems. Continuous reactor investments for high-viscosity fluids exceed batch emulsion equipment by order of magnitude.
- Fluids:Linear polydimethylsiloxane chains spanning 0.65 to 2,000,000 centistokes dominate tonnage throughput. Industrial lubrication buyers in Germany and Japan absorb volumes for high-temperature endurance applications where thermal stability commands specification premiums. Chlorosilane hydrolysis and equilibration chemistry underpins production economics.
- Emulsions:Water-dispersible formats displace neat oils in rinse-off cosmetics. South Korean and French formulators drive specification evolution toward low-VOC, cold-process compatible grades. Aqueous-phase manufacturing demands specialized high-shear equipment and surfactant stabilization expertise.
- Gels:Cross-linked networks for wound care and topical delivery occupy niche margin pools. Hydrophobic silicone gel formulations for scar management require pharmaceutical cGMP documentation and biocompatibility testing.
- Compounds:Filler-reinforced systems for industrial sealing and electrical insulation. Thermal conductivity additives and catalyst packages differentiate performance tiers.
Most installed capacity flows through Fluids. Expansion is steepest in Emulsions.
Application:
Customer procurement sophistication varies from spot-market textile chemical buyers to multi-year offtake negotiators in prestige cosmetics.
- Cosmetics:Personal care emulsion demand concentrates in water-dispersible formats for haircare and skincare. Direct procurement relationships between brand owners and emulsion producers displace distributor intermediaries in France and the United States.
- Textile Processing:China's Zhejiang and Jiangsu province dyeing hubs absorb amino-functional silicone softeners for synthetic fabric finishing. REACH compliance redirects European import flows toward registered producers.
- Industrial Lubrication:EU F-Gas Regulation amendments redirect demand toward silicone-based heat transfer fluids in German and Italian HVAC systems. Equipment OEMs qualify polydimethylsiloxane alternatives for medium-temperature applications.
- Pharmaceuticals:Drug-eluting transdermal patches and implantable components face expanded MDR technical documentation requirements. FDA 510(k) pathway durations extend development-to-revenue cycles.
Volume leadership sits with Industrial Lubrication. Value expansion concentrates in Pharmaceuticals.
Form:
Packaging and delivery format selection determines logistics economics and end-use handling protocols.
- Liquid:Bulk tanker and drum shipments dominate industrial fluid distribution. Viscosity grading determines pumping and metering equipment compatibility.
- Aerosol:Propellant-dispensed formats for precision lubrication and mold release applications. Volatile organic compound regulations constrain formulation flexibility.
- Paste:Thickened consistency grades for vertical surface applications and controlled spread characteristics.
- Concentrate:Dilution-ready formats for on-site emulsion preparation by textile processors.
Logistics infrastructure favors Liquid. Regulatory pressure accelerates Concentrate substitution.
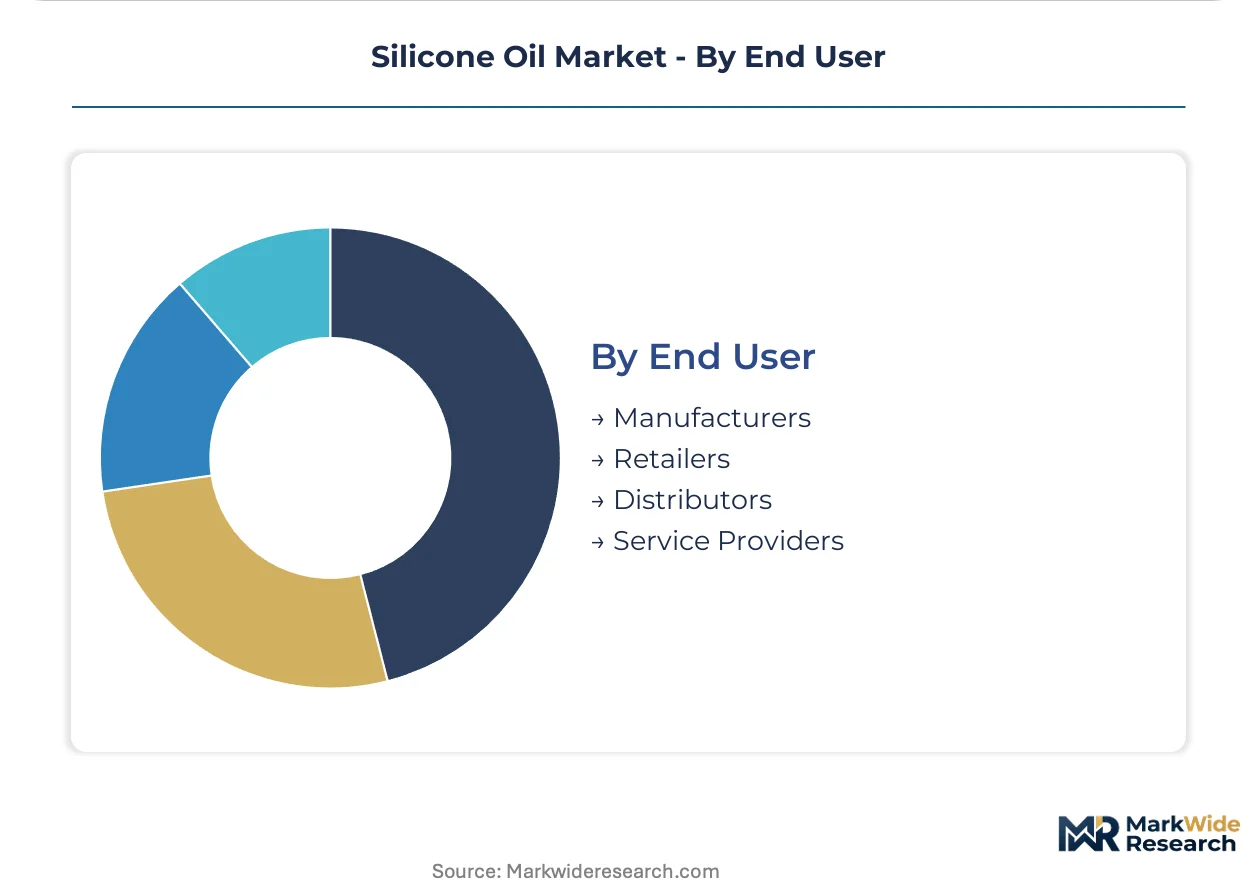
End User:
Channel structure fragments between specification-owning manufacturers and price-sensitive service intermediaries.
- Manufacturers:Formulation-integrated producers in cosmetics and pharmaceuticals negotiate dedicated emulsion manufacturing assets. Multi-year supply security agreements displace spot-market procurement.
- Distributors:Inventory-carrying intermediaries face margin compression from direct brand owner relationships. Technical service capabilities differentiate surviving players.
- Retailers:Consumer-facing channels for small-package maintenance fluids and DIY applications.
- Service Providers:On-site textile finishing operators and industrial maintenance contractors purchasing technical grades.
Procurement control is concentrating in Manufacturers. Distributor relevance is declining fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone oil manufacturing originated in Germany and the United States during the 1940s, with industrial-scale production consolidating in the Rhine-Ruhr corridor and Midland, Michigan. German chemical conglomerates pioneered chlorosilane hydrolysis processes that remain foundational to contemporary siloxane synthesis.
United States
FDA 21 CFR oversight shapes medical-grade certification pathways for implantable silicone components. EPA regulations on volatile organic compounds constrain aerosol formulation flexibility. Industrial lubrication demand concentrates in Texas Gulf Coast petrochemical corridors and Midwest automotive manufacturing belts.
Germany
EU F-Gas Regulation amendments redirect HVAC system manufacturers toward polydimethylsiloxane heat transfer fluids. REACH registration requirements constrain unregistered silicone fluid imports through ECHA enforcement. Specialty emulsion production clusters in Bavaria supply French cosmetics houses with cold-process compatible grades.
China
Zhejiang and Jiangsu province dyeing hubs absorb amino-functional silicone softeners for synthetic fabric finishing. MEE environmental compliance protocols redirect local producers toward low-VOC emulsion technologies. Dual carbon alignment goals favor aqueous-phase process expertise in Yangtze River Delta manufacturing zones.
France
Prestige skincare formulators negotiate multi-year offtake agreements with dedicated emulsion manufacturing assets. ANSM oversight shapes pharmaceutical-grade documentation requirements for wound-care applications. Direct procurement relationships between Paris-based brand owners and specialty chemical producers displace traditional distributor intermediaries.
India
Pharmaceutical manufacturing corridors in Maharashtra and Gujarat drive consumption of hydrophobic silicone gel formulations for scar management. CDSCO regulations extend development-to-revenue cycles for novel drug-eluting transdermal patches. Hospital procurement channels in Delhi-NCR and Bengaluru remain underpenetrated for advanced wound-care grades.
Silicone Oil Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade stratification. The vendor base organizes into three tiers: integrated siloxane backbone producers with captive monomer supply, specialty emulsion manufacturers with surfactant stabilization expertise, and regional compounders serving price-sensitive textile processors. Consolidation pressure concentrates among mid-scale emulsion specialists facing direct procurement displacement by cosmetics brand owners. Dominant competitive moves include backward integration into chlorosilane feedstock and precision viscosity customization through continuous reactor investments.
Among Germany-based chemical conglomerates, Wacker Chemie AG exemplifies specialty emulsion positioning through dedicated manufacturing assets serving European cosmetics manufacturers. Dow Inc. anchors the integrated producer archetype with siloxane backbone capacity sustaining cost advantages in industrial fluid grades. Shin-Etsu Chemical Co., Ltd. occupies a position within the precision viscosity control tier through captive monomer supply and Japanese process technology heritage.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Dow Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Elkem ASA |
| Momentive Performance Materials Inc. |
| Evonik Industries AG |
| KCC Corporation |
| Clearco Products Co., Inc. |
| BCD Chemie GmbH |
| Others |
Cost & Logistics Intelligence
Direct procurement relationships between French and South Korean cosmetics brand owners are forcing silicone emulsion producers to absorb surfactant stabilization costs while maintaining specification premiums, compressing margins across aqueous-phase manufacturing tiers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-fluid, and textile-processing levels dominates transaction structures. Price differentiation hinges on REACH registration completeness and viscosity precision control. Cost compression in emulsion grades is intensifying because personal care formulators are consolidating supplier panels. Spot-market textile processors in China's Zhejiang corridor exhibit highest price sensitivity, while pharmaceutical formulators in India and Germany demonstrate lowest.
Supply Chain Analysis
Direct-to-cosmetics-brand channels displace distributor intermediaries in European and North American procurement flows. Manufacturing concentrates in Germany, China, and Japan through integrated siloxane backbone facilities. Chlorosilane feedstock, silicon metal, and energy inputs at carbothermal reduction sites rest on Norwegian and Brazilian supply nodes. Single-source vulnerability in high-purity pharmaceutical-grade gel purification creates exposure. Distribution runs through bulk tanker shipments for industrial fluids and dedicated emulsion manufacturing assets for cosmetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers as FDA 510(k) pathway requirements create scarcity premiums for compliant producers.
For Market Incumbents: Acquire continuous reactor assets with inline spectroscopic monitoring to automate high-viscosity fluid production. Secure captive chlorosilane supply through backward integration into silicon metal processing. Bio-based emollient substitution in European clean-label cosmetics threatens emulsion volume; defend via pharmaceutical cGMP documentation investments. For New Entrants and Emerging Players: Enter via aqueous-phase emulsion manufacturing for India's underpenetrated hospital procurement channels in scar management and wound care. Target Maharashtra and Gujarat pharmaceutical corridors with hydrophobic silicone gel formulations. Pursue CDSCO regulatory consulting partnerships as go-to-market anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale emulsion specialists possessing surfactant stabilization expertise and existing REACH dossiers. Five-to-ten year viability favors producers with dual carbon alignment capabilities in China's Yangtze River Delta. Monitor GB standard updates on low-VOC emulsion technologies as inflection signal for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive chlorosilane supply insulates against silicon metal price volatility at Norwegian reduction facilities. |
| Pharmaceutical cGMP Certification | FDA 21 CFR pathway completion unlocks premium pricing in implantable device and drug-eluting patch segments. |
| Continuous Reactor Investment | Real-time molecular weight control reduces off-specification material in high-viscosity fluid production. |
| Low-VOC Emulsion Technology | MEE compliance in China's Jiangsu province secures access to synthetic fabric finishing demand. |
| Direct Procurement Partnerships | Multi-year offtake agreements with Paris-based cosmetics houses displace distributor margin extraction. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged formulation chemists at cosmetics houses, procurement leads at textile dyeing hubs, pharmaceutical regulatory affairs directors, and plant managers at siloxane backbone facilities. Secondary validation drew from ECHA registration databases, FDA 510(k) submission records, Chinese customs trade flows, and SEC filings of integrated chemical producers. Bottom-up segment sizing and top-down market reconciliation anchored all value estimates.
Historical reference periods anchored volume and value trajectories across the modeling period. Segmentation dimensions included viscosity grade tier, regulatory certification level, end-use industry, and regional production hub. CAGRs were derived from slope analysis of normalized growth curves. Forecast inputs incorporated chlorosilane feedstock cost indices, REACH registration timelines, and MEE environmental protocol implementation schedules.
Inputs from ECHA dossier submissions and FDA pre-submission meetings were available through the study window; gaps in real-time Chinese provincial environmental enforcement data introduce uncertainty bands around low-VOC emulsion adoption rates. Forecasts reflect documented assumptions on regulatory divergence persistence and substitution elasticity for bio-based alternatives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
LAMEA Metal Biocides Market