
 Free-From Titanium Dioxide Market | 2026-2036
Free-From Titanium Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Free-From Titanium Dioxide Market Foresight
Buyer concentration in the food and beverage sector is broadening as mid-sized clean-label brands gain shelf space alongside multinational reformulation programs. Chr. Hansen Holding A/S leverages its microbial pigment portfolio to compete in natural whitening alternatives. ADM sustains ingredient supply scale across North American and European reformulation pipelines. Sensient Technologies anchors colorant technology leadership through plant-derived opacifier development.
Free-from titanium dioxide refers to colorant and opacifier formulations engineered without TiO2 particles, typically employing calcium carbonate, starch-based complexes, or natural mineral blends that achieve comparable refractive indices between 1.5 and 2.0 for opacity performance. These substitutes serve industrial applications requiring whitening, UV blocking, or visual coverage where regulatory or consumer pressure excludes conventional titanium dioxide. Powder formulations dominate current manufacturing throughput due to stability in dry blending operations and extended shelf compatibility. Liquid and emulsion segments are expanding fastest as beverage and dairy processors seek pumpable, dust-free integration into continuous production lines. UV protection applications command premium positioning within cosmetics and sun care, where mineral-block alternatives to TiO2 command formulation investment.
The European Food Safety Authority's reclassification of titanium dioxide as a food additive of concern, coupled with REACH substance evaluation protocols and FDA guidance on color additive petitions, is redirecting formulation R&D budgets toward certified alternatives. France's national ban on TiO2 in food products, enforced by ANSES, has established a compliance template now referenced by regulators in neighboring jurisdictions. Stakeholders must monitor pending regulatory determinations in additional EU member states and assess certification pathways for novel mineral complexes before committing capital to regional production assets.
Market Dynamics
EFSA's reclassification of titanium dioxide as a food additive of concern has triggered a structural reformulation wave across European food and beverage manufacturing, redirecting R&D budgets toward certified mineral and plant-based opacifiers.
Growth Catalysts
- France's ANSES enforcement template:The national ban on TiO2 in food products establishes compliance precedents now referenced by regulators in neighboring jurisdictions, accelerating substitution timelines.
- Clean-label procurement priorities:German packaged goods producers have elevated natural whitening alternatives to strategic sourcing mandates, compressing supplier qualification cycles.
- Calcium carbonate refractive engineering:Advanced particle size distribution control achieves opacity indices between 1.5 and 2.0, matching TiO2 performance in dry-blend applications.
Market Restraints
- Mineral supply concentration:High-purity calcium carbonate deposits cluster in select Mediterranean and Appalachian extraction zones, creating geographic vulnerability.
- REACH substance evaluation protocols:Novel mineral complexes face extended certification timelines, delaying commercial deployment of next-generation opacifiers.
- Starch-based complex stability limits:Humidity sensitivity restricts shelf-life performance in tropical distribution corridors.
Strategic Opportunities
- Beverage sector pumpable formats:Liquid and emulsion segments expand as dairy processors seek dust-free integration into continuous production lines.
- UV protection premium positioning:Cosmetics and sun care mineral-block alternatives command formulation investment above commodity food-grade substitutes.
- EU Green Deal bio-based mandates:Plant-derived opacifier development aligns with emerging sustainability certification requirements for personal care ingredients.
Industry Challenges
- Refractive index matching expertise:Formulation chemists capable of engineering 1.5-2.0 opacity performance without TiO2 remain scarce across contract manufacturing networks.
- Legacy equipment recalibration:Dry-blending lines optimized for TiO2 particle morphology require retrofitting to handle starch-complex flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free-From Titanium Dioxide Market |
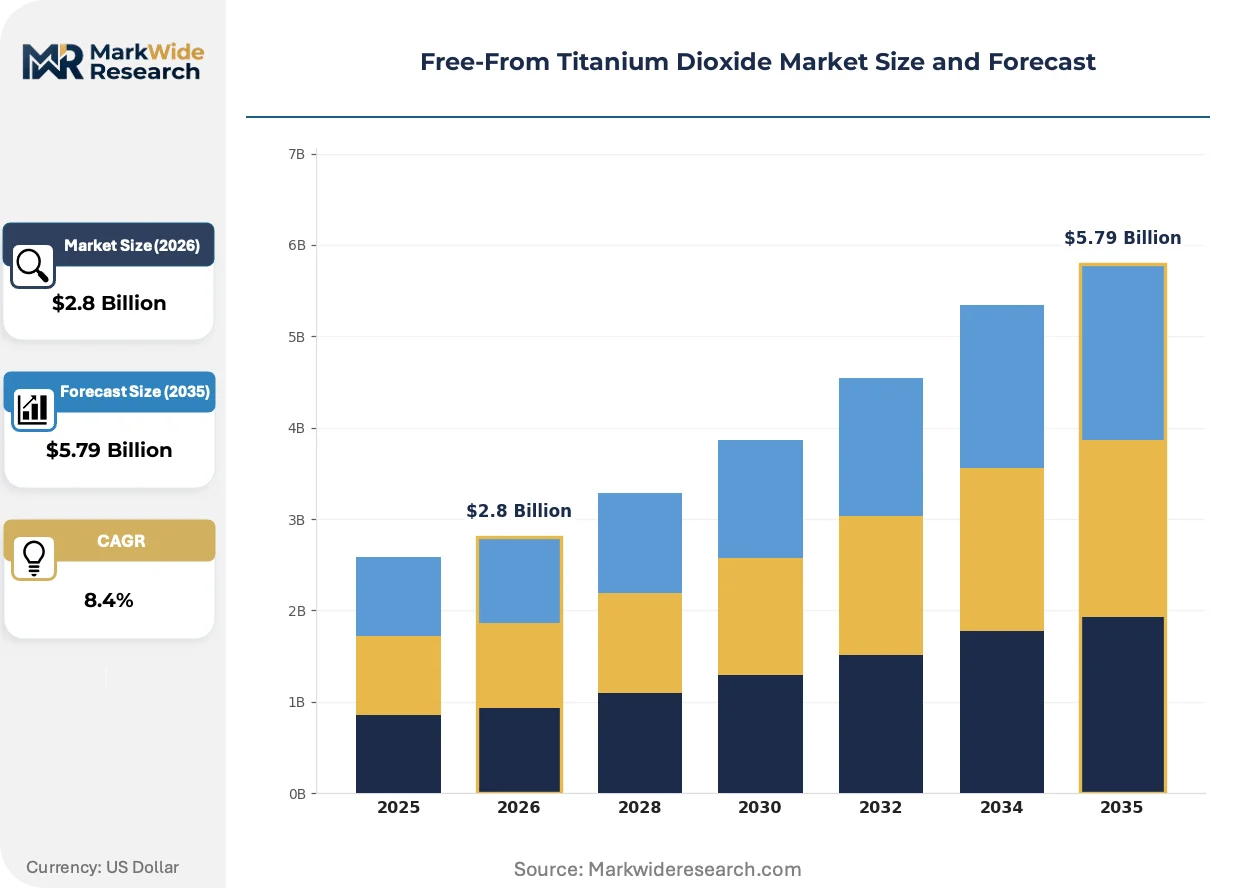
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Paste, Emulsion, Gel End Use Industry: Cosmetics, Food & Beverages, Pharmaceuticals, Paints & Coatings, Adhesives Application: UV Protection, Whitening Agents, Opacifying, Coloring, Filling Agents Packaging Type: Bottles, Pouches, Jars, Tubes, Sachets |
| Companies Covered | Sensient Technologies, ADM, Chr. Hansen Holding A/S, Döhler GmbH, Colorcon Inc., GNT Group, Kalsec Inc., Naturex, Symbioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free-From Titanium Dioxide Market Shifts & Advancements
Reformulation pipelines are compressing development cycles as natural opacifier technologies mature and regulatory deadlines harden across European member states.
Microbial pigment engineering is unifying color and opacity functions in single-ingredient solutions. Dairy and confectionery manufacturers in Northern Europe are adopting these dual-purpose formulations at accelerated rates. This convergence is unifying previously separate supplier relationships, reducing formulation complexity and procurement touchpoints.
REACH substance evaluation protocols are tightening data requirements for novel mineral complexes entering the EU market. Industrial consequence includes extended toxicology study timelines and elevated registration costs for mid-tier ingredient suppliers. Food-grade calcium carbonate and starch-based alternatives face the most intensive scrutiny, with applicants redirecting resources toward existing approved substance modifications rather than novel molecular structures.
Buyer concentration patterns are fragmenting as mid-sized clean-label brands gain retail shelf space alongside multinational reformulation programs. Traditional distribution through bulk ingredient brokers faces displacement by direct technical partnerships between opacifier developers and finished goods manufacturers. Germany exhibits the most pronounced channel compression, where procurement teams embed supplier technical staff within internal formulation labs.
Free-From Titanium Dioxide Market Segmentation
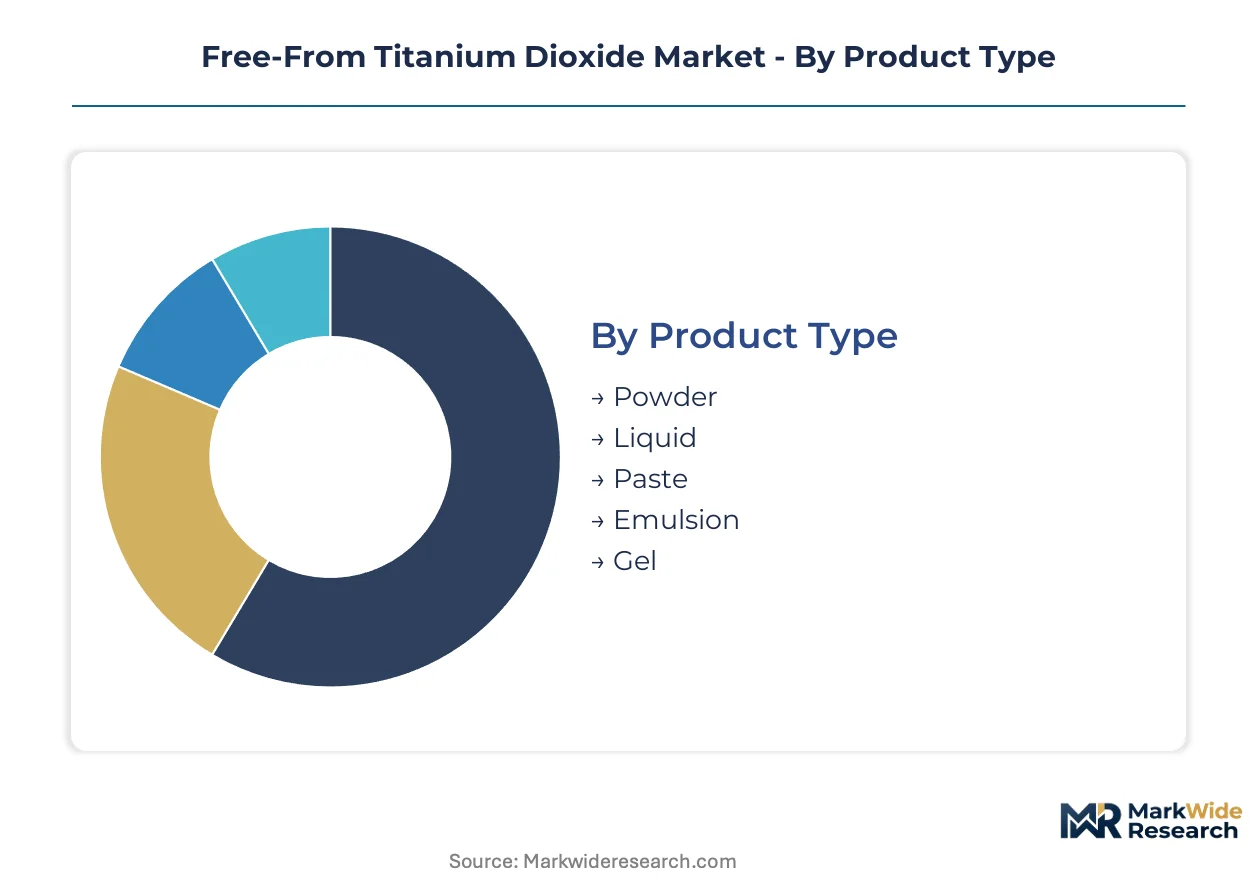
Formulation engineers select TiO2-free alternatives based on integration depth with existing production infrastructure. Powder formats dominate dry-blend operations, while liquid and emulsion variants require pumpable delivery systems. Each segment carries distinct regulatory certification burdens and refractive performance specifications that determine commercial viability.
Product Type:
Powder formats operate as standalone additives requiring minimal equipment modification, whereas liquid and emulsion systems embed into continuous processing lines with deeper integration requirements.
- Powder:Dry calcium carbonate and starch-based complexes achieve refractive indices between 1.5 and 2.0 through controlled particle size distribution. German food manufacturers prioritize powder stability in extended shelf-life applications, though humidity sensitivity constrains tropical distribution.
- Liquid:Pumpable suspensions of mineral opacifiers integrate directly into dairy and beverage continuous production lines without dust generation. French dairy processors are accelerating adoption to meet ANSES compliance deadlines for reformulated product lines.
- Paste:Semi-solid concentrates serve cosmetic compounding where precise viscosity control matters.
- Emulsion:Oil-in-water systems deliver uniform dispersion in sun care and personal care formulations requiring UV-blocking mineral alternatives.
- Gel:Thixotropic matrices support targeted application in pharmaceutical coatings and specialized adhesive systems.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
End Use Industry:
Cost tier stratification separates premium-positioned cosmetic applications from commodity food-grade substitutes, with pharmaceutical and industrial coatings occupying intermediate value bands.
- Cosmetics:Mineral-block UV alternatives command formulation investment above food-grade substitutes due to performance certification requirements. EFSA reclassification has redirected R&D budgets toward plant-derived opacifiers in sun care and color cosmetics.
- Food & Beverages:Calcium carbonate and starch-based whitening agents face intensive REACH scrutiny as manufacturers replace banned TiO2 in confectionery and dairy. French national enforcement templates now influence neighboring jurisdictions.
- Pharmaceuticals:Tablet coating and excipient applications demand validated supply chains with documented purity certifications.
- Paints & Coatings:Industrial opacifiers require weathering stability and tinting strength comparable to legacy TiO2 grades.
- Adhesives:Filler-grade mineral alternatives modify viscosity and opacity in construction and packaging adhesives.
Revenue concentration sits with Cosmetics; the steepest volume climb is occurring in Food & Beverages.
Application:
Functional maturity varies across whitening, UV blocking, and visual coverage roles, with dual-purpose formulations gaining traction as microbial pigments unify color and opacity.
- UV Protection:Mineral-block alternatives to TiO2 in sun care require engineered particle morphology for broad-spectrum efficacy without nano-scale concerns. Premium positioning supports higher ingredient costs versus commodity food substitutes.
- Whitening Agents:Calcium carbonate refractive engineering matches TiO2 opacity in dry-blend food applications. German procurement teams have elevated natural whitening to strategic sourcing mandates.
- Opacifying:Visual coverage functions in cosmetics and coatings demand precise particle size control for consistent light scattering.
- Coloring:Microbial pigment engineering converges color and opacity in single-ingredient solutions for dairy and confectionery.
- Filling Agents:Extender minerals reduce formulation costs while maintaining bulk properties in adhesives and industrial coatings.
Deployment scale favors Whitening Agents; UV Protection is gaining share fastest on premium pricing.
Packaging Type:
Supply chain configuration determines primary packaging selection, with bulk intermediate formats serving industrial processors and unit-dose systems targeting specialty compounding operations.
- Bottles:Standard containment for liquid opacifiers in cosmetic and pharmaceutical formulation labs.
- Pouches:Flexible intermediate bulk formats reduce shipping costs for powder mineral shipments to food manufacturers.
- Jars:Wide-mouth containers facilitate scooping of paste and gel consistencies in small-batch cosmetic production.
- Tubes:Precision-dispensing formats suit adhesive and coating compounding where metered addition matters.
- Sachets:Unit-dose packaging supports sampling programs and just-in-time delivery for contract manufacturers.
Industrial throughput runs through Pouches; technical service sampling is driving Sachet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration in Germany is accelerating reformulation timelines across European food manufacturing. French regulatory enforcement templates now influence substitution mandates in neighboring jurisdictions. Asian cosmetic formulators are adopting mineral-block alternatives ahead of anticipated regulatory alignment.
Germany
Clean-label procurement priorities have elevated natural whitening alternatives to strategic sourcing mandates among major packaged goods producers. REACH substance evaluation protocols govern certification timelines for novel mineral complexes entering the EU market. The Rhine-Ruhr industrial corridor hosts concentrated reformulation activity as dairy and confectionery manufacturers retrofit dry-blending lines for starch-complex flow characteristics.
France
ANSES enforcement of the national TiO2 ban in food products has established compliance precedents referenced by regulators across the continent. EFSA's reclassification of titanium dioxide as a food additive of concern originated from French regulatory pressure. The Lyon-Auvergne-Rhône-Alpes cluster anchors microbial pigment engineering operations serving dual-purpose color and opacity formulations.
United States
FDA guidance on color additive petitions is redirecting formulation R&D budgets toward certified alternatives in sun care and cosmetics. Clean-label brand expansion across mid-sized retail channels is fragmenting traditional buyer concentration patterns. The New Jersey-Pennsylvania pharmaceutical corridor maintains validated supply chains for tablet coating applications requiring documented purity certifications.
China
Domestic cosmetic formulators are investing in mineral-block UV alternatives ahead of anticipated SAMR alignment with international safety standards. GB standards development for food-grade mineral additives is accelerating under dual carbon goals and sustainability mandates. The Yangtze River Delta concentration of personal care manufacturing is driving localized opacifier production capacity expansion.
India
FSSAI monitoring of international TiO2 safety determinations is informing preliminary industry guidance on natural whitening alternatives. Domestic dairy processors are evaluating calcium carbonate refractive engineering for confectionery and beverage applications. The Maharashtra-Gujarat industrial belt hosts emerging contract manufacturing networks developing formulation expertise in 1.5-2.0 opacity performance without conventional titanium dioxide.
Free-From Titanium Dioxide Market Competitive Landscape
German ingredient specialists anchor the premium-tier certification pathway; North American commodity suppliers hold volume-scale positions in dry-blend mineral alternatives. The vendor base stratifies across three functional tiers: microbial pigment engineers, plant-derived opacifier developers, and mineral extraction processors. Strategic moves concentrate on direct technical partnerships with finished goods manufacturers and backward integration into high-purity calcium carbonate deposits.
Within the microbial pigment tier, Chr. Hansen Holding A/S and GNT Group exemplify natural colorant convergence with opacity functions. Among North American diversified ingredient suppliers, ADM occupies a scale-driven position across reformulation pipelines. Sensient Technologies anchors technology leadership in plant-derived opacifier development. These three represent distinct competitive archetypes: specialized biotech, integrated commodity, and applied colorant technology.
| Leading Market Players |
|---|
| Sensient Technologies |
| ADM |
| Chr. Hansen Holding A/S |
| Döhler GmbH |
| Colorcon Inc. |
| GNT Group |
| Kalsec Inc. |
| Naturex |
| Symbioscience |
| Others |
Supply & Pricing Matrix
Calcium carbonate feedstock indices in Mediterranean extraction zones cascade through three distinct pricing tiers as high-purity mineral scarcity concentrates negotiation leverage among German dairy and confectionery processors. REACH certification costs for novel mineral complexes amplify spread between approved substitutes and experimental formulations, compressing margins for mid-tier suppliers while premium microbial pigment engineers capture value through direct technical partnerships.
Pricing Analysis
Volume placements in commodity-grade calcium carbonate and starch-based complexes generate thin margins, while UV-protection mineral blocks in cosmetics sustain premium positioning through performance certification requirements. Price differentiation separates food-grade substitutes from pharmaceutical and sun-care tiers based on purity documentation and toxicology study depth. Cost compression in powder formats is intensifying as German procurement teams consolidate supplier panels around qualified natural whitening alternatives. Mid-sized clean-label brands exhibit highest price sensitivity, whereas multinational reformulation programs prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from French and German food manufacturers require qualification of at least two approved opacifier suppliers per production facility, extending procurement timelines but reducing single-source vulnerability. High-purity calcium carbonate concentrates in select Mediterranean and Appalachian extraction zones, while microbial pigment engineering clusters in Denmark and the Netherlands. Raw material flows draw from mineral extraction networks, plant-derived feedstock cultivation, and fermentation-based pigment production. Tariff exposure on processed mineral imports from non-EU sources presents structural risk. Distribution runs through direct technical partnerships replacing traditional bulk ingredient broker channels, particularly in Germany's compressed procurement landscape.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified natural opacifier supply is tightening as REACH certification backlogs and mineral deposit concentration constrain capacity expansion, propping pricing power for approved-substance holders across European reformulation pipelines.
For Market Incumbents: To counter emerging microbial pigment convergence from specialized biotech competitors, incumbents should accelerate backward integration into captive high-purity calcium carbonate deposits in Mediterranean extraction zones and embed technical service teams within German formulation laboratories to lock in direct partnership structures. For New Entrants and Emerging Players: Liquid and emulsion format engineering for pumpable dairy and beverage integration offers the most penetrable white-space target, with French ANSES compliance deadlines compressing qualification windows. A technology-first wedge opens through proprietary particle size distribution control achieving 1.5-2.0 refractive indices without TiO2, pitched to mid-sized clean-label brands bypassing traditional broker networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mineral extraction processors with existing REACH approvals in Italy and Spain, where certification asset values are depressed by extended novel-substance evaluation timelines. Long-term viability hinges on five-to-ten-year regulatory alignment toward natural whitening mandates across additional EU member states. The signal to watch is FSSAI guidance progression in India, which would validate international demand scaling for approved substitutes.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Fast-Track | Accelerated toxicology data packages compress approval timelines for calcium carbonate modifications ahead of regulatory deadlines. |
| Microbial Pigment Scale-Up | Dual-purpose color-opacity fermentation capacity expansion captures dairy and confectionery reformulation demand in Northern Europe. |
| Direct Technical Partnership | Embedded supplier R&D teams within German procurement labs displace bulk broker distribution channels. |
| High-Purity Mineral Backward Integration | Captive Mediterranean calcium carbonate extraction secures feedstock against geographic concentration risk. |
| Liquid Format Pumpable Development | Dust-free emulsion systems align with French dairy processor ANSES compliance retrofit requirements. |
Research Methodology
Independent corroboration across formulation chemists at German dairy and confectionery manufacturers, procurement leads at French packaged goods producers, and regulatory affairs specialists navigating REACH substance evaluation protocols underwrites the qualitative findings. Secondary validation draws from EFSA safety assessments, ANSES enforcement documentation, customs trade data on mineral additive imports, and SEC filings of diversified ingredient suppliers. Bottom-up volume estimates from individual product line reformulation pipelines triangulate against top-down market sizing from end-use industry consumption patterns.
Comparable-period anchoring to pre-EFSA reclassification baselines establishes trajectory calibration across the projection horizon. The analytical framework models formulation type, end-use industry tier, application function, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from compound growth pathing across approved-substance adoption curves and substitution timeline compression. Forecast inputs incorporate REACH certification queue depth and microbial pigment production capacity expansion schedules.
Several conditions sit outside the modeled scope, including potential EFSA reversal of titanium dioxide reclassification, breakthrough synthetic opacifier technologies bypassing mineral and plant-based pathways, and macroeconomic disruption to German food manufacturing output. Forecasts reflect assumptions on regulatory deadline adherence and supplier qualification cycle stability. Deviation in SAMR alignment timing with international TiO2 safety standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Global Silicone Defoamer Market