
 Acesulfame Potassium Market | 2026-2036
Acesulfame Potassium Market Size, Share, and Industry Trends Forecast 2026-2036
Acesulfame Potassium Market Analysis
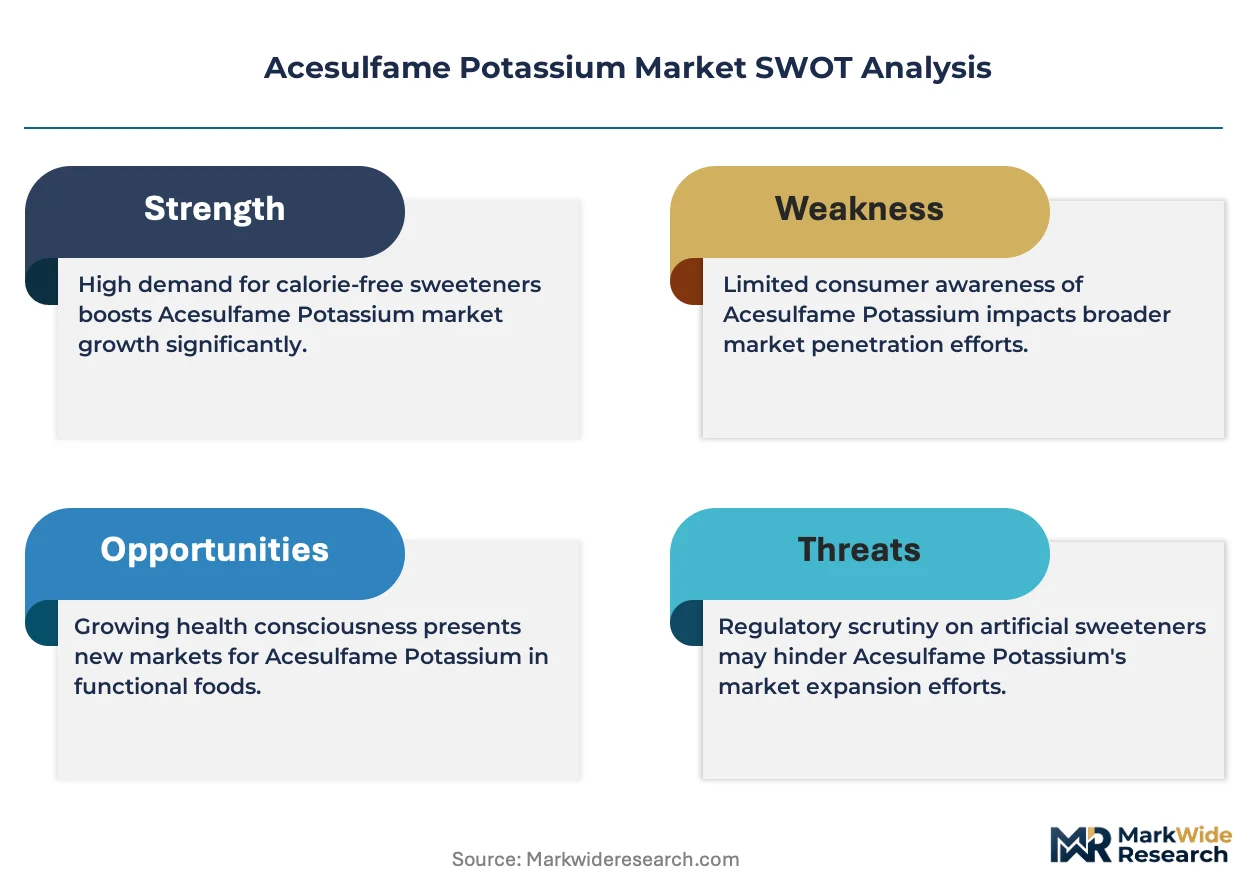
ISO 22000 certification is unwinding the competitive landscape for Acesulfame Potassium suppliers, filtering out smaller producers unable to sustain audit cycles. Changzhou Niutang Chemical Plant leverages captive acetoacetic acid supply to control raw material costs. Nutrinova anchors European demand through its Hoechst legacy distribution network and Celanese backing. Anhui Jinhe Industrial dominates crystallization scale, operating some of the largest continuous production lines serving export markets.
Acesulfame Potassium is a high-intensity, non-caloric sweetener synthesized through acetoacetic acid-sulfur dioxide cyclization, yielding a crystalline product roughly 200 times sweeter than sucrose with exceptional thermal stability for baking and pasteurization. Powder format leads volume due to blending flexibility in dry-mix applications, while liquid concentrate captures expanding demand from ready-to-drink beverage lines seeking dosing precision. Bakery and confectionery segments remain mature with stable offtake, but beverages represent the fastest-growing application as carbonated and functional drink makers reformulate.
FDA GRAS status and EPA effluent guidelines shape US market access, while EU REACH compliance and EFSA sweetener evaluations govern European import eligibility. China's SAMR enforces GB 25540 purity standards that now include tighter heavy metal thresholds, forcing capacity upgrades among domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening additive approvals in one geography can strand inventory and redirect trade flows without warning.
Market Dynamics
Beverage reformulation campaigns are compressing sweetener procurement cycles, forcing suppliers to synchronize crystallization output with just-in-time blending schedules at carbonated and functional drink plants.
Growth Catalysts
- Clean-label mandates:EFSA sweetener evaluations and FDA GRAS pathways are accelerating high-intensity sweetener approvals, opening formulation flexibility for zero-sugar product lines across European and North American beverage portfolios.
- Acetoacetic acid supply security:Captive production of this cyclization precursor is insulating integrated manufacturers from sulfur dioxide feedstock volatility, stabilizing crystallization yields.
- East China production clustering:Jiangsu and Shandong provinces concentrate active manufacturing capacity, creating export-oriented logistics efficiencies that shorten delivery windows to ASEAN and Middle Eastern buyers.
Market Restraints
- Input cost volatility:Sulfur dioxide and acetic anhydride prices fluctuate with petrochemical feedstock markets, compressing margin stability for non-integrated producers.
- Regulatory friction:China's SAMR GB 25540 purity standard revisions impose tighter heavy metal thresholds, forcing crystallization line upgrades that strand smaller domestic suppliers.
- Substitution pressure:Sucralose and stevia glycosides compete for beverage reformulation slots, particularly where thermal stability requirements permit alternative high-intensity options.
Strategic Opportunities
- Functional beverage expansion:Sports and energy drink categories in Brazil and Mexico present underpenetrated demand for heat-stable sweetening systems that survive pasteurization.
- Liquid concentrate formats:Ready-to-drink bottling lines are adopting precision dosing systems that favor pre-dissolved acesulfame potassium over powder blending.
- EU Green Deal alignment:REACH compliance and CSRD reporting requirements are creating preference premiums for suppliers with verified carbon footprint reductions in crystallization energy use.
Industry Challenges
- ISO 22000 audit cycles:Certification maintenance demands documented hazard analysis and critical control point systems that strain quality management resources at mid-scale producers.
- Crystallization scale-up complexity:Continuous production line expansion requires precise temperature and pH control engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acesulfame Potassium Market |
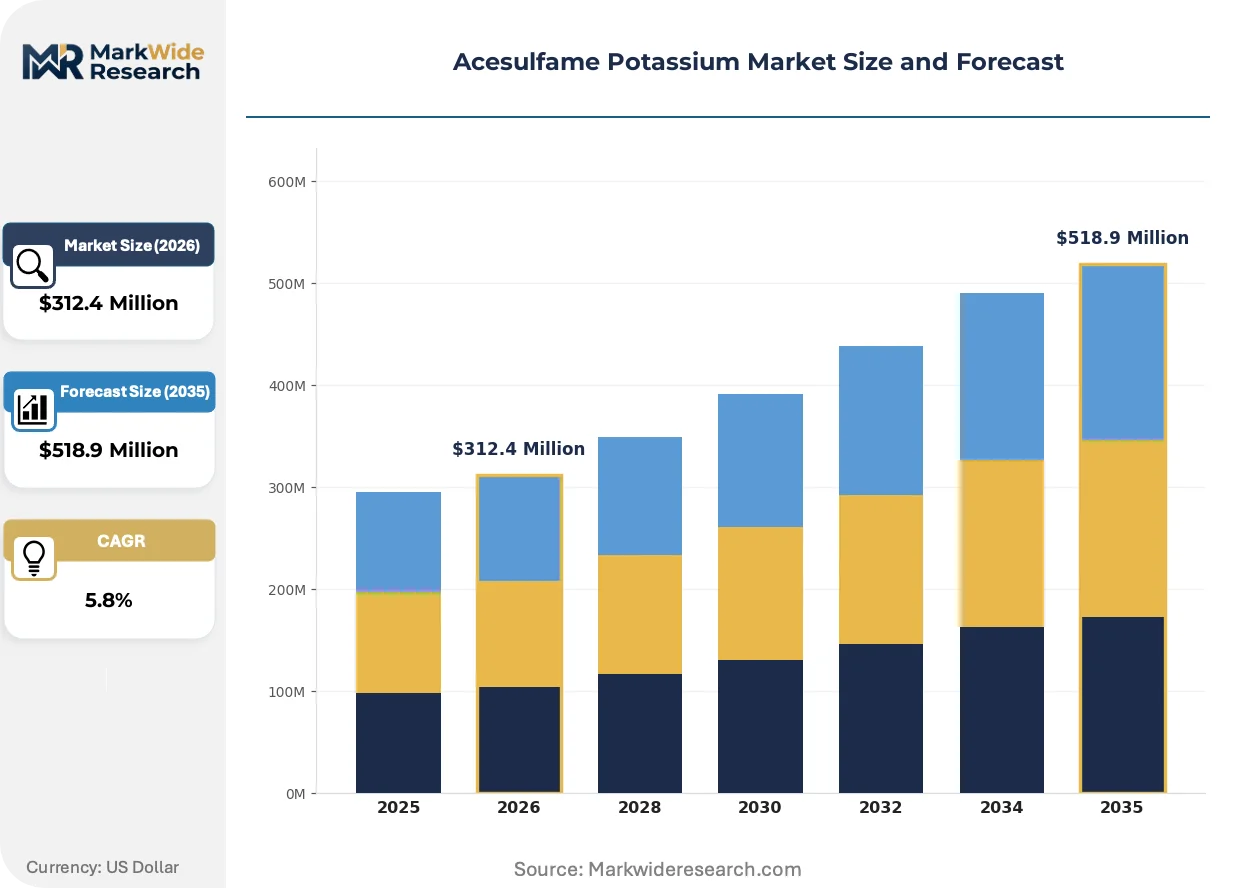
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Liquid Application: Beverages, Bakery, Dairy, Confectionery Customer Type: Food Manufacturers, Beverage Companies, Retailers, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Changzhou Niutang Chemical Plant Co., Ltd., Suzhou Hope Technology Co., Ltd., Nutrinova (Celanese Corporation), Shandong Minghui Food, Jiangsu Vitasweet, HYET Sweet, Anhui Jinhe Industrial Co., Ltd., Jiangxi BEIYANG Food Additive, Hermes Sweeteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acesulfame Potassium Market Emerging Trajectories
Reformulation science is reshaping how sweetener suppliers align crystallization output with beverage manufacturing rhythms, compressing the traditional specification-to-delivery interval.
Continuous crystallization technology is fragmenting batch-production economics in acesulfame potassium manufacturing. Beverage companies operating high-speed bottling lines are adopting this output for its particle-size consistency, which reduces dissolution time in tank-mix operations. The shift is compressing contract structures toward volume-commitment frameworks that lock in crystallization capacity.
REACH substance evaluation workflows under ECHA are extending pre-market notification timelines for new sweetener grades entering European formulations. Manufacturers are responding by front-loading toxicology dossiers and dual-registering intermediates to prevent supply interruptions. This procedural density most affects specialty bakery applications requiring customized particle distributions.
Direct-procurement contracts between sweetener crystallizers and beverage brand technical teams are displacing traditional distributor intermediation in North American and Western European markets. Technical service integration—on-site blending trials and stability testing—is becoming a bundled expectation rather than a premium add-on. This pattern is most pronounced in carbonated soft drink headquarters clusters around Atlanta and Purchase.
Acesulfame Potassium Market Segmentation
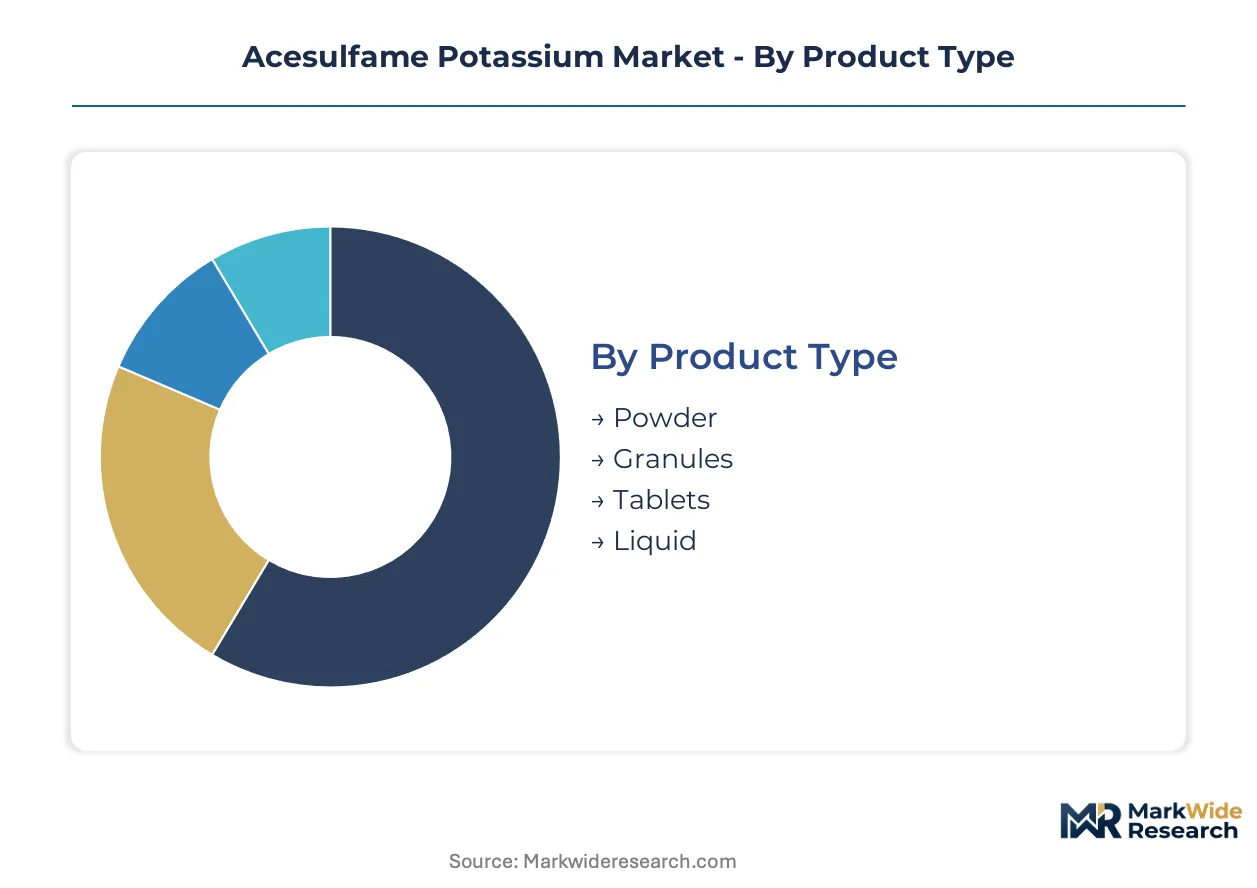
Acesulfame Potassium procurement patterns diverge sharply across product formats and buyer categories. Beverage manufacturers drive crystallization output scheduling, while food service channels impose distinct logistics requirements on packaging and dosing systems.
Product Type:
Powder and granule formats flow through wholesale channels to industrial blenders, while liquid concentrates and tablets serve distinct downstream dosing infrastructures.
- Powder:Fine crystalline particles offer maximum blending flexibility in dry-mix applications. Beverage manufacturers in Jiangsu province consume the bulk of powder output for carbonated drink reformulation campaigns, though sulfur dioxide feedstock volatility compresses margin stability for non-integrated suppliers.
- Liquid:Pre-dissolved concentrate enables precision dosing in high-speed bottling lines without dissolution tanks. Ready-to-drink manufacturers in Brazil and Mexico are adopting this format fastest as pasteurization-stable sweetening systems penetrate functional drink categories.
- Granules:Coarse particle sizing reduces dust generation during bulk handling. Bakery and confectionery producers favor granules for direct addition to dough and fondant systems.
- Tablets:Compressed units serve food service and small-batch manufacturing where measured dosing replaces weighing operations. Specialty stores stock tablet formats for artisanal beverage producers.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Cost tier stratification separates commodity sweetening from premium functional positioning across end-use categories.
- Beverages:Carbonated soft drinks, sports drinks, and energy formulations constitute the primary demand sink. Reformulation campaigns at Atlanta and Purchase headquarters clusters compress procurement cycles toward just-in-time crystallization output.
- Bakery:Thermal stability during oven cycles makes acesulfame potassium viable for reduced-sugar bread and pastry applications. Mature demand in Western Europe concentrates in industrial-scale frozen dough operations.
- Confectionery:Hard candy and chewing gum formulations exploit heat resistance during cooking and extrusion. EFSA sweetener evaluations govern import eligibility for European confectionery manufacturers.
- Dairy:Pasteurized milk and yogurt applications require pH-stable sweetening through UHT processing. SAMR GB 25540 purity standards constrain supplier qualification for Chinese dairy processors.
Beverages command premium pricing tiers. Dairy presents untapped penetration potential.
Customer Type:
Volume concentration and margin structure diverge between formulation-integrated buyers and arms-length distributors.
- Beverage Companies:Technical teams at carbonated and functional drink makers direct-procure crystallization capacity, displacing traditional distributor intermediation. On-site blending trials and stability testing are now bundled expectations rather than premium add-ons.
- Food Manufacturers:Industrial bakeries and confectionery plants purchase through wholesale channels with quarterly contract structures. ISO 22000 certification filters supplier eligibility for multinational food manufacturing accounts.
- Retailers:Private-label sweetener sourcing concentrates in supermarket chains with dedicated additive procurement desks. REACH compliance documentation determines European retail supplier qualification.
- Food Service:Restaurants, cafes, and institutional kitchens purchase tablet and small-package formats through specialty stores. Online channels capture growing share of food service procurement for artisanal beverage startups.
Beverage companies anchor volume commitments. Food service generates highest per-kilogram margins.
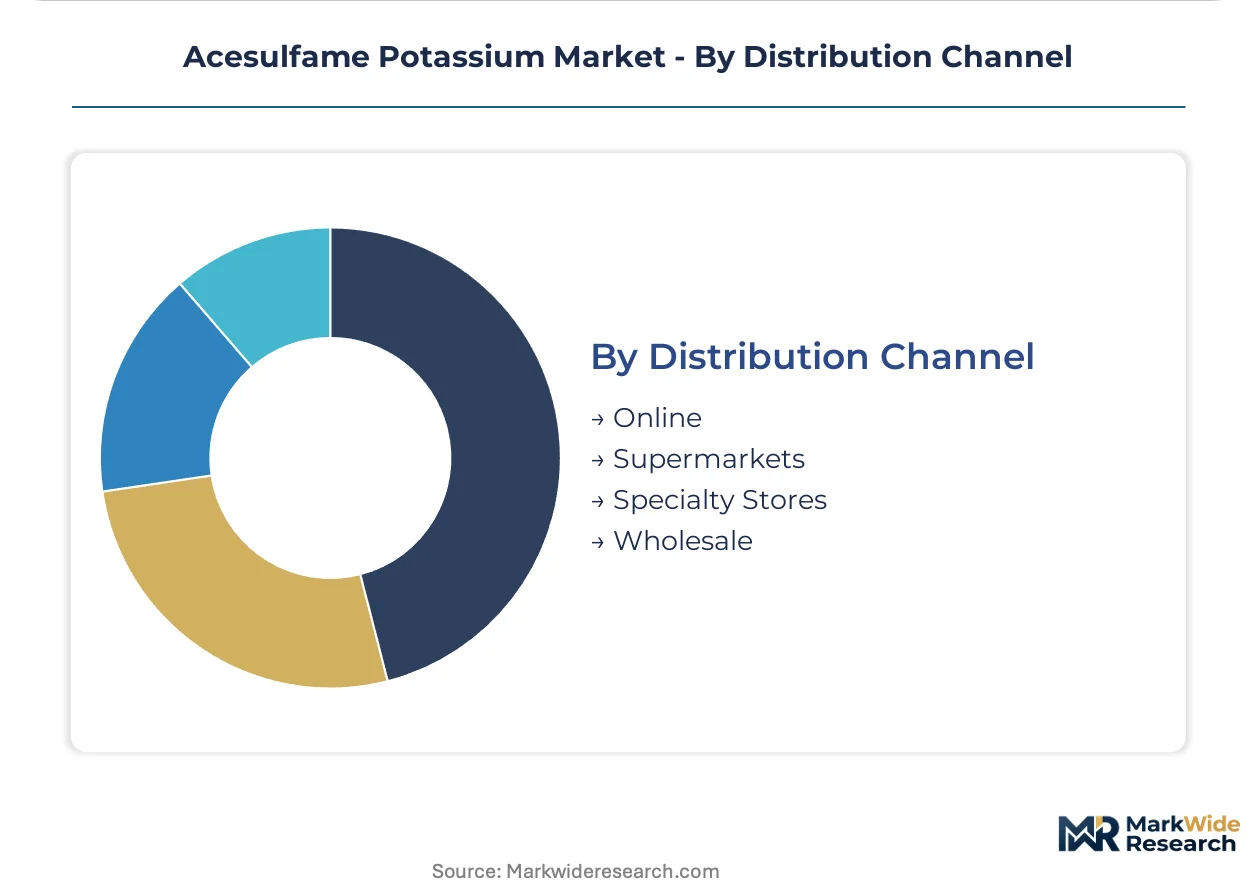
Distribution Channel:
Channel selection correlates with buyer technical sophistication and inventory velocity requirements.
- Wholesale:Bulk powder and granule shipments serve food manufacturers and beverage plants with dedicated receiving infrastructure. East China production clusters leverage export-oriented logistics efficiencies to shorten delivery windows to ASEAN buyers.
- Online:E-commerce platforms capture small-batch and specialty format demand from food service and artisanal producers. Direct procurement interfaces enable technical specification matching without distributor markup.
- Supermarkets:Retail-packaged tablets and consumer-size powder containers serve household and small commercial buyers. Shelf placement competes with stevia and sucralose alternatives in clean-label positioning.
- Specialty Stores:Professional-grade formats and technical consultation support food service and boutique beverage operations. Store staff provide blending ratio guidance for reformulation trials.
Wholesale channels move crystallization tonnage. Online is climbing the fastest for specialty formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugar-reduction mandates and clean-label incentives are redirecting sweetener procurement across major consuming economies. Regulatory divergence between FDA GRAS pathways, EFSA evaluations, and China's SAMR standards is fragmenting supplier qualification requirements.
United States
Beverage reformulation at Atlanta and Purchase headquarters clusters compresses procurement cycles toward just-in-time crystallization output. FDA GRAS status and EPA effluent guidelines shape market access for domestic and imported supply. Carbonated soft drink technical teams direct-procure crystallization capacity, displacing traditional distributor intermediation.
China
SAMR's updated GB 25540 purity standards impose tighter heavy metal thresholds, forcing crystallization line upgrades among domestic producers. East China concentrates manufacturing gravity, with Jiangsu and Shandong provinces hosting export-oriented production clusters serving ASEAN and Middle Eastern buyers. Continuous production lines in these provinces operate at scale for international markets.
Germany
REACH compliance and EFSA sweetener evaluations govern import eligibility for European beverage and confectionery manufacturers. EU Green Deal alignment creates preference premiums for suppliers with verified carbon footprint reductions in crystallization energy use. Nutrinova anchors continental demand through its Hoechst legacy distribution network.
Brazil
Sports and energy drink categories present underpenetrated demand for heat-stable sweetening systems that survive pasteurization. ANVISA regulates food additive approvals, with import documentation requirements affecting supplier qualification timelines. São Paulo-based beverage formulators are adopting liquid concentrate formats for precision dosing in high-speed bottling lines.
India
FSSAI governs food additive standards, with import clearance protocols affecting crystalline sweetener entry timelines. Carbonated and functional drink makers in Maharashtra and Gujarat are reformulating product lines, compressing sweetener procurement cycles. Mumbai and Ahmedabad industrial corridors concentrate beverage manufacturing capacity.
Acesulfame Potassium Market Vendor Landscape
Player mix skews toward integrated chemical manufacturers with captive acetoacetic acid supply and export-oriented crystallization specialists. The competitive terrain splits between scale-driven continuous producers and quality-certified suppliers serving multinational beverage accounts. Three archetypes dominate: backward-integrated chemical conglomerates, export-focused crystallization specialists, and distributor-anchored regional suppliers. Capacity expansion and ISO 22000 certification maintenance constitute the dominant competitive moves, with audit cycles filtering out smaller producers unable to sustain documentation systems.
Within the integrated chemical tier, Changzhou Niutang Chemical Plant Co., Ltd. and Anhui Jinhe Industrial Co., Ltd. represent the archetype of Chinese manufacturers with scale advantages in continuous production. Among European-anchored suppliers, Nutrinova (Celanese Corporation) occupies a position exemplifying legacy distribution network leverage. Suzhou Hope Technology Co., Ltd. sits within the export-specialist tier, reflecting the Jiangsu province production clustering that dominates crystallization output for international markets. These three names illustrate the geographic and structural segmentation that defines competitive positioning.
| Leading Market Players |
|---|
| Changzhou Niutang Chemical Plant Co., Ltd. |
| Suzhou Hope Technology Co., Ltd. |
| Nutrinova (Celanese Corporation) |
| Shandong Minghui Food |
| Jiangsu Vitasweet |
| HYET Sweet |
| Anhui Jinhe Industrial Co., Ltd. |
| Jiangxi BEIYANG Food Additive |
| Hermes Sweeteners |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day crystallization lead times compress pricing power toward East China producers with continuous output capability, while sulfur dioxide feedstock volatility forces non-integrated suppliers into defensive contract structures. Beverage direct-procurement teams exploit this concentration to extract volume-commitment discounts that strand smaller batch producers.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-verified crystallizers and uncertified regional suppliers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade tiers separates multinational beverage accounts from domestic dairy processors. Pricing pressure stems from acetoacetic acid cost compression as captive producers expand upstream control. Food manufacturers exhibit highest price sensitivity due to quarterly contract structures, while beverage technical teams prioritize particle-size consistency over unit cost.
Supply Chain Analysis
China anchors crystallization capacity with Jiangsu and Shandong provinces hosting export-oriented continuous production lines for ASEAN and Middle Eastern buyers. Acetoacetic acid, sulfur dioxide, and acetic anhydride constitute critical input dependencies. Single-source vulnerability concentrates in sulfur dioxide supply chains tethered to petrochemical feedstock markets. Distribution runs through wholesale bulk shipments to beverage plants with dedicated receiving infrastructure, supplemented by liquid concentrate direct delivery to high-speed bottling lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage company consolidation into direct-procurement technical teams has shifted negotiating leverage toward buyers with crystallization scheduling control, fragmenting traditional distributor intermediation.
For Market Incumbents: Secure captive acetoacetic acid supply through backward integration or long-term offtake agreements to stabilize margin exposure against sulfur dioxide volatility. Expand ISO 22000-certified capacity in Jiangsu province to defend position against SAMR purity standard upgrades that strand non-compliant competitors.
For New Entrants and Emerging Players: Lead with liquid concentrate formats targeting São Paulo and Mexico City beverage formulators seeking pasteurization-stable precision dosing systems. Penetrate functional drink categories in Brazil where heat-stable sweetening systems remain underdeployed. Bundle on-site technical service to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 22000 audit cycles filter smaller producers while continuous crystallization scale-up demands capital intensity beyond mid-tier capacity. Target export-oriented Jiangsu specialists with verified EU REACH compliance and carbon footprint documentation. Watch EFSA sweetener evaluation timelines as inflection signals for European formulation lock-ins.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetoacetic Acid | Captive precursor supply insulates Changzhou Niutang and Anhui Jinhe from sulfur dioxide feedstock volatility. |
| Continuous Crystallization Scale-Up | Particle-size consistency reduces dissolution time for Atlanta and Purchase beverage headquarters clusters. |
| ISO 22000 Certification Investment | Audit documentation systems filter smaller domestic suppliers under SAMR GB 25540 heavy metal thresholds. |
| Liquid Concentrate Format Expansion | Precision dosing systems penetrate São Paulo functional drink lines seeking pasteurization stability. |
| EU REACH Compliance Front-Loading | Toxicology dossier preparation prevents supply interruptions from ECHA substance evaluation workflow extensions. |
Methodological Framework
Initial hypotheses were tested against primary input from crystallization plant managers, beverage procurement technical leads, food additive regulatory consultants, and East China logistics operators and refined through secondary validation against SAMR GB standard filings, EFSA sweetener evaluation dossiers, customs export data, and SEC chemical segment disclosures. Bottom-up crystallization capacity estimates triangulated with top-down beverage reformulation demand projections.
Variance decomposition across product format, application category, customer archetype, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by purity grade pricing differentials. Crystallization energy intensity and REACH carbon footprint verification timelines entered as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside SAMR enforcement consistency, EFSA evaluation pacing, or acetoacetic acid supply stability would require recalibration. Forecasts reflect assumptions around sulfur dioxide feedstock market continuity and beverage direct-procurement adoption curves. Recalibration cycles align with material shifts in regulatory divergence patterns and crystallization technology commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market