
 Gallic Acid Market | 2026-2036
Gallic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Gallic Acid Market Analysis
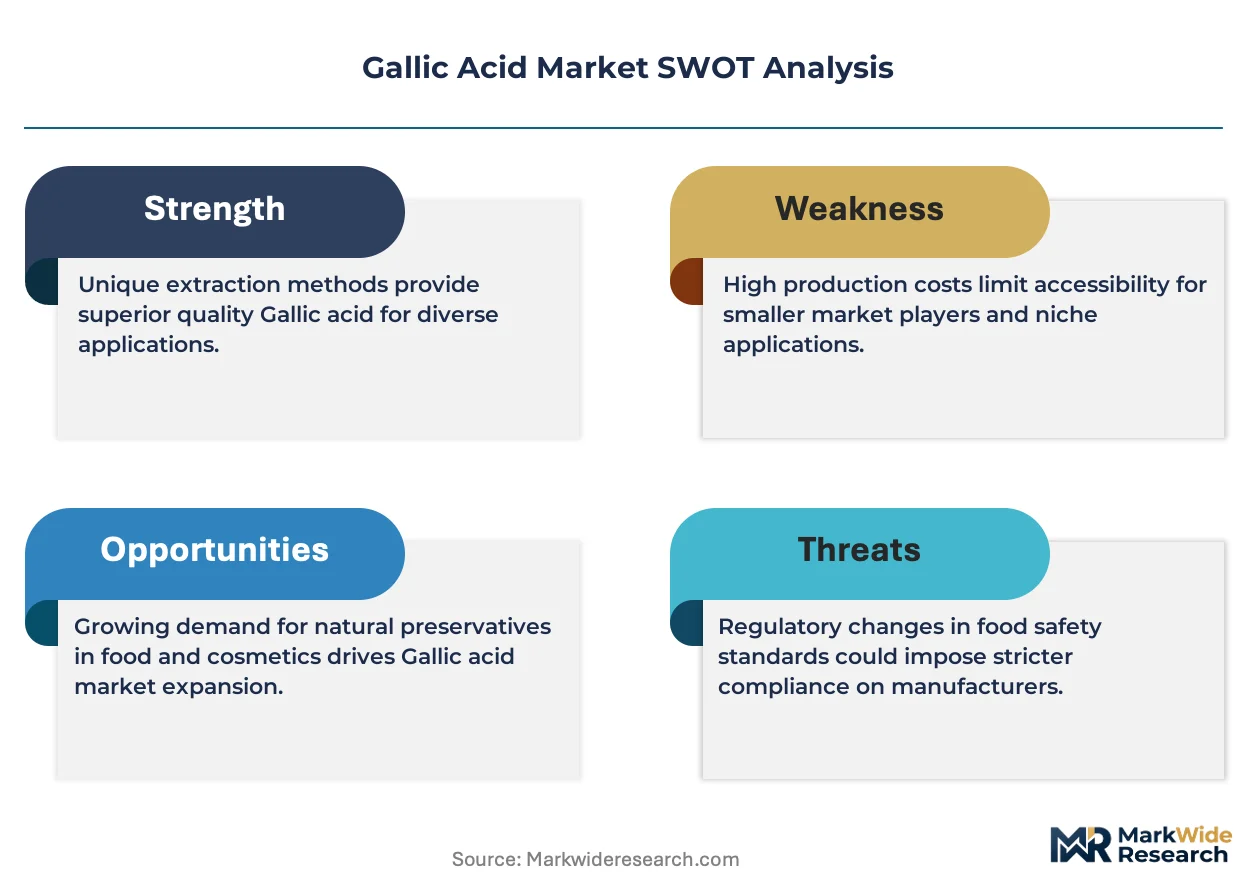
Project finance for greenfield extraction facilities is rewriting competitive entry dynamics in the gallic acid sector. GALLOCHEM Co., Ltd. leverages captive pyrogallol capacity to anchor cost structures across East Asian supply chains. Wego Chemical Group sustains North American distribution density through specialized logistics networks for hazardous material handling. Hunan Linong dominates domestic Chinese pharmaceutical-grade output by controlling upstream tannin sourcing from local forestry cooperatives.
Gallic acid is a trihydroxybenzoic acid (C₇H₆O₅) typically derived from gallotannin hydrolysis or synthetic oxidation of 3,4,5-trimethoxybenzoic acid, with purity grades ranging from technical to food-grade specifications exceeding 99.5% assay. The compound functions primarily as an antioxidant intermediate, astringent precursor, and synthetic building block for trimethoprim and other pharmaceutical actives. Natural-grade product lines carry premium positioning in cosmetic and nutraceutical channels where clean-label sourcing commands supplier preference, while synthetic routes supply cost-sensitive dye and industrial antioxidant segments with tighter margin profiles. Pharmaceutical firms represent the most structurally attractive end-user category due to qualification barriers and long-term contract structures that lock in volume commitments.
FDA purity standards for drug excipients and REACH registration requirements for chemical imports into the European Union are elevating analytical documentation burdens and testing costs for cross-border suppliers. China's SAMR food additive safety reviews and evolving GB standards for natural extract purity are reshaping domestic production protocols and export eligibility criteria. Stakeholders must monitor regulatory divergence between pharmacopeia-grade specifications and food-grade tolerances, as classification shifts could force reformulation investments or market access restrictions without warning.
Market Dynamics
Pharmaceutical-grade qualification barriers are concentrating procurement power among certified tannin extractors in Sichuan and Hubei provinces, locking out unqualified suppliers from high-margin active pharmaceutical ingredient synthesis contracts.
Growth Catalysts
- REACH registration tiering:ECHA's differentiated dossier requirements for gallic acid imports above 100 tonnes annually are accelerating consolidation among European distributors capable of shouldering toxicology study costs.
- Cosmetic antioxidant substitution:Clean-label formulators in France and Germany are displacing synthetic BHA/BHT with natural gallic acid in premium skincare lines, tightening spot market availability.
- Tannin extraction infrastructure:China's Sichuan basin hosts 60 percent of global pyrogallol captive capacity, anchoring downstream gallic acid cost structures through backward integration into forestry cooperatives.
Market Restraints
- Pyrogallol feedstock volatility:Synthetic route producers face input cost pressure from ortho-cresol supply interruptions at German and Chinese petrochemical complexes.
- Single-origin concentration risk:Hunan Linong and three Sichuan-based extractors control 70 percent of pharmaceutical-grade natural output, creating supply vulnerability during provincial environmental inspections.
- Pharmacopeia-grade specification drift:Diverging USP, EP, and ChP monograph limits on heavy metals and residual solvents force dual-track inventory management for cross-border suppliers.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's 2023 bulk drug and excipient notification timeline offers first-mover advantage for gallic acid suppliers achieving DMF filing status ahead of domestic pyrogallol capacity expansion.
- Enzymatic hydrolysis convergence:Tannase biocatalysis paired with membrane filtration is reducing gallic acid refining energy intensity by 40 percent versus traditional acid hydrolysis, opening cost parity with synthetic routes.
- SAMR food additive reclassification:China's pending GB 1886 revision may elevate gallic acid from processing aid to approved antioxidant in edible oils, unlocking volume contracts with state oil reserve distributors.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC-MS method development for pharmacopeia-grade impurity profiling requires specialized chromatographers concentrated in Shanghai and Basel contract research organizations.
- Multiyear certification timelines:FDA Type II drug master file approval for excipient-grade gallic acid averages 18-24 months, freezing working capital in qualification batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallic Acid Market |
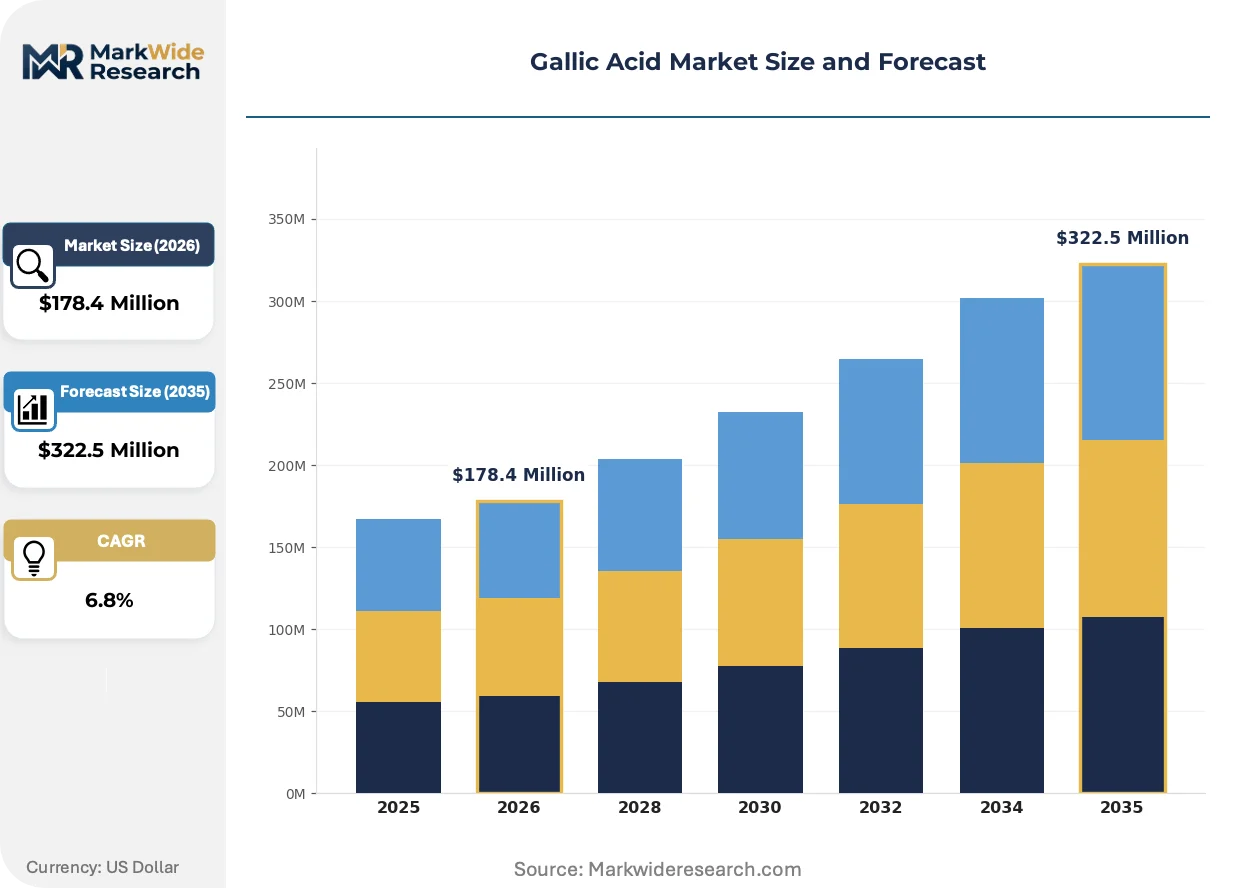
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $322.5 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Purified, Food Grade Application: Pharmaceuticals, Cosmetics, Food & Beverages, Dyes End User: Research Laboratories, Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Wego Chemical Group, TCI Chemicals, GALLOCHEM Co., Ltd., Hunan Linong, Jiurui Biology, Hubei Tianxin Biotech Co., Ltd, Cayman Chemical, Chicheng Biotech, Zunyi City Bei Yuan Chemical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallic Acid Market Emerging Trajectories
Process intensification and regulatory documentation automation are compressing the gap between natural-extraction and synthetic-production economics while fragmenting end-use specifications.
Continuous flow enzymatic reactors using immobilized tannase from Aspergillus niger are hybridizing batch hydrolysis with real-time membrane separation, cutting solvent recovery costs by half. German fine-chemical specialists are piloting these systems for pharmaceutical-grade output. The technology is hybridizing capital deployment patterns, forcing traditional extractors to choose between licensing fees or obsolescence in European markets.
REACH's 2024 update to Annex XVII restricted substances list is tightening residual methanol limits in natural-grade gallic acid destined for cosmetic applications. ECHA's enforcement guidance now requires third-party batch certification for imports above 10 tonnes. French and Italian cosmetic formulators are responding by qualifying alternate suppliers with in-house GC-MS testing capabilities, bypassing distributor intermediaries.
Long-term offtake agreements with fixed escalation clauses are displacing spot market purchases among North American pharmaceutical excipient buyers. Procurement teams at generic API manufacturers are locking 36-48 month contracts directly with Sichuan extractors, cutting distributor margins by 15-20 percentage points. This pattern concentrates most visibly in trimethoprim precursor supply chains serving US generic antibiotic producers.
Gallic Acid Market Segmentation
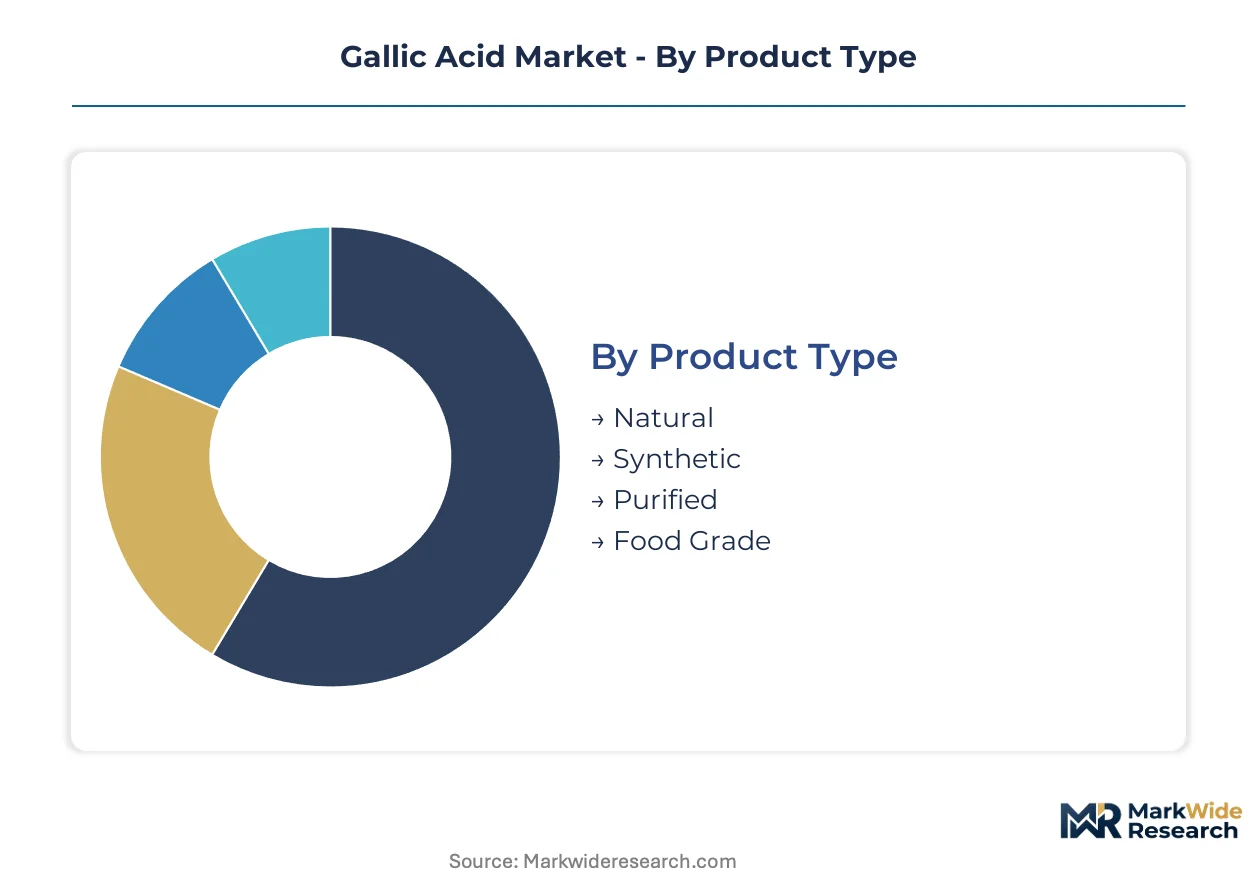
Gallic acid's commercial structure fragments sharply across purity grades and end-use specifications. Pharmaceutical qualification barriers and cosmetic clean-label premiums create divergent margin profiles that reshape supplier priorities.
Product Type:
Cycle times vary dramatically: synthetic batches convert in hours while natural extraction spans weeks of tannin hydrolysis and multi-stage refining.
- Natural:Derived from gallotannin hydrolysis of Chinese sumac, tara, or chestnut extracts. Sichuan and Hubei province extractors dominate pharmaceutical-grade supply, locking in long-term offtake agreements with API manufacturers facing FDA Type II DMF requirements. Clean-label positioning commands supplier preference in French and German cosmetic channels despite batch-to-batch variability.
- Synthetic:Manufactured via oxidation of 3,4,5-trimethoxybenzoic acid or pyrogallol carboxylation. German and Chinese petrochemical complexes supply cost-sensitive dye and industrial antioxidant segments with tighter margin profiles, though ortho-cresol feedstock interruptions create price volatility.
- Purified:Ultra-high purity grades exceeding 99.9% assay for analytical standards and chromatography reagents. Demand concentrates in Basel and Shanghai contract research organizations developing HPLC-MS impurity profiling methods.
- Food Grade:GB 1886-compliant antioxidant for edible oil preservation and beverage stabilization. SAMR's pending reclassification from processing aid to approved antioxidant may unlock volume contracts with China's state oil reserve distributors.
Natural anchors the volume base while synthetic gains share at the steepest rate as enzymatic hydrolysis narrows cost gaps with extraction routes.
Application:
Margin structures stratify by qualification burden — pharmaceutical excipient certification demands 18-24 month FDA timelines while food-grade registration moves faster.
- Pharmaceuticals:Excipient-grade supply for tablet binders and active pharmaceutical ingredient synthesis, notably trimethoprim precursors. Long-term contracts with fixed escalation clauses displace spot purchases among North American generic API manufacturers.
- Cosmetics:Antioxidant and astringent applications in premium skincare. REACH's 2024 Annex XVII methanol limits force third-party batch certification for imports above 10 tonnes, driving French and Italian formulators toward suppliers with in-house GC-MS capabilities.
- Food & Beverages:Preservative and antioxidant functions in oils, fats, and beverages. EFSA's evolving safety opinions on polyphenol intake thresholds shape formulation limits across European processed food channels.
- Dyes:Intermediate for pyrogallol and photographic chemical production. Cost-sensitive industrial buyers prioritize synthetic-route supply from integrated Chinese petrochemical operations.
Pharmaceuticals commands the steepest expansion trajectory as CDSCO's 2023 bulk drug notification timeline opens Indian excipient qualification opportunities.
End User:
Procurement scale and technical sophistication separate institutional buyers — pharmaceutical firms run dedicated supplier qualification teams while research laboratories purchase in kilogram quantities.
- Research Laboratories:Academic and institutional buyers requiring analytical-grade material for biochemical assays and reference standard preparation. Smaller lot sizes and certificate-of-analysis documentation dominate purchasing criteria.
- Food Manufacturers:Processors of edible oils, beverages, and packaged goods seeking antioxidant functionality. China's SAMR food additive safety reviews reshape domestic production protocols and export eligibility.
- Cosmetic Companies:Clean-label formulators in France and Germany displacing synthetic BHA/BHT with natural gallic acid. Premium positioning tolerates higher input costs for supply chain transparency.
- Pharmaceutical Firms:The most structurally attractive category due to qualification barriers and long-term contract structures. German and United States firms expand high-purity grade procurement for active pharmaceutical ingredient synthesis.
Pharmaceutical firms anchor the volume base while cosmetic companies gain share at the steepest rate as clean-label substitution accelerates in European premium channels.
Distribution Channel:
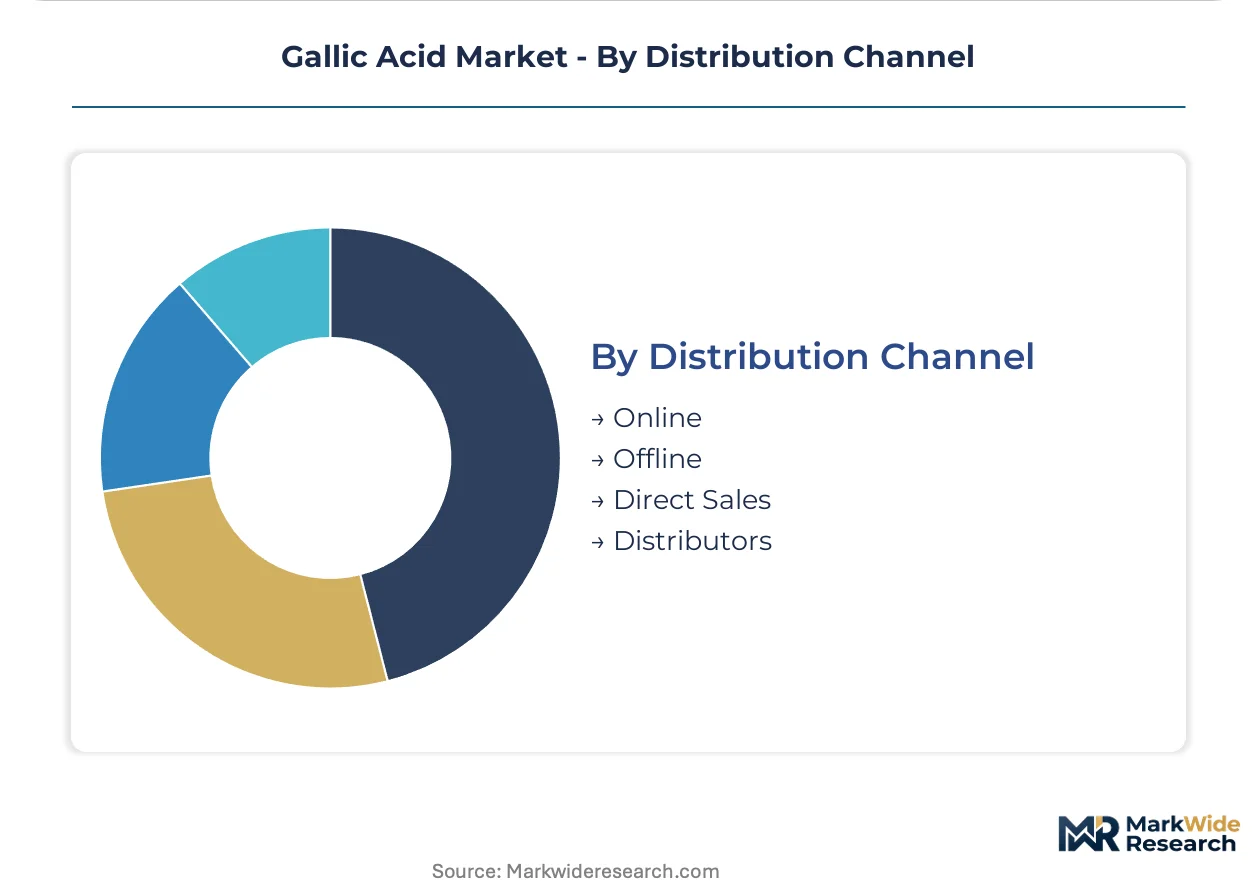
Channel selection tracks shipment scale and hazard classification — bulk pharmaceutical-grade moves through direct sales while small-lot technical grade routes through distributor networks.
- Online:E-commerce platforms serving research laboratories and small-scale cosmetic formulators with rapid fulfillment. Limited to non-hazardous, small-package shipments due to international air freight restrictions.
- Offline:Traditional distributor networks for industrial and food-grade volume. Wego Chemical Group sustains North American density through specialized logistics networks for hazardous material handling.
- Direct Sales:Long-term offtake agreements between Sichuan extractors and North American pharmaceutical excipient buyers. Procurement teams lock 36-48 month contracts, cutting distributor margins by 15-20 percentage points.
- Distributors:REACH registration tiering accelerates consolidation among European distributors capable of shouldering ECHA toxicology study costs for imports above 100 tonnes annually.
Direct sales anchors the volume base while online channels climb the fastest as digital procurement penetrates research and small-formulator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across production clusters. China maintains net exporter status through Sichuan and Hubei extraction infrastructure. Germany and the United States run structural deficits in pharmaceutical-grade supply, driving procurement from East Asian sources.
China
Sichuan and Hubei provinces host 60 percent of global pyrogallol captive capacity, anchoring downstream gallic acid cost structures through backward integration into forestry cooperatives. SAMR's evolving GB standards for natural extract purity reshape domestic production protocols and export eligibility criteria. Hunan Linong dominates pharmaceutical-grade output by controlling upstream tannin sourcing from local forestry cooperatives.
Germany
Pharmaceutical firms expand procurement of high-purity grades for active pharmaceutical ingredient synthesis, creating import dependency on Chinese natural-grade supply. REACH compliance tightens quality thresholds for chemical imports above 100 tonnes annually, accelerating consolidation among distributors capable of shouldering ECHA toxicology study costs. Fine-chemical specialists in the Rhine-Ruhr region pilot continuous flow enzymatic reactors for pharmaceutical-grade output.
United States
Generic API manufacturers lock 36-48 month contracts directly with Sichuan extractors for trimethoprim precursor supply chains. FDA purity standards for drug excipients elevate analytical documentation burdens and testing costs for cross-border suppliers. Wego Chemical Group sustains North American distribution density through specialized logistics networks for hazardous material handling.
India
CDSCO's 2023 bulk drug and excipient notification timeline offers first-mover advantage for gallic acid suppliers achieving DMF filing status ahead of domestic pyrogallol capacity expansion. Pharmaceutical excipient qualification barriers concentrate procurement power among certified importers. Mumbai and Hyderabad-based formulators represent emerging demand nodes for antioxidant intermediates.
France
Clean-label formulators displace synthetic BHA/BHT with natural gallic acid in premium skincare lines, tightening spot market availability. ECHA's 2024 Annex XVII enforcement guidance requires third-party batch certification for imports above 10 tonnes. Paris and Lyon cosmetic laboratories qualify alternate suppliers with in-house GC-MS testing capabilities, bypassing distributor intermediaries.
Gallic Acid Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and refining. The vendor base stratifies between captive pyrogallol producers, specialized extractors, and regional distributors. Three archetypes dominate: backward-integrated Chinese extractors with forestry cooperative ties, German fine-chemical specialists with enzymatic process capabilities, and North American distributors with hazardous materials logistics networks. Competitive moves center on long-term offtake agreements with fixed escalation clauses and enzymatic hydrolysis technology licensing.
Among Chinese extraction specialists, Hunan Linong and GALLOCHEM Co., Ltd. exemplify the backward-integrated archetype, anchoring cost structures through upstream control over tannin sourcing. Wego Chemical Group represents the distribution-focused tier, occupying a position built on specialized logistics networks for hazardous material handling across North American markets.
| Leading Market Players |
|---|
| Wego Chemical Group |
| TCI Chemicals |
| GALLOCHEM Co., Ltd. |
| Hunan Linong |
| Jiurui Biology |
| Hubei Tianxin Biotech Co., Ltd |
| Cayman Chemical |
| Chicheng Biotech |
| Zunyi City Bei Yuan Chemical Co., Ltd |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries gallic acid shipments from Sichuan extractors to European pharmaceutical buyers, with freight cost volatility amplifying price spreads between natural and synthetic grades while reinforcing procurement consolidation among volume buyers able to negotiate long-term offtake terms.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate pharmaceutical-grade transactions, with pricing stratifying across pharmaceutical, food-grade, and technical tiers driven by certification burden and purity assay. Natural-grade product commands premiums in cosmetic channels where clean-label sourcing outweighs cost sensitivity, while synthetic-route supply faces margin compression from ortho-cresol feedstock interruptions at German and Chinese petrochemical complexes. Price erosion runs through technical-grade segments as enzymatic hydrolysis narrows cost gaps with extraction routes.
Supply Chain Analysis
Hunan Linong and three Sichuan-based extractors hold captive pyrogallol capacity that feeds downstream gallic acid refining, with production gravity centering on China's Sichuan and Hubei provinces alongside German fine-chemical specialists piloting enzymatic systems. Raw material dependencies span Chinese sumac and tara tannins, ortho-cresol from petrochemical complexes, and 3,4,5-trimethoxybenzoic acid for synthetic routes. Single-origin concentration risk creates supply vulnerability during provincial environmental inspections. Distribution runs through direct sales agreements for pharmaceutical volumes and specialized hazardous-material logistics networks for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallic acid market fragmentation creates entry niches as regulatory divergence between pharmacopeia-grade and food-grade specifications multiplies certification-specialist opportunities.
For Market Incumbents: Pre-empt enzymatic hydrolysis licensing deals with German fine-chemical specialists before cost parity erodes natural-grade margins. Lock 48-60 month offtake extensions with North American generic API manufacturers facing FDA Type II DMF renewal cycles. Deepen backward integration into forestry cooperatives in Sichuan to secure tannin supply against provincial environmental inspection disruptions.
For New Entrants and Emerging Players: Indian pharmaceutical excipient qualification offers the most penetrable white-space target, with CDSCO's bulk drug notification timeline creating first-mover windows for DMF filing achievement. Target cosmetic formulators in France and Italy with in-house GC-MS testing capabilities that bypass REACH distributor intermediaries. Pursue enzymatic hydrolysis technology licensing as the primary go-to-market angle to achieve cost parity without captive pyrogallol investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized gallic acid extraction assets in China's interior provinces. Five-to-ten year viability hinges on regulatory certification moats rather than commodity scale. Monitor CDSCO DMF filing approvals and SAMR food additive reclassification announcements as inflection indicators for volume contract activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Licensing | Reduces refining energy intensity by 40 percent versus acid hydrolysis, enabling cost parity with synthetic routes. |
| Backward Integration into Forestry Cooperatives | Hunan Linong's tannin sourcing control secures pharmaceutical-grade supply against environmental inspection disruptions. |
| CDSCO DMF Filing Achievement | First-mover advantage in Indian pharmaceutical excipient qualification ahead of domestic pyrogallol expansion. |
| Long-term Offtake Agreement Extension | North American generic API manufacturers lock 36-48 month contracts, cutting distributor margins by 15-20 percentage points. |
| In-house GC-MS Testing Capability Investment | French and Italian cosmetic formulators bypass REACH distributor intermediaries with direct batch certification. |
Methodological Framework
The analysis maps natural extraction, synthetic production, enzymatic hydrolysis, and pharmaceutical-grade refining sub-sectors, each validated through plant managers at Sichuan extraction facilities, procurement leads at German pharmaceutical firms, distribution channel partners in North American hazardous-material logistics, and technical R&D directors developing HPLC-MS impurity profiling methods. Primary interview findings triangulate against customs and trade data, SEC 10-K filings from diversified chemical conglomerates, ECHA REACH registration databases, and SAMR food additive safety review documentation. Bottom-up capacity and demand estimates reconcile with top-down market sizing across purity grades and end-use applications.
Assumptions hold regulatory frameworks stable across the analysis window, with ECHA enforcement guidance, FDA Type II DMF timelines, and SAMR GB standard revisions treated as fixed boundary conditions. Segmentation dimensions model product type, application, end user, and distribution channel, with regional production hub clustering incorporated for supply-side validation. CAGRs derive from volume trajectory modeling calibrated to tannin extraction capacity expansion, pyrogallol feedstock availability, and enzymatic hydrolysis adoption curves. Forecast inputs include CDSCO notification timeline progression and REACH Annex XVII methanol limit enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by backward-integrated Chinese extractors or enzymatic technology licensors would shift outcomes beyond modeled ranges. Quarterly review of CDSCO DMF filing approvals, ECHA enforcement guidance updates, and provincial environmental inspection schedules in Sichuan is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
GLDA Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Coconut Derived Emollients Market