
 LAMEA Metal Biocides Market | 2026-2036
LAMEA Metal Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Metal Biocides Market Insights
Asset-light leasing models for specialty chemical manufacturing equipment is reconfiguring competitive entry barriers across the LAMEA region, enabling mid-sized distributors to contract toll production without committing capital to fixed plants. BASF SE leverages its integrated antimicrobials technology platform to sustain formulation leadership in copper- and silver-based concentrates. Lonza Group anchors its regional presence through controlled-release biocide technologies that extend product efficacy in high-salinity Middle Eastern water treatment applications. Lanxess AG competes on manufacturing scale, operating bulk powder production capabilities that position it for construction-sector procurement tenders in Saudi Arabia and the UAE.
Metal biocides are inorganic antimicrobial agents—typically copper, silver, or zinc compounds formulated as oxides, salts, or complexes—that disrupt microbial cell membranes and enzymatic function at concentrations measured in parts per million. These compounds serve primarily to prevent biofilm formation, algae propagation, and bacterial colonization on industrial surfaces, in process water, and within preserved materials. Copper formulations dominate volume across water treatment and wood preservation applications due to their established efficacy against sulfate-reducing bacteria and lower unit cost relative to silver. Silver-based products command premium positioning in healthcare end uses and textile antimicrobial finishing, where regulatory tolerance for residual toxicity is narrowest. Zinc variants occupy a mid-tier functional role, frequently deployed as synergistic boosters in coating systems rather than standalone primary actives.
South Africa's National Regulator for Compulsory Specifications enforces biocidal product registration requirements that mirror REACH data obligations, while Brazil's ANVISA mandates toxicological dossiers for antimicrobial agents used in food-contact applications. The UAE's Ministry of Climate Change and Environment implements F-Gas-aligned chemical management protocols that restrict certain legacy organic biocides, indirectly expanding addressable demand for inorganic metal alternatives. Stakeholders must monitor evolving registration timelines and local content requirements, as procurement preferences in Saudi Arabia and Nigeria increasingly favor suppliers with regional blending or repackaging capabilities.
Market Dynamics
Desalination capacity expansion across water-stressed LAMEA economies is compressing procurement cycles for copper-based biocide formulations, as utilities prioritize biofouling prevention in membrane-intensive reverse osmosis infrastructure.
Growth Catalysts
- Stricter discharge mandates:South Africa's National Water Act amendments now require enhanced microbial control in industrial effluent, compelling mining and chemical processors to upgrade to silver- and zinc-formulated biocide systems.
- Offshore maintenance intensity:Brazil's pre-salt oil platform fleet generates sustained bulk demand for liquid metal biocide formulations in corrosion prevention and seawater injection systems.
- Controlled-release advances:High-salinity water treatment applications in the Middle East are adopting polymer-encapsulated copper technologies that extend dosing intervals and reduce operator intervention.
Market Restraints
- Silver price volatility:Fluctuations in London Bullion Market Association silver pricing directly compress margins for healthcare-grade antimicrobial formulations, forcing reformulation toward copper-zinc blends.
- Registration timeline friction:Brazil's ANVISA toxicological dossier requirements for food-contact biocide applications extend product commercialization cycles by 18-24 months versus comparable registrations in other LAMEA jurisdictions.
- Legacy organic substitution limits:Certain cooling water applications in the UAE retain isothiazolinone-based treatments where metal biocide compatibility with existing corrosion inhibitor packages remains unproven.
Strategic Opportunities
- Nigerian industrial corridor penetration:Port Harcourt and Lagos petrochemical clusters currently underutilize metal biocide preservation in process water, presenting first-mover positioning for suppliers establishing local blending partnerships.
- Textile antimicrobial finishing:Silver nanoparticle integration into Egyptian and Moroccan garment export production is accelerating as EU buyer specifications harden against residual formaldehyde from traditional organic biocides.
- Solar desalination hybridization:Concentrated solar power-integrated reverse osmosis plants in Saudi Arabia and the UAE require biocide formulations stable across extreme thermal cycling, favoring inorganic copper complexes over temperature-sensitive organic alternatives.
Industry Challenges
- Formulation chemist scarcity:The LAMEA region lacks sufficient technical personnel trained in controlled-release polymer science and high-salinity stability testing, constraining product development velocity for regional applications.
- Multi-jurisdictional dossier fragmentation:Suppliers must maintain separate registration packages for South Africa's NRCS, Brazil's ANVISA, and Saudi Arabia's SFDA, with no mutual recognition reducing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Metal Biocides Market |
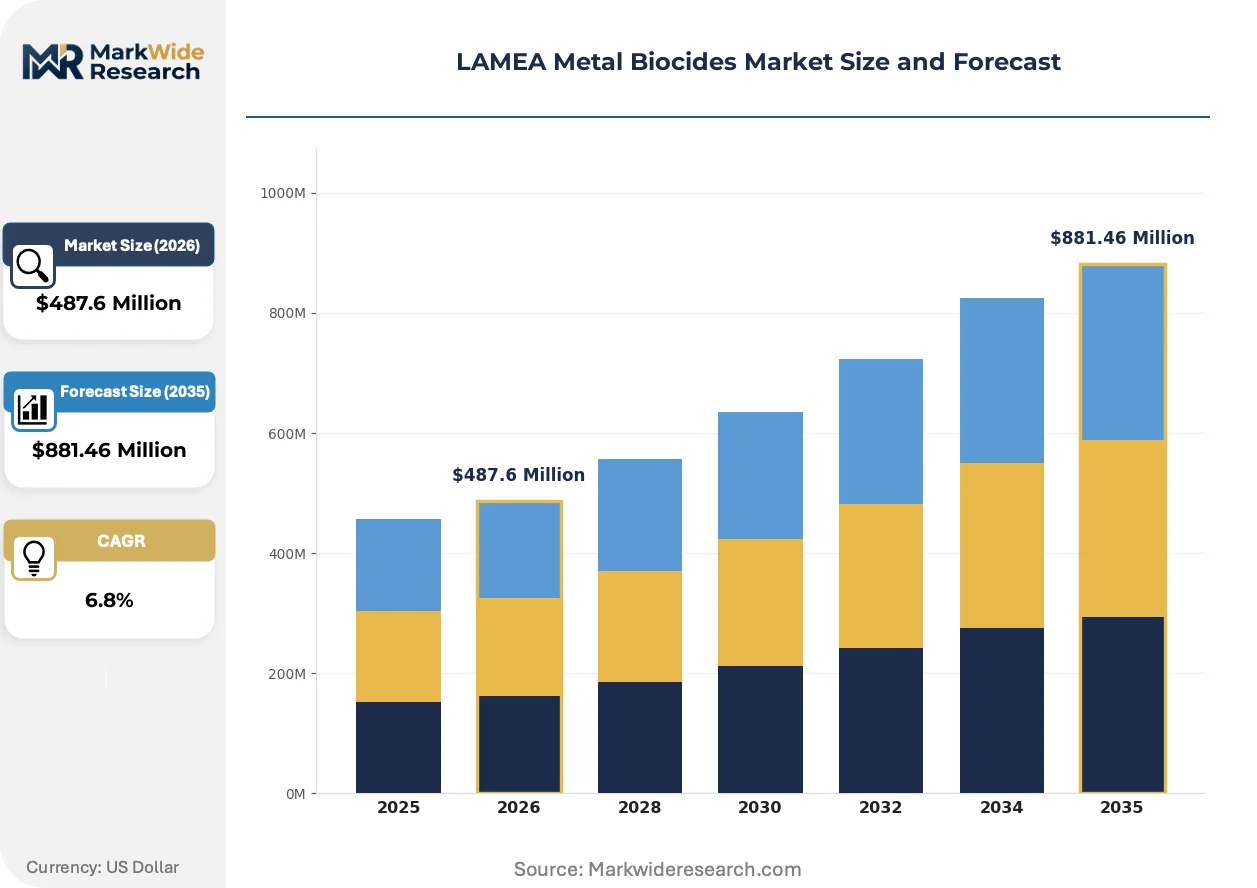
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Silver, Zinc, Others Application: Water Treatment, Wood Preservation, Coatings, Textiles End User: Healthcare, Agriculture, Construction, Food Processing Form: Liquid, Powder, Granular, Paste |
| Companies Covered | BASF SE, Clariant, Dow Chemical Company, Lonza Group, Troy Corporation, Lanxess AG, Evonik Industries AG, Akzo Nobel N.V., DuPont, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Metal Biocides Market Trends and Innovations
Electrochemical synthesis methods and nanostructured metal oxides are compressing production costs while expanding addressable application temperatures, reshaping competitive positioning between commodity and specialty biocide suppliers.
Copper-silver bimetallic nanoparticles synthesized through green electrochemical reduction are rendering obsolete conventional micron-scale copper carbonate suspensions in cooling tower applications. Saudi Aramco's refining operations have adopted these formulations at scale since 2022. The technology is rendering obsolete legacy powder-handling infrastructure and associated dust-exposure compliance costs across Gulf Cooperation Council industrial zones.
REACH-aligned registration requirements are diffusing through South Africa's NRCS and Brazil's ANVISA, elevating toxicological data burdens for biocide importers. This regulatory convergence favors established multinationals with existing European dossier libraries. Domestic Brazilian formulators lacking chronic ecotoxicity studies are retreating from direct importation toward toll-manufacturing arrangements with REACH-registered European principals.
Asset-light toll manufacturing contracts are displacing captive production investments among mid-sized LAMEA distributors. Regional chemical traders in Dubai and São Paulo now specify minimum-run volumes without fixed plant commitments. This model concentrates most visibly in Saudi Arabia's construction chemicals segment, where project-tied procurement favors flexible supply arrangements over long-term offtake agreements with integrated producers.
LAMEA Metal Biocides Market Segmentation
Metal biocide procurement patterns across Latin America, the Middle East, and Africa diverge sharply by product chemistry, application environment, and regulatory exposure. Understanding these segment boundaries enables suppliers to calibrate formulation investments against localized compliance costs and end-use performance requirements.
Product Type:
After-sales technical support intensity varies dramatically across metal biocide chemistries, with copper formulations requiring minimal field intervention while silver-based systems demand ongoing efficacy monitoring and residual testing protocols.
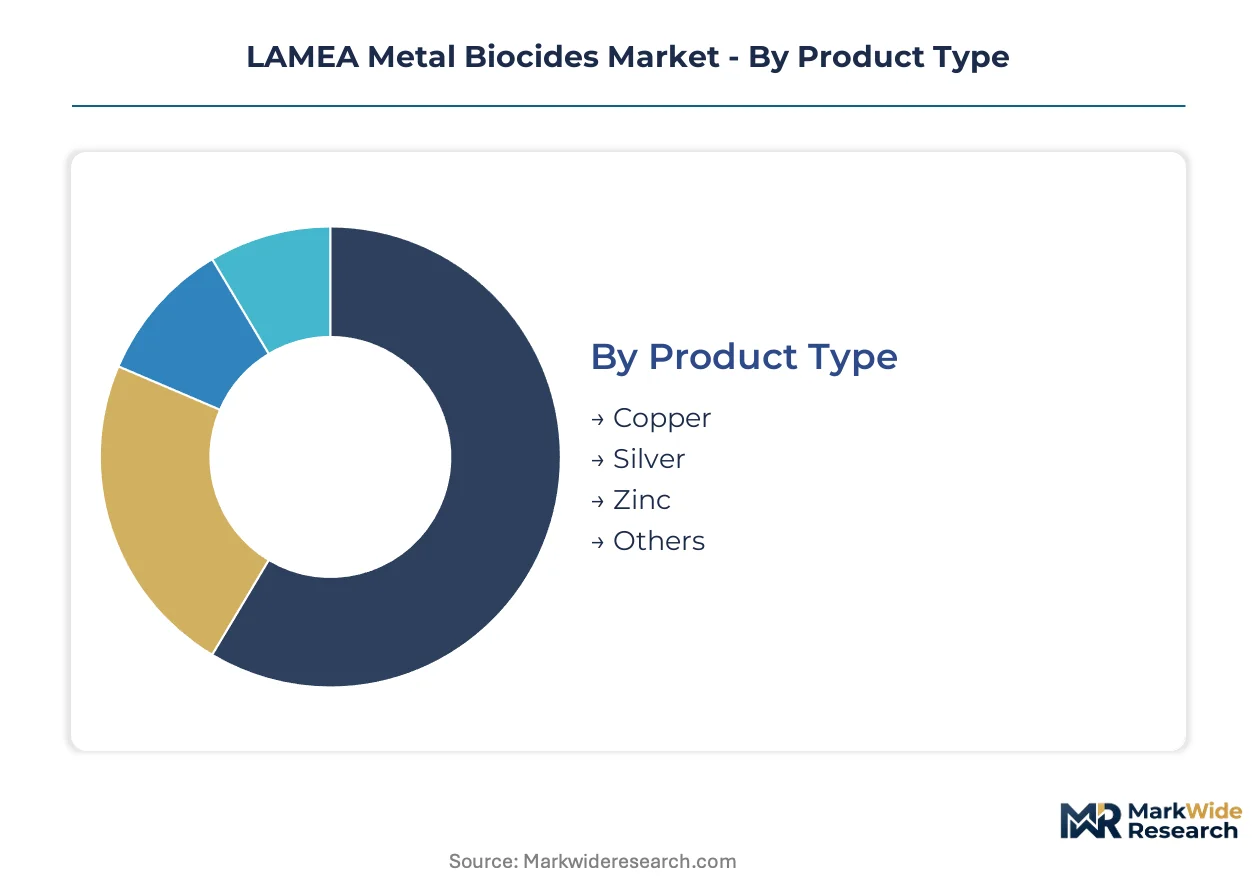
- Copper:Copper oxide and copper sulfate complexes dominate volume due to established efficacy against sulfate-reducing bacteria in cooling systems and wood preservation. Brazilian pulp mills and Middle Eastern desalination utilities drive concentrated procurement of liquid copper formulations where biofouling prevention in membrane infrastructure commands priority.
- Silver:Silver nanoparticle and ionic silver formulations serve healthcare textile finishing and medical device coatings where regulatory tolerance for residual toxicity is narrowest. Egyptian garment exporters and South African hospital procurement systems are expanding silver integration as EU buyer specifications harden against formaldehyde-based organic alternatives.
- Zinc:Zinc pyrithione and zinc oxide variants function primarily as synergistic boosters in marine coating systems rather than standalone actives.
- Others:Emerging bimetallic and organometallic complexes occupy niche positions in specialized industrial preservation.
Copper holds the largest share; momentum sits with silver as healthcare-grade specifications proliferate.
Application:
Application-driven cost tiers separate commodity water treatment volumes from premium coating and textile formulations where performance certification commands price premiums.
- Water Treatment:Reverse osmosis membrane protection, cooling tower biofouling control, and industrial process water preservation constitute the foundational demand base. Saudi Aramco refining operations and Brazilian offshore platforms generate sustained bulk procurement of copper-based liquid formulations.
- Wood Preservation:Pressure-treated lumber and engineered wood products in construction applications utilize copper azole and copper quaternary formulations. South African building code amendments are tightening preservative retention standards for structural timber.
- Coatings:Marine antifouling and architectural antimicrobial paints incorporate zinc pyrithione and silver nanoparticles for surface protection.
- Textiles:Silver-based finishing for healthcare uniforms and consumer apparel is climbing the fastest as Moroccan and Egyptian export manufacturers respond to EU market access requirements.
Water treatment anchors volume; textiles are expanding most quickly on regulatory substitution dynamics.
End User:
Customer-type maturity separates specification-driven healthcare procurement from price-sensitive agricultural applications where generic formulations predominate.
- Healthcare:Hospital surface disinfection, medical textile finishing, and device coating applications demand silver-based formulations with documented biocompatibility data. ANVISA registration requirements for food-contact and medical applications extend commercialization timelines.
- Agriculture:Crop protection and post-harvest preservation utilize copper-based fungicides and bactericides across Brazilian soybean operations and South African fruit export corridors.
- Construction:Wood treatment and antimicrobial concrete additives serve Saudi Arabian and UAE infrastructure development where specification compliance with Gulf standardization requirements governs procurement.
- Food Processing:Equipment sanitization and packaging preservation applications face stringent residual limits under South Africa's NRCS and Brazil's ANVISA jurisdictions.
Construction holds the largest share; healthcare gains share fastest on antimicrobial specification tightening.
Form:
Supply concentration favors liquid formulations where regional toll-blending infrastructure reduces import dependency and customs clearance friction.
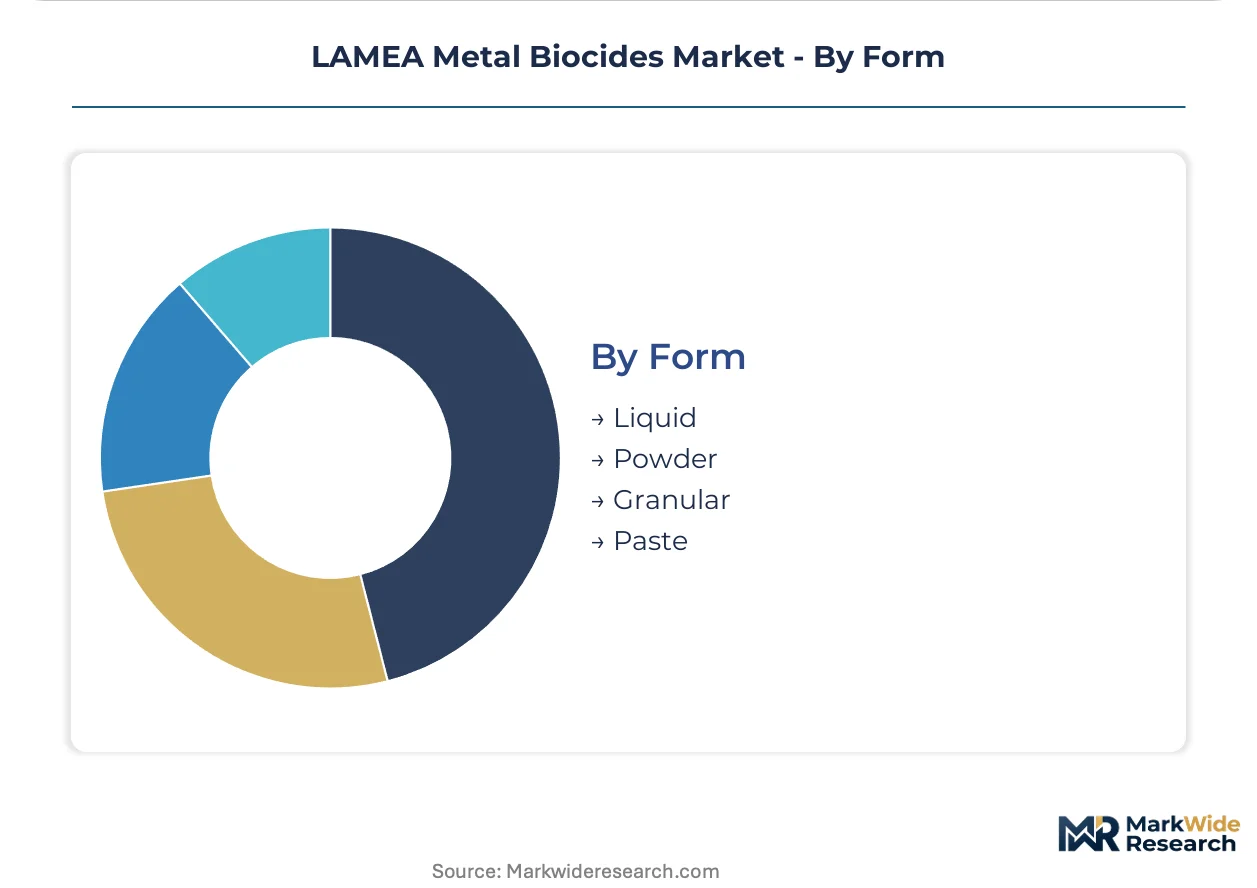
- Liquid:Ready-to-dose aqueous solutions and concentrates dominate industrial water treatment and cooling system applications. Dubai and São Paulo chemical traders specify minimum-run toll manufacturing volumes without fixed plant commitments.
- Powder:Dry copper carbonate and zinc oxide powders serve wood preservation pressure-treatment facilities and coating manufacturing.
- Granular:Controlled-release granules extend dosing intervals in high-salinity Middle Eastern water treatment environments.
- Paste:High-viscosity formulations target specialized marine and industrial maintenance applications requiring targeted application.
Liquid holds the largest share; granular shows steepest expansion trajectory on controlled-release technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desalination utilities in Saudi Arabia and offshore oil operators in Brazil concentrate the highest procurement volumes, while South African mining houses and Egyptian textile exporters drive premium formulation demand.
Brazil
Pre-salt oil platform maintenance and pulp mill operations generate sustained bulk demand for liquid copper biocide formulations. ANVISA mandates toxicological dossiers for food-contact antimicrobial applications, extending commercialization cycles. São Paulo chemical traders now specify minimum-run toll manufacturing volumes without fixed plant commitments.
Saudi Arabia
Solar desalination hybridization and refining operations compress procurement cycles for temperature-stable copper complexes. The SFDA enforces registration requirements that favor suppliers with existing European dossier libraries. The Eastern Province petrochemical corridor has adopted electrochemically synthesized copper-silver nanoparticles at scale since 2022.
South Africa
Mining effluent discharge mandates under amended National Water Act provisions accelerate substitution toward silver- and zinc-formulated systems. The NRCS enforces biocidal product registration mirroring REACH data obligations. The Johannesburg-Pretoria industrial belt drives concentrated demand for wood preservation and cooling water applications.
United Arab Emirates
High-salinity reverse osmosis infrastructure expands controlled-release copper technology adoption. The Ministry of Climate Change and Environment implements F-Gas-aligned protocols that restrict legacy organic biocides. Dubai's construction chemicals segment favors project-tied flexible supply arrangements over long-term offtake agreements.
Egypt
Garment export manufacturers integrate silver nanoparticle finishing to meet hardened EU buyer specifications against residual formaldehyde. The country's national chemical regulator maintains separate registration timelines from Gulf Cooperation Council jurisdictions. Cairo-Alexandria textile clusters present first-mover positioning for antimicrobial finishing suppliers.
LAMEA Metal Biocides Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers. The vendor base organizes around integrated multinationals with European registration libraries, regional toll-manufacturing distributors, and specialty technology licensors. Three archetypes dominate: REACH-registered principals with dossier depth, asset-light regional traders with flexible procurement, and controlled-release technology specialists. Competitive moves concentrate on toll-manufacturing partnerships and registration package leveraging across multiple jurisdictions.
Among integrated German chemical conglomerates, BASF SE and Lanxess AG exemplify scale-driven manufacturing archetypes with bulk powder capabilities positioned for construction-sector tenders. Lonza Group anchors the controlled-release technology specialist tier. These three entities represent distinct strategic positions: formulation leadership through integrated technology platforms, manufacturing scale for commodity procurement, and polymer-encapsulated efficacy extension in high-salinity environments.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Dow Chemical Company |
| Lonza Group |
| Troy Corporation |
| Lanxess AG |
| Evonik Industries AG |
| Akzo Nobel N.V. |
| DuPont |
| Others |
Pricing and Supply Chain Analysis
Silver bullion price volatility indexed to London Bullion Market Association benchmarks determines both margin compression in healthcare-grade formulations and the geographic reconfiguration of toll-manufacturing partnerships across Dubai and São Paulo. This commodity exposure compresses pricing tier spreads while accelerating substitution toward copper-zinc blends in cost-sensitive water treatment segments.
Pricing Analysis
Cost-plus contracts with London Bullion Market Association silver indexation dominate healthcare-grade antimicrobial procurement, while Brazilian pulp mills and Middle Eastern desalination utilities negotiate fixed-price annual offtakes for copper-based liquid formulations. Price differentiation separates REACH-registered premium tiers from unregistered economy imports in South African mining applications. Pricing pressure stems from silver spot volatility forcing reformulation toward bimetallic copper-silver nanoparticles. Agricultural processors in Brazil exhibit highest price sensitivity; Saudi Aramco refining operations demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Dubai-based chemical traders now stretch to 90 days for mid-sized Brazilian distributors, compressing working capital cycles. Manufacturing concentration centers on Germany, China, and India for active pharmaceutical-grade silver salts; copper sulfate feedstock draws from Chilean and Peruvian mining operations. Single-source vulnerability runs through Chinese-controlled electrochemical synthesis equipment for nanoparticle production. Distribution runs through São Paulo and Dubai hub-and-spoke networks with regional toll-blending satellites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA metal biocides market represents a high-growth disruption anchored by electrochemical synthesis methods that collapsed production costs for copper-silver bimetallic nanoparticles. REACH-aligned regulatory convergence across South Africa's NRCS and Brazil's ANVISA is consolidating competitive position behind dossier-rich European principals.
For Market Incumbents: Harden registration package leverage by cross-walking existing REACH chronic ecotoxicity studies into ANVISA and NRCS submissions, compressing compliance overhead relative to domestic Brazilian formulators lacking equivalent data libraries. Deepen backward integration into electrochemical synthesis equipment to capture nanoparticle cost advantages before toll-manufacturing distributors consolidate regional blending capacity.
For New Entrants and Emerging Players: Establish a beachhead in Nigerian petrochemical corridors where Port Harcourt and Lagos clusters currently underutilize metal biocide preservation in process water, presenting first-mover positioning through local blending partnerships with established European principals. Target Egyptian and Moroccan textile export manufacturers responding to hardened EU buyer specifications against residual formaldehyde, deploying silver nanoparticle finishing as a regulatory substitution play.
For Investors and Strategic Acquirers: Asset-light toll-manufacturing specialists with established Dubai or São Paulo hub operations and flexible minimum-run contracts represent the most defensible acquisition archetype in a market trending away from captive production investments. Watch for ANVISA registration timeline compression or mutual recognition agreements with European regulators as the inflection signal that would revalue dossier depth versus regional distribution control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochemical Synthesis | Captures nanoparticle cost compression that legacy powder-handling infrastructure cannot match. |
| REACH Dossier Cross-Registration | Leverages existing European toxicological libraries to accelerate South African NRCS and Brazilian ANVISA approvals. |
| Controlled-Release Polymer Partnership | Extends dosing intervals in high-salinity Middle Eastern desalination applications where operator intervention is costly. |
| Toll-Manufacturing Hub Establishment | Enables project-tied flexible supply arrangements preferred in Saudi Arabian construction chemicals procurement. |
| Silver-Copper Bimetallic Formulation Development | Reduces silver bullion exposure while maintaining healthcare-grade efficacy against formaldehyde-based organic alternatives. |
Research Methodology
A standing panel of desalination utility procurement managers, Brazilian pulp mill technical directors, South African mining house environmental compliance officers, and Dubai-based chemical traders provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, ANVISA registration filings, NRCS biocidal product databases, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume estimates from end-use application sizing were triangulated against top-down market value reconstructions.
Scenario-bracketing across conservative, baseline, and expansion cases anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled included metal chemistry tier, application environment, end-user industry, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves calibrated to disclosed capacity expansions and registration timeline milestones. Forecast inputs incorporated desalination capacity buildout pipelines and solar-integrated reverse osmosis plant commissioning schedules.
Stress conditions across silver bullion price bands, ANVISA registration timeline extensions, and toll-manufacturing contract renewal rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory convergence velocity and electrochemical synthesis technology diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Microcrystalline Wax Market