
 Water Dispersible Granules Market | 2026-2036
Water Dispersible Granules Market Size, Share, and Industry Trends Forecast 2026-2036
Water Dispersible Granules Market Analytics
REACH compliance in Europe is decoupling small formulation houses from viable market access. Syngenta AG leverages captive technical manufacturing to sustain cost advantages across herbicide granule portfolios. BASF SE anchors its position through R&D intensity in polymer dispersant chemistry. Bayer AG dominates commercial channels for fungicide-grade granules in high-value horticulture.
Water dispersible granules are solid, non-dusty agrochemical formulations composed of active ingredients bound with dispersants and carriers, designed to disintegrate rapidly upon contact with water for spray application. The formulation typically contains 50-90% active ingredient by weight with particle sizes between 0.25-2.0 mm to ensure flowability and prevent segregation during handling. Herbicide-grade granules occupy the largest volume position due to glyphosate and atrazine demand in broadacre cropping, while specialty crop fungicide formulations command premium positioning through tighter particle size distribution and enhanced tank-mix compatibility.
The EPA regulates pesticide formulation registration under FIFRA, requiring acute toxicity and environmental fate data that elevates development costs for new granule chemistries. The EU's REACH framework and EFSA residue standards constrain active ingredient selection and adjuvant composition for granules entering European agricultural channels. Brazil's ANVISA and China's MEE impose parallel but non-harmonized testing protocols that fragment regulatory pathways. Stakeholders must weigh regional registration timelines against granule formulation investments before committing to plant capacity or active ingredient partnerships.
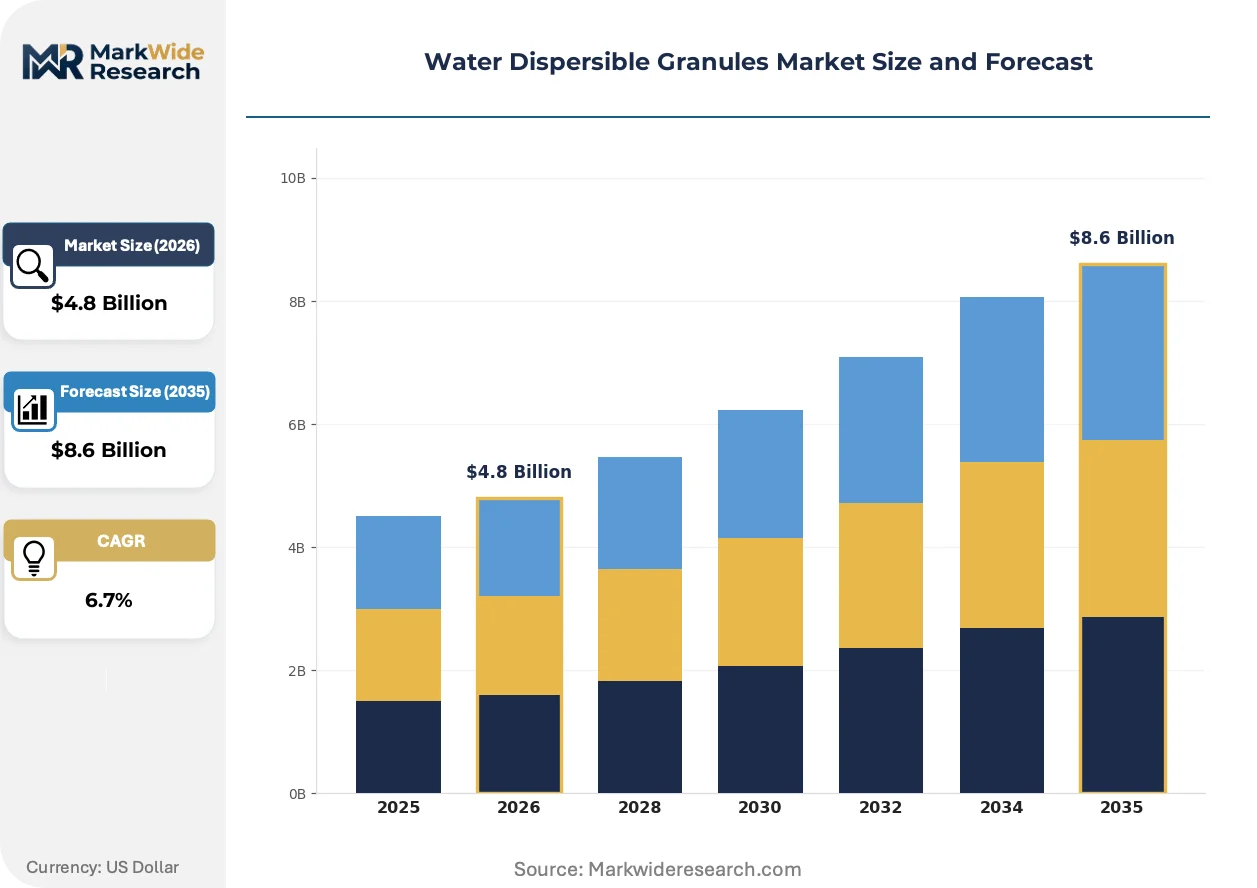
Market Dynamics
EPA's FIFRA registration revisions are compressing formulation approval timelines while elevating toxicity data requirements, forcing agrochemical manufacturers to consolidate R&D pipelines around proven active ingredients rather than novel chemistries.
Growth Catalysts
- Brazil ANVISA fast-track pathways:Accelerated registration for reduced-risk granule formulations is pulling investment toward Mato Grosso soybean operations seeking dust-free alternatives to emulsifiable concentrates.
- Polymer dispersant advances:Enhanced surfactant chemistry enables 90% active ingredient loadings without flowability degradation, opening high-concentration herbicide segments previously reserved for liquid formulations.
- California specialty crop expansion:Vineyard and orchard operators in Central Valley are specifying fungicide-grade granules with sub-millimeter particle distribution for precision airblast applications.
Market Restraints
- Technical-grade active ingredient concentration:Three Chinese manufacturers control bulk glyphosate acid supply, exposing formulation houses to input cost volatility and quota disruptions.
- REACH authorization bottlenecks:ECHA's substance evaluation backlog extends registration timelines for new adjuvant chemistries beyond 36 months, freezing European product launches.
- Liquid suspension concentrate substitution:Improved tank-mix stability in oil-based SC formulations is reclaiming share in broadacre cotton and corn applications where water dispersibility offers marginal advantage.
Strategic Opportunities
- Biostimulant-granule convergence:Combining water dispersible carriers with microbial inoculants addresses organic-certified operations in Florida citrus and California vegetables seeking unified application workflows.
- Drone spray compatibility:Ultra-rapid disintegration specifications below 30 seconds open aerial application channels in Australian broadacre and Ukrainian cereal zones where ground rig access is seasonal.
- EU Green Deal residue targets:EFSA's cumulative exposure assessments favor granule formulations with reduced drift profiles, creating preference pull in Dutch greenhouse and Spanish protected-crop segments.
Industry Challenges
- Formulation chemist scarcity:Expertise in solid-liquid interface engineering and spray-dry optimization concentrates at legacy agrochemical R&D centers, constraining mid-tier manufacturers' pipeline velocity.
- Tank-mix certification complexity:Compatibility testing across 200+ adjuvant and micronutrient combinations requires capital-intensive laboratory infrastructure that smaller formulation houses cannot replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Dispersible Granules Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Other Crop Protection Products Application: Agricultural, Horticultural, Turf Management, Specialty Crops End User: Farmers, Agricultural Retailers, Agrochemical Companies, Consultants Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, Adama Agricultural Solutions Ltd., FMC Corporation, Nufarm Limited, UPL Limited, Sumitomo Chemical Co., Ltd., Croda Agriculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Dispersible Granules Market Evolving Landscape
Granule engineering is pivoting from commodity herbicide carriers toward precision-delivery platforms, with polymer science and application technology convergence redefining performance benchmarks across crop protection segments.
Spray-dried matrix encapsulation is expanding into fungicide applications where controlled-release kinetics extend residual activity against vineyard downy mildew and orchard scab complexes. French and Italian cooperative purchasing groups are specifying these formulations for integrated resistance management programs. The technology is expanding into premium horticulture channels previously dominated by wettable powders, compressing reformulation cycles from five years to eighteen months.
REACH restriction proposals on microplastic-containing formulations are forcing dispersant chemistry transitions toward biodegradable alternatives before 2027 enforcement windows. ECHA's polymer definition criteria now capture conventional synthetic carriers, compelling reformulation investments across herbicide and insecticide portfolios. Granule manufacturers serving Dutch and Belgian export markets are accelerating bio-based dispersant qualification to maintain registration continuity.
Direct-to-farm digital procurement platforms are disintermediating traditional distribution cooperatives in Brazilian soybean and Australian wheat belts. Growers in Mato Grosso and Goias are specifying granule formulations through app-based tenders that bypass regional agrochemical retailers. This channel compression is most visible in high-volume glyphosate procurement where price transparency and bulk logistics integration override technical advisory relationships.
Water Dispersible Granules Market Segmentation
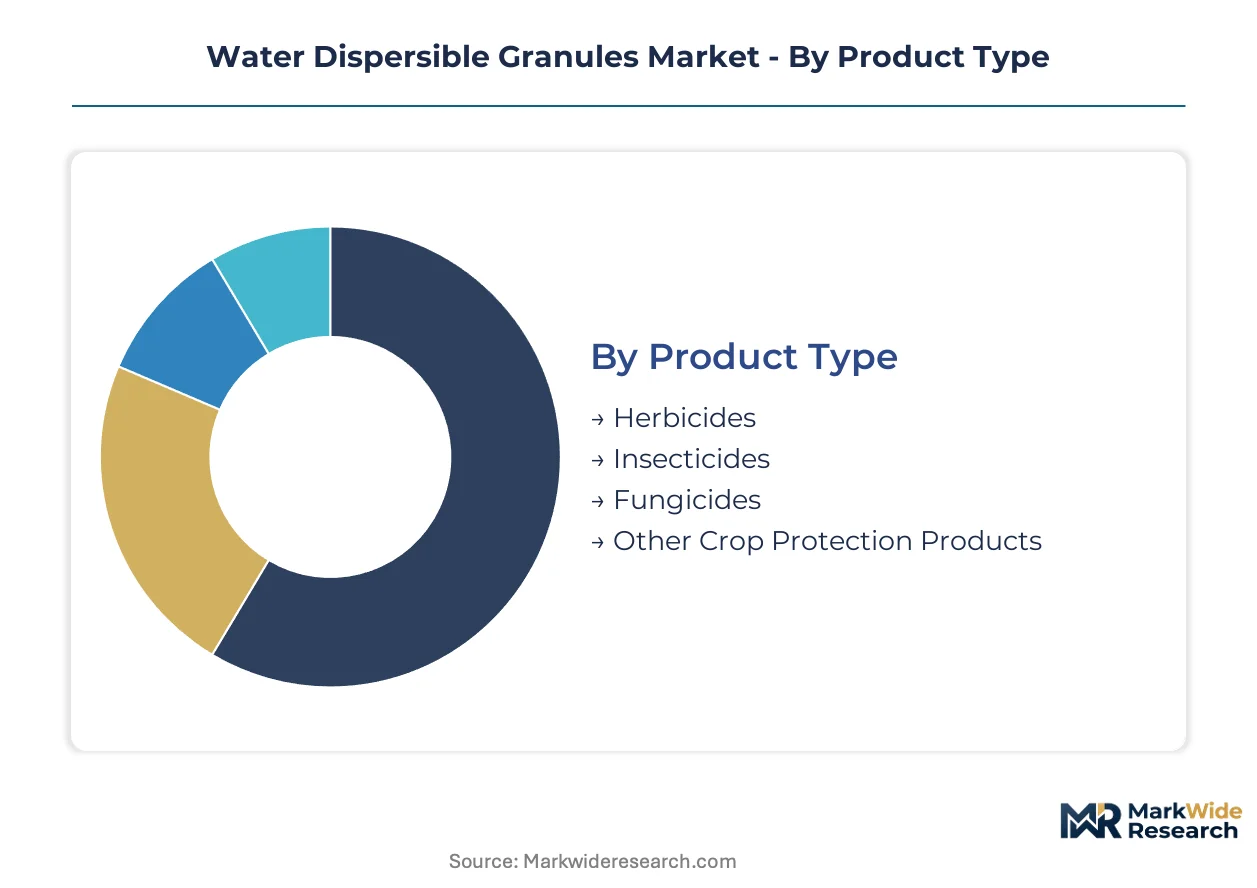
Water dispersible granule buyers diverge sharply in their tolerance for formulation complexity, tank-mix flexibility, and price points. Segmentation reveals how herbicide volume operators, horticultural precision applicators, and digital-native retailers are pulling the category in distinct technical directions.
Product Type:
Buyers in this category separate by cropping system scale and resistance management intensity, with broadacre operators prioritizing cost-effective high-load granules while specialty growers demand rapid disintegration and minimal residue.
- Herbicides:Glyphosate and atrazine-based granules carry 50-90% active ingredient loads with polymer dispersants ensuring flowability at bulk handling scales. Demand clusters in Brazil's Mato Grosso soybean belt where farmers are displacing emulsifiable concentrates to eliminate dust exposure and simplify aerial application logistics.
- Fungicides:Tighter particle size distribution below 0.5 mm enables precision airblast coverage in California vineyards and Florida citrus groves. Premium positioning reflects enhanced tank-mix compatibility with micronutrient programs and resistance management rotation requirements.
- Insecticides:Neonicotinoid and pyrethroid granules target soil-drench and foliar applications with controlled-release matrix options extending residual activity against piercing-sucking pest complexes.
- Other Crop Protection Products:Molluscicide and plant growth regulator granules serve niche horticultural segments where formulation stability in high-humidity storage conditions determines procurement decisions.
Herbicide-grade granules lead volumes today; fungicide formulations are gaining share fastest through premium horticulture channel expansion.
Application:
Application context dictates disintegration speed requirements, with ground-rig operators accepting 60-second specifications while drone and airblast systems demand sub-30-second performance.
- Agricultural:Broadacre corn, soybean, and wheat operations in the US Midwest and Ukrainian cereal zones specify high-volume glyphosate granules with 90% active loads. Cost-per-acre optimization overrides formulation sophistication where tank-mix simplicity and bulk logistics integration drive procurement.
- Horticultural:Orchard and vineyard operators in Italy's Emilia-Romagna and France's Champagne regions prioritize sub-millimeter particle distribution for uniform canopy penetration. Spray-dried encapsulation technologies extend residual activity against downy mildew and scab complexes.
- Turf Management:Golf course and sports field maintenance programs in Florida and California specify low-drift formulations with rapid disintegration for frequent application cycles and aesthetic sensitivity.
- Specialty Crops:Vegetable and nut producers in California's Central Valley require fungicide-grade granules with enhanced compatibility in complex tank-mix sequences involving biostimulants and micronutrients.
Agricultural applications dominate current procurement tonnage; horticultural segments show the steepest expansion trajectory through precision agriculture adoption.
End User:
End-user sophistication varies from price-sensitive bulk purchasers to technically demanding specification writers, with channel power shifting toward digital procurement platforms in major soybean and wheat belts.
- Farmers:Direct procurement through app-based tender platforms is disintermediating traditional cooperatives in Brazil's Goias state and Australia's wheat belt. Price transparency and logistics integration now override technical advisory relationships for high-volume herbicide purchasing.
- Agricultural Retailers:Regional distributors in the US Corn Belt maintain formulation recommendation authority through tank-mix certification services and application equipment expertise that digital channels cannot replicate.
- Agrochemical Companies:Captive technical manufacturing at Syngenta and BASF enables cost advantages across proprietary granule portfolios, with R&D pipelines consolidating around proven active ingredients rather than novel chemistries.
- Consultants:Independent agronomists in California specialty crop sectors specify granule formulations within integrated pest management protocols, creating demand pull for low-drift, reduced-residue options aligned with EFSA cumulative exposure assessments.
Farmers represent the largest volume channel today; agrochemical companies are capturing share fastest through captive formulation integration.
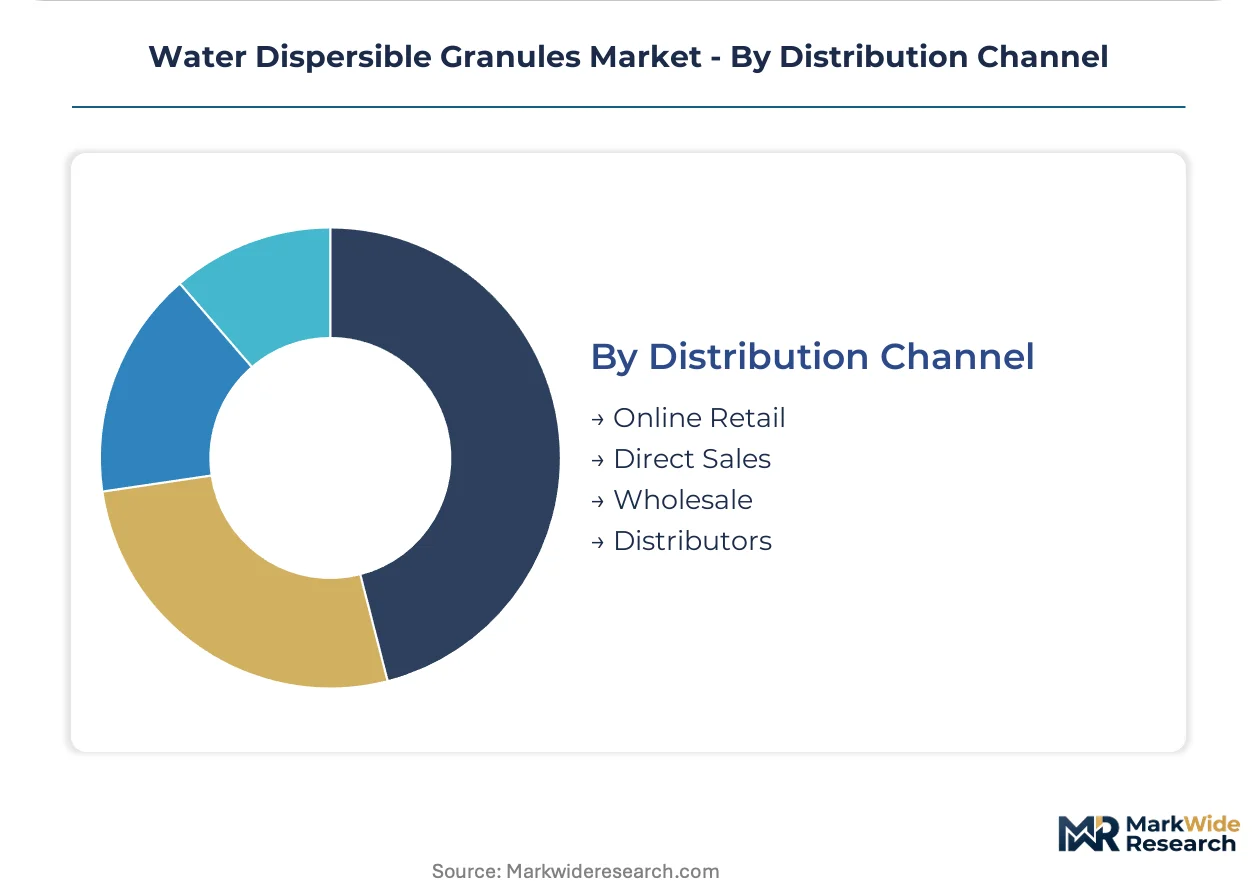
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with large operators bypassing traditional retail while smaller growers retain advisory-dependent relationships.
- Online Retail:Digital platforms aggregate demand from mid-scale Brazilian soybean operations and Australian broadacre farmers, compressing price discovery cycles and enabling bulk logistics optimization previously reserved for cooperative purchasing.
- Direct Sales:Major agrochemical manufacturers maintain dedicated account teams for plantation-scale operators in Mato Grosso and corporate farming enterprises in Ukraine, embedding formulation supply within multi-year crop protection programs.
- Wholesale:Volume aggregators in the US Midwest and EU import hubs manage inventory risk for seasonal demand concentration, requiring granule stability across extended storage periods.
- Distributors:Regional networks in Florida citrus and California vegetable corridors provide tank-mix compatibility testing and application training that sustains technical differentiation against digital competitors.
Direct sales channels lead volume today; online retail is climbing the fastest through platform-based procurement adoption in major soybean and wheat producing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemist expertise concentrates in legacy agrochemical R&D centers across Switzerland, Germany, and the United States, anchoring technical development pipelines for water dispersible granule systems.
United States
California specialty crop growers in the Central Valley are expanding procurement of fungicide-grade granules for vineyard and orchard precision applications. EPA's FIFRA registration revisions under Section 3 are tightening acute toxicity data requirements for new formulations. Florida citrus operations in the Indian River region are specifying dust-free granule alternatives to emulsifiable concentrates for aerial application compatibility.
Brazil
Soybean farmers in Mato Grosso's Cerrado belt are displacing emulsifiable concentrates with water dispersible granule systems to eliminate operator dust exposure. ANVISA's fast-track registration pathways for reduced-risk formulations are accelerating product entry timelines. Bulk procurement platforms in Goias state are disintermediating traditional cooperative distribution channels through app-based tender systems.
Germany
BASF SE maintains captive technical manufacturing capacity for polymer dispersant chemistry serving herbicide-grade granule portfolios. ECHA's REACH authorization backlog for new adjuvant substances extends registration timelines beyond 36 months. The Rhine-Neckar chemical cluster anchors formulation R&D intensity for EU Green Deal-aligned residue reduction targets.
China
Three manufacturers control bulk glyphosate acid supply for granule formulation houses, exposing downstream producers to input cost volatility. MEE environmental compliance inspections are tightening effluent standards for active ingredient production facilities. Shandong Province's chemical industrial parks concentrate technical-grade manufacturing capacity serving export formulation demand.
France
Cooperative purchasing groups in Champagne and Burgundy are specifying spray-dried encapsulation granules for integrated vineyard resistance management. EFSA cumulative exposure assessments under EU Regulation 396/2005 favor low-drift formulations in protected-crop segments. The Lyon chemical corridor hosts dispersant chemistry qualification labs for biodegradable carrier transitions ahead of 2027 microplastic restrictions.
Water Dispersible Granules Market Competitive Landscape
The competitive structure tilts toward integrated agrochemical majors with captive technical manufacturing and polymer science capabilities. Three to four Swiss and German conglomerates control proprietary granule portfolios through backward integration into active ingredient supply, while mid-tier formulation houses face REACH compliance barriers that decouple them from viable European market access. Strategic moves concentrate on portfolio consolidation around proven chemistries rather than novel active ingredient development, alongside capacity expansion in Brazil and North American specialty crop corridors.
Within the integrated major tier, Syngenta AG, BASF SE, and Bayer AG exemplify archetypes of captive supply chain control. Syngenta AG represents the Swiss-domiciled model with technical manufacturing integration across herbicide portfolios. BASF SE anchors German polymer dispersant chemistry leadership. Bayer AG occupies the position of commercial channel dominance for fungicide-grade granules in high-value horticulture applications. These three entities sit within a structure where R&D intensity and registration scale create separation from mid-tier competitors.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| Adama Agricultural Solutions Ltd. |
| FMC Corporation |
| Nufarm Limited |
| UPL Limited |
| Sumitomo Chemical Co., Ltd. |
| Croda Agriculture |
| Others |
Value Network & Pricing Analysis
Brazilian soybean growers' bulk procurement through app-based tender platforms is compressing price discovery cycles and forcing formulation houses to absorb logistics integration costs or cede volume to integrated majors with captive supply chains.
Pricing Analysis
The bundled-versus-unbundled service split separates procurement outcomes across buyer tiers. Three-tier pricing structure across premium, standard, and economy levels reflects active ingredient concentration and tank-mix certification depth. Price differentiation hinges on polymer dispersant quality grades and REACH-compliant adjuvant sourcing. Pricing pressure stems from glyphosate acid cost volatility as Chinese manufacturers adjust export quotas. Mid-scale Brazilian cooperatives exhibit highest price sensitivity; California vineyard operators purchasing fungicide-grade granules show lowest elasticity due to resistance management imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Shandong Province's glyphosate technical manufacturers, where three producers control bulk acid supply for global formulation. Raw material dependencies center on petroleum-derived polymer dispersants, spray-dried carrier substrates, and specialty surfactant chemistries. Supply chain risk manifests as tariff exposure on Chinese technical imports into Brazilian and North American channels. Distribution runs through direct sales teams for plantation-scale operators and regional distributor networks for specialty crop segments in Florida and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: ECHA's 36-month adjuvant authorization timelines in Europe contrast with ANVISA's fast-track pathways in Brazil, creating cost and timing differentials for formulation deployment.
For Market Incumbents: Lock in backward integration into polymer dispersant chemistry to defend margin position against commodity herbicide price erosion. BASF SE's captive manufacturing model in Germany exemplifies this defensive posture. Prioritize capacity expansion in Mato Grosso to capture Brazilian soybean procurement platform volumes before digital channels fully disintermediate traditional cooperatives.
For New Entrants and Emerging Players: Agricultural drone service providers represent the most penetrable channel partner type for ultra-rapid disintegration formulations. Target Australian broadacre and Ukrainian cereal zones where ground rig access is seasonal and aerial application infrastructure is scaling fastest. Pursue biostimulant-granule convergence for organic-certified Florida citrus and California vegetable operations seeking unified application workflows.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier formulation houses possessing REACH-compliant adjuvant portfolios but lacking Brazilian market access. Long-term viability over the coming decade rests on regulatory navigation capabilities rather than active ingredient innovation. Watch ANVISA registration backlog clearance rates as the inflection signal for Brazilian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Dispersants | BASF SE's German manufacturing anchors cost advantages across herbicide portfolios against commodity price swings. |
| Fast-Track Regulatory Registration | ANVISA accelerated pathways pull investment toward Mato Grosso soybean operations seeking dust-free alternatives. |
| Drone Spray Compatibility Development | Sub-30-second disintegration specifications open Australian broadacre channels where ground access is seasonal. |
| Biostimulant-Granule Convergence | Microbial inoculant integration addresses organic-certified Florida citrus demand for unified application workflows. |
| Digital Procurement Platform Partnership | Direct-to-farm app-based tenders in Goias state compress price discovery cycles and override technical advisory relationships. |
Research Methodology
Bottom-up agricultural application modeling reconciled against top-down polymer dispersant supply tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement leads at Brazilian soybean cooperatives, EPA regulatory affairs specialists, and ECHA compliance officers combined with secondary validation from customs trade data, SEC 10-K filings of listed agrochemical majors, ANVISA registration databases, and FIFRA Section 3 submission records. Triangulation between demand-side crop protection expenditure patterns and supply-side active ingredient production capacity ensures cross-verified outputs.
Historical trendline analysis of herbicide-grade and fungicide-grade granule volumes established baseline growth trajectories across the projection horizon. The forecast framework segments by product type, application context, end-user sophistication, and distribution channel structure, with additional granularity on polymer dispersant chemistry tiers. CAGRs derive from regression analysis against planted acreage trends, regulatory approval velocity, and substitution elasticities between granule and liquid suspension concentrate formulations. Drone spray compatibility specifications and EU Green Deal residue targets serve as demand-side inflection inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH microplastic restriction enforcement timelines and Chinese environmental compliance inspections. Projections reflect documented assumptions around regulatory pathway durations and active ingredient supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
North America Industrial Water Treatment Market