
 Organic Catalyst Market | 2026-2036
Organic Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Catalyst Market Outlook
Specialty chemical producers in Germany's Rhineland cluster is realigning capacity toward bio-based organic catalyst precursors. BASF SE leverages its integrated Verbund site in Ludwigshafen to sustain captive supply of homogeneous catalyst intermediates. Evonik Industries AG anchors its position through specialized zeolite-derived platforms for fine chemical synthesis. Johnson Matthey competes via precious-metal recovery loops that reduce net catalyst costs for pharmaceutical clients.
Organic catalysts are molecular substances—typically organometallic complexes, enzymes, or acid-base compounds—that accelerate chemical reactions without being consumed, operating at pressures below 50 bar and temperatures between 20°C and 200°C for selective bond formation in multi-step synthesis. Their primary commercial purpose centers on yield optimization and stereoselectivity in pharmaceutical active ingredient production, where single-enantiomer purity requirements exceed 99.5%. Heterogeneous catalysts dominate volume flows in oil refining and bulk chemical operations due to simpler separation and regeneration economics. Enzymatic catalysts represent the fastest-expanding product class as food and beverage processors adopt biocatalytic routes for natural flavor esterification and lipid modification.
EPA regulations in the United States mandate catalyst waste characterization under RCRA hazardous substance protocols, pushing chemical manufacturers toward recyclable homogeneous systems. REACH registration requirements in Europe enforce full toxicity dossiers for organometallic catalyst imports above one-tonne annual thresholds, elevating compliance costs for non-EU suppliers. FDA guidance on residual metal specifications in drug substances tightens allowable palladium and nickel traces to parts-per-billion levels, directly shaping catalyst selection in pharmaceutical manufacturing. Stakeholders must monitor evolving green chemistry procurement mandates from large chemical buyers, as these specifications increasingly override pure technical performance in supplier qualification decisions.
Market Dynamics
REACH compliance in Europe is tightening purity requirements for catalyst residues, forcing pharmaceutical manufacturers to upgrade filtration and recovery systems ahead of the 2026 registration deadlines.
Growth Catalysts
- Biocatalytic route expansion:Food and beverage processors adopt enzymatic catalysts for natural flavor esterification, displacing chemical synthesis in lipid modification applications.
- FDA residual metal guidance:Parts-per-billion palladium and nickel limits in drug substances push pharmaceutical manufacturers toward homogeneous recyclable systems with superior trace metal control.
- Germany's Rhineland chemical corridor:BASF SE's Ludwigshafen Verbund site sustains captive supply of catalyst intermediates, anchoring regional production gravity for fine chemical synthesis.
Market Restraints
- Precious metal input volatility:Palladium and rhodium price swings compress margin predictability for homogeneous catalyst producers serving pharmaceutical clients.
- REACH registration friction:One-tonne annual import thresholds enforce full toxicity dossiers for non-EU organometallic suppliers, elevating compliance costs and entry barriers.
- Heterogeneous catalyst substitution:Simpler separation and regeneration economics in oil refining and bulk chemicals limit organic catalyst penetration in high-volume process streams.
Strategic Opportunities
- Green chemistry procurement mandates:Large chemical buyers in Europe now override pure technical performance with sustainability specifications in supplier qualification decisions.
- Zeolite-derived platform expansion:Evonik Industries AG's specialized architectures for fine chemical synthesis enable penetration into pharmaceutical active ingredient production previously served by organometallics.
- India's pharmaceutical manufacturing scale-up:CDSCO alignment with ICH Q3D guidelines on elemental impurities creates demand for low-metal catalyst systems in generic API production.
Industry Challenges
- Organometallic synthesis expertise scarcity:Talent pipelines for ligand design and asymmetric catalysis fail to match pharmaceutical industry expansion rates in Germany and Switzerland.
- Multi-step synthesis integration complexity:Legacy batch equipment requires retrofitting to accommodate continuous-flow biocatalytic systems, extending validation timelines for GMP facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Catalyst Market |
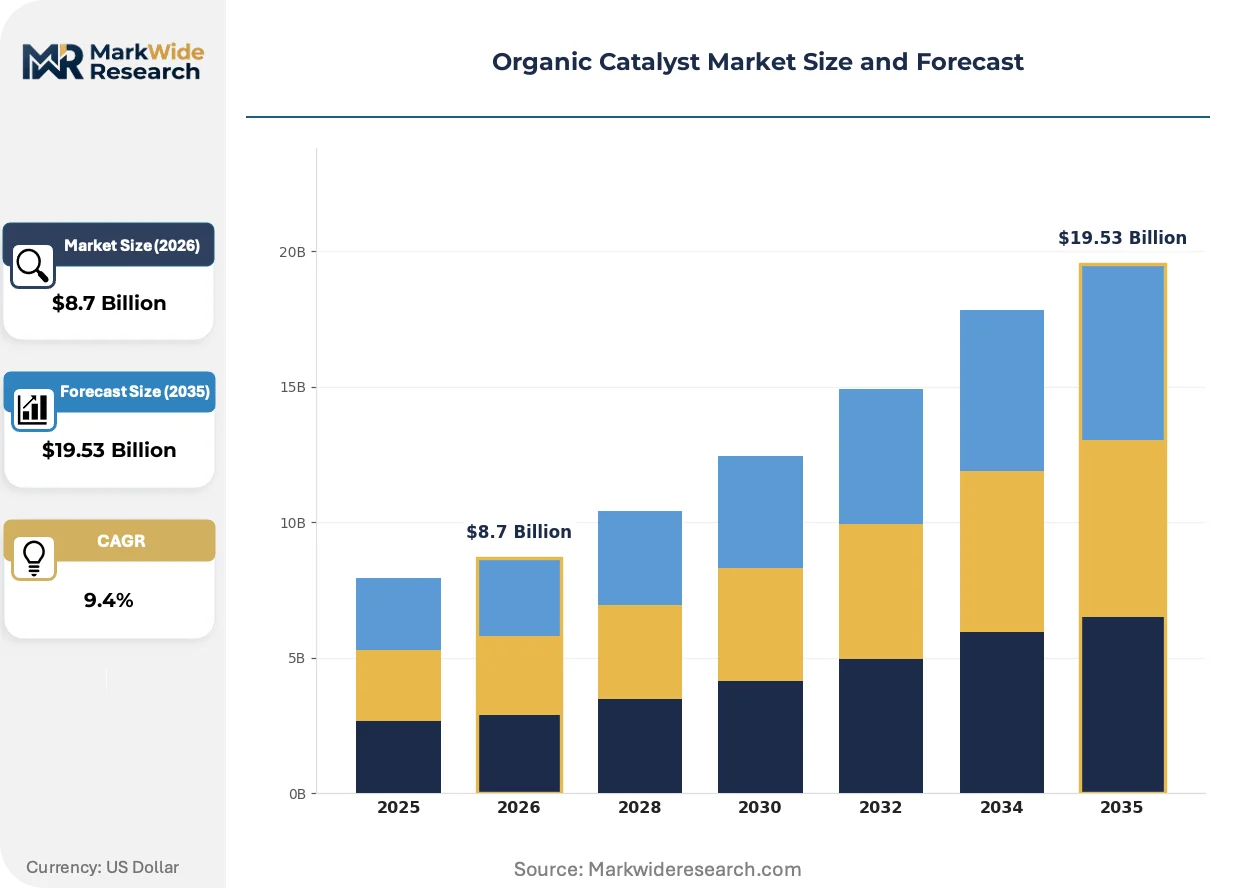
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous Catalysts, Homogeneous Catalysts, Enzymatic Catalysts, Metal Catalysts Application: Synthesis Processes, Oil Refining, Pharmaceuticals, Agrochemicals End User: Chemical Manufacturers, Oil & Gas Industries, Research Institutions, Food & Beverage Form: Liquid, Powder, Pellet, Granule |
| Companies Covered | Evonik Industries AG, W.R. Grace & Co., BASF SE, Haldor Topsoe A/S, Albemarle Corporation, Johnson Matthey, Honeywell UOP, Novozymes A/S, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Catalyst Market Strategic Shifts
Digital process control and closed-loop metal recovery are compressing catalyst lifecycle costs while regulatory thresholds on residual contamination tighten specification windows across pharmaceutical supply chains.
Continuous-flow reactor systems with integrated real-time analytics are automating stereoselective bond formation in multi-step pharmaceutical synthesis. Contract manufacturers in Germany and Switzerland adopt these platforms to reduce solvent waste and compression cycle times. The technology is automating quality assurance steps previously requiring offline chromatographic verification, enabling faster batch release for high-value APIs.
EPA RCRA hazardous substance protocols now mandate catalyst waste characterization for all spent organometallic streams above threshold quantities. Chemical manufacturers in the United States respond by investing in homogeneous systems with closed-loop precious metal recovery, reducing net material costs and landfill liability. Pharmaceutical facilities face the strictest documentation burdens, driving preference for catalysts with established recycling partnerships.
Buyer consolidation among multinational pharmaceutical firms concentrates procurement decisions with centralized technical teams rather than individual plant managers. Specialty catalyst suppliers now negotiate multi-year framework agreements covering ligand families across multiple manufacturing sites, displacing spot purchasing for standard homogeneous platforms. This pattern is most visible in Germany's Ludwigshafen-Leverkusen corridor and Switzerland's Basel pharmaceutical cluster.
Organic Catalyst Market Segmentation
Organic catalyst buyers select product formats and application-specific platforms based on separation economics, thermal stability requirements, and regulatory compliance burdens. Segmentation reveals where capital deployment concentrates and which technology trajectories command R&D investment priority.
Product Type:
Capital intensity varies sharply across catalyst platforms, with precious-metal homogeneous systems requiring the highest upfront ligand synthesis investment and enzymatic platforms demanding dedicated bioreactor infrastructure.
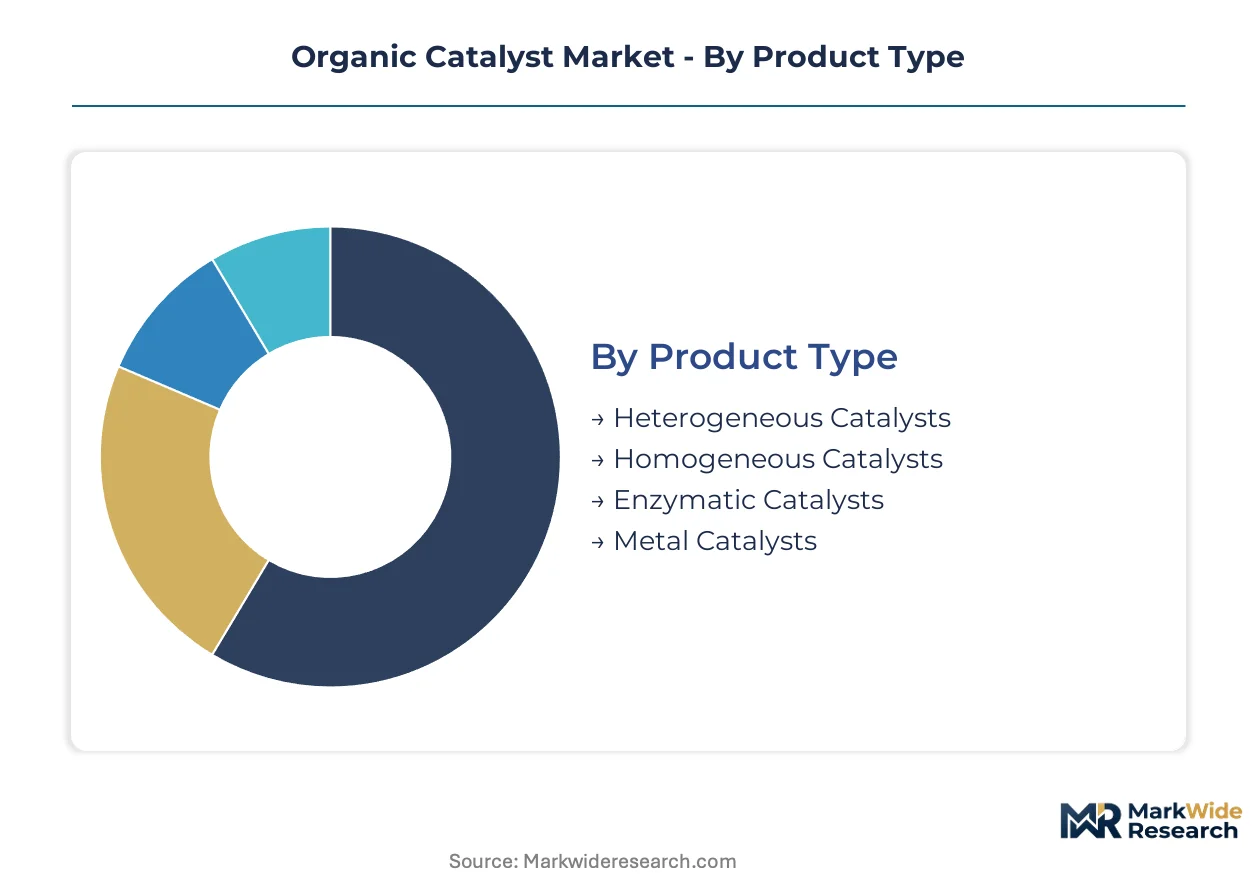
- Heterogeneous Catalysts:Solid-phase materials with discrete active sites on porous supports enable simple filtration recovery and thermal regeneration. Oil refiners in Germany's Rhineland cluster deploy these for hydrocracking and hydrotreating operations where catalyst longevity outweighs selectivity premiums.
- Homogeneous Catalysts:Soluble organometallic complexes operate in single-phase reaction media, delivering precise stereocontrol for pharmaceutical active ingredient synthesis. FDA guidance on residual palladium and nickel traces below parts-per-billion levels drives pharmaceutical manufacturers toward recyclable homogeneous systems with closed-loop metal recovery partnerships.
- Enzymatic Catalysts:Isolated enzymes or whole-cell biocatalysts function under aqueous conditions with mild temperature and pressure requirements. Food and beverage processors adopt these for natural flavor esterification and lipid modification, displacing chemical synthesis routes.
- Metal Catalysts:Unsupported or supported transition metal species including palladium, rhodium, and nickel complexes serve cross-coupling and hydrogenation chemistry. Precious metal price volatility compresses margin predictability for producers serving pharmaceutical contract manufacturers.
Heterogeneous catalysts absorb the bulk of installed capacity; enzymatic catalysts are expanding most quickly.
Application:
Margin structures diverge by application, with pharmaceutical synthesis commanding premium pricing for enantioselective performance and oil refining operating on volume-driven, cost-minimized procurement.
- Synthesis Processes:Fine chemical and specialty chemical manufacturing employs organic catalysts for carbon-carbon bond formation, oxidation, and reduction sequences. Germany's chemical corridor around Ludwigshafen and Leverkusen concentrates demand for multi-step synthesis catalysts serving agrochemical and pharmaceutical intermediates.
- Oil Refining:Fluid catalytic cracking, hydroprocessing, and reforming operations consume catalysts in continuous regeneration cycles. Heterogeneous platforms dominate due to mechanical durability and simplified separation from hydrocarbon product streams.
- Pharmaceuticals:Active ingredient manufacturing requires single-enantiomer purity exceeding 99.5%, driving specification for asymmetric hydrogenation and cross-coupling catalysts. REACH registration deadlines enforce toxicity dossier completeness for all organometallic imports above one-tonne annual thresholds.
- Agrochemicals:Herbicide, fungicide, and insecticide synthesis employs catalysts for heterocycle construction and stereoselective halogenation. Cost pressure from generic competition limits catalyst spend relative to pharmaceutical applications.
Synthesis processes absorb the bulk of installed capacity; pharmaceuticals is climbing the fastest.
End User:
Customer scale and technical sophistication determine procurement patterns, with multinational chemical manufacturers negotiating multi-year framework agreements while research institutions purchase through specialized distributors.
- Chemical Manufacturers:Integrated producers and contract manufacturers consume catalysts across commodity and specialty chemical portfolios. BASF SE's Verbund site in Ludwigshafen sustains captive supply of homogeneous catalyst intermediates for internal fine chemical synthesis.
- Oil & Gas Industries:Refinery operators prioritize catalyst stability under sulfur and nitrogen contamination, with regeneration economics driving total cost of ownership calculations. Heterogeneous platforms with decades of operational track record dominate procurement decisions.
- Research Institutions:Academic and government laboratories source novel catalyst architectures for methodology development and proof-of-concept studies. Small-volume, high-variety purchasing patterns require responsive technical support from specialized suppliers.
- Food & Beverage:Processors adopt enzymatic catalysts for interesterification, esterification, and transglycosylation reactions in edible oil and flavor manufacturing. EFSA safety evaluations and clean-label positioning accelerate biocatalytic route substitution.
Chemical manufacturers absorb the bulk of installed capacity; food and beverage is gaining share fastest.
Form:
Physical form selection balances handling convenience, dispersion characteristics, and reactor compatibility, with liquid formulations simplifying dosing automation and solid forms enabling extended shelf stability.
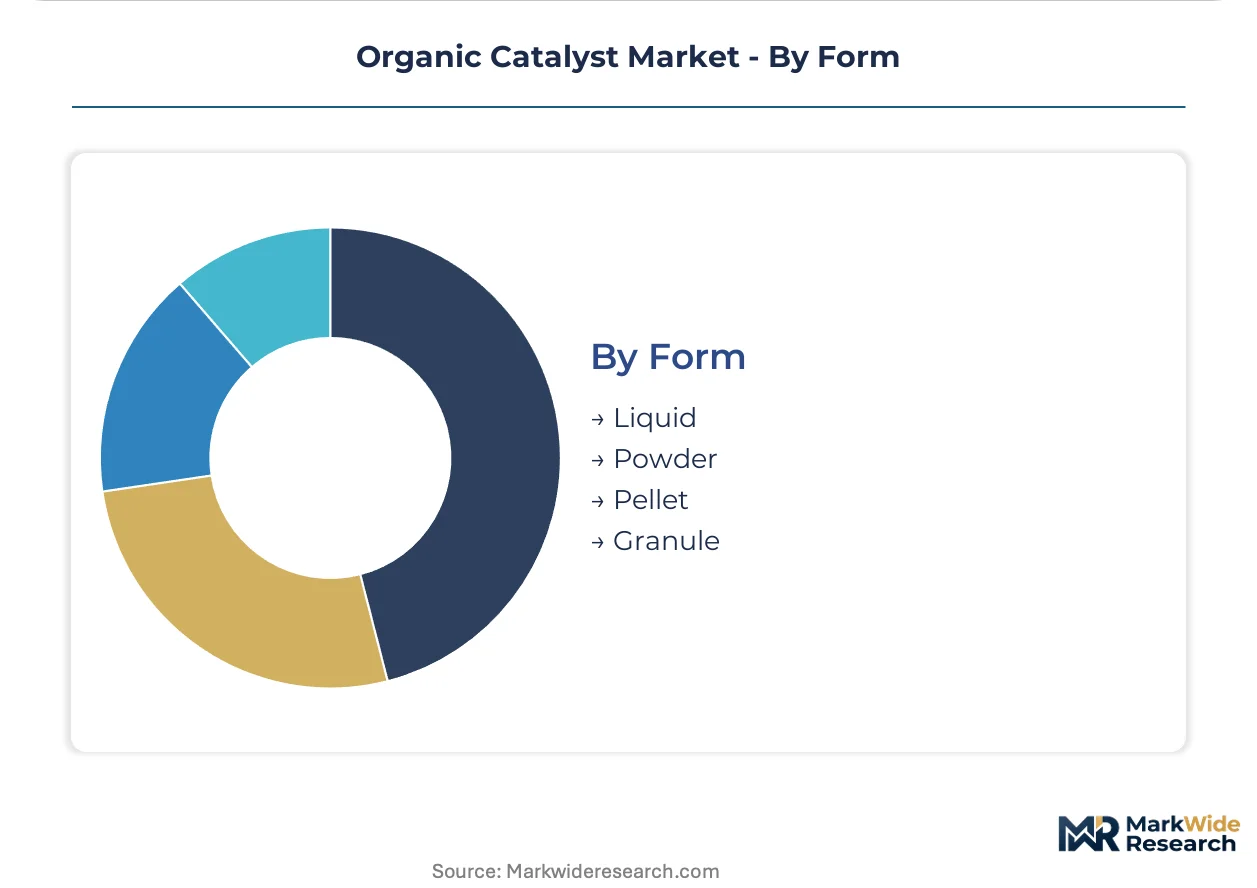
- Liquid:Homogeneous catalysts in solution or suspension facilitate precise metering and rapid dispersion in batch and continuous-flow reactors. Pharmaceutical manufacturers prefer liquid formulations for GMP-validated processes requiring documented concentration consistency.
- Powder:Fine particulate catalysts offer high surface area for gas-phase and slurry-phase reactions. Handling precautions address dust explosion hazards and respiratory exposure in chemical manufacturing facilities.
- Pellet:Extruded cylindrical forms optimize pressure drop and mass transfer in fixed-bed reactor configurations. Oil refining and bulk chemical operations specify pellet dimensions for compatibility with existing reactor internals.
- Granule:Irregular or spherical particulate catalysts balance mechanical strength with porosity for fluidized-bed and moving-bed applications. Attrition resistance determines suitability for continuous regeneration processes.
Pellet absorbs the bulk of installed capacity; liquid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhodium and palladium deposits in South Africa's Bushveld Igneous Complex supply critical precursors for homogeneous catalyst synthesis. Germany's Ludwigshafen chemical corridor processes these materials into pharmaceutical-grade organometallic intermediates. India's pharmaceutical manufacturing clusters increasingly source low-metal catalyst systems for generic API production.
United States
Pharmaceutical contract manufacturers in New Jersey and Massachusetts drive demand for recyclable homogeneous systems with closed-loop metal recovery. EPA RCRA protocols mandate hazardous waste characterization for spent organometallic streams above threshold quantities. The Gulf Coast refining corridor around Houston deploys heterogeneous catalysts for hydroprocessing operations where regeneration economics dominate total cost calculations.
Germany
BASF SE's Verbund site in Ludwigshafen sustains captive production of catalyst intermediates serving fine chemical synthesis across the Rhineland cluster. REACH registration deadlines enforce toxicity dossier completeness for all organometallic imports above one-tonne annual thresholds. Evonik Industries AG anchors specialized zeolite-derived platform development in Marl and Hanau for pharmaceutical active ingredient applications.
India
Generic API manufacturers in Hyderabad and Ahmedabad scale biocatalytic route adoption to meet export quality specifications. CDSCO alignment with ICH Q3D guidelines on elemental impurities creates compliance pressure for low-metal catalyst selection. The Gujarat chemical corridor around Vadodara concentrates new capacity investment in enzymatic lipid modification for food ingredient exports.
China
State-owned refiners in Shandong and Liaoning provinces deploy heterogeneous catalysts for fluid catalytic cracking under dual carbon emission reduction mandates. NMPA tightening of residual metal specifications in drug substances shapes import demand for high-purity homogeneous systems. The Yangtze River Delta around Shanghai hosts expanding fine chemical synthesis capacity serving agrochemical intermediate export markets.
Switzerland
Specialty pharmaceutical manufacturers in the Basel cluster negotiate multi-year framework agreements covering ligand families across multiple manufacturing sites. Swissmedic guidance on catalyst residue specifications in drug substances exceeds FDA stringency for palladium and nickel traces. Lonza and contract manufacturing organizations in Visp drive demand for continuous-flow reactor systems with integrated real-time analytics.
Organic Catalyst Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biocatalytic specialization and regional service models. The market structures around three tiers: integrated chemical conglomerates with captive catalyst production, specialized organometallic suppliers serving pharmaceutical clients, and enzymatic platform developers targeting food and beverage applications. Strategic moves concentrate on precious metal recovery partnership formation and continuous-flow technology licensing to contract manufacturers.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated production archetype through Rhineland manufacturing concentration. Johnson Matthey represents the specialized precious metal services tier with recovery loop infrastructure serving pharmaceutical quality requirements. Novozymes A/S occupies the enzymatic platform developer position with dedicated bioreactor technology for natural flavor synthesis applications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| W.R. Grace & Co. |
| BASF SE |
| Haldor Topsoe A/S |
| Albemarle Corporation |
| Johnson Matthey |
| Honeywell UOP |
| Novozymes A/S |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
Palladium and rhodium feedstock costs cascade through homogeneous catalyst pricing tiers, with precious metal recovery service bundling separating premium pharmaceutical-grade suppliers from standard commodity providers serving bulk chemical processors.
Pricing Analysis
Metal recovery service bundling distinguishes premium homogeneous catalyst suppliers from unbundled commodity sellers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and closed-loop partnership availability. Pricing pressure stems from precious metal volatility compressing margin predictability for producers serving pharmaceutical contract manufacturers. Research institutions and small-volume buyers exhibit highest price sensitivity; multinational pharmaceutical firms with framework agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with South Africa's Bushveld Igneous Complex for rhodium and palladium precursors. Germany and China concentrate downstream catalyst intermediate processing. Homogeneous catalyst production draws from organometallic ligand synthesis and zeolite substrate manufacturing. Tariff exposure on precious metal imports poses structural risk. Distribution runs through direct technical sales to pharmaceutical manufacturers and chemical distribution networks for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH registration compliance costs, forcing smaller non-EU organometallic suppliers below one-tonne thresholds to exit or seek acquisition.
For Market Incumbents: Anticipate biocatalytic substitution threats by deepening precious metal recovery infrastructure and securing multi-year pharmaceutical framework agreements. Invest in continuous-flow reactor technology licensing to contract manufacturers in Germany's Ludwigshafen-Leverkusen corridor. Anchor position through captive ligand synthesis capacity. For New Entrants and Emerging Players: Generic API manufacturers in India's Hyderabad-Ahmedabad cluster represent underserved buyers seeking low-metal catalyst systems aligned with CDSCO-ICH Q3D compliance. Target enzymatic platform specialization for food and beverage lipid modification. Pursue regional service models with dedicated bioreactor technical support. For Investors and Strategic Acquirers: REACH registration deadline extensions or enforcement intensification signal consolidation acceleration among sub-scale organometallic suppliers. Long-term viability favors vertically integrated producers with captive precursor supply and established pharmaceutical recycling partnerships. Monitor EFSA clean-label mandate expansion as biocatalytic adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Recovery | Johnson Matthey's closed-loop infrastructure reduces net palladium costs for pharmaceutical clients. |
| Continuous-Flow Reactor Technology Licensing | Lonza's integrated real-time analytics platforms automate stereoselective bond formation for API manufacturers. |
| Zeolite-Derived Platform Expansion | Evonik's specialized architectures penetrate pharmaceutical active ingredient production previously served by organometallics. |
| Biocatalytic Route Scale-Up | Novozymes A/S bioreactor systems displace chemical synthesis in food and beverage flavor esterification. |
| Regional Service Model Development | Specialized distributors with responsive technical support capture research institution purchasing patterns. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pharmaceutical procurement directors, fine chemical plant managers, catalyst R&D leads, and distribution channel partners combined with ECHA REACH dossiers, FDA guidance documents, and SEC 10-K disclosures. Bottom-up volume modeling and top-down value triangulation validated segment outputs.
Granularity-level modeling deployed catalyst type, application end-use, and pharmaceutical regulatory cluster as core segmentation dimensions. CAGRs derived from historical trajectory analysis and forward-looking capacity announcements across the projection horizon. Precious metal price scenarios and biocatalytic substitution rates served as industry-specific forecast inputs.
Revisions become necessary when REACH enforcement intensity shifts, precious metal supply disruptions materialize, or pharmaceutical buyer consolidation accelerates beyond modeled thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
South America Refining Catalysts Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
North America Zeolite Market