
 Optical Whitening Agents Market | 2026-2036
Optical Whitening Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Whitening Agents Market Analytics
China is rewriting supply dynamics for optical whitening agents through expanded domestic production of fluorescent brightener intermediates. BASF SE leverages backward integration into benzene derivative supply chains to secure feedstock stability. Huntsman International LLC anchors its position through R&D intensity in liquid concentrate formulations for detergent makers. Archroma specializes in textile-specific brighteners that meet ZDHC compliance protocols for apparel brands.
Optical whitening agents are organic compounds, typically stilbene or coumarin derivatives, that absorb ultraviolet light and re-emit visible blue wavelengths to mask yellowing in substrates. Manufacturers synthesize these agents through sulfonation and diazotization routes, yielding products with extinction coefficients above 40,000 L mol⁻¹ cm⁻¹ for maximum whitening efficiency at parts-per-million loadings. Sodium fluorescent brighteners dominate volume in laundry detergent applications where cost-per-wash economics govern procurement decisions. Styrene-acrylate copolymers capture margin pools in plastics compounding for food-contact packaging where migration limits tighten. Powder forms retain share in textile processing despite liquid concentrates gaining ground in continuous dyeing operations.
EPA regulations in the United States restrict certain benzoxazole derivatives in aquatic environments, redirecting formulation toward biodegradable alternatives. REACH registration requirements in Europe enforce full toxicological dossiers for stilbene-based brighteners, raising barriers for non-EU suppliers. The EU Green Deal pushes paper mills toward chlorine-free bleaching sequences that increase optical brightener dependency. Stakeholders must monitor regulatory divergence between jurisdictions while building regional formulation capabilities that preempt compliance gaps.
Market Dynamics
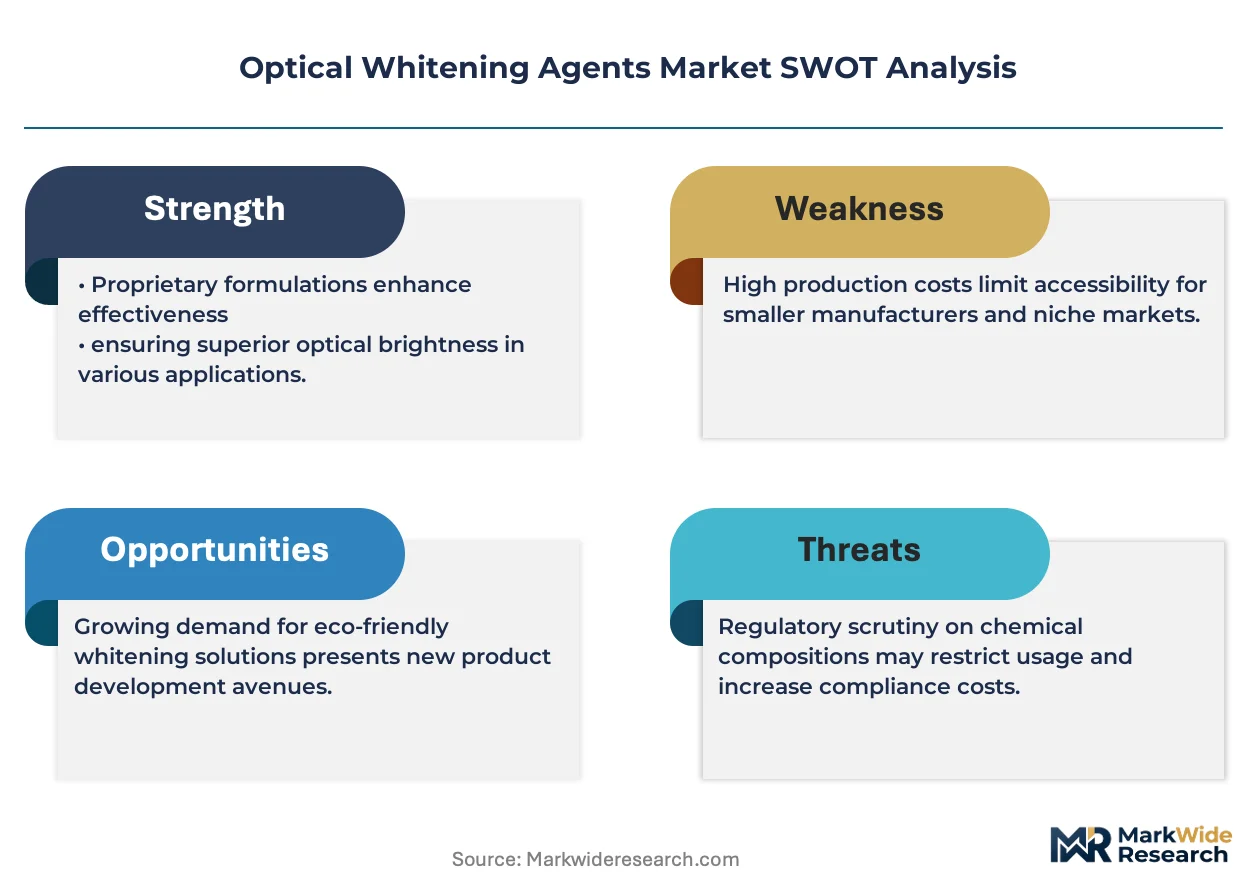
REACH registration dossiers for stilbene-based brighteners are forcing non-EU suppliers to abandon the European market or invest in toxicological testing infrastructure, consolidating supply among compliant incumbents.
Growth Catalysts
- EU Green Deal paper bleaching mandates:Chlorine-free sequences in European paper mills drive higher optical brightener loadings to achieve brightness targets without elemental chlorine.
- India textile export expansion:Apparel shipments to EU and US markets require ZDHC-compliant brighteners, pulling domestic chemical production toward certified grades.
- Fluorescent brightener intermediate localization:Chinese domestic production of benzene derivatives reduces import dependency for regional formulators.
Market Restraints
- Benzene derivative cost volatility:Crude-linked feedstock pricing squeezes margin stability for stilbene-based brightener manufacturers.
- EPA aquatic toxicity restrictions:Benzoxazole derivative bans in US waterways limit formulation options for detergent applications.
- Biodegradable substitute performance gap:Current alternatives fail to match extinction coefficients of conventional coumarin derivatives in plastics compounding.
Strategic Opportunities
- Underpenetrated Brazilian detergent market:Liquid concentrate brightener adoption lags in Latin America's largest economy, creating white space for technical service-intensive entry.
- Food-contact packaging migration compliance:Tightening styrene-acrylate copolymer limits in EU and US push demand for polymer-bound brightener systems.
- Continuous dyeing liquid concentrate transition:Textile mills in Vietnam and Bangladesh are converting from powder to liquid handling systems.
Industry Challenges
- Sulfonation process engineering talent scarcity:Specialized reactor operation and diazotization control expertise concentrates among aging workforces in Germany and Japan.
- REACH dossier compilation timelines:Full toxicological registration packages demand 18-24 month preparation cycles, freezing product portfolio decisions.
- Legacy powder-to-liquid handling infrastructure:Textile processors face capital requirements for tank farm and dosing system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Whitening Agents Market |
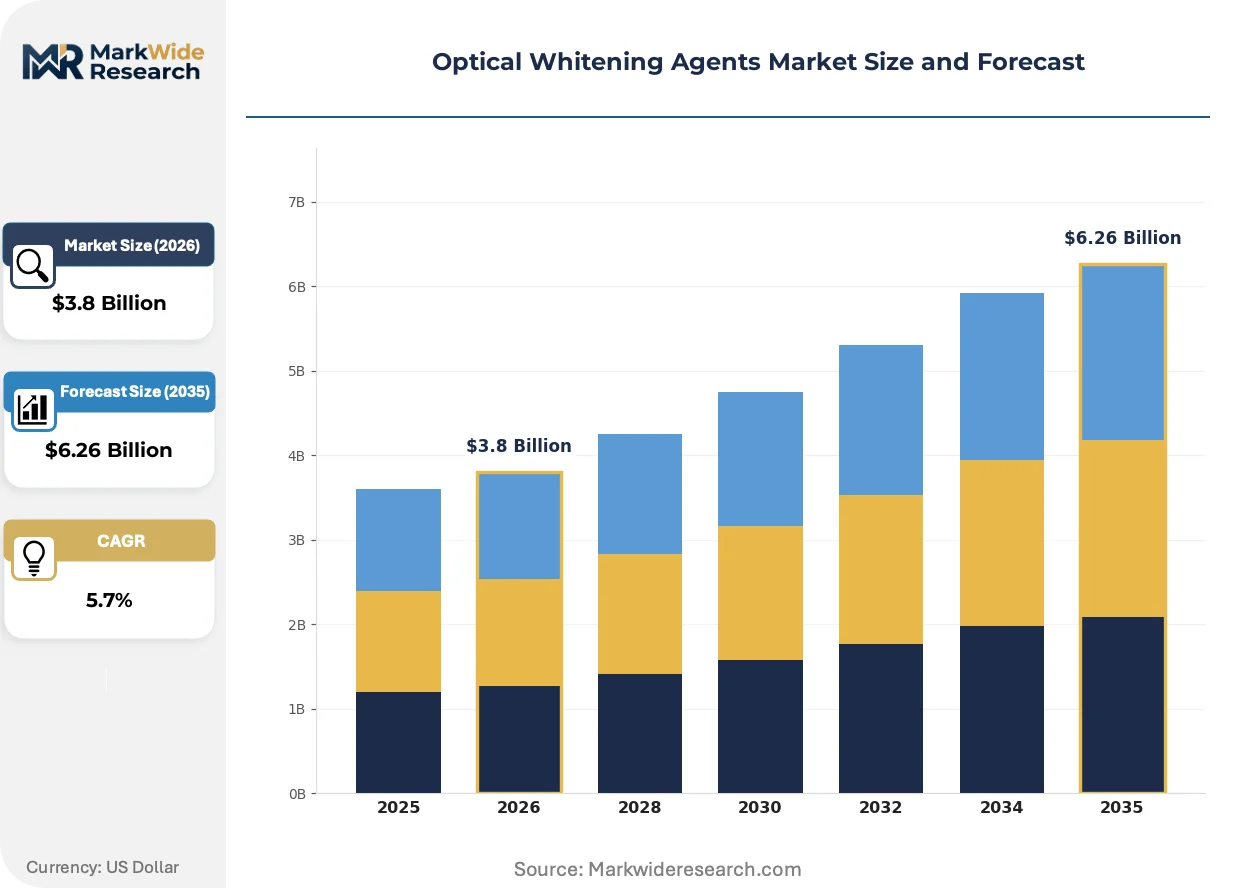
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Fluorescent Brighteners, Styrene-Acrylate Copolymers, Polyamide Resins, Peracetic Acid Application: Textiles, Plastics, Paper, Detergents End User: Consumer Goods, Industrial Manufacturing, Cosmetic Products, Specialty Chemicals Form: Liquid, Powder, Granule, Paste |
| Companies Covered | BASF SE, Huntsman International LLC, Archroma, Clariant AG, 3V Sigma S.p.A., Eastman Chemical Company, Teh Fong Min International, Kolorjet Chemicals Pvt Ltd, Aron Universal Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Whitening Agents Market Evolving Landscape
Formulation science and regulatory chemistry are converging to redefine competitive advantage, with digitization of quality assurance and biodegradable molecular design emerging as decisive capability differentiators.
Inline spectrophotometric monitoring is digitizing quality control workflows in brightener synthesis plants. Detergent manufacturers in Germany and Japan are deploying real-time extinction coefficient verification to replace batch sampling protocols. This compression of release-cycle time is digitizing supplier-customer data interfaces, enabling just-in-time inventory positioning.
REACH authorization requirements for stilbene derivatives are tightening substance volume thresholds across the European Economic Area. Formulators face mandatory substitution planning for non-authorized grades by 2026-2027. Paper mills in Finland and Austria are accelerating trials of triazine-based alternatives to preempt supply disruption.
Technical service bundling is displacing commodity spot purchasing in textile processing channels. Mills in India and Turkey now specify brightener suppliers based on shade-matching software compatibility and on-site colorimetry support. This preference shift concentrates procurement decisions among integrated service providers with regional application laboratories.
Optical Whitening Agents Market Segmentation
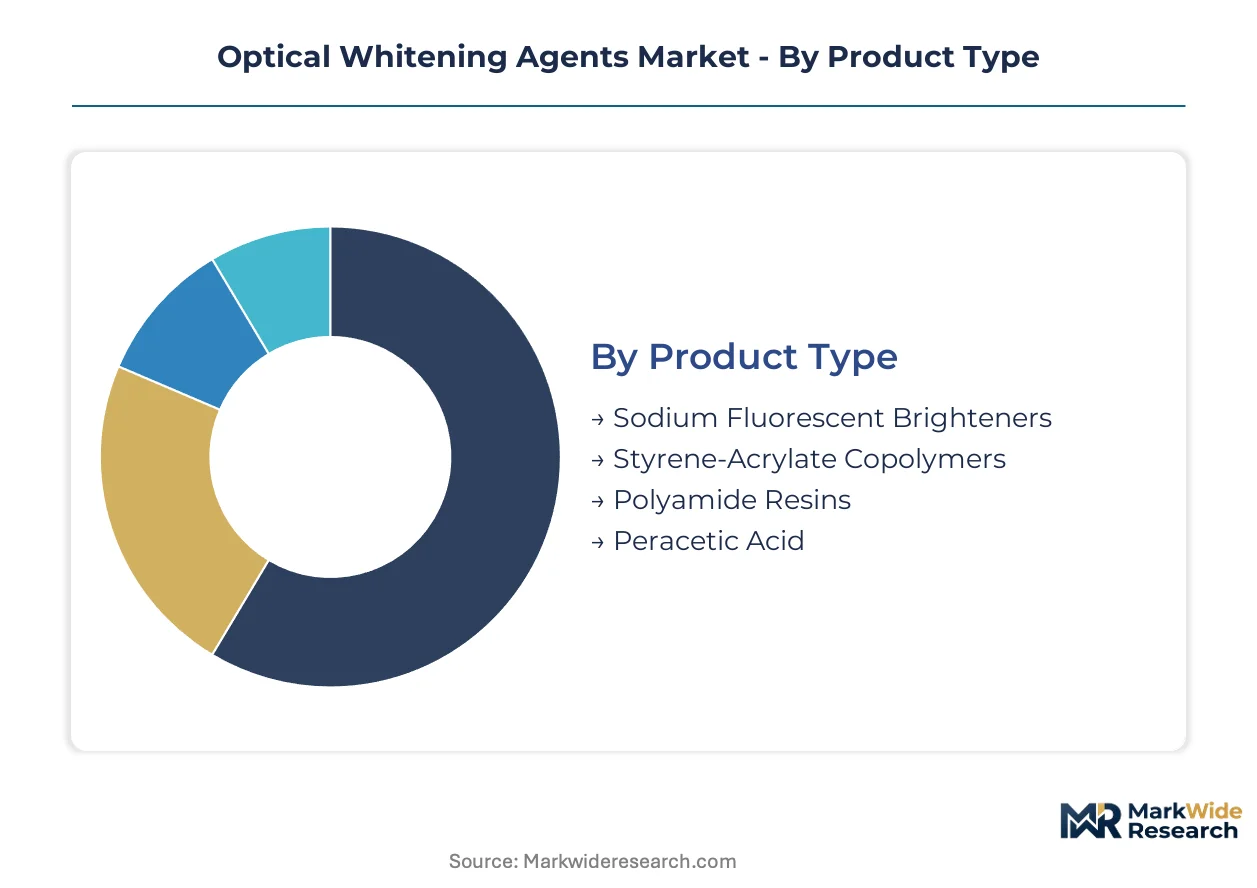
Optical whitening agents serve divergent performance requirements across substrates that demand precise molecular matching. Formulators select brightener architectures based on substrate compatibility, regulatory migration limits, and processing economics.
Product Type:
Use-case spectrum spans cost-sensitive detergent formulations to high-value polymer-bound systems for regulated food-contact applications.
- Sodium Fluorescent Brighteners:Sulfonated stilbene derivatives deliver extinction coefficients exceeding 40,000 L mol⁻¹ cm⁻¹ for maximum whitening efficiency at parts-per-million loadings. Demand concentrates in Indian detergent manufacturing where cost-per-wash economics govern procurement decisions, though EPA aquatic toxicity restrictions on benzoxazole derivatives constrain formulation flexibility.
- Styrene-Arylate Copolymers:Polymer-bound architectures immobilize brightener molecules within plastic matrices to meet EU and US migration limits for food-contact packaging. Paper mills in Finland and Austria favor these systems for chlorine-free bleaching sequences mandated by the EU Green Deal.
- Polyamide Resins:Thermoplastic carriers enable high-temperature processing in engineering plastics compounding.
- Peracetic Acid:Oxidative brightening adjuncts complement fluorescent agents in textile bleaching sequences.
Established volume favors sodium fluorescent brighteners; emerging adoption favors styrene-acrylate copolymers.
Application:
Cost tier separation distinguishes commodity laundry applications from specification-driven textile and packaging segments.
- Textiles:Mills in Vietnam and Bangladesh convert from powder to liquid handling systems for continuous dyeing operations. ZDHC compliance requirements for EU and US apparel exports pull Indian domestic production toward certified grades.
- Detergents:Liquid concentrate formulations displace powder in German and Japanese manufacturing where real-time extinction coefficient verification compresses release cycles.
- Plastics:Styrene-acrylate copolymer migration limits tighten in EU and US jurisdictions.
- Paper:Chlorine-free bleaching mandates elevate optical brightener dependency.
Margin concentration favors plastics; steepest expansion trajectory favors textiles.
End User:
Customer type stratification separates specification buyers with technical service requirements from price-takers in commodity channels.
- Consumer Goods:Detergent and fabric care brands in India drive volume procurement of sodium fluorescent brighteners.
- Industrial Manufacturing:Paper and plastics compounders demand polymer-bound systems with migration compliance documentation.
- Cosmetic Products:Skin-contact applications require dermatological safety testing beyond standard toxicological dossiers.
- Specialty Chemicals:Technical service bundling concentrates procurement among integrated providers with regional application laboratories.
Volume leadership sits with consumer goods; value capture concentrates in industrial manufacturing.
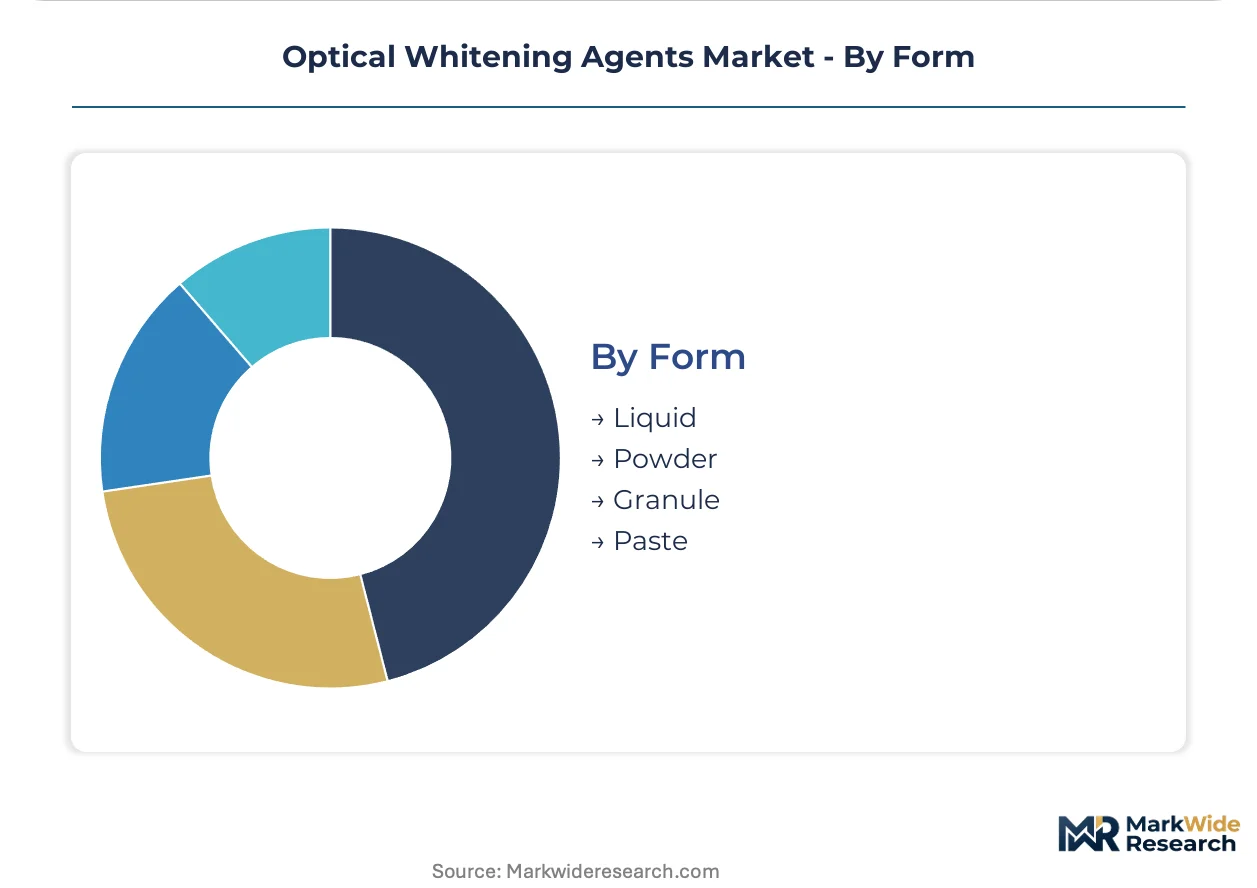
Form:
Supply concentration in legacy powder infrastructure creates conversion costs for textile processors adopting liquid systems.
- Liquid:Concentrate formulations enable continuous dyeing automation and just-in-time inventory positioning. Dosing system upgrades require capital investment that fragments adoption timing across mill networks.
- Powder:Retains share in batch textile processing and geographic markets with limited liquid handling infrastructure.
- Granule:Flowable solids address dust containment requirements in plastics compounding.
- Paste:High-viscosity carriers suit specialized coating applications.
Installed base favors powder; technical transition favors liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization timelines for stilbene derivatives are concentrating supplier investment in toxicological testing infrastructure across the European Economic Area. India and China are expanding domestic brightener intermediate production to reduce import dependency. Paper mills in Finland and Austria are accelerating chlorine-free bleaching trials ahead of EU Green Deal mandates.
China
Domestic production of benzene derivatives and fluorescent brightener intermediates is displacing import volumes for regional formulators. MIIT's dual carbon goals are pushing coastal chemical clusters toward cleaner sulfonation process technologies. The Yangtze River Delta hosts expanded capacity for detergent-grade sodium fluorescent brighteners serving Southeast Asian export markets.
India
Textile exports to EU and US markets are pulling domestic chemical production toward ZDHC-compliant brightener grades. BIS certification requirements for imported feedstocks are raising barriers for non-compliant suppliers. Gujarat and Maharashtra house expanded capacity for both textile and detergent applications, with mills in Surat converting from powder to liquid handling systems.
Germany
REACH registration dossiers for stilbene-based brighteners are forcing toxicological testing investments among incumbent suppliers. The EU Green Deal's chlorine-free paper bleaching mandates are elevating optical brightener loadings in domestic mills. The Rhine-Ruhr chemical corridor retains specialized sulfonation process engineering expertise concentrated among aging technical workforces.
United States
EPA aquatic toxicity restrictions on benzoxazole derivatives are redirecting detergent formulation toward biodegradable alternatives. The IRA's domestic manufacturing incentives are supporting reshoring of brightener intermediate production. Gulf Coast petrochemical clusters are expanding benzene derivative supply chains for captive brightener synthesis.
Brazil
Liquid concentrate brightener adoption lags in Latin America's largest detergent market, creating technical service-intensive entry opportunities. ANVISA's evolving chemical substance regulations are aligning with OECD test guidelines for new brightener registrations. São Paulo's industrial belt hosts underpenetrated textile processing demand for continuous dyeing system conversions.
Optical Whitening Agents Market Competitive Landscape
Backward-integrated multinationals and regional formulation specialists split the market along regulatory compliance and cost efficiency vectors. The structure concentrates among REACH-registered incumbents in Europe and domestic intermediate producers in Asia. Three archetypes dominate: petrochemical-backed integrated suppliers, application-specific technical service providers, and commodity-scale regional formulators. Competitive moves center on toxicological dossier compilation for EU market access and liquid concentrate formulation partnerships with detergent makers.
Among Germany-based integrated suppliers, BASF SE exemplifies the petrochemical-backed archetype through captive benzene derivative supply chains. Huntsman International LLC represents the technical service-intensive tier with R&D focus on liquid concentrate systems. Archroma occupies a position within the application-specific segment, anchoring textile brightener supply for ZDHC-compliant apparel brands. These three entities illustrate how regulatory geography and substrate specialization stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| Archroma |
| Clariant AG |
| 3V Sigma S.p.A. |
| Eastman Chemical Company |
| Teh Fong Min International |
| Kolorjet Chemicals Pvt Ltd |
| Aron Universal Limited |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese fluorescent brightener intermediate production is compressing export pricing while forcing European formulators toward higher-cost REACH-compliant supply chains. This utilization asymmetry between Asian commodity output and European specialty manufacturing creates divergent margin structures across regulatory jurisdictions.
Pricing Analysis
Price spreads between Indian commodity-grade sodium fluorescent brighteners and EU-certified polymer-bound systems exceed threefold, reflecting REACH dossier amortization and toxicological testing burdens. Three-tier pricing structure across premium, standard, and economy levels separates ZDHC-compliant textile grades from detergent commodity volumes and plastics food-contact specifications. Cost compression in Indian detergent-grade supply is intensifying as domestic benzene derivative capacity expands. Consumer goods manufacturers exhibit highest price sensitivity, while industrial manufacturing segments absorb premiums for migration compliance documentation.
Supply Chain Analysis
Export-control scrutiny on benzene derivative process technology limits technology transfer to emerging brightener manufacturers, concentrating advanced sulfonation capability in Germany and Japan. Feedstock supply draws from Chinese benzene derivative clusters, Indian naphthalene processing hubs, and Gulf Coast petrochemical corridors. Single-source vulnerability concentrates in aged sulfonation reactor engineering talent pools. Distribution runs through regional chemical distributors with technical service capabilities, anchored by formulation partnerships with detergent makers and textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized diazotization control expertise is aging out of the workforce faster than training pipelines can replace it, creating a bottleneck that will determine which suppliers capture margin in specification-driven segments.
For Market Incumbents: Insulate REACH-registered positions by accelerating toxicological dossier updates ahead of stilbene authorization deadlines, while locking Brazilian detergent makers into liquid concentrate technical service partnerships before regional formulators mature. Backward integration into captive benzene derivative supply hedges crude-linked feedstock volatility threatening margin stability. For New Entrants and Emerging Players: Brazilian liquid concentrate underpenetration offers the most accessible entry vector, given technical service requirements that favor agile specialists over commodity-scale incumbents. Vietnamese and Bangladeshi textile mills converting from powder to liquid handling systems present equipment-plus-formulation bundled sales opportunities. Target ANVISA-aligned registration pathways to preempt regulatory alignment with OECD test guidelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-compliant toxicological testing infrastructure, favoring scaled incumbents over capital-constrained challengers. Acquire application-specific technical service providers with regional colorimetry laboratories and ZDHC certification relationships. Monitor ECHA authorization timeline announcements as inflection signals for portfolio reallocation between stilbene-based and triazine-alternative technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzene Derivatives | Captive feedstock supply insulates margin from crude-linked volatility in stilbene synthesis. |
| REACH Dossier Pre-Registration | Early toxicological investment secures European market access before authorization deadlines tighten. |
| Liquid Concentrate Formulation Partnerships | Technical service bundling locks detergent makers into just-in-time inventory systems. |
| Continuous Dyeing System Conversion Support | Equipment financing accelerates Vietnamese and Bangladeshi textile mill adoption trajectories. |
| ZDHC Compliance Certification | Certified grades capture premium positioning in EU and US apparel export supply chains. |
Research Methodology
Cross-validation between primary interviews with sulfonation plant engineers, detergent procurement leads, textile technical directors, and REACH regulatory consultants anchors the qualitative findings against customs trade data, ECHA registration databases, SEC chemical sector filings, and Indian BIS certification records. Bottom-up capacity estimates triangulate against top-down consumption models across end-use segments.
Calibration against historical REACH implementation timelines in adjacent chemical sectors shapes the projection framework. Segmentation models incorporate product type, application substrate, form factor, and regional regulatory cluster dimensions. CAGRs derive from intensity-of-use coefficients applied to downstream industry output forecasts, with specific inputs from paper mill chlorine-free bleaching adoption curves and textile export volume trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic intermediate producers or accelerated triazine substitution in European paper mills would shift outcomes. Material shifts in ECHA authorization timelines or EPA aquatic toxicity rulemakings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Australia and New Zealand Aerosol Market