
 UV/IR Blocker Market | 2026-2036
UV/IR Blocker Market Size, Share, and Industry Trends Forecast 2026-2036
UV/IR Blocker Market Analytics
Advancements in nano-coating deposition techniques is rewriting how UV/IR blocking functionality integrates into optical substrates without compromising visible light transmission. Materion Company leverages its thin-film expertise to sustain leadership in precision-coated components for defense and semiconductor applications. Optics Balzers anchors its position through specialized sputtering processes that dominate European aerospace and automotive supply chains. LightPath Technologies differentiates by controlling vertical manufacturing of molded infrared optics for thermal imaging systems.
UV/IR blockers are materials engineered to attenuate ultraviolet radiation and infrared energy through selective absorption, reflection, or interference, typically specified by cutoff wavelengths, optical density at target bands, and thermal stability thresholds exceeding 150°C for coated glass applications. Their primary commercial purpose centers on protecting sensitive electronics, reducing thermal loads in enclosed spaces, and preventing photodegradation of organic substrates exposed to solar radiation. Films and coatings represent the most mature revenue pools where automotive glazing and architectural window retrofits generate predictable volume, while nano-coating technology commands premium positioning due to sub-wavelength layer precision and durability advantages over conventional polymer-based alternatives. Devices segment growth concentrates in healthcare phototherapy equipment and semiconductor lithography where wavelength-selective filtering determines process yield.
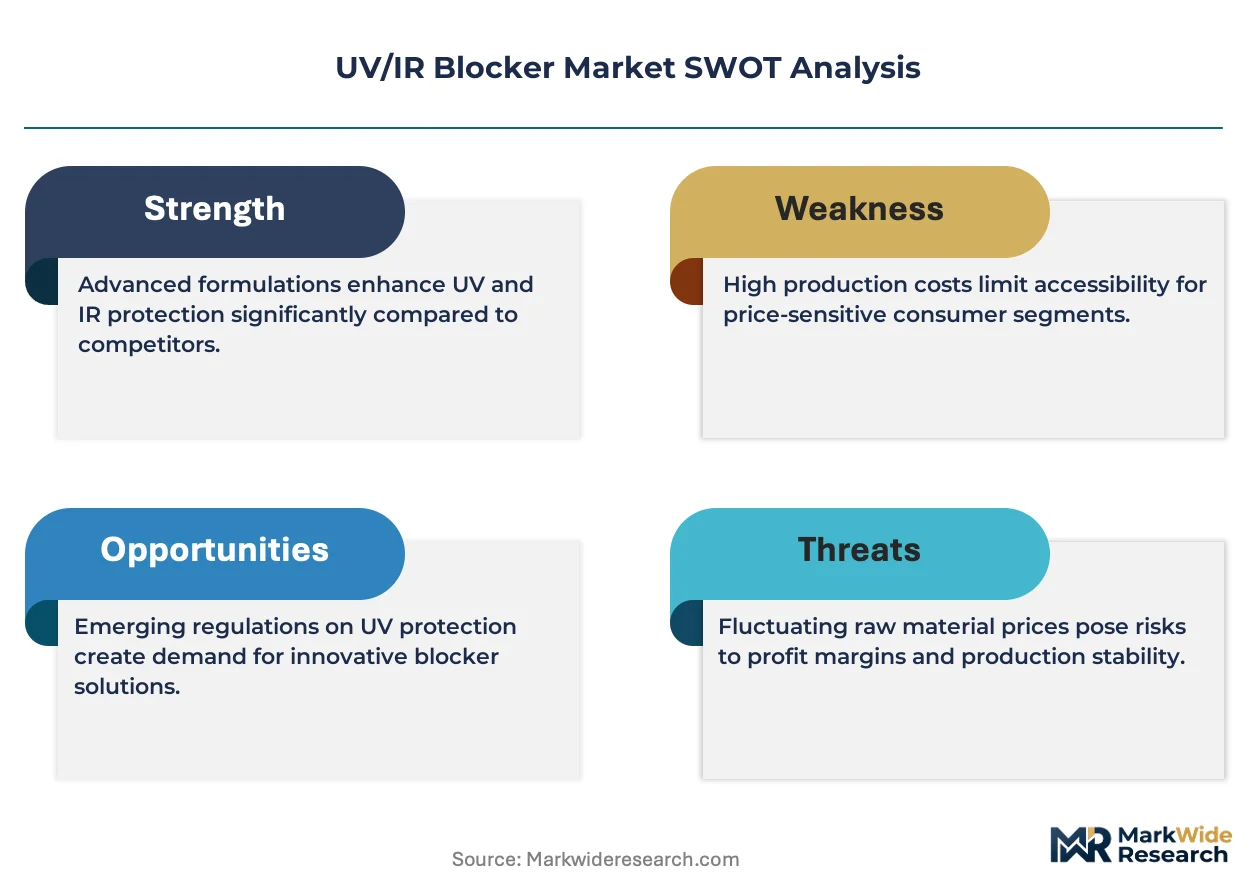
EPA guidelines on volatile organic compound emissions constrain solvent-based coating formulations in the United States, while REACH registration requirements in Europe govern chemical additive compositions used in textile UV treatments. FDA device classification rules shape validation protocols for healthcare applications involving patient-contact UV/IR blocking materials. Stakeholders must monitor evolving dual-use export control lists that could restrict thermal-blocking optical components with military applicability.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating nano-coated windshield procurement to comply with stricter solar gain standards, compressing adoption timelines for sub-wavelength precision deposition techniques across the supply base.
Growth Catalysts
- ECE R43 and JIS D 5705 Standards:German and Japanese automotive glazing regulations mandate reduced solar heat gain coefficients, forcing OEMs to specify advanced UV/IR blocking films in new vehicle platforms.
- Healthcare Infrastructure Modernization:South Korea and the United States are expanding polymer-based textile treatments for medical protective equipment, concentrating demand for UV-blocking fabric coatings in hospital procurement.
- Nano-Coating Deposition Advancement:Sub-wavelength layer precision now enables optical substrates to maintain visible light transmission while blocking targeted wavelengths, opening defense and semiconductor applications.
Market Restraints
- Indium Tin Oxide Input Volatility:Sputtering targets for transparent conductive coatings face price swings tied to rare earth supply concentration in Chinese processing facilities.
- REACH Registration Burden:ECHA chemical additive requirements for textile UV treatments impose multi-year validation timelines and documentation costs on European formulators.
- Polymer Degradation Limitations:Organic UV absorbers in conventional films exhibit photostability thresholds below 150°C, constraining deployment in high-temperature automotive glazing zones.
Strategic Opportunities
- Semiconductor Lithography Expansion:Wavelength-selective filtering for EUV and DUV photolithography equipment represents underpenetrated demand from foundries in Taiwan and South Korea.
- EPA VOC Compliance Tailwind:Waterborne coating formulations meeting EPA volatile organic compound guidelines capture retrofit volume as U.S. architectural window regulations tighten.
- Phototherapy Device Convergence:Integration of UV-blocking optics with LED-based medical equipment creates new specification channels in hospital systems modernizing dermatology suites.
Industry Challenges
- Thin-Film Sputtering Talent Scarcity:Specialized vacuum deposition engineers command premium compensation, constraining capacity expansion at precision optics manufacturers.
- Dual-Use Export Control Complexity:Thermal-blocking optical components with military applicability face evolving restriction lists, requiring legal review of customer end-use declarations.
- FDA Device Validation Timelines:Patient-contact UV/IR blocking materials for healthcare applications require 510(k) or PMA pathways that extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV/IR Blocker Market |
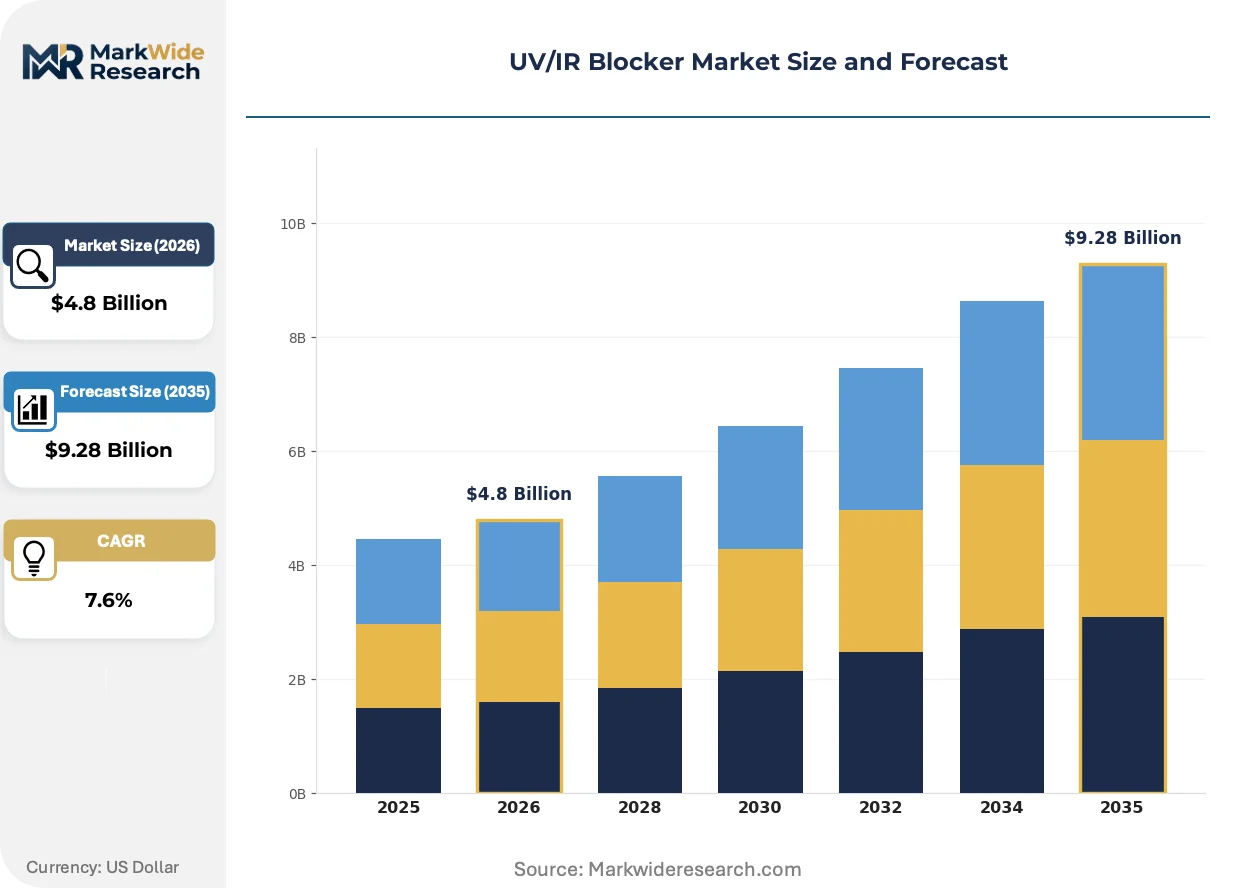
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Coatings, Devices, Textiles Technology: Nano-coating, Polymer-based, Glass-based, Chemical additives Application: Automotive, Construction, Healthcare, Electronics End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Materion Company, Astronomik, Optics Balzers, UQG Optics Ltd, Baader Planetarium, LightPath Technologies, Midwest Optical Systems Inc., Teleskop Service, Optolong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV/IR Blocker Market Evolving Landscape
Digital process control is penetrating deposition equipment, enabling real-time thickness monitoring that reduces coating variability and compresses qualification cycles for automotive and aerospace suppliers.
Atomic layer deposition is digitizing quality assurance protocols in precision optics manufacturing. Defense contractors and semiconductor equipment OEMs are adopting ALD-equipped production lines at accelerated rates. This technology is digitizing specification documentation, allowing substrate-by-substrate traceability that satisfies dual-use audit requirements.
REACH restrictions on perfluorinated compounds are forcing reformulation of durable water-repellent textile treatments that incorporate UV-blocking functionality. European medical textile suppliers face supply interruptions as legacy chemistries lose authorization. Automotive seating fabric manufacturers in Germany and France are responding fastest, qualifying silicone-based alternatives ahead of 2025 sunset dates.
Hospital procurement departments are consolidating vendor lists for phototherapy equipment around suppliers offering integrated UV-filtering optics with validated service life data. Device manufacturers are displacing standalone filter suppliers by bundling wavelength-selective components into system-level contracts. This concentration is most visible in U.S. academic medical centers and South Korean hospital networks undergoing central purchasing reorganizations.
UV/IR Blocker Market Segmentation
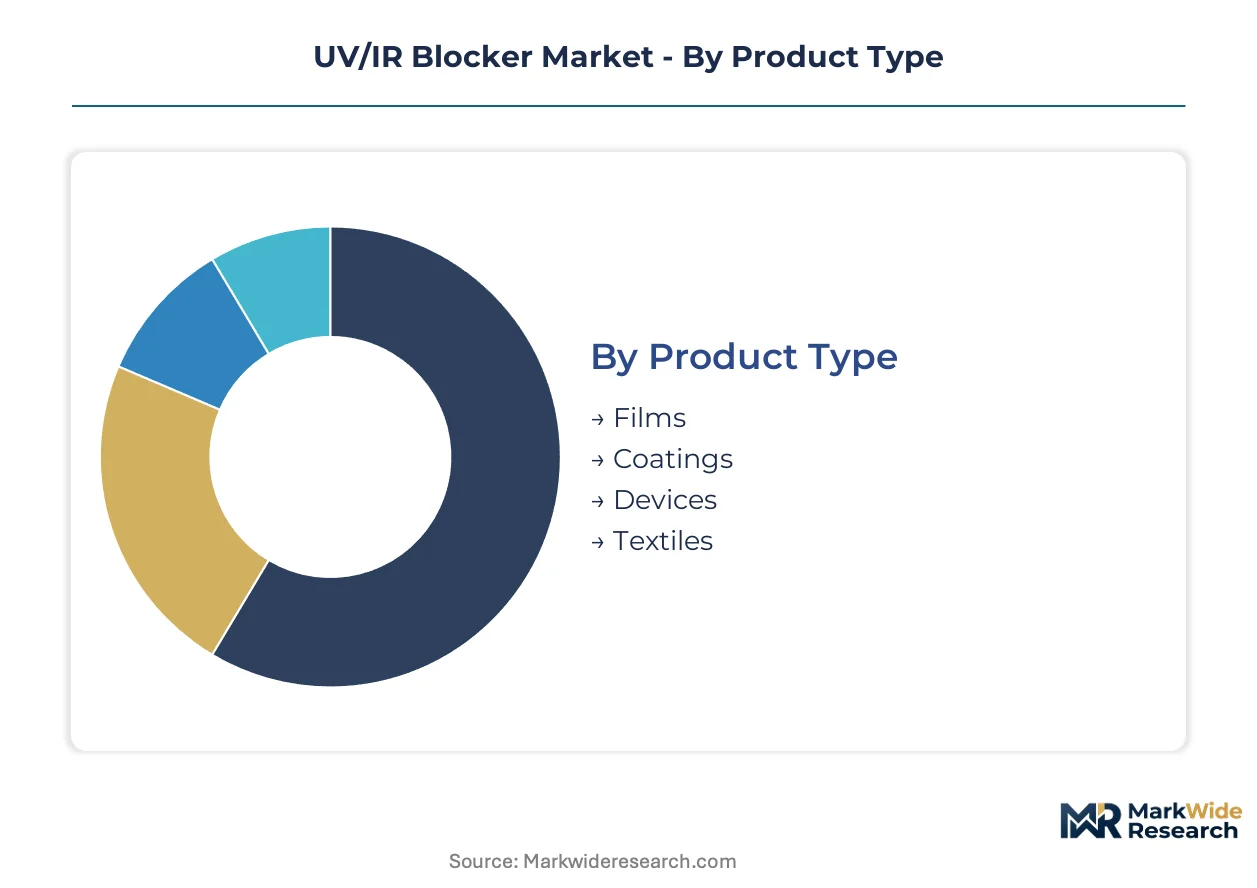
UV/IR blocker procurement patterns diverge sharply across product formats and customer tiers, with automotive OEMs demanding validated service life documentation while healthcare systems prioritize integrated device-level contracts over component sourcing.
Product Type:
After-sales service intensity varies dramatically across physical formats, with coated glass requiring field inspection protocols and textile treatments needing laundering durability certification.
- Films:Multi-layer polymer laminates with embedded UV absorbers and metallic IR reflectors, typically 50-200 microns thick. German and Japanese automotive glazing procurement concentrates demand here as ECE R43 and JIS D 5705 compliance tightens.
- Coatings:Liquid-deposited layers including sputtered metal oxides and sol-gel ceramic formulations applied to rigid substrates. Nano-coated deposition techniques command premium positioning in semiconductor lithography and defense optics where sub-wavelength precision determines yield.
- Devices:Discrete optical components including bandpass filters, cold mirrors, and heat-absorbing glass for phototherapy equipment and thermal imaging systems.
- Textiles:Fabric treatments incorporating UV-absorbing dyes or surface-deposited nanoparticles for medical protective equipment and outdoor apparel.
By volume, Films leads. By growth pace, Coatings is climbing the fastest.
Technology:
Cost tier stratification separates precision deposition methods from commodity chemical approaches, with vacuum-based processes carrying 3-5x capital intensity versus solution-based alternatives.
- Nano-coating:Atomic layer deposition and magnetron sputtering achieve sub-nanometer thickness control for wavelength-selective interference stacks. Taiwan and South Korea foundry expansion for EUV lithography equipment drives specification intensity here.
- Polymer-based:Organic UV absorbers including benzotriazoles and hindered amine light stabilizers dispersed in acrylic or polyester matrices. Photostability thresholds below 150°C constrain deployment in high-temperature automotive zones.
- Glass-based:Bulk-doped silicate or phosphate glasses with inherent absorption bands, primarily for phototherapy and laser safety applications.
- Chemical additives:Masterbatch concentrates for extrusion into films and fibers, governed by REACH registration requirements for European textile formulators.
By installed base, Polymer-based dominates. By specification premium, Nano-coating is gaining share fastest.
Application:
Customer type fragmentation splits procurement between specification-driven OEMs and price-sensitive retrofit installers, with diverging validation requirements.
- Automotive:Windshield and side glazing treatments reducing solar heat gain coefficients. OEMs in Germany and Japan are compressing supplier qualification timelines for nano-coated deposition capacity.
- Construction:Architectural window retrofits and new build glazing, with EPA VOC compliance favoring waterborne formulations in United States retrofit volume.
- Healthcare:Phototherapy equipment, surgical protective textiles, and patient-contact UV filtering. FDA device classification rules extend validation cycles for materials with patient contact.
- Electronics:Semiconductor lithography filtering, display polarizers, and sensor protection. Wavelength-selective components for EUV and DUV equipment represent underpenetrated demand from Taiwan and South Korea foundries.
By current revenue, Automotive leads. By expansion trajectory, Healthcare is ahead.
End User:
Supply concentration differs across channel tiers, with direct OEM relationships requiring dedicated technical service teams versus distributor networks handling standard SKU fulfillment.
- Manufacturers:Tier-1 and Tier-2 suppliers integrating UV/IR blocking into finished goods including automotive glazing systems, medical devices, and semiconductor equipment.
- Retailers:Big-box and specialty channels for consumer-facing window film and protective textile products.
- Distributors:Industrial supply houses serving architectural contractors and automotive aftermarket installers.
- Consumers:Direct purchasers of DIY window films, protective eyewear, and outdoor apparel with UV-blocking claims.
By transaction value, Manufacturers lead. By channel expansion, Distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for indium tin oxide sputtering targets tilts trade balances toward Chinese processing facilities, while automotive glazing procurement in Germany and Japan drives export demand for precision-coated substrates. South Korean foundries and Taiwanese semiconductor equipment manufacturers concentrate specification intensity for wavelength-selective optical components.
United States
Healthcare infrastructure modernization concentrates procurement for polymer-based textile treatments in hospital systems across the Southeast and Pacific Coast. EPA volatile organic compound guidelines constrain solvent-based coating formulations, favoring waterborne alternatives in architectural window retrofits. FDA device classification rules extend validation timelines for patient-contact UV/IR blocking materials in phototherapy equipment.
Germany
Automotive OEM procurement for nano-coated windshield films accelerates as ECE R43 compliance tightens solar heat gain coefficients. KBA oversight of vehicle glazing homologation compresses supplier qualification timelines. Stuttgart and Munich industrial clusters host Tier-1 glazing system integrators expanding deposition capacity for sub-wavelength precision coatings.
Japan
Domestic automotive production under JIS D 5705 standards drives specification intensity for multi-layer polymer laminates in windshield applications. METI industrial policy supports domestic sputtering target manufacturing to reduce rare earth import exposure. Nagoya and Hiroshima production corridors concentrate OEM technical service teams for deposition process validation.
South Korea
Foundry expansion for EUV lithography equipment generates underpenetrated demand for wavelength-selective filtering components. MFDS medical device regulations govern validation protocols for phototherapy equipment integrating UV-blocking optics. Seoul Capital Area and Busan-Ulsan clusters concentrate semiconductor equipment OEM procurement for atomic layer deposition capacity.
Taiwan
Semiconductor lithography supply chains anchor specification intensity for nano-coating deposition techniques in precision optics. Domestic industrial policy prioritizes captive production of sputtered metal oxide coatings for display polarizers and sensor protection. Hsinchu Science Park and Taichung precision manufacturing zones concentrate foundry equipment sub-tier procurement.
UV/IR Blocker Market Competitive Landscape
On the supply side, the industry is bifurcated between precision deposition specialists and commodity chemical formulators, with thin-film sputtering expertise commanding 3-5x capital intensity premiums over solution-based alternatives. Strategic archetypes separate nano-coating deposition houses, polymer masterbatch compounders, and integrated device-level suppliers. Dominant competitive moves center on capacity expansion for atomic layer deposition lines and strategic partnerships securing indium tin oxide feedstock agreements.
Specialists in thin-film precision deposition include Materion Company, Optics Balzers, and LightPath Technologies. Materion exemplifies the vertically integrated materials-to-components archetype, leveraging bulk material expertise into coated substrate supply. Optics Balzers occupies a position within European aerospace and automotive supply chains through specialized sputtering process control. LightPath Technologies anchors the molded infrared optics segment, representing backward integration into substrate manufacturing for thermal imaging applications.
| Leading Market Players |
|---|
| Materion Company |
| Astronomik |
| Optics Balzers |
| UQG Optics Ltd |
| Baader Planetarium |
| LightPath Technologies |
| Midwest Optical Systems Inc. |
| Teleskop Service |
| Optolong |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor carries sputtering target shipments from Chinese indium tin oxide processors to European automotive glazing integrators, with freight cost volatility amplifying price spreads between nano-coated deposition capacity and commodity polymer film alternatives while compressing margins for mid-tier formulators caught between feedstock concentration and OEM purchasing power.
Pricing Analysis
Prior-generation polymer-based UV absorbers trade at commodity levels, current-generation nano-coated deposition commands 3-5x capital-intensity premiums, and next-generation atomic layer deposition capacity is capturing specification premiums in semiconductor lithography applications. Pricing stratifies across automotive OEM certification tiers, FDA device-grade validation levels, and architectural retrofit volume scales. Cost compression in commodity polymer films is intensifying because Chinese masterbatch compounders are expanding capacity. Hospital procurement committees exhibit lowest price sensitivity due to patient-safety liability exposure, while architectural retrofit installers demonstrate highest sensitivity to per-square-meter material costs.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities backed by Japanese trading houses are restructuring working capital requirements for Tier-1 glazing system integrators. Raw material sourcing concentrates in China for indium tin oxide sputtering targets, Germany for precision deposition equipment, and South Korea for EUV-grade optical substrates. Critical input dependencies span rare earth processing for transparent conductive coatings, high-purity metal oxides for interference stacks, and fluoropolymer precursors for durable textile treatments. Single-source vulnerability in Chinese rare earth concentrate supply poses structural risk. Distribution runs through direct OEM technical service teams for validated automotive and healthcare applications, with industrial distributors handling standard architectural film SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from deposition process validation, field inspection protocols, and certified laundering durability testing for medical textiles is expanding faster than hardware shipments, creating recurring-revenue economics that favor incumbents with captive technical service infrastructure.
For Market Incumbents: Build certification moats around FDA 510(k) pathways and ECE R43 homologation pre-approvals. Secure captive indium tin oxide feedstock agreements through long-term offtakes with Chinese rare earth processors to insulate against price volatility. Add atomic layer deposition capacity in Taiwan and South Korea to intercept foundry equipment procurement for EUV lithography filtering components.
For New Entrants and Emerging Players: South Korean hospital network consolidation around integrated phototherapy device contracts offers the most penetrable entry point for wavelength-selective optical component suppliers lacking automotive OEM validation histories. Target waterborne coating formulations for U.S. architectural window retrofits where EPA VOC compliance creates specification barriers for incumbent solvent-based players. Lead with validated service life documentation bundled into system-level contracts rather than component sales.
For Investors and Strategic Acquirers: Thin-film sputtering specialists with demonstrated ECE R43 homologation track records represent the most defensible acquisition archetype in a five-to-ten-year window. Monitor dual-use export control list revisions as the critical inflection signal; restriction expansion would strand capital in defense-exposed precision optics capacity while creating scarcity premiums for cleared suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Capacity Expansion | Taiwan and South Korea foundries demand sub-nanometer precision for EUV lithography filtering components. |
| Backward Integration into Sputtering Target Supply | Indium tin oxide feedstock security insulates margin structures from Chinese rare earth processing volatility. |
| FDA 510(k) Premarket Submission Pathway | Patient-contact UV/IR blocking materials require validation cycles that extend commercialization timelines by 18-36 months. |
| Waterborne Coating Formulation Transition | EPA VOC compliance captures U.S. architectural retrofit volume as solvent-based alternatives face regulatory sunset. |
| Hospital System Direct Partnership | Seoul Capital Area and U.S. academic medical center procurement consolidation favors integrated device-level contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automotive OEM glazing procurement directors, thin-film deposition equipment engineers, hospital purchasing committee administrators, and ECHA regulatory affairs specialists; alongside secondary validation against SEC 10-K filings from precision optics manufacturers, FDA 510(k) submission databases, ECE R43 homologation registries, and customs trade data for indium tin oxide sputtering target flows. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Forecast inputs span product format evolution, technology generation substitution rates, application penetration curves, and end-user channel mix shifts across the projection horizon. Segmentation dimensions modeled include physical format, deposition technology tier, application vertical, and customer type. CAGRs derive from segment-level volume trajectories and value-per-unit trends, with specific weighting for EUV lithography equipment capex cycles and automotive glazing regulatory compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese masterbatch compounders or accelerated REACH authorization withdrawals would shift outcomes. Macroeconomic deviation in semiconductor capital expenditure, regulatory tightening in dual-use export controls, or breakthrough organic UV absorber photostability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Alpha Bisabolol Market