
 Catharanthine Market | 2026-2036
Catharanthine Market Size, Share, and Industry Trends Forecast 2026-2036
Catharanthine Market Outlook
Oncology API sourcing is broadening as pharmaceutical manufacturers diversify beyond traditional vinblastine and vincristine supply chains. AK Scientific leverages its catalog breadth to serve research-stage buyers with high-purity reference standards. Cayman Chemical Company anchors North American supply through specialized alkaloid extraction capabilities. Hainan Yueyang Biotech competes on cost-efficient botanical sourcing from subtropical cultivation zones.
Catharanthine is an indole alkaloid extracted from Catharanthus roseus, typically requiring chromatographic purification to achieve pharmaceutical-grade purity above 98 percent for use as a precursor in semisynthetic vinca alkaloid production. Powder formulations dominate commercial transactions due to stability advantages in long-haul shipping and flexible downstream processing. Pharmaceutical applications lead segment value, while nutraceuticals represents the fastest-growing category as functional ingredient formulators explore alkaloid-adjacent bioactive positioning. Research institutions sustain extract demand through consistent procurement of small-batch certified reference materials.
FDA current Good Manufacturing Practice requirements and EMA active substance master file guidelines shape purity documentation burdens for catharanthine suppliers seeking commercial pharmaceutical qualification. China's NMPA imposes additional botanical source traceability mandates under revised traditional medicine ingredient regulations. Stakeholders must monitor evolving pharmacopeial monograph revisions and cultivation sustainability certifications that could reshape raw material access economics.
Market Dynamics
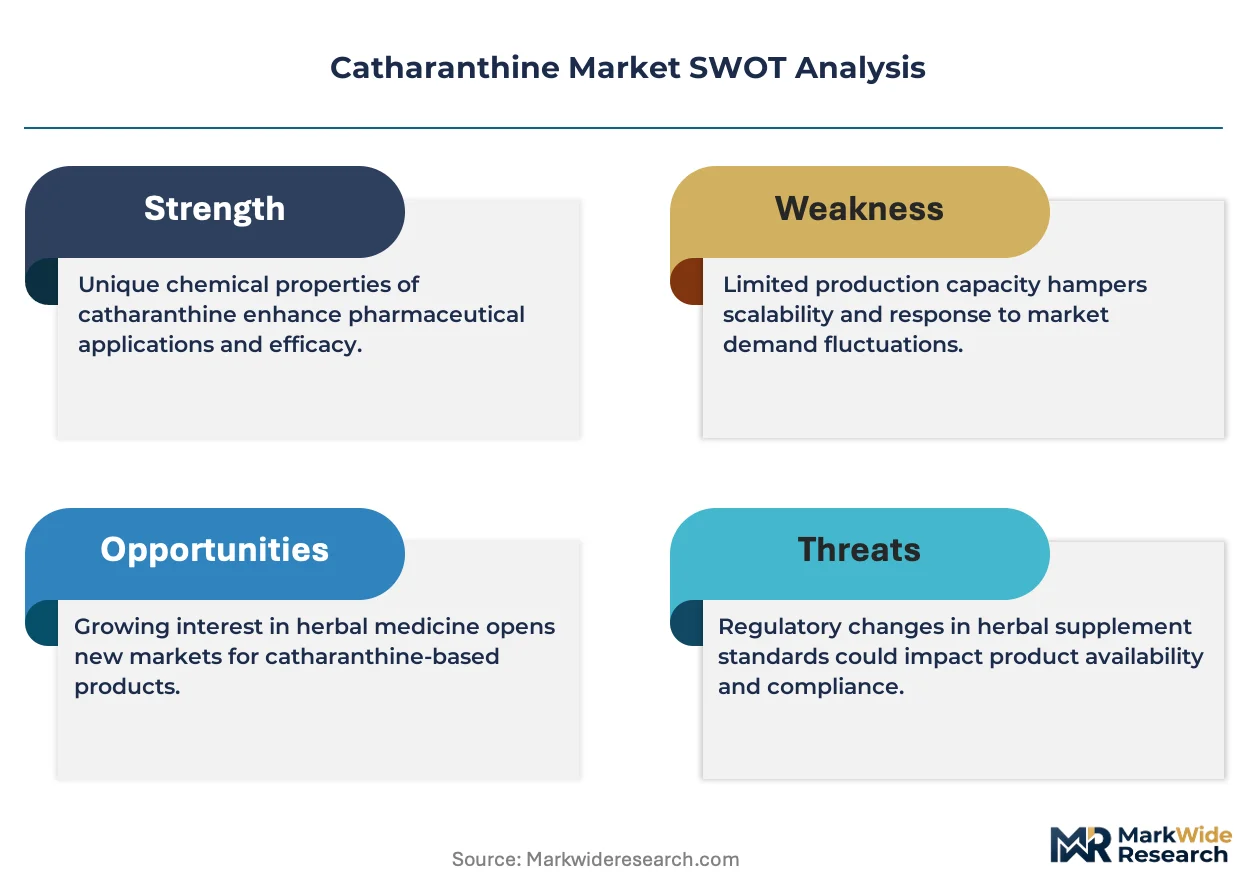
Pharmaceutical-grade catharanthine supply is tightening as FDA and EMA purity documentation requirements force smaller botanical extractors out of commercial qualification, concentrating viable supply among chromatography-capable manufacturers in three countries.
Growth Catalysts
- Vinca Alkaloid Pipeline Expansion:Oncology drug developers are securing long-term catharanthine offtake agreements for vincristine and vinblastine semisynthesis, pulling demand from research-grade into commercial-scale procurement.
- EMA Active Substance Master File Harmonization:Streamlined regulatory pathways for qualified suppliers are accelerating pharmaceutical-grade catharanthine qualification timelines across European manufacturing networks.
- Botanical Extraction Automation:Supercritical CO2 and simulated moving bed chromatography systems are reducing per-batch purification costs for high-purity indole alkaloid isolation.
Market Restraints
- Madagascar Cultivation Concentration:Over 60 percent of wild Catharanthus roseus sourcing traces to southwestern Madagascar growing zones, exposing supply to climate volatility and export licensing disruptions.
- Chromatographic Solvent Cost Inflation:Acetonitrile and high-purity ethanol price volatility is compressing margins for pharmaceutical-grade catharanthine producers maintaining 98.5 percent purity thresholds.
- Biosynthetic Alkaloid Substitution:Microbial fermentation routes to vinca alkaloid precursors are advancing in academic and industrial biotechnology programs, threatening long-term botanical extraction demand.
Strategic Opportunities
- Indian Contract Manufacturing Expansion:CDSCO pharmaceutical ingredient regulations and PLI scheme incentives are positioning Indian chemical synthesis clusters as alternative catharanthine purification hubs.
- Nutraceutical Bioactive Positioning:Functional ingredient formulators in Germany and the United States are exploring catharanthine-adjacent alkaloid extracts for cellular health positioning in premium supplement lines.
- Blockchain Source Traceability:NMPA-mandated botanical chain-of-custody documentation is creating first-mover advantage for suppliers deploying digital provenance systems from cultivation to final extract.
Industry Challenges
- Alkaloid Chemist Talent Scarcity:Specialized expertise in indole alkaloid isolation and chiral separation is concentrating among retiring specialists, constraining technical workforce expansion for new market entrants.
- Multi-Jurisdiction Master File Synchronization:Parallel FDA Drug Master File, EMA Active Substance Master File, and NMPA registration requirements are extending qualification timelines and legal compliance costs for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catharanthine Market |
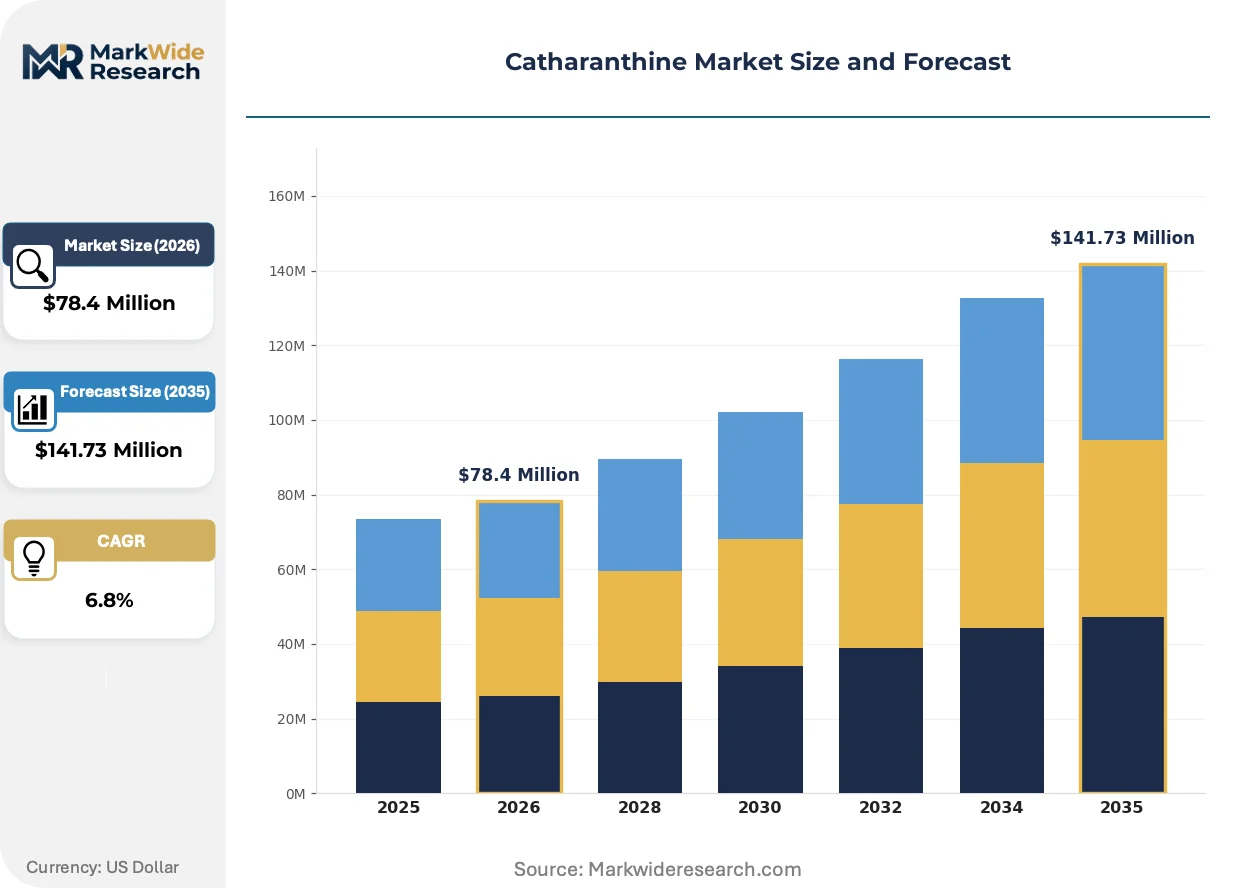
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powder, Capsules, Tablets Application: Pharmaceuticals, Nutraceuticals, Herbal Remedies, Cosmeceuticals End User: Clinics, Hospitals, Research Institutions, Homecare Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | AK Scientific, Cayman Chemical Company, Stanford Chemicals, BioVision Inc., Enzo Biochem, Hainan Yueyang Biotech, Abcam, ChemFaces, Selleck Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catharanthine Market Strategic Shifts
Continuous processing technologies and digital supply chain verification are compressing catharanthine production economics while fragmenting traditional botanical sourcing relationships toward controlled-environment cultivation.
Simulated moving bed chromatography is decentralizing catharanthine purification capacity from centralized European pharmaceutical chemical hubs toward regional botanical processing centers. Mid-scale alkaloid extractors in subtropical growing regions are adopting this continuous separation technology to achieve pharmaceutical-grade purity without capital-intensive batch infrastructure. The structural consequence is opening commercial qualification pathways for suppliers previously confined to research-grade material.
EMA revised guidelines on herbal substance identification and NMPA traceability mandates for traditional medicine ingredients are forcing catharanthine suppliers to deploy genomic authentication and isotopic sourcing verification. Industrial consequence includes mandatory documentation of Catharanthus roseus cultivar provenance and harvest location coordinates for commercial pharmaceutical qualification. European oncology API manufacturers are responding by consolidating supplier relationships toward vertically integrated botanical processors with captive cultivation operations.
Long-term offtake contracting is displacing spot market purchasing among pharmaceutical manufacturers securing catharanthine for vinca alkaloid semisynthesis programs. Tier-one oncology API producers are locking three-to-five-year supply agreements directly with Madagascar and Indian botanical processors, bypassing traditional alkaloid trading intermediaries. This pattern is most visible in United States and German manufacturing networks where vincristine and vinblastine production continuity carries critical therapeutic supply obligations.
Catharanthine Market Segmentation
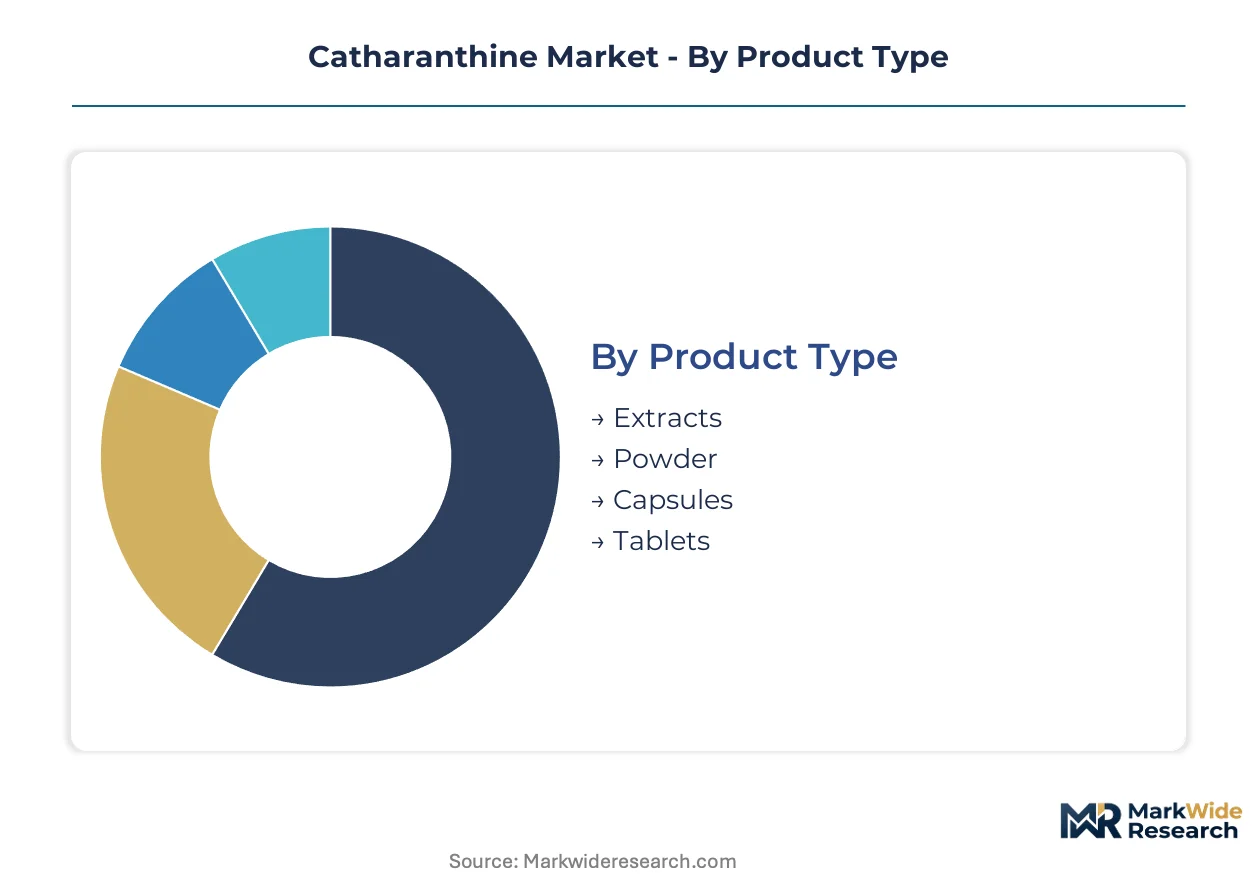
Catharanthine procurement patterns diverge sharply across product formats and end-use applications. Pharmaceutical buyers prioritize purity documentation and regulatory compliance, while nutraceutical formulators emphasize cost efficiency and botanical provenance. Understanding these segment-specific decision drivers illuminates supplier positioning opportunities.
Product Type:
Buyers select catharanthine formats based on downstream processing requirements and stability needs during transport and storage.
- Powder:Crystalline or lyophilized powder dominates commercial transactions due to extended shelf stability and flexible reconstitution for semisynthetic vinca alkaloid production. United States and German pharmaceutical manufacturers favor this format for vincristine and vinblastine synthesis programs requiring precise dosing control.
- Extracts:Botanical concentrates retain broader alkaloid profiles suitable for research applications and nutraceutical formulation where single-molecule purity is less critical. Chinese traditional medicine ingredient processors source these for multi-alkaloid traditional preparations.
- Capsules:Pre-measured dosage units serve functional supplement brands in Germany and the United States exploring cellular health positioning.
- Tablets:Compressed formulations appear in limited commercial volumes, primarily for standardized traditional medicine products in regulated Asian markets.
Powder leads on scale; capsules lead on momentum.
Application:
End-use sectors impose distinct purity thresholds, documentation burdens, and volume requirements on catharanthine suppliers.
- Pharmaceuticals:Active pharmaceutical ingredient production demands chromatographic purification exceeding 98 percent purity with full FDA Drug Master File or EMA Active Substance Master File documentation. Oncology drug manufacturers in the United States, Germany, and China anchor procurement volumes for vincristine and vinblastine semisynthesis.
- Nutraceuticals:Functional ingredient formulators leverage catharanthine-adjacent alkaloid extracts for cellular health and longevity product positioning. German and United States supplement brands drive category expansion through premium positioning in mitochondrial support formulations.
- Herbal Remedies:Traditional medicine systems utilize Catharanthus roseus preparations with broader phytochemical profiles. Chinese NMPA traceability mandates reshape sourcing relationships for botanical ingredient suppliers.
- Cosmeceuticals:Topical alkaloid applications remain nascent, with limited commercial traction in anti-aging skincare formulations.
Pharmaceuticals commands volume concentration; nutraceuticals climbs fastest.
End User:
Customer type determines order scale, certification requirements, and technical support intensity from catharanthine suppliers.
- Research Institutions:Universities and contract research organizations sustain consistent demand for small-batch certified reference materials with full analytical characterization. United States academic medical centers and European oncology research networks procure through specialized chemical catalog distributors.
- Hospitals:Integrated health systems with in-house compounding pharmacies represent emerging procurement nodes for specialized alkaloid preparations in select markets.
- Clinics:Outpatient oncology and integrative medicine practices generate limited direct catharanthine demand, primarily through compounded medication intermediaries.
- Homecare:Direct consumer access remains negligible due to prescription status and handling requirements for vinca alkaloid precursors.
Research institutions anchor steady demand; hospitals represent emerging volume.
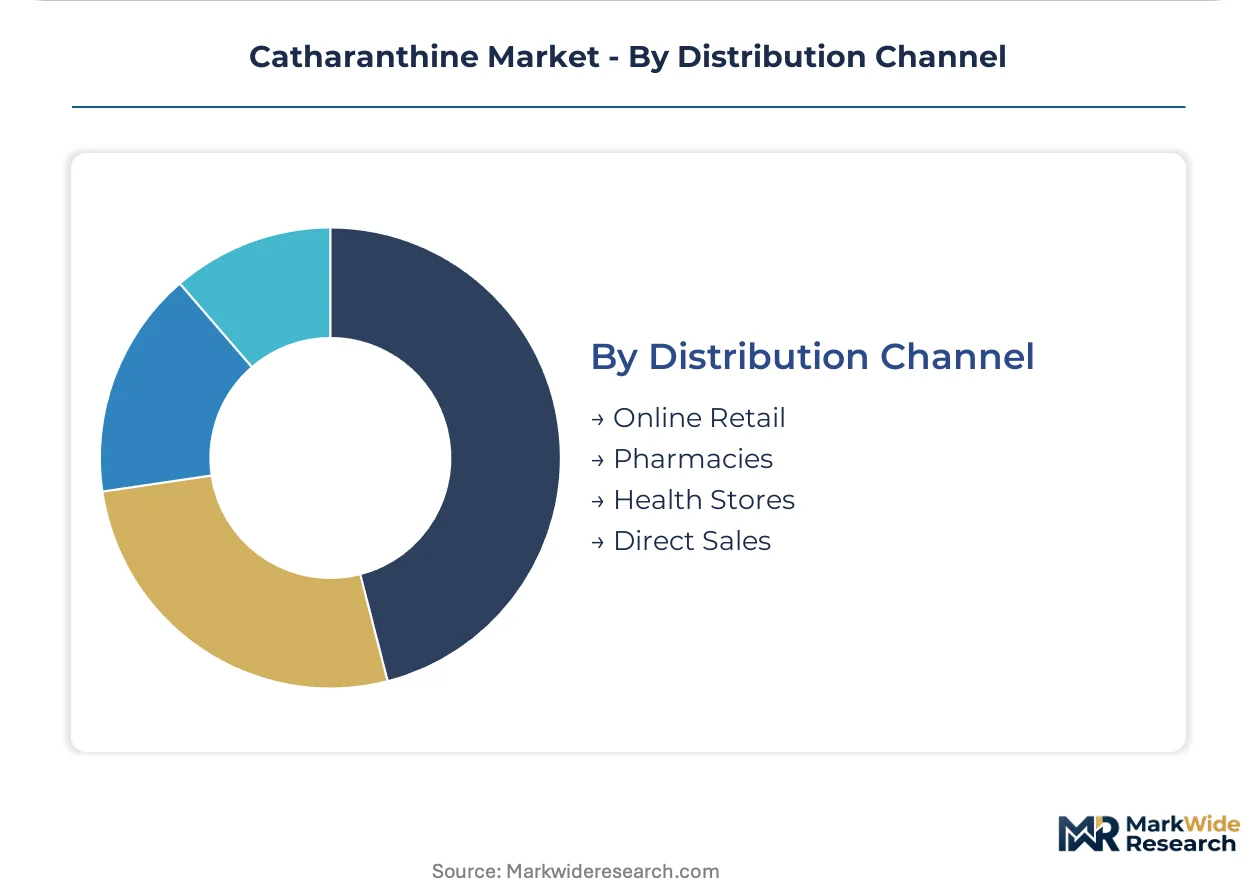
Distribution Channel:
Channel selection reflects buyer sophistication, urgency requirements, and regulatory compliance needs.
- Direct Sales:Long-term offtake agreements between pharmaceutical manufacturers and botanical processors bypass intermediaries for commercial-scale catharanthine procurement. Tier-one oncology API producers in the United States and Germany favor this channel for supply security.
- Pharmacies:Hospital and clinical pharmacies handle specialized alkaloid preparations through regulated compounding supply chains.
- Online Retail:Research-grade material and reference standards flow through specialized chemical supply platforms serving academic and industrial R&D buyers.
- Health Stores:Limited presence for catharanthine-specific products; broader Catharanthus roseus supplements appear in botanical retail channels.
Direct sales dominates commercial volume; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting catharanthine purification investment toward jurisdictions where CDSCO pharmaceutical ingredient rules and PLI scheme incentives compress compliance costs relative to FDA and EMA documentation burdens. This cost-of-compliance gap is accelerating contract manufacturing migration to Indian chemical synthesis clusters while Madagascar retains wild-source botanical dominance.
United States
FDA Drug Master File requirements for active pharmaceutical ingredient qualification sustain demand for high-purity catharanthine among oncology API manufacturers. United States pharmaceutical chemical networks concentrate vincristine and vinblastine semisynthesis programs in New Jersey and Massachusetts manufacturing corridors. Tier-one producers are locking direct offtake agreements with botanical processors to bypass traditional alkaloid trading intermediaries.
China
NMPA traceability mandates for traditional medicine ingredients are reshaping sourcing relationships for Catharanthus roseus extract suppliers. Yangtze River Delta chemical processing clusters host chromatography-capable manufacturers serving both domestic pharmaceutical networks and export markets. Genomic authentication and isotopic sourcing verification systems are becoming mandatory for commercial pharmaceutical qualification.
Germany
EMA Active Substance Master File harmonization is accelerating pharmaceutical-grade catharanthine qualification timelines across European manufacturing networks. Baden-Württemberg and North Rhine-Westphalia host specialized alkaloid extraction capabilities anchoring North American supply relationships. German oncology API producers are consolidating supplier relationships toward vertically integrated botanical processors with captive cultivation operations.
India
CDSCO pharmaceutical ingredient regulations and PLI scheme incentives are positioning Indian chemical synthesis clusters as alternative catharanthine purification hubs. Maharashtra and Gujarat contract manufacturers are adopting simulated moving bed chromatography to achieve pharmaceutical-grade purity without capital-intensive batch infrastructure. This technical adoption is opening commercial qualification pathways for suppliers previously confined to research-grade material.
Madagascar
Wild Catharanthus roseus sourcing from southwestern Madagascar growing zones supplies over sixty percent of global botanical raw material. Export licensing disruptions and climate volatility expose concentrated supply risk for pharmaceutical-grade catharanthine producers. Local processors are deploying blockchain source traceability systems to satisfy NMPA-mandated chain-of-custody documentation requirements.
Catharanthine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with research-grade catalog distributors occupying distinct positioning from commercial-scale botanical processors. The vendor base concentrates among chromatography-capable manufacturers in three countries as FDA and EMA purity documentation requirements force smaller botanical extractors out of commercial qualification. Three strategic archetypes dominate: catalog-breadth research chemical suppliers, specialized alkaloid extraction specialists, and cost-efficient subtropical botanical processors. Competitive moves center on long-term offtake contracting and purification technology licensing rather than horizontal consolidation.
Within the research-grade tier, AK Scientific leverages catalog breadth to serve academic and industrial R&D buyers with high-purity reference standards. Cayman Chemical Company anchors North American supply through specialized alkaloid extraction capabilities. Hainan Yueyang Biotech occupies a position exemplifying cost-efficient botanical sourcing from subtropical cultivation zones. These three represent the dominant geographic and functional archetypes structuring competitive positioning.
| Leading Market Players |
|---|
| AK Scientific |
| Cayman Chemical Company |
| Stanford Chemicals |
| BioVision Inc. |
| Enzo Biochem |
| Hainan Yueyang Biotech |
| Abcam |
| ChemFaces |
| Selleck Chemicals |
| Others |
Value Chain & Pricing Dynamics
Chromatographic solvent costs cascade through catharanthine pricing tiers as acetonitrile and high-purity ethanol volatility compresses margins for producers maintaining FDA-mandated purity thresholds above 98 percent. Pharmaceutical manufacturers absorbing these input costs through long-term offtake contracts create pricing stratification between qualified suppliers and research-grade botanical extractors.
Pricing Analysis
Distributor margins compress as tier-one oncology API producers lock direct procurement agreements with Madagascar and Indian botanical processors. Three-tier pricing structure across pharmaceutical-grade, research-grade, and nutraceutical-grade levels reflects certification burden differentiation, with FDA Drug Master File documentation commanding substantial premia. Cost compression in research-grade tiers is intensifying because smaller botanical extractors face EMA purity documentation barriers. Nutraceutical formulators exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States and German pharmaceutical manufacturers mandate multi-supplier qualification across Madagascar wild-source operations and Indian contract manufacturing clusters. Raw material flows draw from southwestern Madagascar Catharanthus roseus growing zones, Yangtze River Delta chromatography equipment, and Maharashtra simulated moving bed chromatography adoption. Single-source vulnerability concentrates in Madagascar wild cultivation exposing over sixty percent of global botanical feedstock to climate volatility and export licensing disruptions. Distribution runs through direct sales channels for commercial volumes and specialized chemical supply platforms for research-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catharanthine procurement is shifting toward premium specifications as FDA and EMA tighten active pharmaceutical ingredient purity documentation, favoring suppliers with chromatography-capable infrastructure and captive cultivation control.
For Market Incumbents: Anticipate biosynthetic alkaloid substitution threats by deepening backward integration into controlled-environment Catharanthus roseus cultivation and securing genomic authentication capabilities ahead of NMPA traceability mandate expansion. Lock three-to-five-year offtake agreements with tier-one oncology API producers to defend against emerging Indian contract manufacturers adopting continuous processing technologies.
For New Entrants and Emerging Players: Launch via online retail channels serving research institutions with certified reference materials, exploiting lower regulatory barriers compared to pharmaceutical-grade qualification. Target nutraceutical cellular health positioning in German and United States premium supplement markets where botanical provenance commands pricing power absent FDA Drug Master File burdens.
For Investors and Strategic Acquirers: Consolidation pressure builds where chromatography-capable manufacturers face retiring alkaloid chemist expertise and escalating multi-jurisdiction master file synchronization costs. Position for five-to-ten-year viability around vertically integrated botanical processors with Madagascar cultivation assets and Indian purification capacity. Watch microbial fermentation route advancement in academic and industrial biotechnology programs as inflection indicator threatening long-term botanical extraction demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Madagascar captive growing operations satisfy NMPA blockchain traceability mandates for pharmaceutical qualification. |
| Continuous Processing Adoption | Simulated moving bed chromatography deployment in Indian chemical synthesis clusters reduces per-batch purification costs. |
| Long-term Supply Agreement | Direct offtake contracting with United States oncology API producers bypasses traditional alkaloid trading intermediaries. |
| Regulatory Certification Investment | Parallel FDA Drug Master File and EMA Active Substance Master File qualification opens commercial pharmaceutical pathways. |
| Digital Provenance System Deployment | Blockchain source traceability from Madagascar cultivation to final extract creates first-mover advantage under NMPA mandates. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with drug development executives, regulatory affairs leads at alkaloid extraction specialists, botanical procurement managers, and chromatography equipment technical directors. Secondary validation draws from FDA Drug Master File submissions, EMA Active Substance Master File guidelines, NMPA traditional medicine ingredient regulations, and CDSCO pharmaceutical ingredient filings. Bottom-up demand modeling across end-use segments triangulates against top-down supply-side capacity assessments.
Granularity-level modeling disaggregates volume and value outputs by product format, application sector, end-user type, and distribution channel across the analysis window. Segmentation dimensions include pharmaceutical grade tier, nutraceutical positioning, research versus commercial procurement scale, and regional regulatory cluster. CAGRs derive from trend extrapolation of purification technology adoption rates, regulatory qualification timeline compression, and substitution threat progression from biosynthetic routes. Industry-specific forecast inputs incorporate chromatographic solvent cost indices and Madagascar export licensing volatility patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated microbial fermentation breakthrough or Madagascar climate disruption scenarios. Deviation in EMA pharmacopeial monograph revision timing or NMPA traceability mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Europe Malic Acid Market