
 Silicone Gel Market | 2026-2036
Silicone Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Gel Market Analysis
The silicone gel market is consolidating around a widening gap between premium medical-grade formulations and commodity industrial supplies. Momentive Performance Materials leverages its vertical integration in siloxane chemistry to sustain pricing power at the high end. Dow Corning Corporation anchors North American supply chains for healthcare applications, while Shin-Etsu Chemical Co., Ltd. dominates Asian electronics-grade production with proprietary polymerization technology.
Silicone gel consists of cross-linked polydimethylsiloxane networks with tunable viscosity ranging from soft tissue mimics to structural encapsulants, manufactured through platinum-catalyzed hydrosilylation or condensation curing. Medical grade formulations command the deepest margin pools due to ISO 10993 biocompatibility certification burdens and extended validation timelines. Industrial grade segments compete on volume scale in sealant and mold-making applications where performance tolerances permit broader formulation flexibility.
FDA 21 CFR Part 177.2600 compliance, EU MDR Class III device requirements, and REACH SVHC restrictions on residual platinum catalysts collectively elevate barriers for new entrants. Manufacturers must navigate divergent regional testing protocols to maintain multi-jurisdictional market access. Stakeholders should monitor evolving biocompatibility standards and catalyst purity thresholds as decisive variables for portfolio allocation and capital deployment timing.
Market Dynamics
Platinum catalyst purity thresholds under REACH SVHC restrictions and FDA biocompatibility protocols are compressing supplier margins while concentrating procurement among ISO 10993-certified manufacturers. This regulatory tightening is forcing capital reallocation toward validation infrastructure and captive siloxane production.
Growth Catalysts
- Wound Care Device Expansion:Chronic wound management protocols in Germany and Japan are accelerating demand for soft-tissue-mimic silicone gel formulations in negative-pressure wound therapy systems.
- EU MDR Class III Requirements:Stricter material traceability mandates for implantable devices are locking in long-term supply contracts with certified gel producers who maintain batch-level documentation.
- Platinum-Catalyzed Hydrosilylation:Advances in low-residual catalyst curing chemistry are enabling thinner, more conformable gel layers for transdermal drug delivery patches.
Market Restraints
- Siloxane Feedstock Concentration:Merchant siloxane supply concentrates among three Asian chemical conglomerates, exposing formulators to D4/D5 cyclic volatility and force majeure risk.
- ISO 10993-5 Cytotoxicity Testing Burden:Extended validation timelines for new gel formulations stretch 18-24 months, freezing formulation innovation cycles for mid-tier producers.
- Polyurethane Encapsulant Substitution:Lower-cost thermal potting compounds are displacing silicone gel in non-medical electronics applications where biocompatibility is not required.
Strategic Opportunities
- Indian Medical Device Manufacturing:CDSCO's phased alignment with ISO 13485 and PLI scheme incentives for domestic production are opening procurement channels for imported medical-grade gel.
- Convergence of Antimicrobial Additives:Integration of silver-ion or quaternary ammonium compounds into gel matrices is creating premium pricing tiers for infection-resistant wound dressings.
- Direct Hospital Procurement Platforms:Group purchasing organizations in the US are consolidating silicone gel buying for catheter and drain systems, bypassing traditional distributor markups.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in platinum catalyst inhibition kinetics and rheology tuning for medical applications commands premium compensation and limits R&D throughput.
- Cleanroom Capacity Constraints:ISO 7-certified gel compounding suites require seven-figure capital deployment with 4-5 year depreciation horizons, constraining capacity expansion.
- Legacy Molding Equipment Retrofit Complexity:Transitioning industrial sealant production lines to medical-grade gel output demands complete decontamination and validation protocols that idle assets for months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Gel Market |
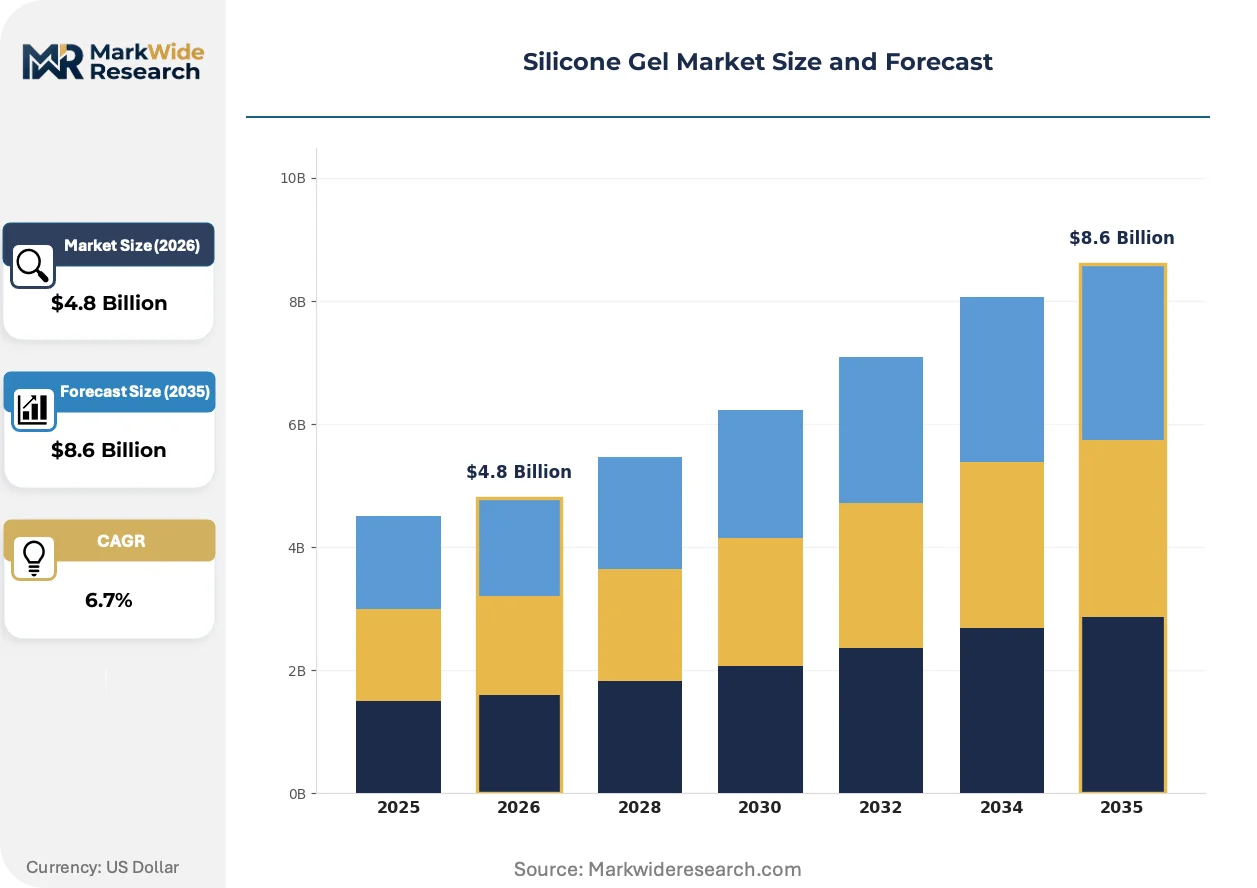
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Grade, Industrial Grade, Cosmetic Grade, Food Grade Application: Wound Healing, Drug Delivery, Sealants, Mold Making Form: Liquid, Gel, Foam, Sheet End User: Hospitals, Clinics, Manufacturing, Cosmetic Industry |
| Companies Covered | Momentive Performance Materials Inc., ACC Silicones Ltd., Dow Corning Corporation, Bluestar Silicones, NuSil Technology LLC, Shin-Etsu Chemical Co., Ltd., Elkem Silicones, KCC Corporation, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Gel Market Emerging Trajectories
Digital twin modeling of gel curing kinetics and real-time viscosity monitoring are compressing development cycles while enabling mass customization. These tools are redistributing competitive advantage toward data-capable formulators.
Additive manufacturing of patient-specific wound dressings is decentralizing silicone gel deposition from centralized molding facilities to point-of-care 3D printing stations. Hospital systems in the Netherlands and South Korea are piloting bedside gel extrusion for burn and pressure ulcer management. This distributed production model is compressing inventory carrying costs while demanding shelf-stable, UV-curable gel chemistries with extended pot life.
REACH restrictions on residual platinum catalysts in consumer-facing applications are forcing reformulation toward condensation-cure systems or platinum scavenger technologies. German chemical regulators are tightening enforcement through 2025, pushing gel producers to validate alternative curing chemistries for skin-contact devices. Electronics-grade segments remain less affected, maintaining hydrosilylation dominance where catalyst residues pose no exposure risk.
Buyer consolidation among US hospital networks is compressing silicone gel supplier rosters from multi-source to dual-source or sole-source arrangements. Procurement teams are unbundling technical service from material supply, negotiating standalone validation support contracts. This pattern is most visible in cardiovascular device supply chains, where original equipment manufacturers face direct pressure from consolidated health systems to absorb regulatory documentation costs.
Silicone Gel Market Segmentation
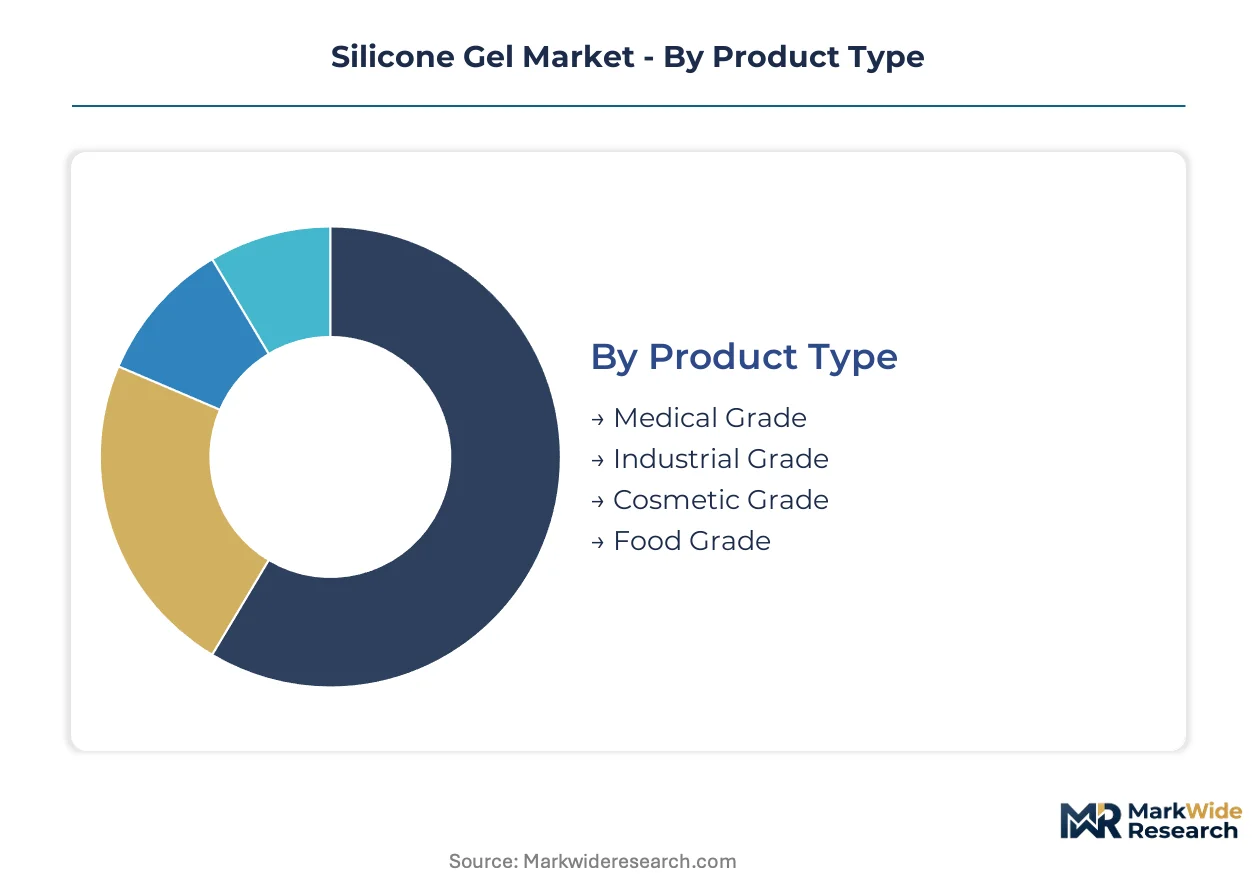
Silicone gel segmentation reflects a fundamental divergence between biocompatibility-certified medical formulations and volume-driven industrial supplies. Product grade distinctions determine pricing power, regulatory burden, and customer switching costs across every downstream application.
Product Type:
Volume concentrates in industrial formulations, while margin pools deepen in certified medical grades that command extended validation timelines.
- Medical Grade:Cross-linked polydimethylsiloxane networks meeting ISO 10993 biocompatibility protocols with platinum-catalyzed hydrosilylation curing. German precision medical manufacturers in Tuttlingen and Freiburg drive procurement for implantable device encapsulation and soft-tissue prosthetics under EU MDR Class III traceability mandates.
- Industrial Grade:Lower-viscosity formulations optimized for thermal stability and electrical insulation in non-biomedical environments. Electronics manufacturers in South Korea and Taiwan absorb volume for LED encapsulation and potting applications where REACH SVHC catalyst restrictions pose minimal compliance burden.
- Cosmetic Grade:Ultra-low residual platinum formulations for topical skin-contact applications in personal care products.
- Food Grade:FDA 21 CFR Part 177.2600 compliant gels for baking molds and food processing equipment seals.
Today's leader: Medical Grade. Tomorrow's challenger: Cosmetic Grade.
Application:
End-use demand fragments across acute care protocols, chronic disease management, and non-medical manufacturing processes with divergent performance specifications.
- Wound Healing:Soft-tissue-mimic gels with tunable viscosity for negative-pressure wound therapy systems. Japanese chronic wound management protocols and German hospital procurement standards are accelerating formulation development for pressure ulcer and burn treatment devices.
- Drug Delivery:Thin, conformable gel matrices enabling transdermal patch architectures with controlled release kinetics. Advances in low-residual catalyst curing chemistry are expanding addressable therapeutic categories in the US and European markets.
- Sealants:High-durometer formulations for automotive and aerospace gasket applications requiring thermal cycling resistance.
- Mold Making:Room-temperature vulcanizing compounds for industrial prototyping and art casting where biocompatibility certification adds unnecessary cost.
Drug Delivery is climbing the fastest as transdermal therapeutic categories expand. Wound Healing holds the deepest incumbent position.
Form:
Physical state determines processing equipment requirements and point-of-care deployment flexibility.
- Liquid:Low-viscosity precursors for injection molding and automated dispensing systems in high-volume manufacturing environments.
- Gel:Cross-linked networks with thixotropic behavior for manual application and conformable medical device interfaces.
- Foam:Cellular structures for cushioning and vibration damping in prosthetic and industrial applications.
- Sheet:Pre-cured planar formats for wound dressing lamination and die-cutting into device components.
Sheet formats are gaining share fastest through hospital point-of-care deployment. Liquid precursors retain volume dominance in centralized manufacturing.
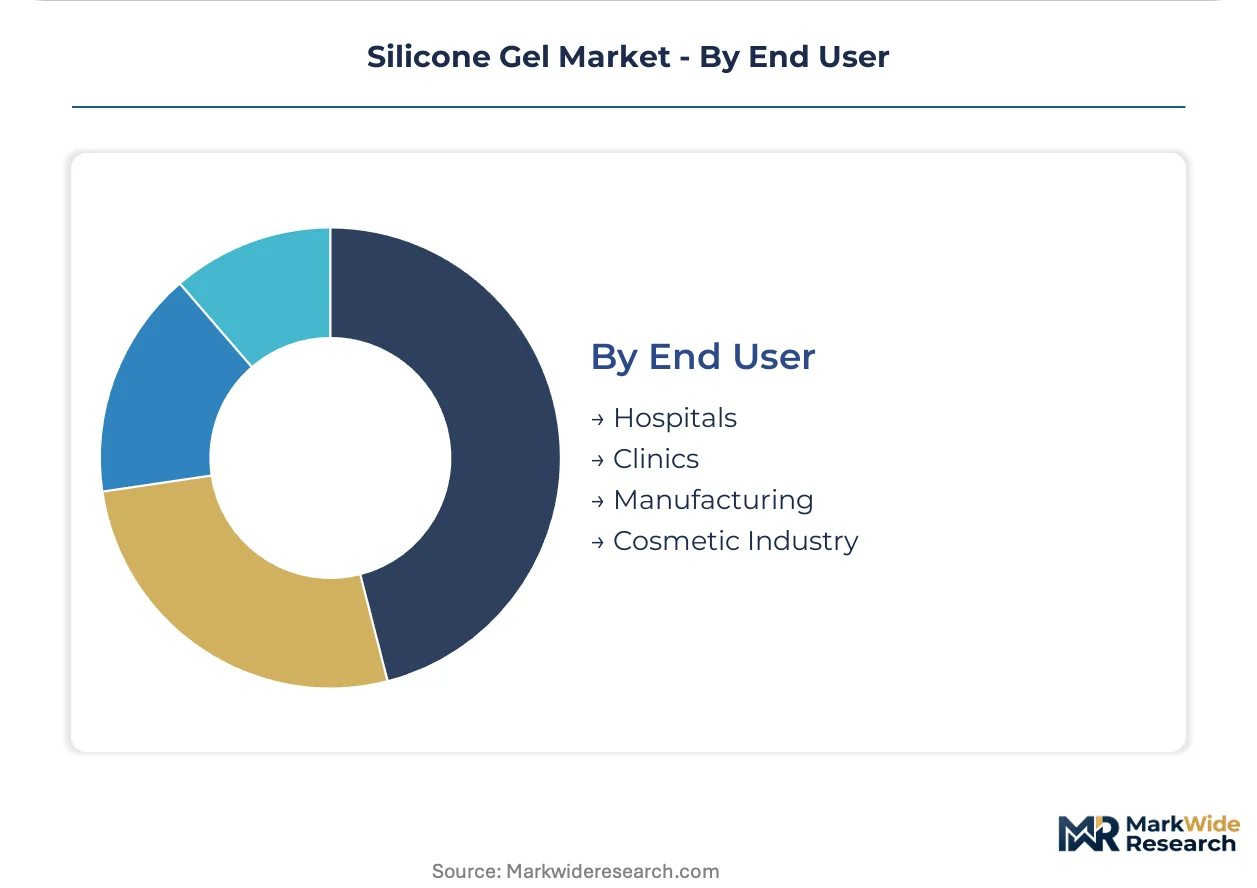
End User:
Customer concentration patterns separate institutional procurement with validation requirements from industrial buyers competing on unit economics.
- Hospitals:Consolidated US health systems and Dutch hospital networks are driving direct procurement platform adoption. Group purchasing organizations are unbundling technical service contracts from material supply for catheter and drain system gel components.
- Clinics:Outpatient wound care centers in Japan and specialized burn units in South Korea piloting bedside 3D printing for patient-specific gel deposition.
- Manufacturing:Electronics assemblers and automotive suppliers procuring industrial-grade formulations on volume contracts with minimal regulatory documentation.
- Cosmetic Industry:Personal care formulators seeking ultra-low residual platinum grades for topical applications facing tightening German chemical enforcement.
Hospitals command the steepest pricing tiers through validation bundling. Manufacturing represents the largest volume absorption with thinnest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulation chemists and Japanese polymer scientists anchor the highest-value segments of silicone gel supply chains. Their concentration in precision medical manufacturing clusters creates persistent talent scarcity that shapes regional procurement patterns.
Germany
Tuttlingen and Freiburg medical device clusters drive demand for EU MDR Class III certified gels in implantable encapsulation. ECHA's REACH SVHC enforcement on residual platinum catalysts tightens through 2025. Baden-Württemberg precision manufacturers are locking in long-term supply contracts with batch-level documentation capabilities.
United States
Consolidated hospital networks in the Midwest and Southeast are unbundling technical service contracts from material supply for catheter systems. FDA 21 CFR Part 177.2600 compliance burdens favor established ISO 10993-certified suppliers. Greater Boston's medical technology corridor is piloting direct procurement platforms for silicone gel components.
Japan
Chronic wound management protocols in Tokyo and Osaka are accelerating soft-tissue-mimic gel formulations for negative-pressure therapy. METI guidance on medical device material traceability aligns with international standards. Nagoya-area electronics assemblers absorb industrial-grade volumes for LED encapsulation.
South Korea
Busan-Ulsan electronics manufacturers procure industrial-grade gels for thermal potting applications with minimal biocompatibility requirements. MFDS alignment with ISO 13485 opens procurement channels for imported medical-grade formulations. Seoul Capital Area hospital networks are piloting bedside 3D printing for patient-specific wound dressings.
India
CDSCO's phased ISO 13485 alignment and PLI scheme incentives are opening channels for imported medical-grade gel in Maharashtra and Gujarat. Domestic medical device manufacturing clusters in Karnataka and Tamil Nadu are expanding procurement of certified formulations. Delhi-NCR distributors are consolidating supplier relationships for catheter and drain system components.
Silicone Gel Market Vendor Landscape
Top-tier vendors anchor medical-grade certification tiers, while commodity industrial suppliers compete on siloxane feedstock access and volume scale. The vendor base stratifies across three archetypes: integrated siloxane producers with captive polymerization capabilities, specialized medical-grade formulators with ISO 10993 validation infrastructure, and regional industrial compounders serving electronics and automotive sealant demand. Consolidation pressures favor backward integration into siloxane production and multi-jurisdictional regulatory certification investments.
Among integrated chemical conglomerates, Momentive Performance Materials Inc., Dow Corning Corporation, and Shin-Etsu Chemical Co., Ltd. occupy positions representing distinct geographic and technological anchoring. Momentive exemplifies North American vertical integration in siloxane chemistry. Dow Corning represents the legacy healthcare supply chain concentration. Shin-Etsu anchors Asian electronics-grade production capabilities. These three sit within the premium-tier vector where platinum-catalyzed hydrosilylation expertise and REACH-compliant catalyst scavenging technology concentrate.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| ACC Silicones Ltd. |
| Dow Corning Corporation |
| Bluestar Silicones |
| NuSil Technology LLC |
| Shin-Etsu Chemical Co., Ltd. |
| Elkem Silicones |
| KCC Corporation |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with platinum catalyst expertise in Baden-Württemberg command compensation premiums that widen spreads between medical-grade and industrial-grade silicone gel tiers. Labor-cost differentials between ISO 10993-certified specialists and commodity compounders translate directly into pricing stratification across wound care and electronics applications.
Pricing Analysis
Bundled technical service contracts are unbundling as US hospital group purchasing organizations separate validation support from material supply. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification burden, platinum catalyst purity thresholds, and volume scale. Pricing pressure stems from polyurethane encapsulant substitution in non-medical electronics where biocompatibility certification adds unnecessary cost. Manufacturing buyers exhibit highest price sensitivity; cardiovascular device OEMs absorb premium tiers through sole-source arrangements.
Supply Chain Analysis
Dual-sourcing requirements from EU MDR Class III device manufacturers mandate multi-supplier qualification for implantable gel components. Siloxane feedstock concentrates in Germany, Japan, and South Korea, exposing formulators to D4/D5 cyclic volatility. Merchant supply of platinum catalysts and specialized siloxane monomers rests on Asian chemical conglomerates with force majeure exposure. Distribution runs through authorized distributors for medical grades and direct procurement platforms for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone gel market represents a late-cycle quality story as chronic wound management protocols in Germany and Japan shift procurement toward premium soft-tissue-mimic formulations with extended validation documentation.
For Market Incumbents: Deepen backward integration into captive siloxane production to defend margin position against merchant feedstock volatility. Lock in long-term supply contracts with batch-level documentation capabilities to satisfy EU MDR Class III traceability mandates. Expand ISO 7-certified cleanroom capacity in Tuttlingen and Freiburg clusters before formulation chemist scarcity constrains R&D throughput. For New Entrants and Emerging Players: Direct hospital procurement platforms offer the lowest-friction entry path for imported medical-grade gel in India's Maharashtra and Gujarat clusters. Target CDSCO-aligned domestic manufacturers seeking ISO 13485-certified formulations under PLI scheme incentives. Pilot UV-curable gel chemistries with extended pot life for South Korean bedside 3D printing deployments. For Investors and Strategic Acquirers: Medical device OEMs with catheter and drain system portfolios are the most active acquirer in this space, seeking captive gel formulation capabilities. Five-to-ten-year viability hinges on platinum scavenger technology validation for REACH-compliant skin-contact applications. Monitor ECHA enforcement intensity on residual catalyst thresholds as the decisive inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Production | Captive feedstock supply insulates Momentive and Dow Corning from D4/D5 cyclic volatility. |
| ISO 10993-5 Cytotoxicity Certification Investment | Extended validation timelines create switching costs that lock in cardiovascular device supply chains. |
| Platinum Scavenger Technology Development | REACH SVHC compliance enables continued hydrosilylation dominance in German skin-contact applications. |
| Hospital Group Purchasing Organization Partnership | Direct procurement platform access bypasses distributor markups in consolidated US health systems. |
| Bedside 3D Printing Gel Chemistry Pilot | UV-curable formulations with extended pot life address Netherlands and South Korean point-of-care demand. |
Methodological Framework
Direct dialogue with silicone gel formulation chemists, medical device procurement managers at German precision manufacturers, CDSCO regulatory affairs leads, and GPO contracts managers grounded qualitative findings. Secondary validation drew from ECHA REACH SVHC candidate lists, FDA 21 CFR Part 177.2600 compliance databases, EU MDR technical documentation requirements, and SEC filings from integrated siloxane producers. Bottom-up demand modeling across wound care, drug delivery, and electronics applications triangulated against top-down chemical industry production data.
Bottom-up volume estimates aggregated application-level consumption across the projection horizon, while top-down analysis anchored total addressable market sizing in siloxane industry output reports. Segmentation dimensions included product grade tier, end-use application, physical form factor, and customer concentration pattern. CAGRs derived from regression analysis of historical procurement volumes and regulatory-driven demand inflection points. Forecast inputs incorporated platinum catalyst purity threshold evolution and hospital network consolidation trajectories.
The model assumes a particular technology adoption path; alternative pathways for condensation-cure chemistry or UV-initiated polymerization would alter the outlook for hydrosilylation-dominant suppliers. Deviation in ECHA enforcement intensity or FDA biocompatibility protocol revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Halloysite Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Global PE Films Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market