
 Silicone Derivative Market | 2026-2036
Silicone Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Derivative Market Outlook
Aftermarket service revenue for silicone formulation troubleshooting is tilting toward integrated suppliers with captive technical service teams. Dow Inc. leverages its global manufacturing footprint to sustain bulk silicone oil supply contracts with automotive Tier 1s. Shin-Etsu Chemical Co., Ltd. anchors high-purity electronic-grade silicone gel production for semiconductor packaging in East Asia. Wacker Chemie AG differentiates through specialty silicone resin formulations serving European construction refurbishment cycles.
Silicone derivatives encompass organosilicon compounds built on siloxane backbones with varying degrees of cross-linking, functional group substitution, and molecular weight, typically synthesized via hydrolysis of chlorosilanes or direct process routes using silicon metal and methyl chloride. These materials deliver thermal stability across −60°C to 250°C ranges, dielectric insulation, and biocompatibility for medical and industrial systems. Silicone rubbers occupy the largest volume position owing to gasket and sealant demand in transportation and energy infrastructure, while silicone gels represent the fastest-expanding category as power electronics and battery thermal management applications multiply. Silicone oils retain mature, high-margin positions in personal care and textile finishing where formulation specificity commands premium pricing.
EPA oversight of volatile organic compound emissions constrains solvent-based silicone processing in the United States, while REACH registration requirements in Europe elevate compliance costs for imported silicone intermediates. China's GB standards and MEE enforcement on chemical manufacturing emissions shape production location decisions for multinational silicone derivative suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation adaptation or supply chain regionalization delivers lower total compliance burden.
Market Dynamics
Electric vehicle thermal management requirements are compressing silicone gel qualification cycles from 18 months to under 9 months, forcing reformulation investments ahead of platform launches.
Growth Catalysts
- EV Battery Thermal Interface Materials:Silicone gels with thermal conductivity above 3.5 W/m·K penetrate new electric vehicle platforms as cell-to-pack architectures proliferate.
- REACH VOC Threshold Tightening:European ECHA enforcement pushes solvent-free silicone sealant adoption in automotive assembly lines.
- Semiconductor Packaging:High-purity electronic-grade silicones absorb volume as advanced packaging for AI accelerators expands wafer-level processing.
Market Restraints
- Methyl Chloride Feedstock Volatility:Natural gas price swings transmit directly to chlorosilane production economics, compressing margin predictability for silicone rubber compounders.
- Chinese Supply Concentration:Over 60% of fumed silica capacity clusters in Shandong and Jiangsu provinces, creating geographic single-point vulnerability.
- Acrylic Sealant Substitution:Construction applications below 150°C service temperature face displacement from lower-cost hybrid polymer alternatives in cost-sensitive housing markets.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme coverage for specialty chemicals attracts silicone derivative investments serving domestic electronics and automotive sectors.
- Medical Implant-Grade Silicones:ISO 10993 biocompatibility certification opens neurostimulator and long-term implantable device supply chains previously dominated by US and European compounders.
- Digital Distribution Platforms:Technical data sheet standardization enables direct procurement of silicone fluids by mid-sized textile finishers, bypassing traditional distributor markups.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Hydrolysis process expertise concentrates among retiring cohorts, constraining new plant commissioning timelines.
- Multijurisdictional Registration Burden:Separate REACH, EPA TSCA, and China MEE new chemical substance notifications extend product launch cycles by 14-22 months.
- Legacy Equipment Retrofit Complexity:Continuous reactor upgrades for reduced volatile organic compound emissions demand capital deployment without immediate throughput gains.
Report Scope
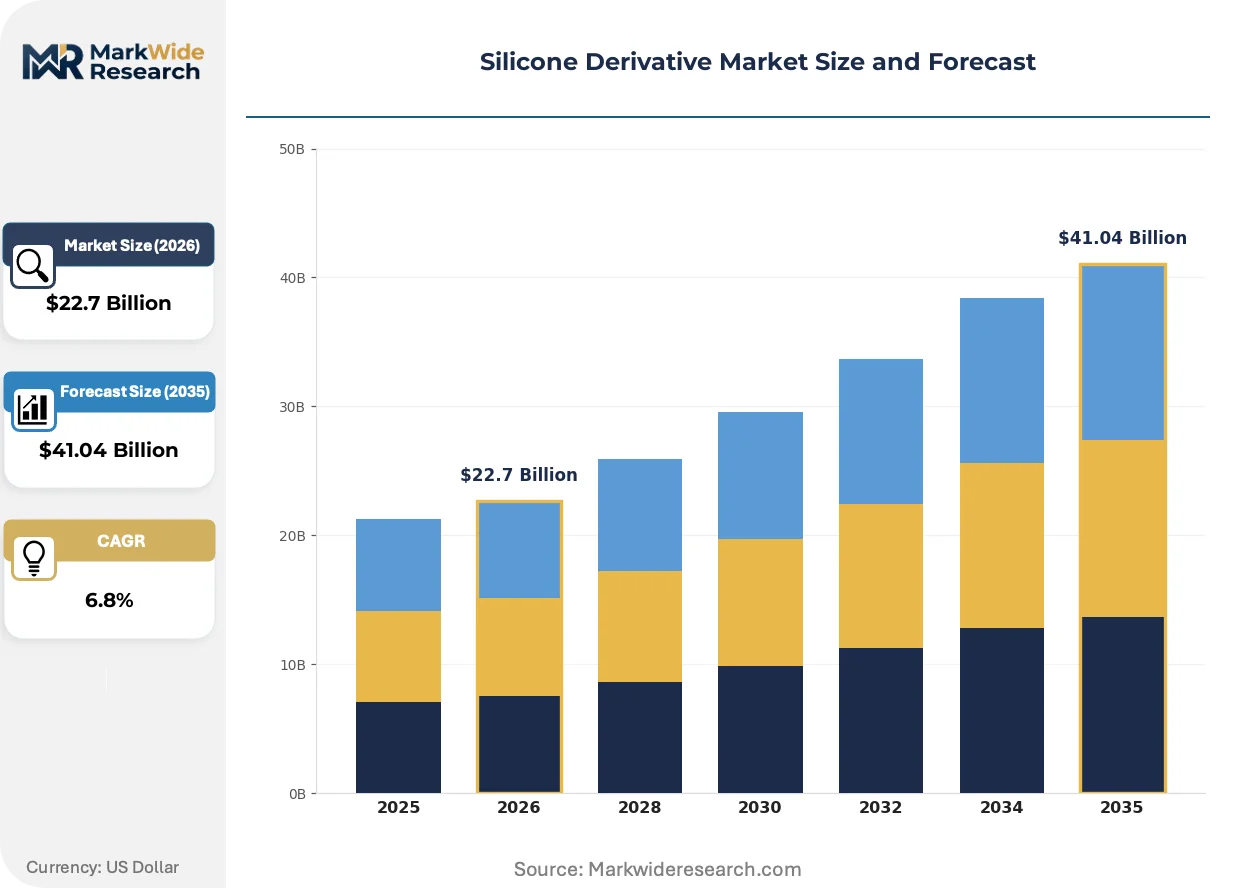
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Derivative Market |
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $41.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Oils, Silicone Resins, Silicone Gels, Silicone Rubbers Application: Personal Care, Construction, Electronics, Automotive End Use Industry: Healthcare, Textiles, Food Processing, Adhesives Form: Liquid, Solid, Paste, Aerosol |
| Companies Covered | Momentive Performance Materials Inc., Elkem ASA, Dow Inc., DuPont, KCC Corporation, Shin-Etsu Chemical Co., Ltd., Evonik Industries AG, Gelest Inc., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Derivative Market Strategic Shifts
Additive manufacturing of silicone lattice structures for cushioning and sealing applications is compressing tooling costs and enabling geometry complexity previously unattainable through compression molding.
Self-healing silicone elastomers incorporating dynamic covalent bond chemistry are rendering obsolete scheduled gasket replacement intervals in aerospace and heavy equipment maintenance programs. Boeing and Airbus specification writers now evaluate these materials for pressurized cabin seal applications where access for service is severely constrained. The technology compresses total cost of ownership calculations and shifts procurement criteria toward lifetime performance guarantees.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants at silicone monomer plants tightens monitoring and leak detection requirements. Facility operators invest in optical gas imaging and fence-line monitoring systems to demonstrate compliance. The regulatory pressure accelerates capital rotation toward newer continuous process designs with inherently lower fugitive emission profiles.
Specification authority is migrating from brand owners to contract manufacturers in personal care silicone fluid procurement. Toll compounders now dictate viscosity grade and volatile content requirements based on finished formulation performance, compressing the value capture of traditional fluid suppliers. This shift concentrates volume with integrated compounders capable of rapid lot matching and certificate of analysis standardization.
Silicone Derivative Market Segmentation
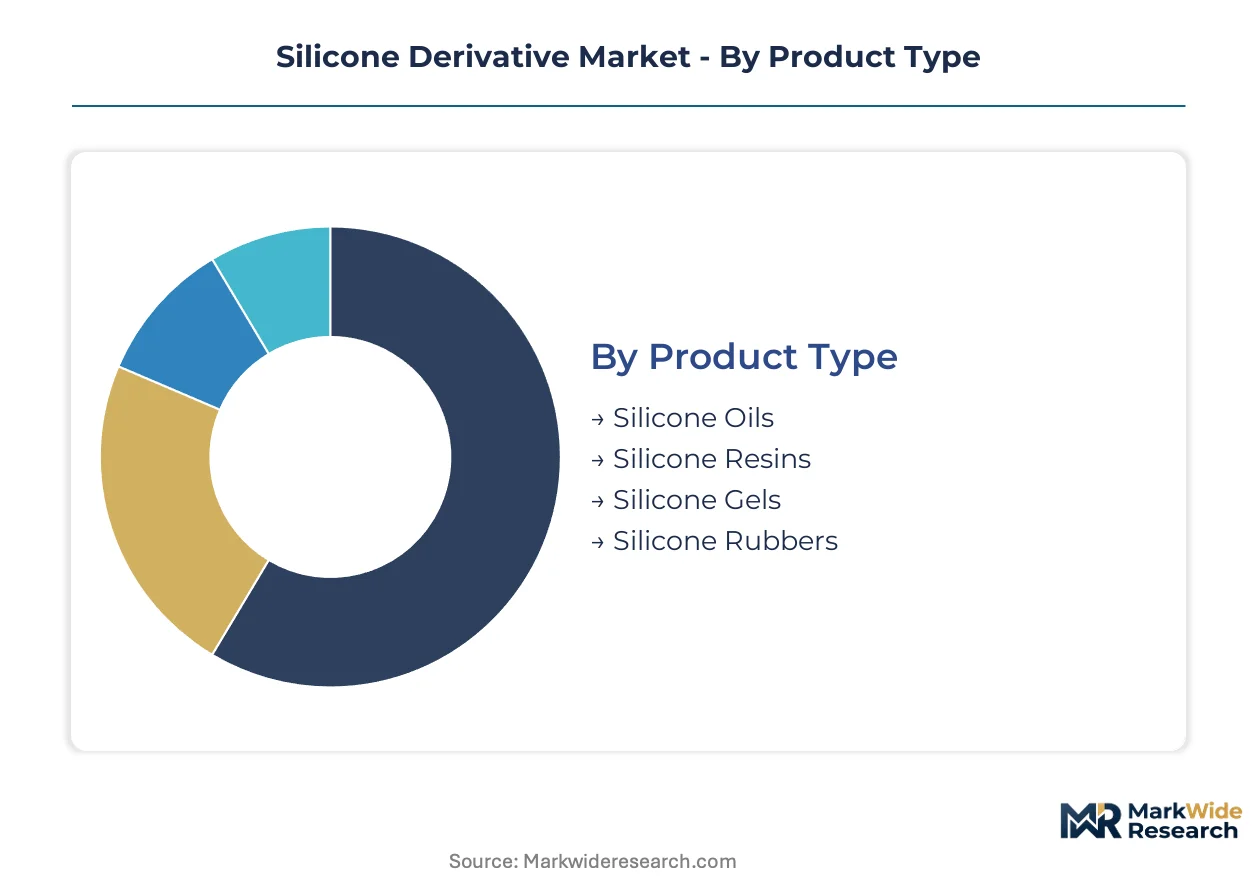
Silicone derivative demand fragments across functional chemistries, application temperatures, and regulatory exposure profiles. Each segmentation dimension carries distinct margin structures and qualification barriers that determine supplier positioning.
Product Type:
Volume concentration and margin profile vary sharply by molecular architecture and cross-link density.
- Silicone Rubbers:Cross-linked elastomers with methyl and vinyl substituents deliver compression set resistance from −60°C to 230°C. Automotive sealing and energy infrastructure gaskets in Germany and Japan absorb the largest production volumes, constrained by methyl chloride feedstock cost volatility.
- Silicone Gels:Low-modulus, lightly cross-linked networks with tunable dielectric properties enable conformal thermal interface layers. Power electronics packaging in South Korea and battery module assemblies in China are compressing qualification cycles below nine months.
- Silicone Oils:Linear polydimethylsiloxane fluids with viscosity grades from 0.65 to 1,000,000 cSt serve personal care and textile finishing formulations.
- Silicone Resins:Highly cross-linked three-dimensional siloxane networks provide thermal stability and weather resistance for construction coatings.
Silicone rubbers hold installed capacity. Silicone gels are rotating up the share rankings.
Application:
End-use thermal and regulatory requirements dictate formulation complexity and pricing power.
- Automotive:EV battery thermal management and sealant applications demand flame-retardant grades meeting UL 94 V-0 specifications. European assembly lines under ECHA REACH VOC tightening are converting to solvent-free curing systems.
- Electronics:Semiconductor packaging and AI accelerator substrates require sub-ppm ionic purity. Wafer-level processing expansion in Taiwan and Japan is absorbing high-purity electronic-grade volumes.
- Construction:Structural glazing and weatherproofing sealants compete with hybrid polymer alternatives in cost-sensitive housing markets.
- Personal Care:Volatile silicone fluids and conditioning agents face specification authority migration toward toll compounders.
Automotive commands formulation R&D investment. Electronics is climbing the fastest on margin contribution.
End Use Industry:
Certification requirements and contract duration separate premium-grade from commodity supply tiers.
- Healthcare:Implantable device grades require ISO 10993 biocompatibility and long-term stability data. Neurostimulator and drug delivery device manufacturers in Switzerland and the United States maintain qualified supplier lists with 18-36 month onboarding.
- Adhesives:Pressure-sensitive and structural bonding formulations leverage silicone tackifiers and release coatings. Industrial tape manufacturers in Italy and industrial assembly operations in Mexico specify peel adhesion and thermal aging performance.
- Textiles:Fiber lubricants and fabric softeners utilize amino-functional silicone emulsions with defined particle size distribution.
- Food Processing:FDA 21 CFR 177.2600 compliant grades for baking equipment and conveyor belts require extractables testing and lot traceability.
Healthcare holds qualification barriers. Adhesives is expanding most quickly on volume uptake.
Form:
Physical state determines processing equipment compatibility and logistics economics.
- Liquid:Pumpable fluids and dispersions enable automated metering and spray application. Bulk tanker deliveries to textile finishers in India and automotive Tier 1s in the United States minimize packaging cost.
- Solid:Gum rubber and resin pellets require compounding equipment for dispersion into host matrices. Masterbatch producers in Thailand and compounders in Turkey control intermediate value capture.
- Paste:Thixotropic sealants and thermal greases suit manual and robotic dispensing in electronics assembly.
- Aerosol:Sprayable mold release and lubricant formulations face EPA NESHAP compliance costs for propellant handling.
Liquid holds logistics efficiency. Solid is gaining share fastest on regional compounding investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs silicone rubber derivatives at volumes unmatched elsewhere, while Germany and Japan concentrate on high-purity electronic grades. The United States splits demand between automotive sealants and healthcare biocompatibility applications. This consumption-mix differential shapes supplier investment priorities across manufacturing footprints.
China
Electric vehicle battery thermal management and semiconductor packaging drive silicone gel consumption in Jiangsu and Shandong provinces. MEE enforcement on chemical manufacturing emissions forces continuous reactor upgrades at monomer plants. The Yangtze River Delta cluster concentrates fumed silica capacity serving both domestic formulation houses and export markets.
Germany
Automotive OEM assembly lines in Bavaria and Baden-Württemberg convert to solvent-free silicone sealants under ECHA REACH VOC tightening. The KBA maintains type-approval authority over gasket materials in commercial vehicle platforms. Industrial compounding operations in North Rhine-Westphalia supply construction refurbishment cycles across Central Europe.
United States
EPA NESHAP compliance costs at silicone monomer plants accelerate capital rotation toward continuous process designs in Texas and Louisiana. FDA 21 CFR 177.2600 extractables testing requirements govern food-contact grades for baking equipment manufacturers. The Southeast automotive corridor absorbs flame-retardant thermal interface materials for EV platform launches.
Japan
Wafer-level processing expansion in Kyushu and Chubu absorbs high-purity electronic-grade silicones for AI accelerator packaging. METI industrial policy directs domestic supply chain security investments in organosilicon intermediate production. Shin-Etsu Chemical anchors semiconductor gel manufacturing in East Asia with qualification protocols exceeding 18 months.
South Korea
Power electronics packaging in Gyeonggi Province compresses silicone gel qualification cycles below nine months for battery module assemblies. MFDS medical device regulations open neurostimulator supply chains to implantable-grade compounders. The Busan-Ulsan petrochemical complex hosts downstream formulation operations serving ASEAN export markets.
Silicone Derivative Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three to five integrated multinationals commanding bulk intermediate supply, alongside regional compounders capturing formulation-specific value. Strategic archetypes include captive feedstock operators, specialty resin formulators, and toll compounding services. Dominant competitive moves encompass backward integration into chlorosilane production and geographic expansion into Indian PLI-subsidized manufacturing zones.
Within the integrated multinational tier, Dow Inc. and Shin-Etsu Chemical Co., Ltd. exemplify divergent geographic anchoring strategies. Dow leverages North American petrochemical integration for automotive Tier 1 supply contracts. Shin-Etsu occupies a position in East Asian electronic-grade purity standards. Wacker Chemie AG represents the European specialty resin formulator archetype, with differentiation through construction refurbishment cycle alignment. These three anchors illustrate how feedstock access, regulatory proximity, and end-use qualification barriers stratify competitive positioning.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| Elkem ASA |
| Dow Inc. |
| DuPont |
| KCC Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Evonik Industries AG |
| Gelest Inc. |
| Wacker Chemie AG |
| Others |
Value Chain & Pricing Dynamics
Fumed silica capacity clustering in Shandong and Jiangsu provinces anchors margin capture at the formulation stage, where automotive Tier 1s and electronics assemblers negotiate thermal gel and sealant supply. Methyl chloride feedstock volatility transmits directly from natural gas benchmarks to chlorosilane production economics, compressing compounder margins and forcing contract restructuring.
Pricing Analysis
Long-term offtake agreements dominate silicone rubber supply to German automotive OEMs, while spot purchasing prevails in Indian textile finishing applications. Price differentiation rests on ISO 10993 biocompatibility certification for healthcare grades and UL 94 V-0 flame retardancy for EV battery thermal materials. Cost compression in construction sealants is intensifying as hybrid polymer substitutes gain specification share. Personal care toll compounders exhibit highest price sensitivity, whereas semiconductor packaging buyers prioritize ionic purity over unit cost.
Supply Chain Analysis
Export-control regimes on advanced semiconductor packaging materials constrain high-purity silicone gel flows between East Asian manufacturing hubs. Supply concentrates in China, Germany, and Japan, with methyl chloride, silicon metal, and platinum catalysts as critical inputs. Single-source vulnerability clusters in Chinese fumed silica production. Distribution runs through regional masterbatch compounders in Thailand and Turkey who control intermediate value capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal management requirements are compressing silicone gel qualification cycles below nine months, creating a high-growth disruption as power electronics and battery module demand multiplies. REACH VOC tightening and EPA NESHAP enforcement simultaneously reshape formulation investments and manufacturing location decisions.
For Market Incumbents: Build captive chlorosilane production moats to insulate margin from methyl chloride volatility. Secure automotive Tier 1 supply contracts through integrated technical service teams. Defend against hybrid polymer substitution in construction by accelerating solvent-free curing system deployment ahead of ECHA enforcement timelines. For New Entrants and Emerging Players: Build out medical implant-grade silicone capabilities targeting ISO 10993 certification gaps in neurostimulator supply chains. Penetrate India's PLI-subsidized specialty chemicals manufacturing zones serving domestic electronics and automotive sectors. Lead with digital distribution platforms offering standardized technical data sheets to mid-sized textile finishers. For Investors and Strategic Acquirers: Capital is best deployed toward electronic-grade silicone gel producers with sub-ppm ionic purity capabilities and established wafer-level processing qualifications. Long-term viability hinges on positioning for AI accelerator packaging expansion. Watch for qualification cycle compression below six months as the signal of platform commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Production | Captive methyl chloride supply insulates margin from natural gas price swings at Dow and Shin-Etsu facilities. |
| Electronic-Grade Purity Certification Investment | Sub-ppm ionic purity standards unlock AI accelerator packaging contracts with Taiwan wafer-level processors. |
| Solvent-Free Curing System Transition | ECHA REACH VOC tightening forces European automotive assembly line conversion ahead of competitor readiness. |
| Medical Implant-Grade ISO 10993 Certification | Biocompatibility qualification opens neurostimulator supply chains previously dominated by Swiss and US compounders. |
| India PLI-Subsidized Manufacturing Footprint | Domestic production serving electronics and automotive sectors captures import substitution incentives and logistics savings. |
Study Parameters
A spread of perspectives from silicone plant managers, automotive Tier 1 procurement leads, electronics packaging engineers, and distribution channel partners converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from SEC 10-K filings, ACC and Cefic industry reports, customs and trade data, and EPA enforcement records. Bottom-up volume triangulation across product grades and top-down macroeconomic cross-checks established forecast boundaries.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by molecular architecture, end-use thermal requirements, and regulatory exposure profiles. CAGRs derived from trend extrapolation of EV battery thermal material penetration, semiconductor packaging expansion, and construction refurbishment cycle timing. Methyl chloride feedstock cost trajectories and REACH enforcement intensity served as scenario variables.
Stress conditions across natural gas price bands, ECHA VOC threshold tightening schedules, and Chinese MEE enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about qualification cycle compression rates and substitution elasticity in construction sealants. Material shifts in semiconductor packaging substrate technology or EV cell-to-pack architecture adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Vulcanization Accelerators Market