
 Thermolysin Market | 2026-2036
Thermolysin Market Size, Share, and Industry Trends Forecast 2026-2036
Thermolysin Market Analytics
Recombinant microbial expression is hardening cost structures against traditional animal-derived protease sourcing. Novozymes A/S leverages its fermentation platform to dominate industrial-grade supply chains. Merck KGaA anchors its position through deep vertical integration into pharmaceutical-grade purification. Thermo Fisher Scientific Inc. competes by extending distribution density across research-grade channels in North America and Europe.
Thermolysin is a thermostable neutral metalloproteinase derived from Bacillus thermoproteolyticus, typically active at 65–80°C with a molecular weight near 34.6 kDa, and functions primarily to cleave peptide bonds at hydrophobic amino acid residues for protein sequencing and precursor activation. Its industrial purpose centers on peptide synthesis, food protein hydrolysis, and biopharmaceutical processing where thermal stability reduces contamination risk. Pharmaceutical Grade thermolysin commands the dominant margin pool due to cGMP compliance burdens and lot-to-lot consistency requirements. Research Grade supply is fragmenting across catalog distributors while Biochemical formulations face substitution pressure from engineered variants in diagnostic kit manufacturing.
FDA biologics guidance and EMA's MDR framework enforce escalating purity thresholds for enzymes used in therapeutic manufacturing, directly raising barrier costs for uncertified suppliers. ISO 13485 and REACH compliance in Europe further constrain raw material sourcing flexibility for non-integrated producers. Stakeholders must monitor CRISPR-edited strain development timelines and dual-use export controls on precision fermentation technology.
Market Dynamics
Precision fermentation capacity expansion in the United States, Germany, and Japan is consolidating thermolysin supply chains around recombinant microbial expression, displacing traditional animal-derived protease sourcing and hardening cost structures for uncertified suppliers.
Growth Catalysts
- FDA biologics guidance:Escalating purity thresholds for enzymes used in therapeutic manufacturing are compressing supplier qualification timelines and favoring cGMP-certified producers.
- Enzyme-based drug formulation:Biopharmaceutical manufacturers are expanding thermolysin procurement for peptide synthesis and precursor activation in next-generation biologics.
- Precision fermentation clusters:Concentrated capacity buildouts in Bavaria and Kansai are reducing per-unit production costs for industrial-grade thermolysin.
Market Restraints
- Strain development timelines:CRISPR-edited Bacillus thermoproteolyticus variants require 18-24 month validation cycles before commercial scale-up.
- Dual-use export controls:Precision fermentation technology faces licensing restrictions from the Wassenaar Arrangement, constraining equipment transfers to uncertified facilities.
- Engineered protease substitution:Diagnostic kit manufacturers are displacing biochemical-grade thermolysin with site-specific variants offering narrower cleavage specificity.
Strategic Opportunities
- Contract manufacturing expansion:CDMOs in Singapore and Switzerland are building dedicated thermolysin suites to capture pharmaceutical-grade outsourcing demand.
- ISO 13485 certification:In vitro diagnostic reagent producers in South Korea are accelerating thermolysin qualification for CE-marked immunoassay kits.
- Food protein hydrolysis:Clean-label peptide ingredient demand from sports nutrition formulators is opening industrial-grade volume contracts.
Industry Challenges
- cGMP compliance timelines:Pharmaceutical-grade lot-to-lot consistency validation requires 12-18 month documentation cycles that delay revenue recognition.
- Metalloproteinase stabilization:Zinc cofactor retention during lyophilization demands specialized excipient formulations that inflate COGS.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermolysin Market |
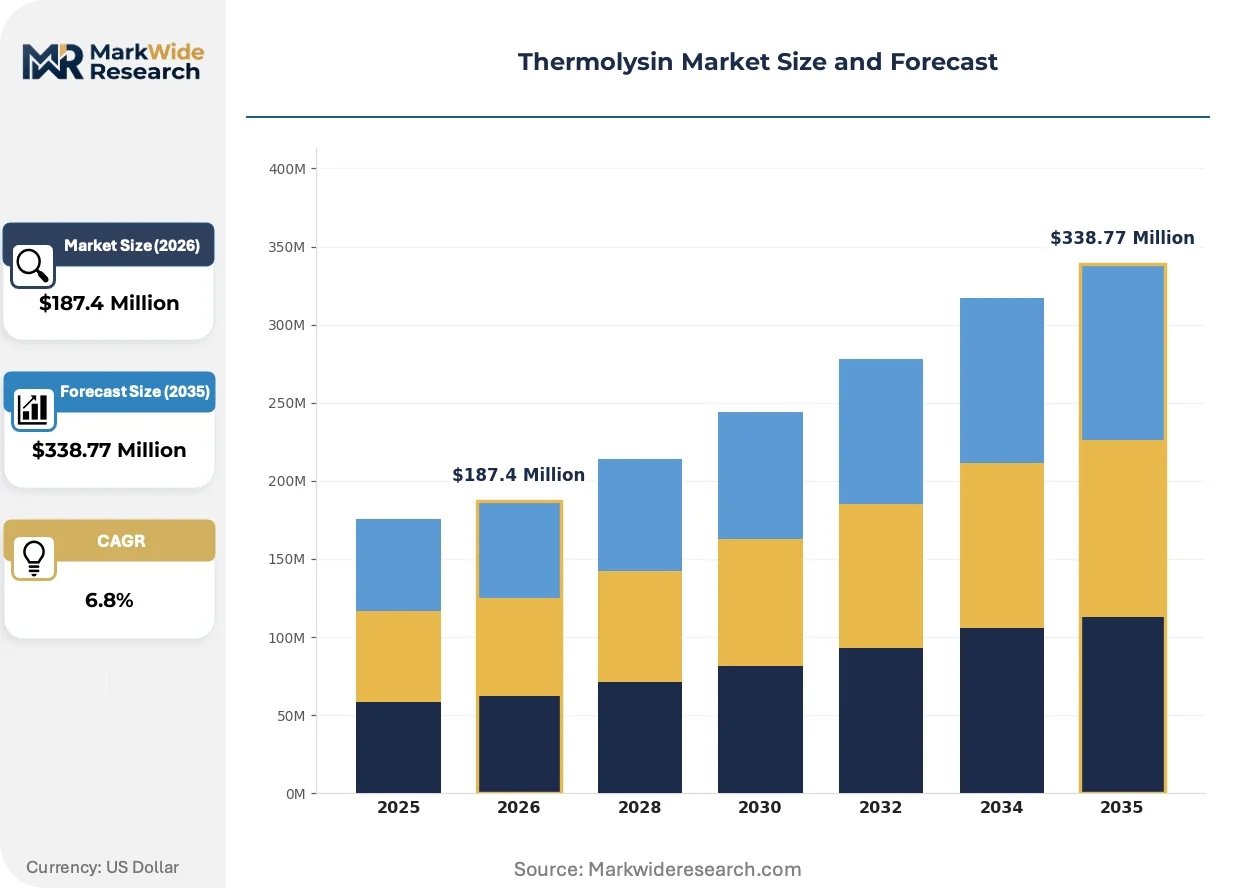
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemical, Enzyme Preparations, Pharmaceutical Grade, Research Grade Therapy Area: Oncology, Cardiovascular, Infectious Diseases, Metabolic Disorders Application: Drug Formulation, Diagnostic Kits, Research Studies, Bioproduction End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Hospitals |
| Companies Covered | Worthington Biochemical Corporation, Roche Diagnostics GmbH, Novozymes A/S, Thermo Fisher Scientific Inc., Kaneka Corporation, Merck KGaA, Amicogen, Inc., BBI Solutions, Enzo Life Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermolysin Market Evolving Landscape
Continuous processing architectures and single-use bioreactor adoption are compressing batch cycle times and reducing cross-contamination risk in thermolysin manufacturing, while regulatory data integrity requirements are reshaping supplier qualification protocols.
CRISPR-Cas9 strain engineering is unifying thermostability and specific activity optimization in a single editing workflow. Biopharmaceutical enzyme suppliers are adopting these platforms at pilot scale within 18 months. The technology is unifying strain development and downstream purification design, collapsing traditional stage-gate timelines.
EMA's Medical Device Regulation framework is tightening substrate purity documentation for enzymes incorporated into companion diagnostics. Manufacturers must now submit lot-specific heavy metal and endotoxin certificates with each shipment. In vitro diagnostic reagent producers in the Netherlands and Denmark are responding by qualifying secondary suppliers with redundant cGMP certifications.
Long-term offtake agreements are displacing spot-market catalog purchases for research-grade thermolysin. Academic core facilities and CROs in Massachusetts and North Carolina are consolidating procurement through preferred distributor contracts with fixed annual volumes. This concentration is most visible in CRISPR screening services, where standardized enzyme lots reduce protocol variability across multi-site studies.
Thermolysin Market Segmentation
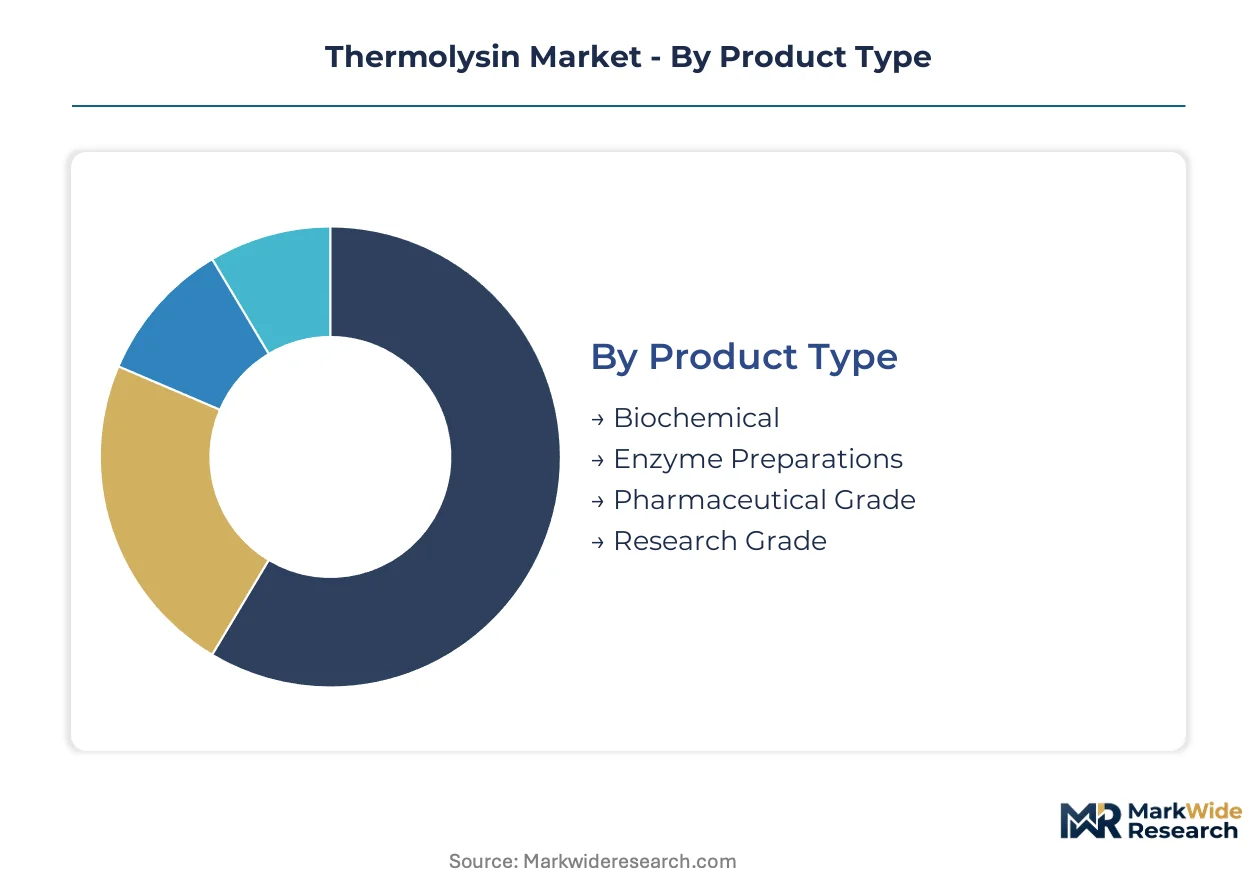
Thermolysin procurement splits sharply between high-margin pharmaceutical-grade lots and high-volume industrial formulations. Understanding these segment boundaries reveals where certification burdens concentrate and where substitution pressure operates most intensely.
Product Type:
Volume concentrates in industrial-grade enzyme preparations while premium pools accrue to certified pharmaceutical grades.
- Pharmaceutical Grade:cGMP-compliant lots with documented endotoxin and heavy metal certificates for therapeutic manufacturing. Demand clusters with biopharmaceutical CDMOs in Bavaria and Massachusetts where FDA and EMA audits enforce lot-to-lot consistency. Validation timelines stretch 12-18 months, entrenching incumbent suppliers.
- Research Grade:Catalog-distributed formulations for academic core facilities and CROs. Procurement is consolidating through preferred distributor contracts with fixed annual volumes, particularly in CRISPR screening services across North Carolina and Massachusetts.
- Biochemical:Standardized preparations for general laboratory use with lower purity thresholds.
- Enzyme Preparations:Bulk industrial formulations for food protein hydrolysis and peptide synthesis.
Today's leader: Pharmaceutical Grade. Tomorrow's challenger: Research Grade.
Therapy Area:
Oncology and metabolic disorders concentrate therapeutic enzyme demand while infectious diseases applications face funding volatility.
- Oncology:Thermolysin activates prodrugs and processes peptide-based cancer therapeutics. Demand aligns with CAR-T and bispecific antibody manufacturing expansion in Basel and Boston.
- Metabolic Disorders:Enzyme replacement therapy precursor activation drives procurement from rare disease specialists. Swissmedic and FDA orphan drug designations accelerate validation pathways for certified suppliers.
- Cardiovascular:Peptide synthesis for antihypertensive drug candidates.
- Infectious Diseases:Vaccine adjuvant and antigen processing applications.
Cardiovascular represents the fastest-expanding trajectory as peptide-based hypertension therapies advance through Phase II trials.
Application:
Drug formulation commands the steepest margins while diagnostic kit manufacturing faces engineered protease substitution.
- Drug Formulation:Peptide synthesis and precursor activation for next-generation biologics. Biopharmaceutical manufacturers in Germany and Japan are expanding thermolysin procurement for continuous processing architectures.
- Diagnostic Kits:Immunoassay reagent formulations requiring ISO 13485 certification. South Korean IVD producers are accelerating qualification for CE-marked kits under EMA MDR framework requirements.
- Research Studies:Protein sequencing and structural biology applications.
- Bioproduction:Upstream cell culture and downstream purification processing.
Drug formulation holds margin dominance. Diagnostic kits face the steepest substitution pressure from site-specific engineered variants.
End User:
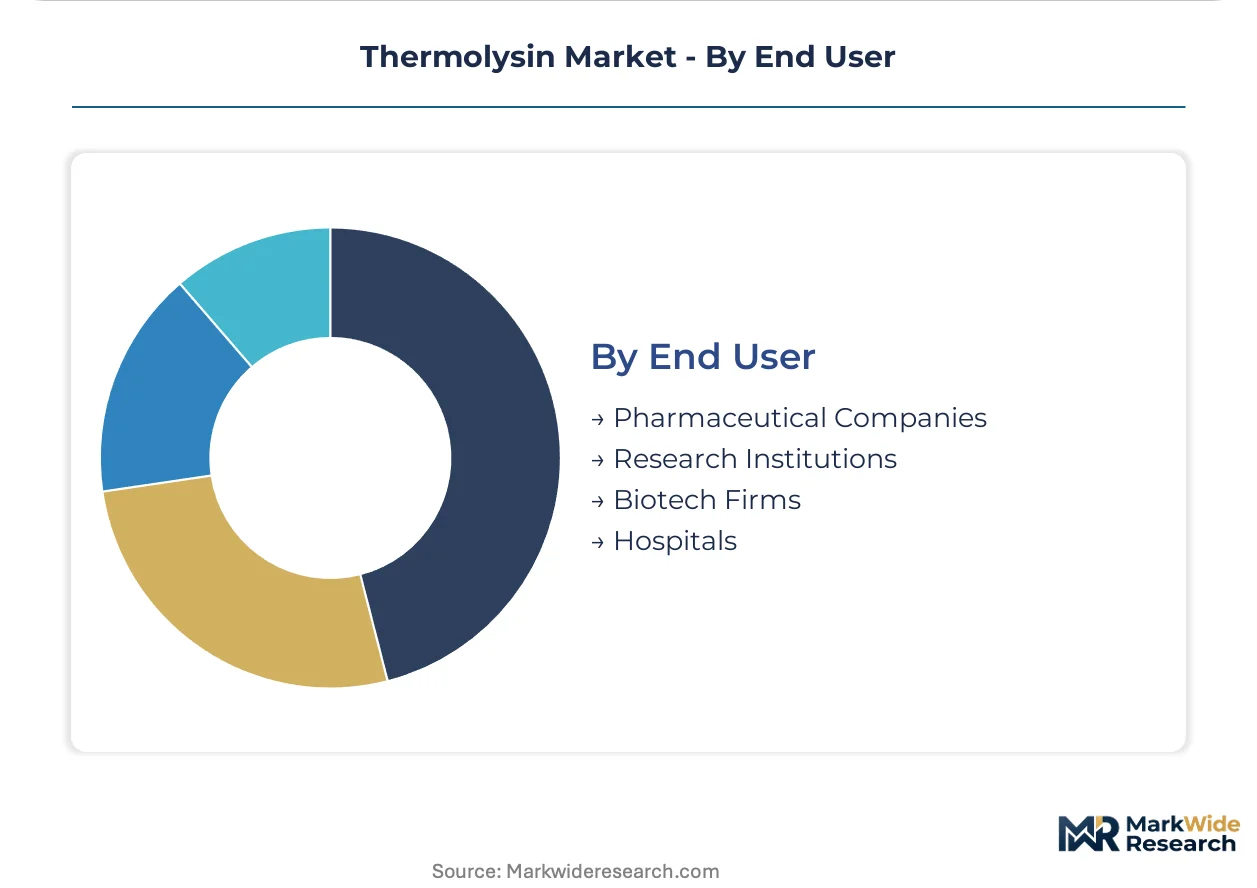
Pharmaceutical companies anchor volume commitments while research institutions fragment across catalog distributors.
- Pharmaceutical Companies:Integrated biopharmaceutical manufacturers and CDMOs with captive enzyme supply or long-term offtake agreements. Novozymes and Merck KGaA serve this tier through dedicated fermentation capacity.
- Biotech Firms:Venture-backed developers of peptide therapeutics with outsourced manufacturing models. Singapore and Switzerland CDMOs are building dedicated thermolysin suites to capture this demand.
- Research Institutions:Academic core facilities with consolidated procurement through preferred distributors.
- Hospitals:Limited direct procurement, primarily through central pharmacy compounding operations.
Pharmaceutical companies lock in supply security. Biotech firms are gaining share fastest as outsourced biologics manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's precision fermentation corridor anchors thermolysin manufacturing capacity, with industrial clusters across Germany, the United States, Japan, Switzerland, and South Korea translating regulatory pressure into competitive positioning for certified enzyme suppliers.
Germany
EMA's MDR framework and REACH compliance requirements tighten substrate purity documentation for pharmaceutical-grade thermolysin. Bavarian CDMOs in Munich and Regensburg are scaling dedicated fermentation suites to capture outsourced biologics manufacturing demand from Swiss and Danish drug developers.
United States
FDA biologics guidance compresses supplier qualification timelines for cGMP-certified thermolysin lots. Massachusetts and North Carolina academic core facilities are consolidating procurement through preferred distributor contracts with fixed annual volumes for CRISPR screening services.
Japan
PMDA orphan drug designations accelerate validation pathways for enzyme replacement therapy applications. The Kansai region's precision fermentation buildouts near Osaka are reducing per-unit production costs for industrial-grade thermolysin destined for peptide synthesis operations.
Switzerland
Swissmedic certification requirements and dual-use export controls on precision fermentation equipment constrain technology transfers to uncertified facilities. Basel-area biopharmaceutical manufacturers are locking in long-term offtake agreements with captive enzyme suppliers for CAR-T and bispecific antibody manufacturing.
South Korea
MFDS regulatory alignment with EMA MDR standards accelerates ISO 13485 qualification for in vitro diagnostic reagent producers. Seoul and Gyeonggi Province IVD manufacturers are building redundant cGMP certifications to satisfy CE-marked immunoassay kit documentation requirements.
Thermolysin Market Competitive Landscape
Global majors compete with regional champions across certification tiers, with pharmaceutical-grade supply consolidating around cGMP-validated fermentation platforms while research-grade procurement fragments across catalog distributors. Market structure hardens into three archetypes: integrated bioprocess suppliers with captive strain development, specialized enzyme houses with deep purification expertise, and research-grade catalog distributors with dense geographic coverage. Dominant competitive moves include backward integration into precision fermentation capacity and strategic partnerships with CDMOs seeking dedicated thermolysin suites.
Within the integrated bioprocess tier, Novozymes A/S and Merck KGaA exemplify scale-driven positioning through fermentation platform control and vertical purification integration respectively. Thermo Fisher Scientific Inc. occupies a distinct research-grade vector, with distribution density across North American and European academic channels representing the catalog-distributor archetype. These three anchors illustrate how certification burden concentration separates pharmaceutical-grade margin pools from industrial-grade volume competition.
| Leading Market Players |
|---|
| Worthington Biochemical Corporation |
| Roche Diagnostics GmbH |
| Novozymes A/S |
| Thermo Fisher Scientific Inc. |
| Kaneka Corporation |
| Merck KGaA |
| Amicogen, Inc. |
| BBI Solutions |
| Enzo Life Sciences, Inc. |
| Others |
Value Network & Pricing Analysis
Biopharmaceutical CDMOs in Bavaria and Massachusetts concentrate procurement power for pharmaceutical-grade thermolysin, anchoring a contract-based long-term offtake pricing model that rewards cGMP certification with 12-18 month volume commitments and penalizes uncertified suppliers with spot-market exclusion.
Pricing Analysis
Input-cost pass-through from precision fermentation infrastructure and zinc cofactor excipients shapes tiered pricing across certification grades. Pharmaceutical-grade lots command premium positioning through FDA and EMA audit documentation, while industrial-grade supply faces cost compression from engineered protease substitution in diagnostic applications. Research-grade procurement exhibits highest price sensitivity as academic core facilities consolidate through preferred distributor contracts with fixed annual volumes.
Supply Chain Analysis
Regional distribution centers in Munich, Boston, and Osaka operate hub-and-spoke patterns for temperature-controlled enzyme logistics. Manufacturing concentrates in Germany, the United States, and Japan where precision fermentation capacity scales. Raw material dependencies include Bacillus thermoproteolyticus seed stocks, zinc sulfate cofactors, and specialized lyophilization excipients. Single-source vulnerability runs through CRISPR-edited strain developers facing 18-24 month validation cycles. Distribution runs through cGMP-certified cold chain networks serving biopharmaceutical manufacturers and CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermolysin functions as a stable compounder anchored by FDA and EMA biologics guidance that entrenches cGMP-certified suppliers through escalating purity thresholds and extended validation timelines.
For Market Incumbents: Cement dominance by backward integration into precision fermentation capacity in Bavaria and Kansai, locking in captive strain development. Deepen ISO 13485 certification investments to defend against engineered protease substitution in South Korean diagnostic kit manufacturing. Priority lever rests on long-term offtake agreements with Basel-area CAR-T manufacturers. For New Entrants and Emerging Players: Begin with ISO 13485 qualification for in vitro diagnostic reagent supply to South Korean and Dutch manufacturers facing EMA MDR documentation requirements. White-space concentrates in research-grade catalog distribution where academic core facilities seek standardized lots for CRISPR screening services. Go-to-market angle emphasizes redundant cGMP certifications that satisfy CE-marked immunoassay kit demands. For Investors and Strategic Acquirers: CDMOs seeking dedicated enzyme suites represent the most active acquirer in this space, particularly Singapore and Switzerland contract manufacturers building thermolysin-specific capacity. Five-to-ten year viability hinges on precision fermentation technology control rather than catalog distribution density. Signal to monitor: CRISPR-edited strain development timelines collapsing below 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Certification Investment | FDA and EMA audit documentation compresses supplier qualification timelines for biopharmaceutical CDMOs. |
| Precision Fermentation Capacity Expansion | Bavarian and Kansai buildouts reduce per-unit production costs for industrial-grade thermolysin supply. |
| ISO 13485 Qualification | South Korean IVD producers accelerate CE-marked immunoassay kit compliance under EMA MDR framework. |
| Long-term Offtake Agreements | Basel-area CAR-T manufacturers lock in supply security with captive enzyme suppliers. |
| CRISPR Strain Development | Edited Bacillus thermoproteolyticus variants unify thermostability and specific activity optimization workflows. |
Research Methodology
Bottom-up biopharmaceutical procurement modeling reconciled against top-down precision fermentation capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and academic core facility directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of enzyme procurement patterns and fermentation capacity utilization established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product grade tier, therapy area application, end-user category, and regional regulatory cluster. CAGRs derived from volume-weighted growth rates applied to each segment with cross-validation against biopharmaceutical manufacturing expansion data and precision fermentation investment flows.
Caveats apply where CRISPR strain validation timeline compression or dual-use export control relaxation could materially shift the outlook. Forecasts reflect documented assumptions about regulatory stringency persistence and substitution technology advancement rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Solanesol Market