
 Global Release Agents Market | 2026-2036
Global Release Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Release Agents Market Foresight
Multi-source procurement among compounders is consolidating around fewer qualified release-agent suppliers with verified regulatory dossiers. BASF SE leverages its polymer science heritage to sustain formulation leadership across high-temperature molding applications. Cargill Incorporated anchors its position through bio-based emulsifier technology that addresses renewable-content mandates in European automotive supply chains. Dow Inc. competes on silicone chemistry breadth, extending portfolio coverage from rubber molding into advanced composite fabrication.
Release agents are surface-active formulations, typically comprising silicone oils, wax emulsions, or fluoropolymer dispersions at 5-30% active content, that prevent adhesion between a mold surface and the finished part during thermoset or thermoplastic processing. Their primary industrial purpose is to enable clean demolding, reduce scrap rates, and extend mold life in repetitive manufacturing cycles. Silicone-based release agents dominate volume due to thermal stability above 200°C, while water-based formulations represent the fastest-expanding category as VOC regulations tighten across manufacturing jurisdictions. Rubber molding and plastics manufacturing applications command the largest combined share, though composite fabrication is gaining share as aerospace manufacturers scale thermoset part production.
FDA food-contact regulations, EPA VOC emission standards, and REACH substance restrictions collectively determine which chemistries gain market access in the United States and European Union. These frameworks push formulators toward aqueous and bio-derived alternatives while disqualifying legacy solvent-based products from qualified supplier lists. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluoropolymer-based release agents face prospective phase-down pressures that could force rapid portfolio restructuring.
Market Dynamics
Automotive lightweighting mandates are intensifying mold-release complexity as carbon-fiber-reinforced thermoplastics displace traditional metal stampings, forcing formulators to engineer agents compatible with higher processing temperatures and reactive resin chemistries.
Growth Catalysts
- FDA Food-Contact Modernization:Updated FDA food-contact notification requirements are accelerating water-based formulation adoption across US packaging converters seeking compliant barrier coatings.
- China Dual Carbon Targets:MEE emission intensity rules are pressuring domestic molders to replace solvent-based release agents with low-VOC alternatives in Ningbo and Shenzhen manufacturing clusters.
- Silicone Thermal Stability:Polysiloxane chemistry advances enabling sustained performance above 250°C are expanding addressable applications in aerospace thermoset composite fabrication.
Market Restraints
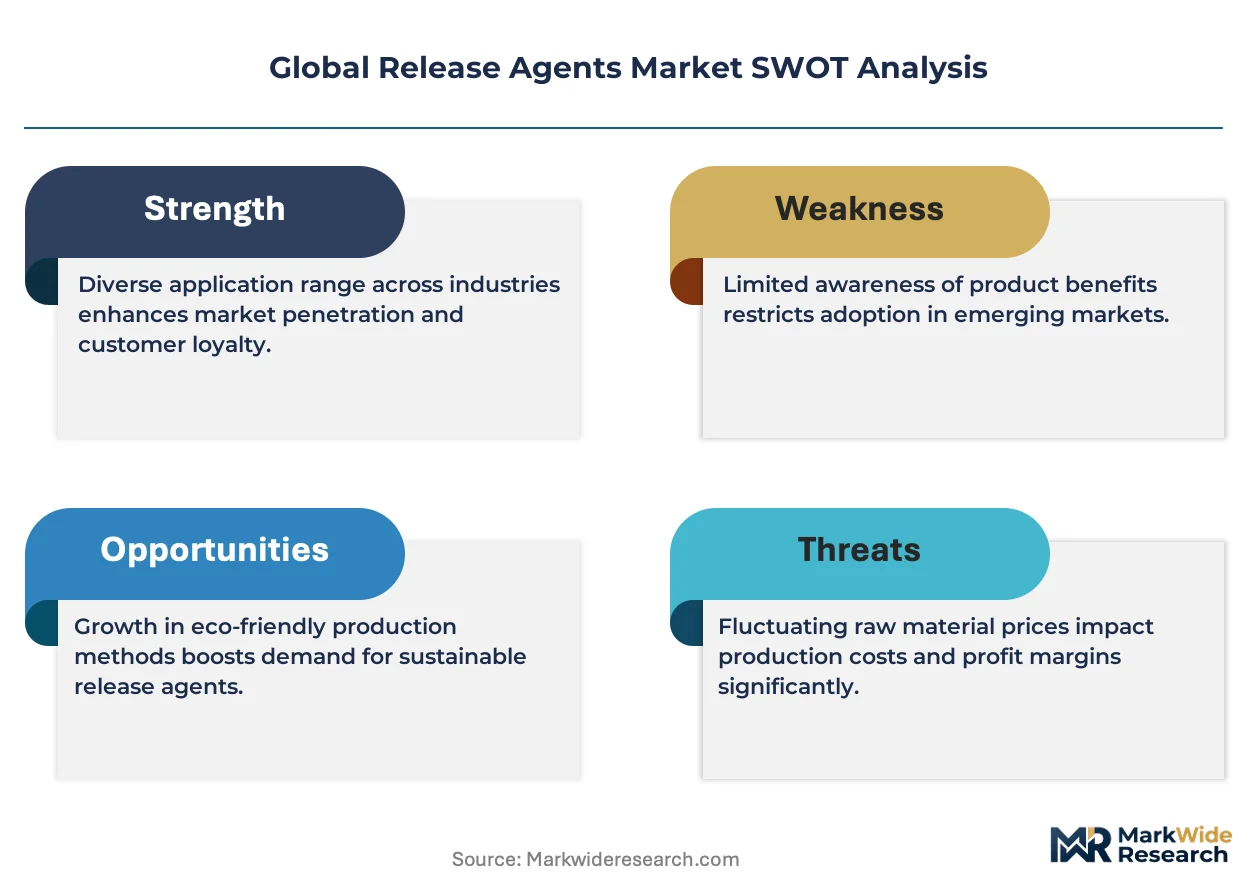
- Fluoropolymer Feedstock Volatility:Perfluorinated raw material supply disruptions and prospective PFAS restrictions under REACH and state-level US legislation are compressing margins for high-performance fluorinated release agent producers.
- Specialized Additive Concentration:German and Japanese suppliers dominate proprietary emulsifier chemistries, creating single-source vulnerability for compounders requiring qualified automotive-grade formulations.
- Aqueous Drying Energy Burden:Water-based formulations require 40-60% longer mold cycle times in high-throughput injection molding, limiting adoption in cost-sensitive commodity plastics processing.
Strategic Opportunities
- Brazilian Automotive Localization:ANVISA chemical registration harmonization with REACH principles is opening qualified supplier positions for bio-based release agents serving expanding São Paulo automotive plastics clusters.
- Wind Blade Manufacturing Scale-Up:Vacuum-assisted resin transfer molding of epoxy composites for 100+ meter turbine blades is creating demand for semi-permanent release coatings with 500+ cycle durability.
- EU Green Deal Procurement Mandates:CSRD-aligned renewable content requirements in German and French automotive supply chains are favoring formulators with verified bio-based carbon content above 30%.
Industry Challenges
- Formulation Chemistry Expertise Gap:Shortage of polymer chemists experienced in silicone-polyether copolymer synthesis is constraining R&D velocity at mid-tier specialty chemical producers.
- Multi-Jurisdiction Registration Burden:Simultaneous REACH, TSCA, and NMPA substance dossier preparation extends product commercialization timelines by 18-24 months for novel bio-derived active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Release Agents Market |
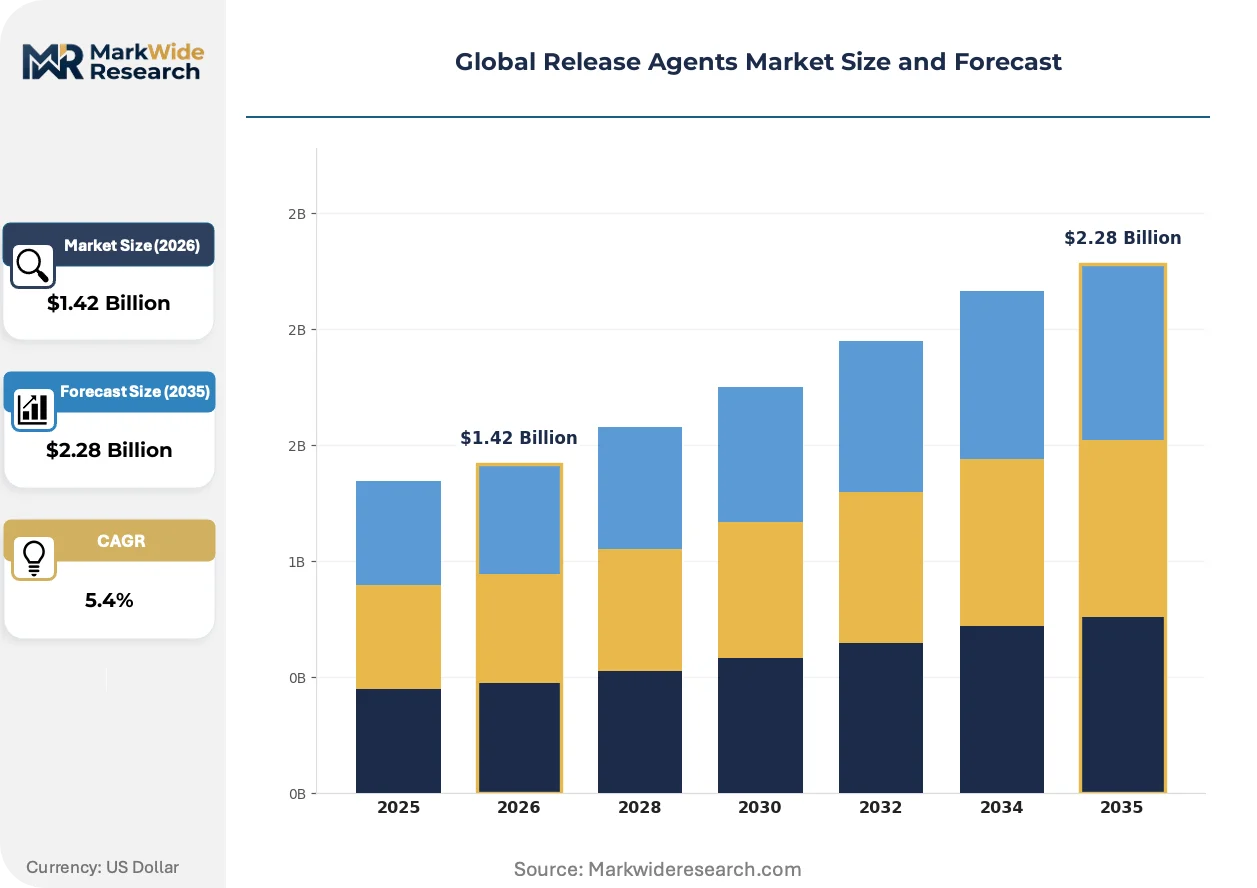
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Wax-Based, Water-Based, Epoxy-Based, Fluoropolymer-Based Application: Rubber Molding, Plastics Manufacturing, Metal Casting, Concrete Forming, Composite Fabrication End User Industry: Automotive OEMs, Aerospace Manufacturers, Consumer Electronics, Construction Firms, Packaging Companies Packaging Type: Bulk Containers, Aerosol Cans, Drums, Pails, Cartridge Tubes |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Dow Inc., BASF SE, AAK AB, Lallemand, Henkel AG & Co. KGaA, Chem Trend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Release Agents Market Shifts & Advancements
Formulation architecture is fragmenting into application-specific modules as regulatory heterogeneity and performance specialization outpace the economics of universal product platforms.
Semi-permanent release coating systems is modularizing around substrate-specific primer layers and sacrificial topcoat combinations. Aerospace tier-one suppliers in Toulouse and Hamburg are adopting these stackable architectures to optimize release performance across carbon, glass, and aramid fiber variants without complete formulation redevelopment. This modularity is compressing qualification timelines for new composite programs while fragmenting supplier R&D priorities.
REACH Annex XVII PFAS restriction proposals are forcing portfolio restructuring across European formulators. The anticipated prohibition on perfluorooctanoic acid precursors and long-chain fluoropolymer derivatives is redirecting development resources toward short-chain fluorotelomer and silicone-hybrid alternatives. German automotive OEMs are accelerating supplier audits to identify qualified non-fluorinated options ahead of anticipated 2026-2027 enforcement windows.
Compounders are consolidating qualified supplier lists around vertically integrated formulators with in-house emulsification and regulatory dossier capabilities. Tier-two automotive molders in Michigan and Ontario are displacing distributor-mediated procurement with direct technical partnerships, exchanging volume commitments for formulation co-development access. This concentration is most visible in North American electric vehicle battery housing programs where thermal management requirements demand customized release agent performance.
Global Release Agents Market Segmentation
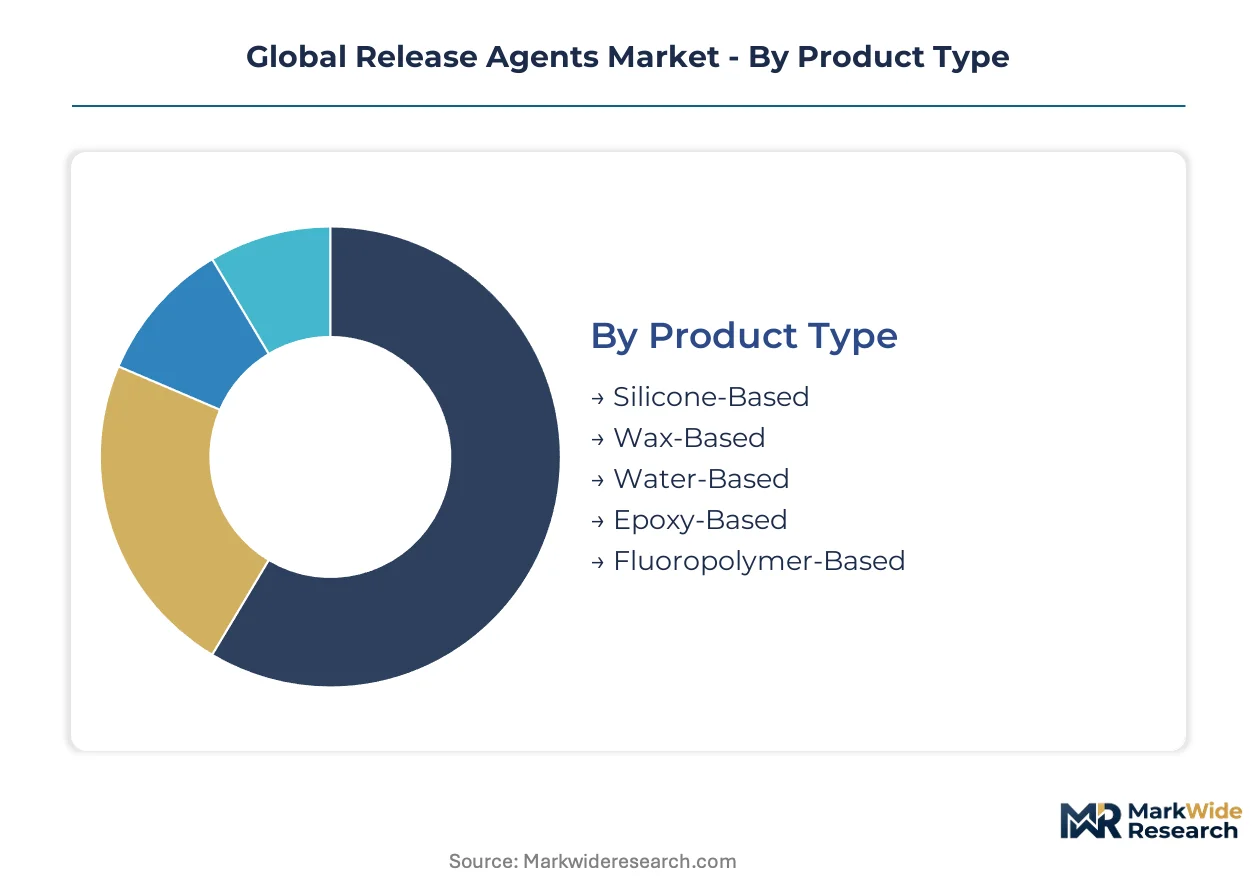
Release agent procurement decisions pivot on processing temperature, regulatory jurisdiction, and mold cycle economics. Formulators must align product architectures with distinct performance thresholds across thermoplastic, thermoset, and elastomer manufacturing environments.
Product Type:
Material cost and thermal ceiling dictate supplier selection across high-volume molding operations.
- Silicone-Based:Polysiloxane formulations deliver sustained lubricity above 250°C through oxidative stability of Si-O backbones. Automotive OEMs in Stuttgart and Detroit specify these grades for glass-filled nylon battery housings where mold temperatures exceed 200°C and cycle consistency is non-negotiable.
- Water-Based:Aqueous emulsions at 15-25% solids content eliminate VOC emissions but extend drying cycles by 40-60 seconds. Packaging converters in Wisconsin and Hesse are migrating to these formulations ahead of EPA and REACH solvent restrictions, accepting throughput penalties for compliance certainty.
- Wax-Based:Microcrystalline and synthetic paraffin dispersions serve lower-temperature elastomer molding below 150°C.
- Epoxy-Based:Reactive systems cure onto mold surfaces for semi-permanent release in wind blade manufacturing.
- Fluoropolymer-Based:Perfluorinated coatings dominate aerospace composite release where surface finish requirements are most stringent.
Silicone-based products lead on scale; water-based alternatives lead on momentum.
Application:
Process mechanics and surface quality requirements fragment demand across discrete manufacturing technologies.
- Rubber Molding:High-viscosity elastomer compounds require release agents with boundary lubrication properties to prevent mold fouling from sulfur crosslink residues. Tire manufacturers in Qingdao and Clermont-Ferrand consume bulk volumes for steel-belted radial production where mold cleaning downtime costs exceed $15,000 per hour.
- Composite Fabrication:Vacuum-assisted resin transfer molding of epoxy prepregs demands semi-permanent coatings with 500+ release cycles. Aerospace tier-one suppliers in Toulouse and Hamburg are qualifying new formulations for 100+ meter wind turbine blades where coating durability directly determines manufacturing economics.
- Plastics Manufacturing:Injection and blow molding operations specify release agents compatible with polyolefin and engineering thermoplastic chemistries.
- Metal Casting:Die-casting of aluminum alloys requires refractory-grade release coatings for thermal shock resistance.
- Concrete Forming:Construction formwork release agents prioritize biodegradability for wastewater compliance.
Rubber molding dominates current volume; composite fabrication is expanding most quickly.
End User Industry:
Supply chain concentration and qualification rigor determine account-level profitability for formulators.
- Automotive OEMs:Lightweighting mandates are displacing metal stampings with carbon-fiber-reinforced thermoplastics, forcing release agent reformulation for higher processing temperatures. German and US electric vehicle programs are consolidating qualified supplier lists around formulators with in-house emulsification and REACH dossier capabilities.
- Aerospace Manufacturers:Thermoset composite fabrication for airframes and interiors requires release coatings certified to OEM-specific surface quality and FST (fire, smoke, toxicity) standards. Boeing and Airbus tier-one suppliers in Wichita and Nantes conduct 18-24 month qualification protocols that lock in formulation specifications for program durations.
- Consumer Electronics:Precision molding of polycarbonate and ABS housings for smartphones and laptops demands cosmetic-grade surface finish.
- Construction Firms:Concrete formwork release prioritizes cost minimization over performance optimization.
- Packaging Companies:Food-contact compliance drives water-based formulation adoption for barrier coatings.
Automotive OEMs anchor volume concentration; aerospace manufacturers command premium pricing tiers.
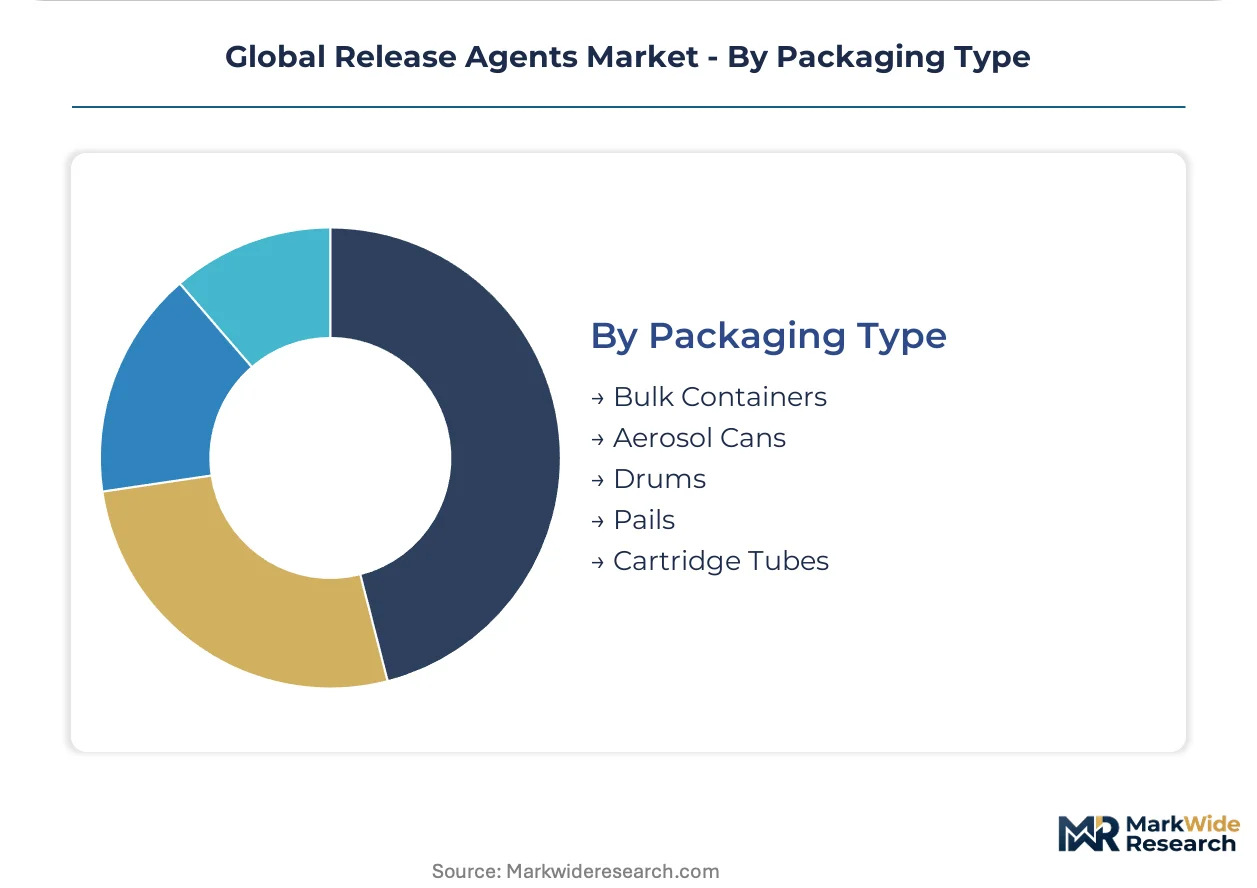
Packaging Type:
Logistics economics and application method determine format selection across customer scale tiers.
- Bulk Containers:Tote and tanker deliveries of 1,000-20,000 liter volumes serve compounders and large molding operations with centralized chemical handling infrastructure. Automotive plastics clusters in Michigan and Bavaria specify bulk delivery for silicone emulsion concentrates that are diluted on-site to 5-10% use dilution.
- Drums:200-liter steel and polyethylene drums balance shipping efficiency with inventory flexibility for mid-tier molders without bulk storage capacity.
- Aerosol Cans:Pressurized solvent-based formulations persist in maintenance and repair applications despite VOC regulatory pressure.
- Pails:20-25 liter containers serve specialty compounders requiring frequent formulation changes.
- Cartridge Tubes:Meter-dose packaging enables precise application in aerospace composite layup operations.
Bulk containers dominate tonnage; drums capture the broadest customer count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial demand as automotive OEMs intensify mold-release complexity for carbon-fiber-reinforced thermoplastics. REACH compliance deadlines and FDA food-contact modernization are reshaping qualified supplier geography across manufacturing clusters.
Germany
Automotive lightweighting mandates from BMW and Mercedes-Benz drive specification of silicone-based agents above 250°C. ECHA's REACH Annex XVII PFAS restriction proposals accelerate supplier audits for non-fluorinated alternatives. The Stuttgart-Munich corridor concentrates qualified formulators with in-house emulsification capabilities serving electric vehicle battery housing programs.
United States
Packaging converters in Wisconsin and Michigan seek water-based formulations ahead of EPA VOC emission standards. FDA updated food-contact notification requirements favor aqueous barrier coatings for compliant food packaging. The Detroit automotive plastics cluster consolidates procurement around vertically integrated suppliers with TSCA dossier capabilities.
China
Ningbo and Shenzhen manufacturing clusters face MEE emission intensity rules pressuring solvent-based release agent replacement. The country's dual carbon targets mandate low-VOC alternatives in precision molding operations. Qingdao tire manufacturers consume bulk volumes for steel-belted radial production where mold cleaning downtime costs exceed $15,000 per hour.
France
Aerospace tier-one suppliers in Toulouse and Nantes conduct 18-24 month qualification protocols for thermoset composite release coatings. EU Green Deal procurement mandates favor formulators with verified bio-based carbon content above 30%. The CSRD-aligned renewable content requirements in automotive supply chains are redirecting compounder procurement toward sustainable alternatives.
Brazil
ANVISA chemical registration harmonization with REACH principles opens qualified supplier positions for bio-based release agents. Expanding São Paulo automotive plastics clusters create demand for compliant formulations serving localized OEM production. The regulatory alignment reduces commercialization barriers for European formulators seeking Latin American market entry.
Global Release Agents Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry breadth and regulatory dossier depth. The supplier base concentrates around vertically integrated formulators with in-house emulsification capabilities, displacing distributor-mediated procurement in automotive programs. Three archetypes dominate: polymer science heritage companies, bio-based emulsion specialists, and silicone chemistry breadth providers. Competitive moves center on portfolio restructuring ahead of PFAS restrictions and direct technical partnerships exchanging volume commitments for co-development access.
Among diversified chemical conglomerates, BASF SE and Dow Inc. occupy positions spanning high-temperature molding through advanced composite fabrication. Cargill Incorporated anchors the bio-based tier through renewable emulsifier technology addressing European automotive supply chain mandates. These three exemplify the consolidation trajectory as compounders narrow qualified supplier lists around verified regulatory dossiers and demonstrated formulation leadership across silicone, aqueous, and bio-derived architectures.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Dow Inc. |
| BASF SE |
| AAK AB |
| Lallemand |
| Henkel AG & Co. KGaA |
| Chem Trend |
| Others |
Supply & Pricing Matrix
Automotive-grade certification divergence separates premium silicone formulations from commodity wax emulsions, with this bifurcation manifesting in both pricing power concentration among REACH-dossier holders and supply chain consolidation around vertically integrated German and Japanese suppliers. Compounders in Stuttgart and Detroit pay 40-60% cycle-time penalties for water-based compliance, while aerospace tier-one suppliers in Toulouse absorb semi-permanent coating premiums for 500+ cycle durability.
Pricing Analysis
Silicone feedstock volatility from polysiloxane precursor markets passes through to finished release agent pricing within 60-90 days, compressing margins for non-integrated formulators. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-commodity levels reflects certification investment recovery and volume scale. Cost compression in water-based emulsions is intensifying because MEE emission rules in China force solvent-based displacement. Packaging converters in Wisconsin exhibit highest price sensitivity; aerospace manufacturers in Hamburg show lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Dual-sourcing requirements from BMW and Mercedes-Benz procurement mandates force compounders to qualify second-source release agent suppliers for carbon-fiber-reinforced thermoplastic programs. Manufacturing concentrates in Germany, China, and the United States where precision molding clusters anchor consumption. Raw material dependencies rest on polydimethylsiloxane, fluorotelomer precursors, and bio-based emulsifier feedstocks. Single-source vulnerability from German and Japanese proprietary emulsifier chemistry dominance creates supply risk. Distribution runs through direct technical partnerships displacing distributor mediation in automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European formulators leverage REACH dossier depth to capture premium positioning in Brazil's ANVISA-harmonized regulatory environment, while Asian producers exploit MEE compliance cost advantages in domestic Ningbo and Shenzhen clusters.
For Market Incumbents: Anchor regulatory dossier leadership through accelerated PFAS-free formulation portfolios ahead of ECHA Annex XVII enforcement windows. Deepen backward integration into silicone-polyether copolymer synthesis to offset proprietary emulsifier single-source vulnerability from Japanese suppliers. Defend automotive account control by exchanging volume commitments for battery housing program co-development access. For New Entrants and Emerging Players: Launch via direct technical partnerships with tier-two automotive molders in Michigan and Ontario seeking alternatives to consolidated qualified supplier lists. Target Brazilian São Paulo automotive plastics clusters where ANVISA harmonization reduces commercialization barriers for bio-based emulsion specialists. Penetrate wind blade manufacturing scale-up demand for semi-permanent epoxy coatings with 500+ cycle specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier formulators lack in-house emulsification capabilities and face 18-24 month novel bio-derived ingredient registration timelines. Long-term viability favors vertically integrated specialists with captive silicone chemistry and verified 30%+ bio-based carbon content. Acquisition target archetype: regional champions with REACH-compliant portfolios and underutilized emulsification capacity. Watch PFAS restriction implementation velocity as inflection indicator for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Chemistry | Captive polydimethylsiloxane supply secures margin control against feedstock volatility from German and Japanese precursor markets. |
| PFAS-Free Portfolio Restructuring | Short-chain fluorotelomer and silicone-hybrid alternatives qualify formulators for ECHA Annex XVII compliance ahead of enforcement. |
| Direct Technical Partnership Programs | Volume-commitment exchanges with Detroit and Stuttgart OEMs displace distributor mediation in electric vehicle battery housing procurement. |
| Bio-Based Emulsifier Scale-Up | Verified 30%+ renewable carbon content addresses CSRD-aligned mandates from BMW and Mercedes-Benz supply chain requirements. |
| Wind Blade Coating Qualification | Semi-permanent epoxy systems with 500+ cycle durability capture vacuum-assisted resin transfer molding demand from Toulouse and Hamburg tier-one suppliers. |
Research Methodology
Multiple input streams — technical interviews with release agent formulators, procurement discussions with automotive OEMs, and regulatory dossier analysis — were reconciled against customs data and chemical industry association filings. Primary engagement spanned R&D directors at silicone chemistry specialists, procurement leads at Stuttgart and Detroit automotive clusters, and regulatory affairs managers navigating REACH and TSCA submissions. Secondary validation drew from ECHA substance registrations, EPA VOC emission databases, SEC chemical segment disclosures, and trade flow records from Ningbo and Shenzhen manufacturing hubs. Bottom-up formulation demand modeling and top-down chemical consumption estimates were triangulated.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers: silicone thermal stability thresholds for aerospace composites, water-based drying cycle economics for packaging converters, and bio-based renewable content mandates for European automotive supply chains. Segmentation dimensions encompassed chemistry type, application process temperature, regulatory jurisdiction cluster, and end-use industry qualification tier. CAGRs were derived from regression analysis of historical chemical consumption against manufacturing output indices. Forecast inputs included MEE emission intensity rule implementation pace and PFAS restriction proposal advancement through ECHA committees.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS prohibition timelines or silicone precursor supply disruptions. Deviation in ECHA Annex XVII enforcement scheduling would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Panthenol Market