
 Xanthene Derivatives Market | 2026-2036
Xanthene Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Xanthene Derivatives Market Analytics
Specialized organic chemist availability is unwinding capacity expansion timelines across xanthene derivative manufacturers. Thermo Fisher Scientific extends its analytical-grade supply chain through direct synthesis partnerships. BASF SE anchors European production with backward integration into phthalic anhydride feedstocks. Shandong Xinhua Pharmaceutical dominates bulk fluorescein output through dedicated reactor trains.
Xanthene derivatives comprise tricyclic oxygen-containing heterocycles synthesized via condensation of phthalic anhydride with resorcinol or phenol derivatives under acidic conditions, yielding chromophores with quantum yields exceeding 90% for fluorescein variants. These compounds serve as core chromophores in fluorescence microscopy, laser dye systems, and photodynamic therapy agents where precise excitation-emission profiles determine clinical utility. Fluorescein and Rhodamine B lead product type revenue due to entrenched diagnostic staining protocols, while Phloxine B exhibits the fastest growth trajectory driven by phototherapy device approvals. Biological staining anchors application demand through histology laboratory contracts, though fluorescent dyes command premium pricing in flow cytometry reagent kits.
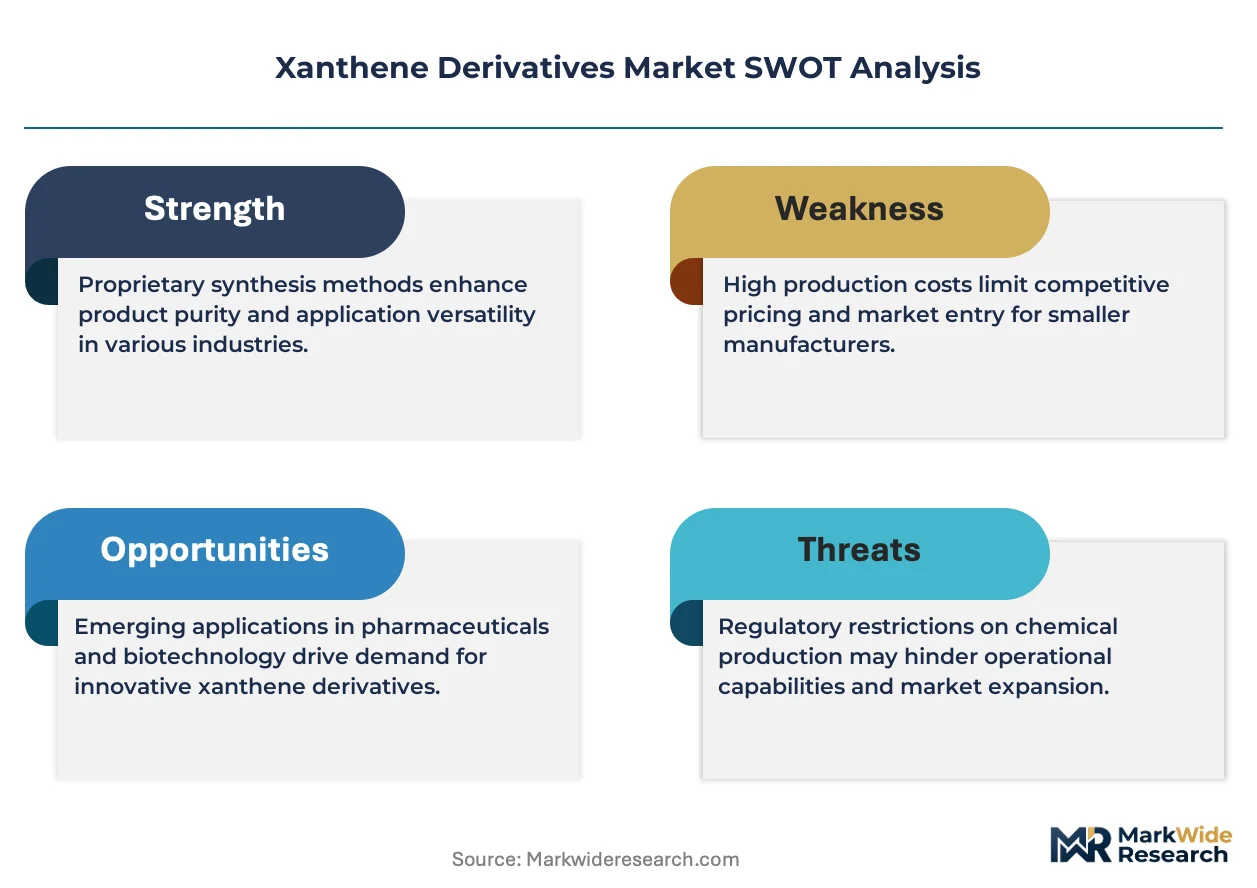
FDA cGMP standards and EMA impurity profiling guidelines enforce batch-level certification for pharmaceutical-grade xanthene lots, elevating compliance costs for cross-border suppliers. China's NMPA alignment with ICH Q3D elemental impurity limits is reshaping export qualification protocols for domestic manufacturers. Stakeholders must monitor evolving pharmacopeial monographs and phototoxicity testing requirements as therapeutic applications expand beyond diagnostics into oncology protocols.
Market Dynamics
Specialized organic chemist scarcity is compressing capacity expansion timelines across xanthene derivative manufacturers, forcing reliance on automated synthesis platforms and contract manufacturing partnerships to meet pharmaceutical-grade demand.
Growth Catalysts
- Photodynamic therapy expansion:FDA approvals for oncology protocols are pulling rhodamine-derived photosensitizers into clinical pipelines, expanding therapeutic applications beyond traditional diagnostics.
- REACH compliance alignment:ECHA substance registration deadlines are consolidating European supplier bases toward certified manufacturers with full toxicological dossiers.
- Flow cytometry reagent standardization:Clinical laboratory consolidation is mandating ISO 13485-certified fluorescent dye lots, favoring suppliers with validated quality management systems.
Market Restraints
- Phthalic anhydride feedstock volatility:Petrochemical input cost swings are compressing margin stability for non-integrated producers lacking captive supply.
- Chinese production concentration:Bulk fluorescein synthesis clusters in Shandong province, creating single-point vulnerability for global dye intermediate supply.
- Elemental impurity testing burdens:ICH Q3D compliance is elevating analytical costs per batch, disadvantaging smaller manufacturers without in-house ICP-MS capabilities.
Strategic Opportunities
- NMPA-aligned export protocols:China's harmonization with ICH standards is opening pharmaceutical-grade qualification pathways for domestic manufacturers targeting regulated markets.
- Near-infrared dye convergence:Coupling xanthene scaffolds with cyanine chromophores is unlocking deeper tissue imaging for surgical navigation systems.
- Direct synthesis partnerships:Laboratory chemical distributors are bypassing traditional wholesale tiers through exclusive manufacturing agreements with specialized synthesis houses.
Industry Challenges
- Specialized organic chemist recruitment:Heterocyclic synthesis expertise is concentrating at top-tier contract research organizations, inflating salary benchmarks for captive manufacturing teams.
- cGMP facility certification timelines:FDA pre-approval inspection backlogs are delaying pharmaceutical-grade lot releases by six to twelve months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xanthene Derivatives Market |
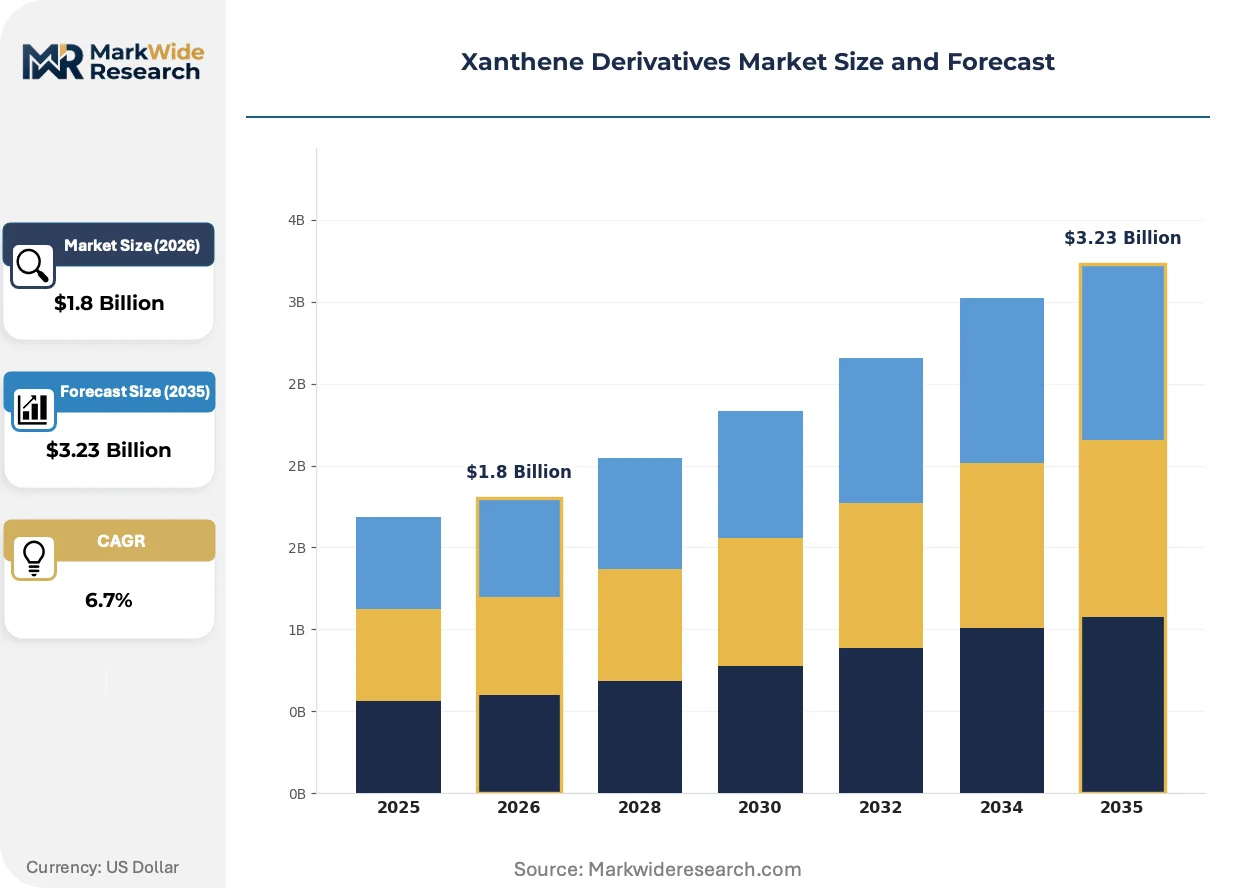
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescein, Rhodamine B, Eosin Y, Phloxine B Application: Biological Staining, Fluorescent Dyes, Laser Printing, Phototherapy End User: Healthcare, Education, Research Institutions, Chemical Manufacturers Form: Powder, Liquid, Gel, Emulsion |
| Companies Covered | VIVAN Life Sciences, Pfizer Inc, Astellas Pharma, Thermo Fisher Scientific Inc, Shandong Xinhua Pharmaceutical Co Ltd, Surya Life Sciences, BASF SE, Merck KGaA, Aarti Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xanthene Derivatives Market Evolving Landscape
Continuous flow photochemistry is displacing batch synthesis as the dominant production paradigm, enabling precise control over quantum yield consistency while reducing solvent waste footprints across xanthene derivative manufacturing.
Microreactor-based synthesis platforms are displacing conventional batch reactors in pharmaceutical-grade fluorescein production. Thermo Fisher Scientific and BASF SE are adopting these systems for active pharmaceutical ingredient intermediates. This technology is displacing legacy condensation vessels by compressing reaction times from hours to minutes while improving batch-to-batch chromophore purity.
EMA impurity profiling guidelines are tightening specification windows for residual phthalic anhydride and unreacted phenol derivatives. European manufacturers are retrofitting purification trains with preparative HPLC capabilities. Pharmaceutical-grade lots face elevated rejection rates, driving consolidation toward integrated producers with captive analytical laboratories.
Histology laboratories are consolidating procurement through group purchasing organizations, unbundling reagent kits from instrumentation service contracts. Academic medical centers in Germany and the United States are leading this shift, pressuring standalone dye suppliers to adopt ISO 17025-certified reference standards or exit clinical segments entirely.
Xanthene Derivatives Market Segmentation
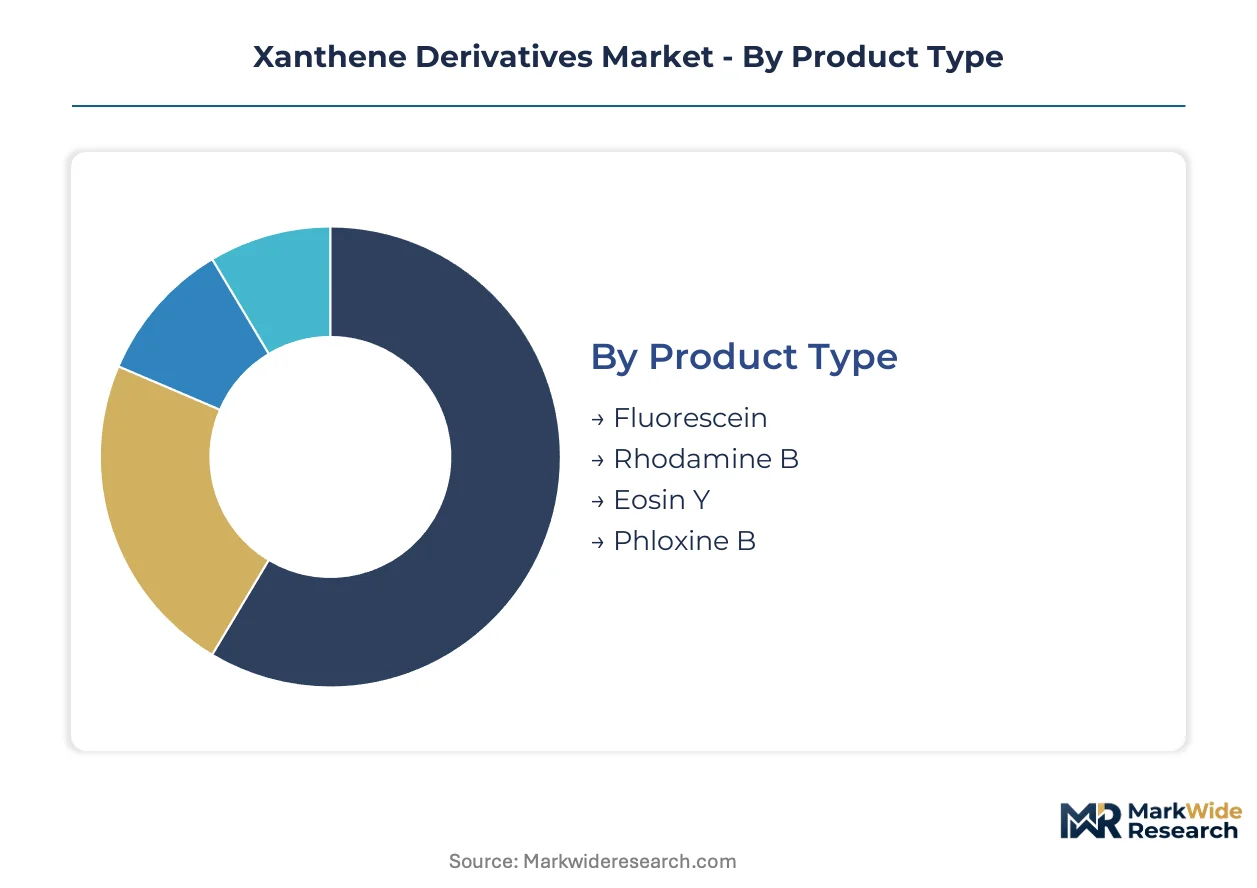
Xanthene derivative procurement channels diverge sharply by certification grade. Pharmaceutical-grade lots flow through validated distributor networks with batch documentation, while technical-grade materials move through chemical wholesale markets with minimal traceability.
Product Type:
Channel mix splits between diagnostic reagent suppliers capturing high-margin certified grades and bulk chemical distributors handling industrial volumes.
- Fluorescein:Quantum yields exceeding 90% define pharmaceutical-grade specifications. Demand concentrates in histology laboratories across Germany and the United States where ISO 13485-certified lots command premium positioning.
- Rhodamine B:Lipophilic variant with red-shifted emission profiles. Photodynamic therapy device manufacturers in Japan and South Korea are pulling material through specialized photosensitizer supply chains as oncology protocols expand.
- Eosin Y:Acidic xanthene dye for routine histological counterstaining. Academic medical centers procure through consolidated group purchasing agreements.
- Phloxine B:Halogenated derivative with enhanced singlet oxygen generation. Phototherapy equipment OEMs source directly from synthesis houses with validated impurity profiles.
Fluorescein dominates installed base. Phloxine B is where expansion concentrates.
Application:
Cost tier stratification separates premium-certified clinical applications from economy-grade industrial uses.
- Biological Staining:Hematoxylin-eosin protocols and fluorescence microscopy anchor histology workflow demand. Academic medical centers in the United States and Germany are unbundling reagent procurement from instrumentation service contracts.
- Fluorescent Dyes:Flow cytometry reagent kits require ISO 17025-certified reference standards. Clinical laboratory consolidation is mandating validated quality management systems from suppliers.
- Laser Printing:Industrial marking applications tolerate broader specification windows. Chemical manufacturers in China supply technical-grade material through commodity channels.
- Phototherapy:Photosensitizer synthesis for oncology protocols demands ICH Q3D elemental impurity compliance. FDA cGMP standards enforce batch-level certification.
Biological staining anchors volume throughput. Phototherapy is climbing the fastest.
End User:
Customer type determines specification stringency and procurement modality.
- Healthcare:Hospital laboratories and diagnostic centers require pharmacopeial-grade material with full traceability documentation. EMA impurity profiling guidelines enforce tight specification windows.
- Education:University teaching laboratories prioritize cost efficiency over certification. Bulk powder purchases through academic distributors predominate.
- Research Institutions:Principal investigators procure specialized derivatives through laboratory chemical distributors with exclusive synthesis partnerships.
- Chemical Manufacturers:Dye intermediate producers in Shandong province scale bulk fluorescein output through dedicated reactor trains for export markets.
Healthcare commands premium pricing tiers. Chemical manufacturers handle volume scaling.
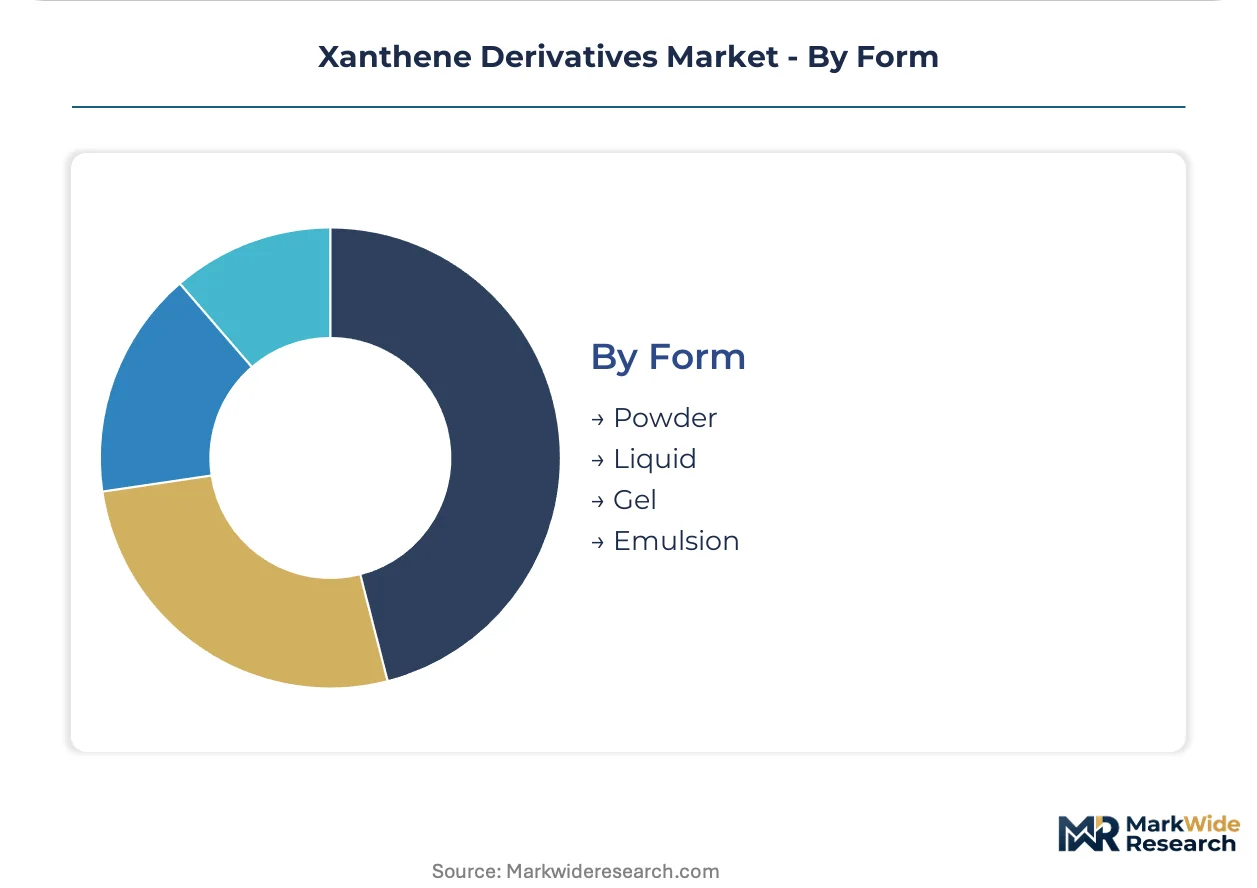
Form:
Supply concentration varies by physical state and stability requirements.
- Powder:Standard solid form for long-term storage and flexible reconstitution. Dominates bulk international shipments from Chinese production clusters.
- Liquid:Ready-to-use formulations for clinical laboratories. Thermo Fisher Scientific extends analytical-grade supply chains through direct synthesis partnerships.
- Gel:Viscous preparations for topical phototherapy applications. Specialized compounding pharmacies handle formulation.
- Emulsion:Lipid-encapsulated variants for enhanced tissue penetration in surgical navigation systems. Near-infrared dye convergence is unlocking deeper imaging capabilities.
Powder dominates international trade flows. Liquid formulations are gaining share fastest in clinical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP standards anchor pharmaceutical-grade demand in the United States, while NMPA alignment with ICH Q3D protocols is reshaping export qualification pathways from Chinese manufacturing clusters.
United States
Academic medical centers in Boston and New York Metro drive histology laboratory procurement through consolidated group purchasing agreements. FDA batch-level certification requirements enforce tight specification windows for diagnostic-grade xanthene lots. The Research Triangle in North Carolina anchors photodynamic therapy clinical trial activity for oncology protocol expansion.
Germany
EMA impurity profiling guidelines tighten residual phthalic anhydride specifications for European pharmaceutical manufacturers. REACH compliance deadlines consolidate supplier bases toward certified producers with full toxicological dossiers. The Rhine-Ruhr industrial corridor hosts backward-integrated dye intermediate production with captive analytical laboratories.
China
Shandong province chemical manufacturers scale bulk fluorescein output through dedicated reactor trains for export markets. NMPA harmonization with ICH Q3D elemental impurity limits streamlines pharmaceutical-grade qualification for regulated markets. The Yangtze River Delta concentrates flow cytometry reagent kit assembly for domestic diagnostic consumption.
Japan
PMDA approvals for photodynamic therapy devices pull rhodamine-derived photosensitizers into clinical oncology pipelines. METI standards for laser dye purity support domestic flow cytometry instrument manufacturing. The Osaka-Kobe industrial zone maintains specialized synthesis capabilities for halogenated xanthene derivatives.
India
CDSCO import substitution policies encourage domestic active pharmaceutical ingredient intermediate production for diagnostic reagents. Bulk chemical distributors in Gujarat and Maharashtra handle technical-grade material through commodity wholesale channels. Hyderabad's pharmaceutical cluster incubates contract manufacturing partnerships for fluorescence microscopy dyes.
Xanthene Derivatives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the xanthene derivatives market. Integrated chemical conglomerates with captive feedstock supply anchor pharmaceutical-grade production, while specialized synthesis houses serve research-grade demand through direct distribution partnerships. Three archetypes dominate: backward-integrated multinationals with in-house phthalic anhydride production, regional bulk manufacturers scaling commodity fluorescein output, and niche laboratory chemical distributors with exclusive synthesis agreements. Competitive moves concentrate on automated synthesis platform deployment and cGMP facility certification acceleration.
Among diversified chemical conglomerates, BASF SE and Merck KGaA exemplify the integrated archetype with upstream control over critical feedstocks. Thermo Fisher Scientific Inc occupies a position bridging analytical-grade supply chain extension with direct synthesis partnerships. Shandong Xinhua Pharmaceutical Co Ltd represents the scale-driven regional manufacturer archetype, while VIVAN Life Sciences and Surya Life Sciences sit within the specialized synthesis tier serving diagnostic reagent kit assemblers.
| Leading Market Players |
|---|
| VIVAN Life Sciences |
| Pfizer Inc |
| Astellas Pharma |
| Thermo Fisher Scientific Inc |
| Shandong Xinhua Pharmaceutical Co Ltd |
| Surya Life Sciences |
| BASF SE |
| Merck KGaA |
| Aarti Industries Ltd |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between pharmaceutical-grade manufacturers and diagnostic reagent kit assemblers lock in supply access and price visibility across the forecast horizon. These arrangements insulate integrated producers from phthalic anhydride feedstock volatility while exposing non-integrated distributors to margin compression.
Pricing Analysis
Pharmaceutical-grade fluorescein commands a fourfold premium over technical-grade material sourced from Shandong province. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale. Cost compression in economy-grade segments is intensifying because Chinese manufacturers scale dedicated reactor trains. Academic medical centers exhibit highest price sensitivity; phototherapy device OEMs demonstrate lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate clinical laboratory procurement, while strategic stockpiling characterizes phototherapy device manufacturers managing photosensitizer supply security. Production concentrates in China, Germany, and Japan. Feedstock draws from petrochemical-derived phthalic anhydride, resorcinol, and phenol derivatives. Single-source vulnerability stems from Shandong province concentration for bulk fluorescein. Distribution runs through validated distributor networks for certified grades and chemical wholesale markets for technical material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as flow cytometry reagent standardization forces ISO 13485-certified dye lots into interoperable diagnostic ecosystems. This interoperability shift consolidates procurement through group purchasing organizations.
For Market Incumbents: Secure backward integration into phthalic anhydride feedstocks to defend against petrochemical input cost swings. Accelerate cGMP facility certification to exploit FDA pre-approval inspection backlogs delaying new entrants. Channel control through direct synthesis partnerships with laboratory chemical distributors anchors analytical-grade positioning. For New Entrants and Emerging Players: Custom synthesis capabilities for halogenated xanthene derivatives represent a service-layer gap where incumbents under-serve principal investigators at research institutions. Target near-infrared dye convergence applications for surgical navigation systems. Exclusive manufacturing agreements with regional distributors provide fastest go-to-market traction. For Investors and Strategic Acquirers: Capital is best deployed toward specialized synthesis houses with validated impurity profiles and ISO 17025-certified reference standards. Long-term viability rests on therapeutic application expansion beyond diagnostics into oncology protocols. Watch FDA photodynamic therapy approval velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | BASF SE anchors European production with captive phthalic anhydride supply. |
| Microreactor Platform Deployment | Continuous flow photochemistry compresses reaction times from hours to minutes. |
| cGMP Facility Certification | FDA batch-level certification delays new entrants by six to twelve months. |
| Direct Synthesis Partnerships | Thermo Fisher Scientific extends analytical-grade supply chains through exclusive agreements. |
| Near-Infrared Dye Convergence | Coupling xanthene scaffolds with cyanine chromophores unlocks deeper tissue imaging. |
Research Methodology
The analysis maps fluorescein, rhodamine, eosin, and phloxine derivative segments, each validated through synthesis chemists, diagnostic reagent procurement managers, and pharmaceutical quality assurance leads. Primary interviews with plant managers at Shandong production facilities, regulatory affairs specialists at EMA, and hospital GPO contracts managers combined with secondary validation from FDA cGMP filings, REACH registration dossiers, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. Segmentation dimensions modeled include product type, application, certification grade, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline consumption estimates. Industry-specific inputs incorporated photodynamic therapy device approval pipelines and histology laboratory consolidation patterns.
Forecasts assume regulatory continuity in FDA cGMP standards and EMA impurity profiling guidelines; material policy shifts would require re-modeling. Revision becomes warranted when ICH Q3D elemental impurity testing requirements or phototoxicity protocols cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Magnesium Chelates Market