
 Isoeicosane Market | 2026-2036
Isoeicosane Market Size, Share, and Industry Trends Forecast 2026-2036
Isoeicosane Market Intelligence
EU REACH restrictions on cyclosiloxanes in cosmetic formulations is pivoting formulators toward branched alkanes as drop-in replacements. Sasol Limited leverages its Fischer-Tropsch heritage to sustain high-purity isoeicosane output from South African gas-to-liquids facilities. INEOS Oligomers competes through backward integration into ethylene feedstocks, anchoring cost positions across European personal-care supply chains. Dow Chemical Company differentiates via controlled polymerization expertise, extending technical service reach to multinational cosmetic houses seeking formulation stability.
Isoeicosane is a highly branched C20 saturated hydrocarbon synthesized through oligomerization or wax cracking routes, typically exhibiting a boiling point near 330°C and a viscosity below 10 cSt at 40°C, valued chiefly as a non-volatile emollient and solvent in topical preparations. The emollient segment dominates value capture in personal-care applications where sensory profiles command premium positioning over commodity mineral oils. Solvent-grade material leads volume throughput in industrial coatings and agrochemical dispersions, though margin pools remain thinner than in cosmetic-grade refining. Fuel additive applications occupy a narrower niche, with demand tied to specific cold-flow improver formulations for middle-distillate upgrading.
EPA oversight under the Toxic Substances Control Act shapes import and domestic manufacturing requirements for hydrocarbon substances in the United States, while ECHA REACH registrations govern substance identity and hazard communication across European supply chains. China's MEE enforces emission controls on paraffin production clusters that indirectly constrain isoeicosane precursor availability. Japan's METI chemical substance classifications influence market access timelines for novel cosmetic raw materials. Stakeholders must monitor evolving biobased labeling standards and carbon intensity disclosures that threaten to recategorize fossil-derived emollients in premium personal-care positioning.
Market Dynamics
Cosmetic formulators are abandoning cyclosiloxane emollients under regulatory pressure, redirecting procurement toward branched C20 alkanes as functionally equivalent replacements in premium skin-care formulations.
Growth Catalysts
- REACH Annex XVII restrictions on D4/D5/D6 cyclosiloxanes:EU cosmetic manufacturers must reformulate rinse-off and leave-on products by mandated deadlines, creating immediate pull for isoeicosane as a sensory-matched silicone alternative.
- Fischer-Tropsch synthesis advancement:Gas-to-liquids facilities now yield cosmetic-grade purity at scale, expanding available supply for personal-care applications previously constrained by wax-cracking yield limitations.
- China's personal-care export manufacturing:Contract manufacturers serving international beauty brands are scaling domestic emollient procurement to meet clean-label requirements from European and North American clients.
Market Restraints
- Feedstock concentration in South African GTL complexes:Overreliance on Sasol's Secunda and Mossel Bay facilities exposes supply chains to regional energy instability and logistics bottlenecks.
- Biobased certification complexity:Fossil-derived isoeicosane faces recategorization risk under emerging EU Green Deal carbon intensity disclosures for premium cosmetic positioning.
- Polyalphaolefin substitution in industrial solvents:PAO manufacturers are targeting coatings and agrochemical dispersion markets with comparable viscosity profiles at lower per-unit costs.
Strategic Opportunities
- Indian domestic cosmetic brand expansion:Local formulators in Mumbai and Bengaluru are seeking non-silicone emollients for ayurveda-inspired skin-care lines targeting middle-class consumers.
- Japan METI chemical substance fast-track classification:Accelerated approval pathways for pre-registered cosmetic raw materials reduce market access timelines from 18 months to 6 months for compliant suppliers.
- Sustainable aviation fuel co-production synergies:GTL facilities can configure Fischer-Tropsch output toward isoeicosane during off-peak jet fuel demand cycles, improving asset utilization.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in silicone-to-hydrocarbon substitution lags behind regulatory deadlines, extending product development cycles.
- Multi-jurisdiction purity standard harmonization:Divergent EPA TSCA, ECHA REACH, and China MEE specifications force redundant testing protocols for global cosmetic ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoeicosane Market |
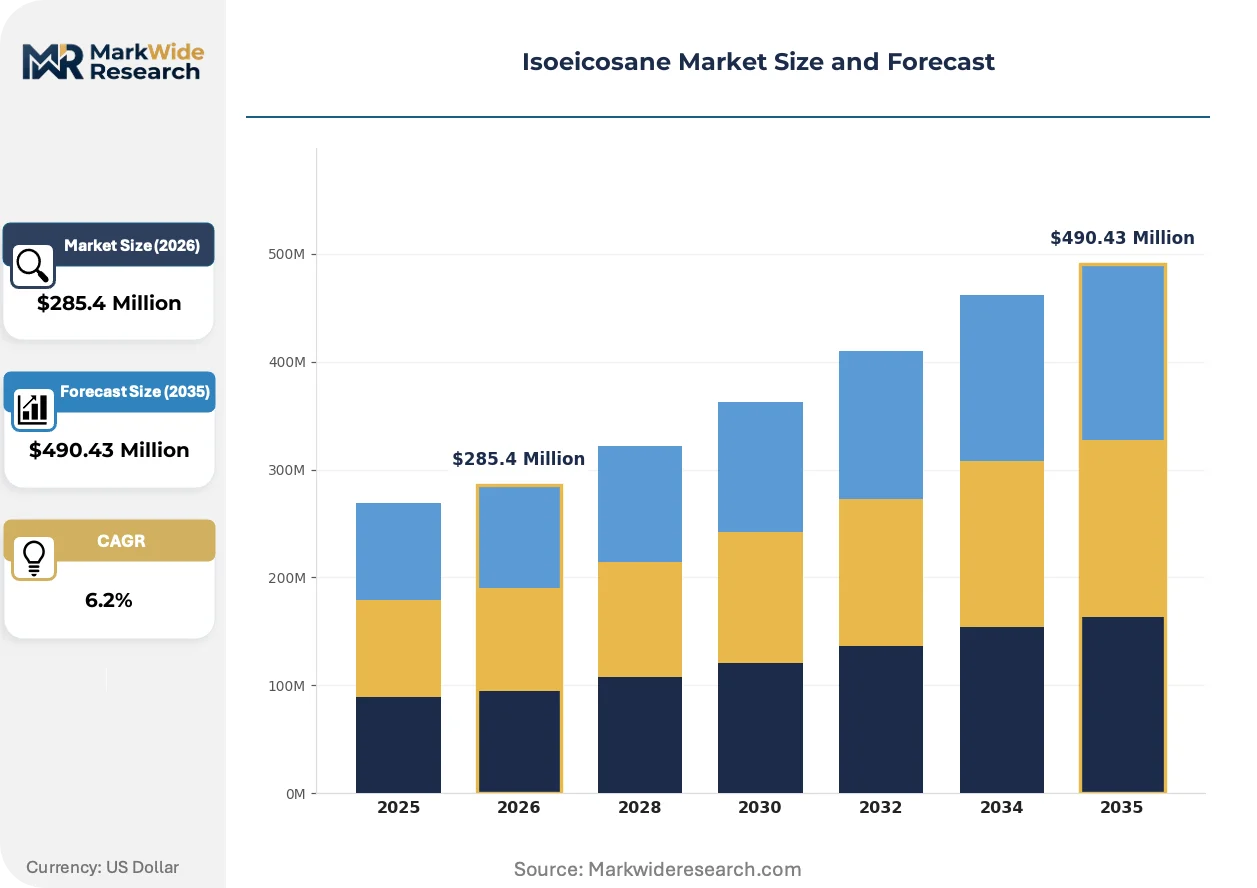
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Emollient, Fuel Additive, Lubricant End User: Automotive, Cosmetics, Pharmaceuticals, Agriculture Application: Personal Care, Industrial Lubrication, Coatings, Agrochemicals Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Innospec Inc., INEOS Oligomers, Sasol Limited, Presperse, Givaudan Active Beauty, Dow Chemical Company, Exxon Mobil Corporation, LANXESS, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoeicosane Market Strategic Shifts & Innovations
Formulation science is pivoting toward sensory-engineered hydrocarbon emollients as silicone replacements, while regulatory chemistry is tightening substance identity requirements across cosmetic supply chains.
Membrane filtration and molecular distillation is decentralizing high-purity isoeicosane production away from integrated GTL megacomplexes toward regional specialty refiners. Mid-scale processors in Germany and the United States are installing supercritical extraction units to upgrade technical-grade paraffin streams into cosmetic-grade material. This capability diffusion is compressing minimum efficient scale thresholds and enabling formulators to source from multiple qualified suppliers rather than single-source dependencies.
ECHA's 2024 updates to REACH registration dossiers for hydrocarbon substances are mandating enhanced analytical characterization of C20 isomer distribution patterns. Cosmetic-grade suppliers must now submit detailed chromatographic fingerprinting to demonstrate batch-to-batch consistency in branching ratios. European personal-care contract manufacturers are responding by tightening supplier qualification audits and demanding certificate-of-analysis transparency that was previously standard only in pharmaceutical excipient supply.
Clean-label procurement is consolidating ingredient selection authority from regional formulators toward central sustainability offices at multinational cosmetic houses. These procurement functions are imposing carbon intensity scoring on emollient purchases, favoring suppliers with verified Scope 1-3 disclosures. The shift is most visible in France and California, where beauty brands are marketing hydrocarbon-derived emollients as "silicone-free" while simultaneously screening fossil-origin feedstocks for climate impact alignment.
Isoeicosane Market Segmentation
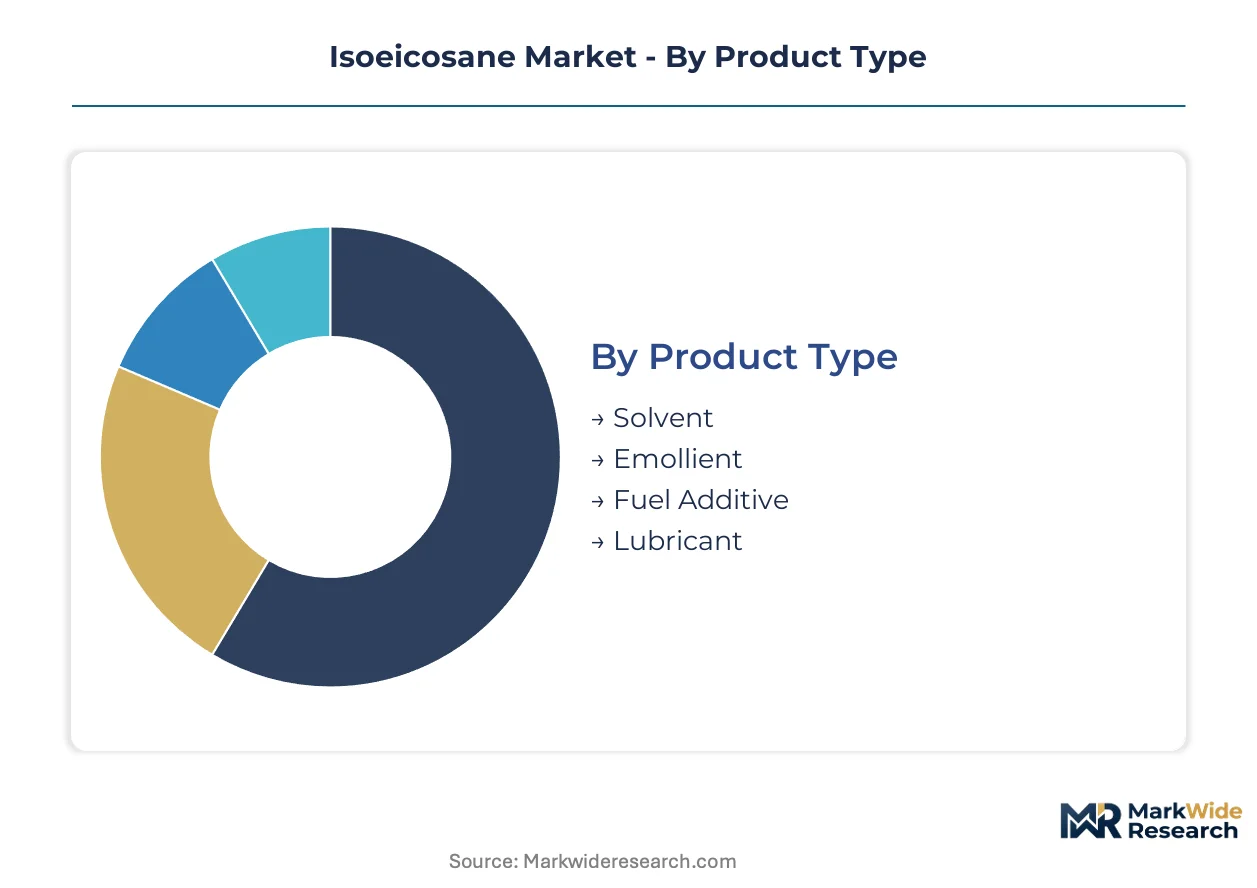
Segmentation in the Isoeicosane Market reveals how purity grades and application specifications fragment procurement patterns across cosmetic, industrial, and specialty fuel end-uses. Each dimension exposes distinct margin structures, regulatory exposures, and supplier qualification thresholds that shape competitive positioning.
Product Type:
Customization intensity spans from commodity solvent specifications to pharmaceutical-grade emollient certifications, with each tier demanding different upstream process controls and analytical documentation.
- Emollient:Cosmetic-grade branched C20 alkane with controlled isomer distribution and sub-ppm aromatic content, refined through molecular distillation or supercritical extraction. Demand concentrates in European and Chinese skin-care formulators replacing cyclosiloxanes under REACH Annex XVII deadlines.
- Solvent:Technical-grade hydrocarbon fluid with broader boiling range tolerance, serving industrial coatings and agrochemical dispersion applications. Procurement from South African GTL facilities dominates volume throughput, though regional specialty refiners in Germany and the United States are installing membrane filtration capacity.
- Fuel Additive:Narrow-application cold-flow improver for middle-distillate upgrading, tied to specific diesel and jet fuel formulation requirements.
- Lubricant:Base oil component for synthetic and semi-synthetic industrial lubricant blends, competing with polyalphaolefin alternatives on viscosity index and oxidative stability.
Leading the category by volume: Solvent. Expanding most quickly: Emollient.
End User:
Margin capture varies sharply across end-user categories, with pharmaceutical and cosmetic applications commanding analytical certification premiums over automotive and agricultural commodity procurement.
- Cosmetics:Premium skin-care and color cosmetic manufacturers in France, California, and Shanghai seeking silicone-free emollient alternatives with verified carbon intensity disclosures.
- Pharmaceuticals:Topical drug formulation houses requiring GMP-compliant excipient documentation and batch-to-batch chromatographic fingerprinting under ECHA REACH dossier updates.
- Automotive:Lubricant blenders and fuel additive formulators sourcing technical-grade material on viscosity and pour-point specifications rather than trace impurity profiles.
- Agriculture:Agrochemical dispersion manufacturers integrating isoeicosane as carrier solvent for crop protection actives, price-sensitive to polyalphaolefin substitution threats.
Widest margin pool: Cosmetics. Steepest regulatory climb: Pharmaceuticals.
Application:
Application segmentation tracks how formulation science requirements diverge between sensory-engineered personal care and performance-specified industrial uses.
- Personal Care:Skin-care serums, color cosmetics, and sun care formulations demanding non-volatile emollients with specific spreadability and skin-feel profiles. Procurement authority is consolidating into central sustainability offices at multinational cosmetic houses in France and California.
- Industrial Lubrication:Synthetic lubricant base stocks and metalworking fluids where oxidative stability and viscosity index determine specification compliance.
- Coatings:Architectural and industrial paint formulations using isoeicosane as coalescing aid or flow modifier, competing with oxygenated solvents on volatile organic compound regulations.
- Agrochemicals:Pesticide and herbicide dispersion carriers where solvency power and environmental fate profiles influence registration acceptance by EPA and PMRA.
Highest purity threshold: Personal Care. Largest volume throughput: Industrial Lubrication.
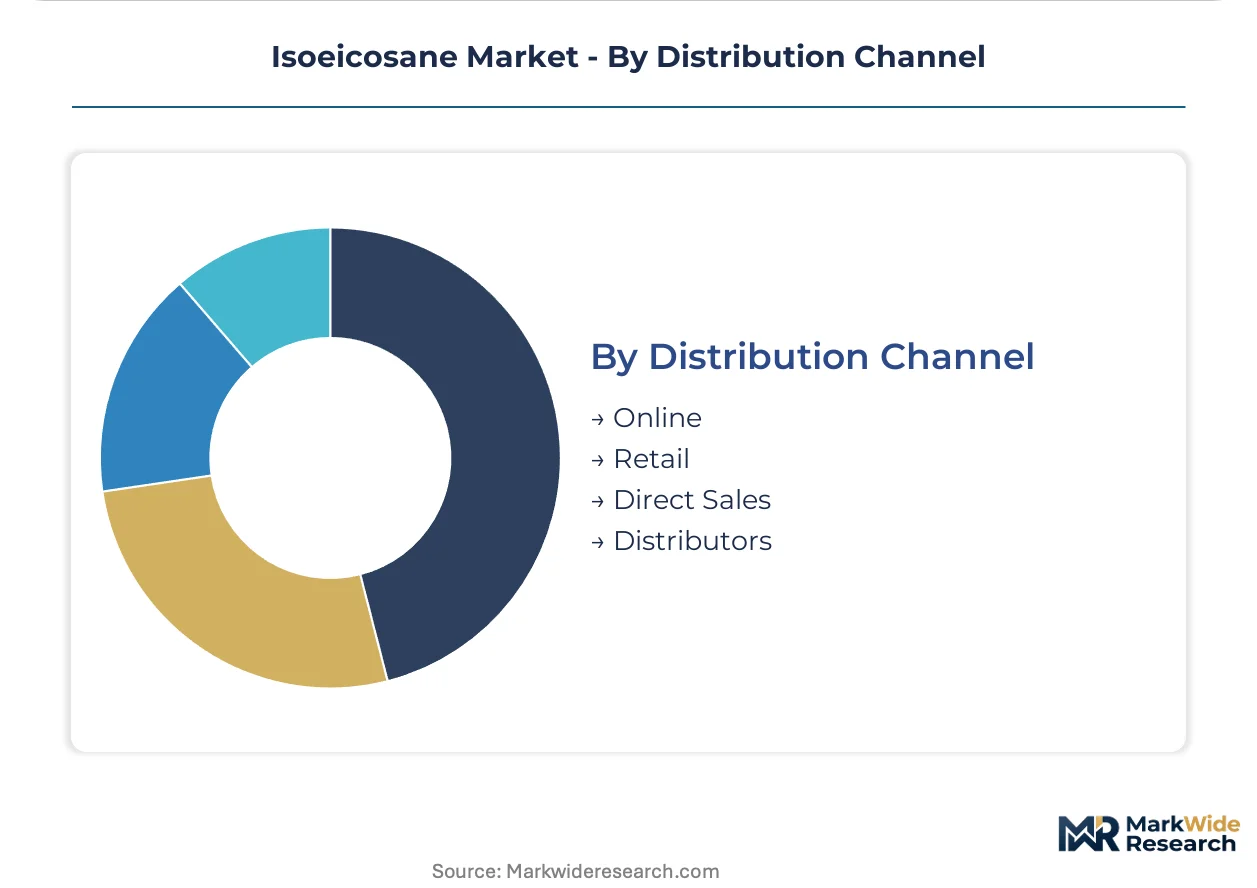
Distribution Channel:
Channel selection reflects customer scale and documentation intensity, with direct relationships dominating qualified cosmetic supply and distributor networks serving fragmented industrial accounts.
- Direct Sales:Long-term supply agreements between GTL producers and multinational cosmetic houses or lubricant blenders, embedding technical service and joint formulation development.
- Distributors:Regional chemical distributors stocking technical-grade solvent and lubricant material for mid-scale coatings and agrochemical formulators across Germany, the United States, and India.
- Online:Emerging procurement channel for sample quantities and small-batch cosmetic-grade material, particularly among Indian domestic brands and Japanese specialty formulators.
- Retail:Minimal presence, limited to specialty chemical retailers serving research institutions and independent cosmetic chemists.
Dominant channel by value: Direct Sales. Fastest channel expansion: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors procurement acceleration for isoeicosane emollients as Chinese contract manufacturers scale output for European and North American beauty brands. Domestic production clusters in Jiangsu and Zhejiang provinces now supply both local personal-care formulators and export-oriented compounders seeking REACH-compliant alternatives to cyclosiloxanes.
China
Cosmetic-grade demand concentrates in skin-care serums and color cosmetics manufactured for international clean-label requirements. MEE emission controls on paraffin production clusters indirectly constrain precursor availability for branched alkane synthesis. The Yangtze River Delta corridor, spanning Shanghai and surrounding Jiangsu manufacturing zones, hosts expanding molecular distillation capacity serving both domestic brands and contract manufacturers.
United States
California-based sustainability offices at multinational cosmetic houses impose carbon intensity scoring on emollient procurement, screening fossil-origin feedstocks for climate alignment. EPA oversight under TSCA shapes import and domestic manufacturing requirements for hydrocarbon substances in topical applications. The Pacific Northwest and Northeast Corridor host specialty refiners installing supercritical extraction units to upgrade technical-grade paraffin streams.
Germany
ECHA's 2024 REACH registration dossier updates mandate enhanced analytical characterization of C20 isomer distribution patterns for cosmetic-grade suppliers. Personal-care contract manufacturers tighten supplier qualification audits and demand certificate-of-analysis transparency previously standard only in pharmaceutical excipient supply. The North Rhine-Westphalia chemical corridor anchors regional specialty refining capacity serving European formulators.
Japan
METI chemical substance classifications influence market access timelines for novel cosmetic raw materials, with accelerated approval pathways reducing entry periods for compliant suppliers. Formulators in Osaka and Tokyo seek sensory-matched silicone alternatives for premium skin-care lines targeting domestic middle-class consumers. The Kansai region hosts technical service operations supporting multinational cosmetic houses.
India
Domestic cosmetic brands in Mumbai and Bengaluru seek non-silicone emollients for ayurveda-inspired skin-care lines targeting expanding middle-class consumption. BIS standards for cosmetic raw materials create qualification thresholds for imported branched alkane grades. The Maharashtra-Gujarat industrial corridor attracts distributor investment for technical-grade solvent and lubricant material serving fragmented coatings and agrochemical accounts.
Isoeicosane Market Key Industry Players
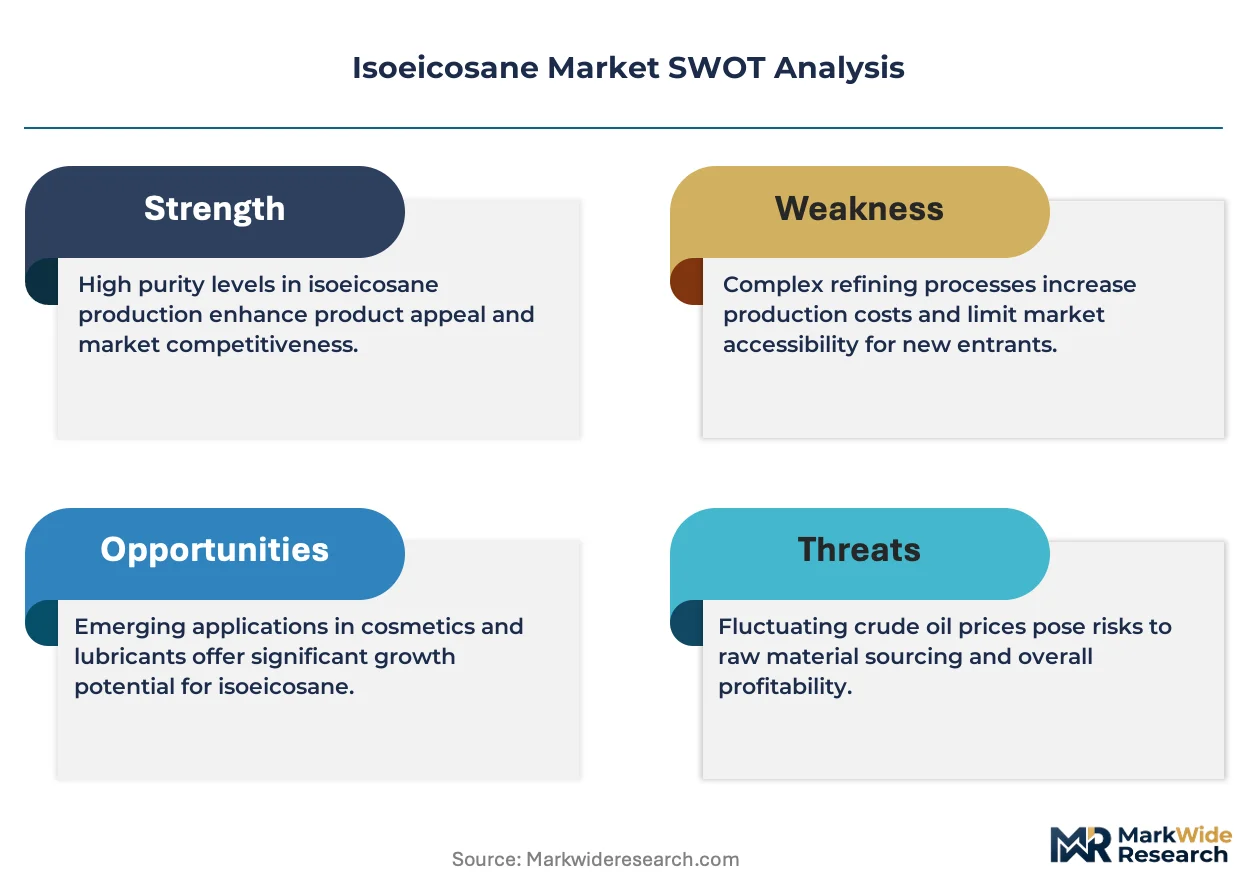
Premium-margin players sit above commodity-margin players across purity-grade and certification-intensity dimensions. The market structures around three tiers: integrated gas-to-liquids producers commanding cosmetic-grade output, petrochemical majors with backward integration into ethylene feedstocks, and regional specialty refiners deploying membrane filtration for technical-grade material. Consolidation pressures concentrate among GTL-dependent suppliers exposed to single-source geographic risk, while capability diffusion enables mid-scale processors to compress minimum efficient scale thresholds. Dominant competitive moves include capacity expansion in Fischer-Tropsch synthesis and strategic partnerships embedding technical service into long-term supply agreements.
Among integrated GTL producers, Sasol Limited and INEOS Oligomers exemplify archetypes anchored in gas-to-liquids heritage and ethylene feedstock control respectively. Sasol represents the Fischer-Tropsch synthesis advancement tier sustaining high-purity output from South African facilities, while INEOS occupies a position defined by backward integration into European personal-care supply chains. Dow Chemical Company sits within the controlled polymerization expertise tier, extending technical service reach to multinational cosmetic houses. These three anchors illustrate how supplier qualification now hinges on chromatographic fingerprinting capabilities and Scope 1-3 disclosure verification rather than volume scale alone.
| Leading Market Players |
|---|
| Innospec Inc. |
| INEOS Oligomers |
| Sasol Limited |
| Presperse |
| Givaudan Active Beauty |
| Dow Chemical Company |
| Exxon Mobil Corporation |
| LANXESS |
| Nouryon |
| Others |
Cost & Logistics Intelligence
Backward integration into Fischer-Tropsch synthesis anchors Sasol's supply position and pricing power across cosmetic-grade isoeicosane, while INEOS's ethylene feedstock control secures parallel leverage in European personal-care supply chains. This upstream concentration enables volume-tiered contracting that compresses margins for non-integrated regional refiners.
Pricing Analysis
Value-based pricing anchored to formulation stability outcomes dominates cosmetic-grade procurement, with multinational cosmetic houses in France and California paying premiums for verified carbon intensity disclosures and chromatographic fingerprinting. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade material reflects certification burden and analytical documentation intensity. Cost compression in technical-grade solvent tiers is intensifying because polyalphaolefin manufacturers are targeting coatings and agrochemical dispersion markets. Agrochemical formulators exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
Isoeicosane supply rests on South African gas-to-liquids complexes, German specialty refiners, and Chinese molecular distillation installations in Jiangsu and Zhejiang provinces. Fischer-Tropsch synthesis output, ethylene oligomerization feedstocks, and wax-cracking paraffin streams constitute the primary input dependencies. Single-source vulnerability concentrates around Sasol's Secunda and Mossel Bay facilities, exposing chains to regional energy instability. Distribution runs through long-term direct sales agreements for qualified cosmetic supply, with regional chemical distributors serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated GTL producers and backward-integrated petrochemical majors, with ECHA's enhanced REACH characterization requirements forcing weaker regional refiners toward exit or acquisition.
For Market Incumbents: Anticipate polyalphaolefin substitution threats in industrial solvent tiers by deepening analytical service capabilities and embedding technical staff within multinational cosmetic houses. Prioritize capacity addition in China to serve contract manufacturers scaling for European clean-label requirements. Secure REACH dossier pre-registration advantages to compress competitor market access timelines. For New Entrants and Emerging Players: Capture white-space in Indian domestic cosmetic brands seeking silicone-free emollients for ayurveda-inspired skin-care lines, where BIS qualification thresholds remain less stringent than ECHA equivalents. Penetrate Japan through METI fast-track classification pathways for pre-registered cosmetic raw materials. Lead with supercritical extraction technology partnerships to bypass GTL scale disadvantages. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated petrochemical majors seeking cosmetic-grade certification capabilities and geographic diversification beyond South African supply concentration. Five-to-ten year viability favors processors with verified Scope 1-3 disclosure infrastructure and molecular distillation asset bases. Watch ECHA carbon intensity disclosure enforcement as inflection indicator for fossil-derived emollient recategorization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstocks | INEOS anchors cost positions across European personal-care supply chains through captive olefin supply. |
| Fischer-Tropsch Capacity Expansion | Sasol sustains cosmetic-grade purity output from South African GTL facilities serving REACH-compliant formulators. |
| Supercritical Extraction Technology Deployment | Mid-scale German and US processors compress minimum efficient scale thresholds for technical-grade upgrading. |
| Long-term Supply Agreement with Multinational Cosmetic Houses | Dow extends technical service reach through embedded formulation stability expertise. |
| Joint Venture for Chinese Molecular Distillation Capacity | Regional processors in Jiangsu serve domestic brands and export-oriented contract manufacturers simultaneously. |
Research Approach
Multi-period observation of ECHA REACH registration timelines, EPA TSCA import volumes, and China MEE emission control enforcement anchored the trend analysis, supplemented by interviews with Fischer-Tropsch plant managers, cosmetic formulation chemists, and procurement leads at multinational personal-care houses. Secondary validation drew from customs trade data, SEC 10-K chemical segment disclosures, and Cefic high-purity hydrocarbon reports. Bottom-up triangulation across grade-tier production estimates converged with top-down personal-care emollient demand modeling.
An input-output matrix framework mapped Fischer-Tropsch synthesis yields, ethylene oligomerization throughput, and wax-cracking paraffin availability against cosmetic-grade, pharmaceutical-grade, and technical-grade demand segments across the projection horizon. Segmentation dimensions included purity tier, end-use industry concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating silicone substitution velocity and clean-label procurement consolidation. Forecast inputs incorporated REACH Annex XVII compliance deadlines and METI accelerated approval pathway utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon intensity disclosure enforcement and biobased certification complexity that could recategorize fossil-derived emollients. Forecasts reflect documented assumptions regarding regulatory deadline adherence and substitution technology performance parity. A small set of named triggers—including ECHA hydrocarbon substance reclassification, South African energy grid instability, and polyalphaolefin viscosity index advancement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Isostearyl Alcohol Market