
 APAC Semiconductor Device in Consumer Industry Market | 2026-2036
APAC Semiconductor Device in Consumer Industry Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Semiconductor Device in Consumer Industry Market Insights
Component refurbishment and second-life chip recovery is rewriting margin economics for consumer semiconductor suppliers. Samsung Electronics Co. Ltd leverages captive memory fabrication to sustain pricing power across smartphone and smart TV verticals. TSMC Limited anchors advanced node production for fabless consumer chip designers, while SK Hynix Inc. competes aggressively in high-bandwidth memory stacks for wearables and laptops.
APAC semiconductor devices in the consumer industry encompass integrated circuits fabricated on silicon wafers ranging from 28 nanometer to 3 nanometer process nodes, designed to process, store, or transmit signals in mass-market electronic goods. These devices primarily enable computation, sensing, power conversion, and wireless connectivity across portable and home-based consumer systems. Power Management ICs dominate unit shipments due to universal deployment across battery-operated devices, while RF segments capture premium pricing from 5G smartphone complexity. Mixed-Signal technology leads design activity as consumer products demand seamless analog-digital interfaces for audio, touch, and biometric functions.
Japan's METI directs industrial policy toward semiconductor reshoring through facility subsidies and supply chain security frameworks. China's MIIT enforces GB standards and dual carbon goals that constrain foundry energy intensity while promoting domestic equipment sourcing. South Korea's MFDS and K-Battery regulations indirectly shape semiconductor demand through battery safety mandates that require tighter power management integration. Stakeholders must monitor how divergent subsidy regimes across Seoul, Tokyo, and Beijing reshape cost structures for cross-border chip procurement.
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is forcing consumer semiconductor buyers to diversify procurement geography while absorbing advanced node premiums for smartphone and AI-enabled wearables.
Growth Catalysts
- 5G RF Front-End Complexity:Smartphone OEMs across China and India require multi-band power amplifiers and filter banks, expanding discrete component demand per device.
- Japan's METI Subsidy Framework:Facility construction grants for legacy node fabrication are reshoring consumer PMIC supply chains previously dependent on Taiwanese foundries.
- India's PLI Scheme:Smartphone assembly localization mandates are pulling upstream semiconductor packaging and testing operations into Gujarat and Tamil Nadu industrial corridors.
Market Restraints
- Advanced Lithography Equipment Access:Dutch and Japanese export controls on EUV and DUV systems constrain Chinese foundry progression below 7 nanometer nodes for consumer AI accelerators.
- Silicon Wafer Price Volatility:300mm prime-grade substrate contracts exhibit 15-20% quarterly swings, compressing IDM gross margins on memory and logic products.
- Geographic Concentration Risk:90% of leading-edge foundry output originates from Taiwan's Hsinchu Science Park, exposing consumer electronics supply chains to single-point disruption.
Strategic Opportunities
- Vietnam and Indonesia Assembly Migration:Labor cost arbitrage and tariff mitigation are attracting smartphone and laptop OEMs to establish captive semiconductor warehousing and last-mile configuration.
- Chiplets and 3D Integration:Die disaggregation enables cost-effective mixing of mature and advanced nodes in consumer SoCs, opening fabless design opportunities without full node migration.
- China's Dual Carbon Enforcement:Foundry energy intensity regulations are accelerating renewable-powered fabrication investments in Sichuan and Yunnan provinces with hydroelectric surplus.
Industry Challenges
- Packaging Engineer Scarcity:Fan-out wafer-level packaging and hybrid bonding expertise concentrates in Taiwan and South Korea, constraining China's domestic advanced packaging ramp.
- Multi-Jurisdiction Compliance Burden:Simultaneous navigation of China's GB standards, South Korea's K-Battery regulations, and Japan's JIS certification creates product qualification timeline fragmentation.
- Legacy Node Depreciation Pressure:28 nanometer and above capacity expansion in China is eroding utilization rates and pricing power for established Taiwanese and Japanese foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Semiconductor Device in Consumer Industry Market |
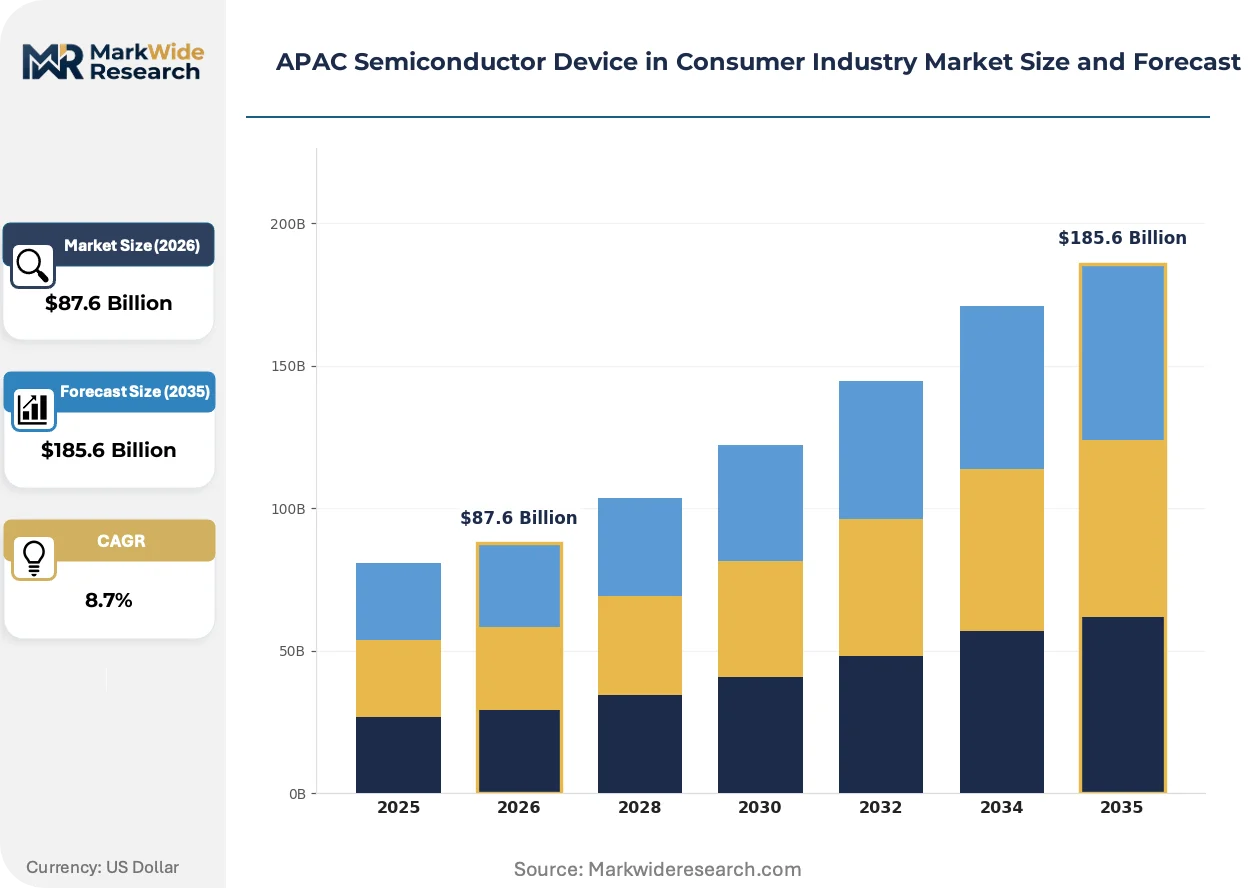
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Sensors, Amplifiers, Power Management ICs End User: Consumer Electronics, Automotive Electronics, Industrial Devices, Home Appliances Technology: Analog, Digital, Mixed-Signal, RF Application: Smartphones, Laptops, Wearables, Smart TVs |
| Companies Covered | Taiwan Semiconductor Manufacturing Company (TSMC) Limited, Samsung Electronics Co. Ltd, SK Hynix Inc., Toshiba Corporation, STMicroelectronics NV, NXP Semiconductors NV, Intel Corporation, Renesas Electronics Corporation, Kyocera Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Semiconductor Device in Consumer Industry Market Trends and Innovations
Silicon-to-substrate integration architectures and regulatory energy mandates are compressing design cycles while fragmenting procurement geography across the APAC consumer semiconductor supply base.
Gallium nitride power transistors are replacing silicon MOSFETs in smartphone fast-charging circuits and laptop adapter designs. Chinese OEMs including Xiaomi and Oppo have adopted GaN-based 65W-120W chargers since 2021, rendering obsolete traditional silicon-based power delivery topologies below 100W. This displacement is compressing BOM costs while enabling smaller form factors that differentiate premium device tiers.
China's MIIT enforcement of GB 4943.1-2022 safety standards and energy efficiency labeling is mandating standby power consumption below 0.5W for consumer electronics. Foundries serving domestic brands must now certify process nodes against electromagnetic compatibility and thermal runaway protocols previously voluntary. South Korean and Japanese component suppliers are establishing in-country testing facilities to maintain access without cross-border certification delays.
Direct foundry contracting is displacing traditional distributor intermediation for high-volume smartphone and tablet manufacturers. ByteDance, Transsion, and BBK Electronics subsidiaries are negotiating wafer starts directly with TSMC, Samsung Foundry, and SMIC, bypassing Avnet and Arrow Electronics for 40% of their PMIC and SoC procurement. This channel compression is most visible in Shenzhen and Dongguan procurement offices where supplier relationship managers now embed inside OEM headquarters.
APAC Semiconductor Device in Consumer Industry Market Segmentation
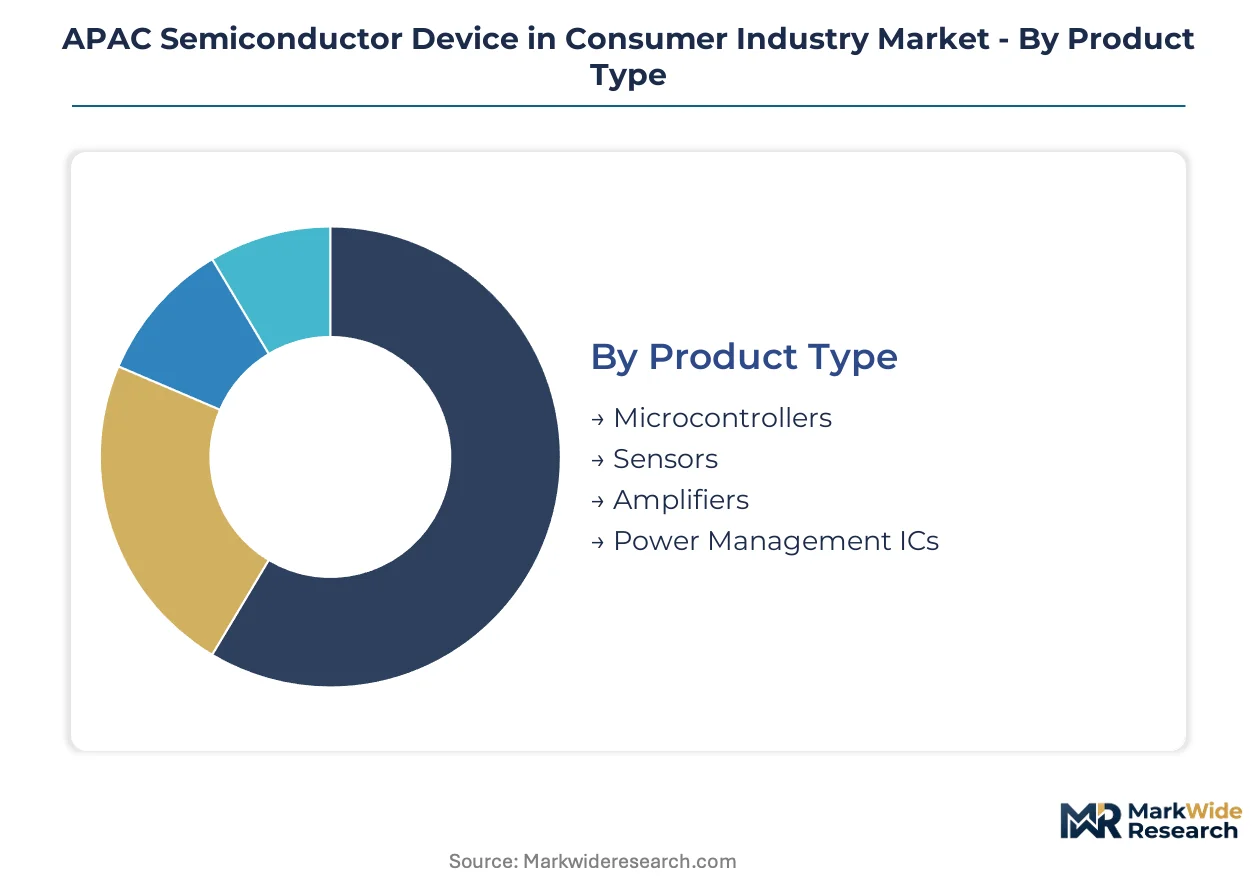
Segmentation in the APAC consumer semiconductor market reveals how process node specialization, power architecture requirements, and end-use form factors create distinct procurement corridors. Buyers optimize supplier relationships differently across each dimension, with smartphone OEMs demanding advanced node access while appliance manufacturers prioritize cost-optimized mature processes.
Product Type:
Mature analog and power segments coexist with emerging sensor architectures as battery-operated devices multiply across the region.
- Microcontrollers:ARM Cortex-M and RISC-V cores dominate 32-bit implementations for touch interfaces and motor control in smart appliances. Chinese foundries including SMIC and Hua Hong are expanding 40-90nm MCU capacity to serve domestic white-goods manufacturers in Guangdong and Zhejiang provinces facing import substitution mandates.
- Sensors:Inertial measurement units, ambient light sensors, and fingerprint modules integrate MEMS fabrication with CMOS readout circuits. Demand clusters in Shenzhen and Seoul for smartphone camera stabilization and wearable health monitoring, though packaging yield challenges constrain margin expansion.
- Amplifiers:Class-D audio amplifiers and operational amplifiers process analog signals for smart TV and laptop audio subsystems.
- Power Management ICs:Voltage regulators, battery chargers, and DC-DC converters enable efficient energy distribution across portable devices.
Power Management ICs retain volume leadership; Sensors hold the steepest expansion curve.
End User:
Cost tier stratification separates high-volume consumer electronics from price-sensitive appliance segments with diverging qualification timelines.
- Consumer Electronics:Smartphones, tablets, and laptops drive leading-edge node demand and account for the majority of RF and application processor procurement. Samsung and Xiaomi anchor wafer commitments at TSMC and Samsung Foundry, while Indian PLI beneficiaries including Dixon and Lava International are localizing PCB assembly and chip-on-board operations.
- Automotive Electronics:Infotainment systems and ADAS modules consume consumer-grade semiconductors repurposed under AEC-Q100 stress testing. Japanese tier-1 suppliers including Denso and Panasonic source PMICs and MCUs through dual-qualified foundries in Taiwan to satisfy Toyota and Honda traceability requirements.
- Industrial Devices:Programmable logic controllers and industrial IoT gateways employ extended-temperature-range semiconductors.
- Home Appliances:Refrigerators, washing machines, and air conditioners integrate motor control ICs and touch controllers at 28-130nm nodes.
Consumer Electronics commands the revenue concentration; Automotive Electronics is gaining share fastest as cockpit digitization accelerates.
Technology:
Application requirements dictate whether discrete analog, pure digital, or integrated mixed-signal approaches minimize BOM complexity and power consumption.
- Analog:Continuous signal processing for audio, power conversion, and sensor interfaces relies on specialized BCD (Bipolar-CMOS-DMOS) processes. Tower Semiconductor and Vanguard International maintain capacity leadership for high-voltage analog in Israel and Taiwan, though Chinese foundries are adding 200mm BCD lines in Wuxi and Hefei.
- Digital:Logic gates, memory arrays, and processor cores execute computation at 5-28nm nodes for smartphone SoCs and laptop chipsets. Access to EUV lithography restricts sub-7nm production to TSMC and Samsung Foundry, creating supply bottlenecks for Chinese fabless designers.
- Mixed-Signal:Data converters and touchscreen controllers merge analog front-ends with digital signal processing.
- RF:Power amplifiers, switches, and filter banks manage wireless transmission across 5G sub-6GHz and mmWave bands.
Digital technology captures the premium pricing tier; RF is expanding most quickly with 5G band proliferation.
Application:
Geography of final assembly shapes procurement patterns as Vietnam and India attract smartphone manufacturing migration from coastal China.
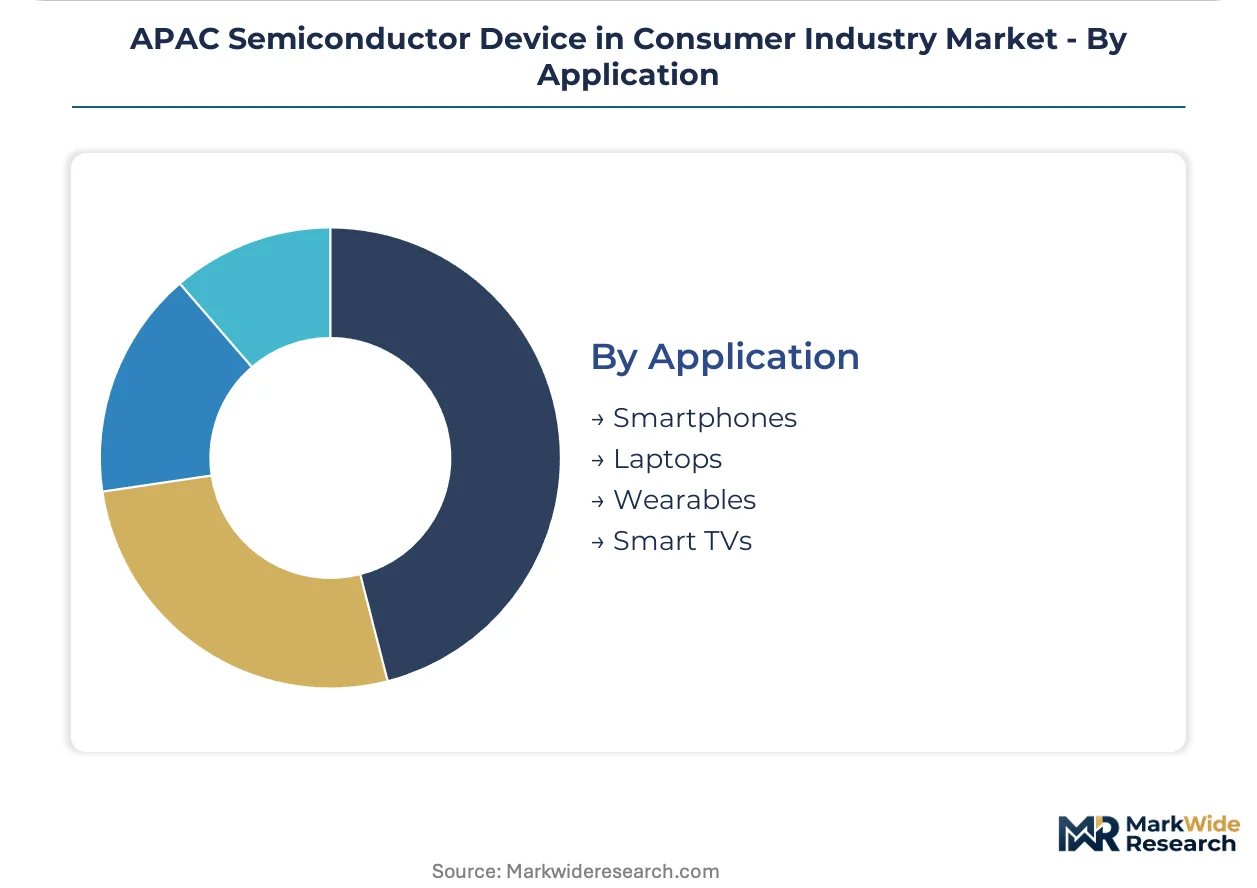
- Smartphones:Application processors, modem-baseband SoCs, and camera ISPs require 4-7nm finFET processes and advanced packaging. Apple and Qualcomm reserve TSMC N3E capacity through 2026, while MediaTek and UNISOC diversify across TSMC and SMIC for mid-tier 5G chipsets targeting India and Southeast Asia.
- Laptops:x86 and ARM-based compute platforms, alongside discrete GPUs and memory controllers, consume mature and advanced nodes. Taiwanese ODMs including Quanta and Compal concentrate motherboard assembly in Chongqing and Mexico, sourcing PMICs and USB-C controllers from Richtek and ON Semiconductor.
- Wearables:Ultra-low-power MCUs and Bluetooth SoCs enable fitness bands and smartwatches.
- Smart TVs:Media processors and display timing controllers drive 4K and 8K resolution support.
Smartphones maintains the wafer volume dominance; Wearables posts the steepest unit growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Vietnam exhibit acute price sensitivity on mature-node PMICs and MCUs, while Japanese and South Korean OEMs absorb premiums for advanced-node RF and memory components with minimal demand elasticity.
China
Domestic smartphone brands drive wafer demand for 28-7nm application processors and modem SoCs. MIIT enforces GB 4943.1-2022 safety standards and dual carbon goals that constrain foundry energy intensity. The Yangtze River Delta cluster concentrates SMIC and Hua Hong capacity alongside downstream assembly in Suzhou and Wuxi.
Japan
Automotive infotainment and smart appliance OEMs source consumer-grade semiconductors repurposed under AEC-Q100 stress testing. METI directs facility construction grants toward legacy node fabrication reshoring. Kyushu and Tohoku regions host Renesas and Toshiba expansion of 40-90nm analog and power management capacity.
South Korea
Samsung and SK Hynix anchor captive demand for high-bandwidth memory stacks in smartphones and wearables. MFDS battery safety mandates require tighter PMIC integration for consumer electronics. The Seoul Capital Area concentrates advanced packaging and memory fabrication with downstream assembly in Gyeonggi-do.
India
Smartphone assembly localization under PLI schemes pulls upstream packaging and testing into Gujarat and Tamil Nadu. BIS certification requirements and DGFT import substitution mandates accelerate domestic MCU sourcing for white-goods manufacturers. The Delhi-Mumbai Industrial Corridor hosts Dixon and Lava International chip-on-board operations.
Vietnam
Labor cost arbitrage attracts smartphone and laptop OEMs establishing captive semiconductor warehousing for last-mile configuration. General functional descriptors for national trade policy facilitate tariff mitigation for re-export to North American and European markets. The Bac Ninh and Hai Phong industrial zones concentrate Samsung and Apple supplier configuration facilities.
APAC Semiconductor Device in Consumer Industry Market Competitive Landscape
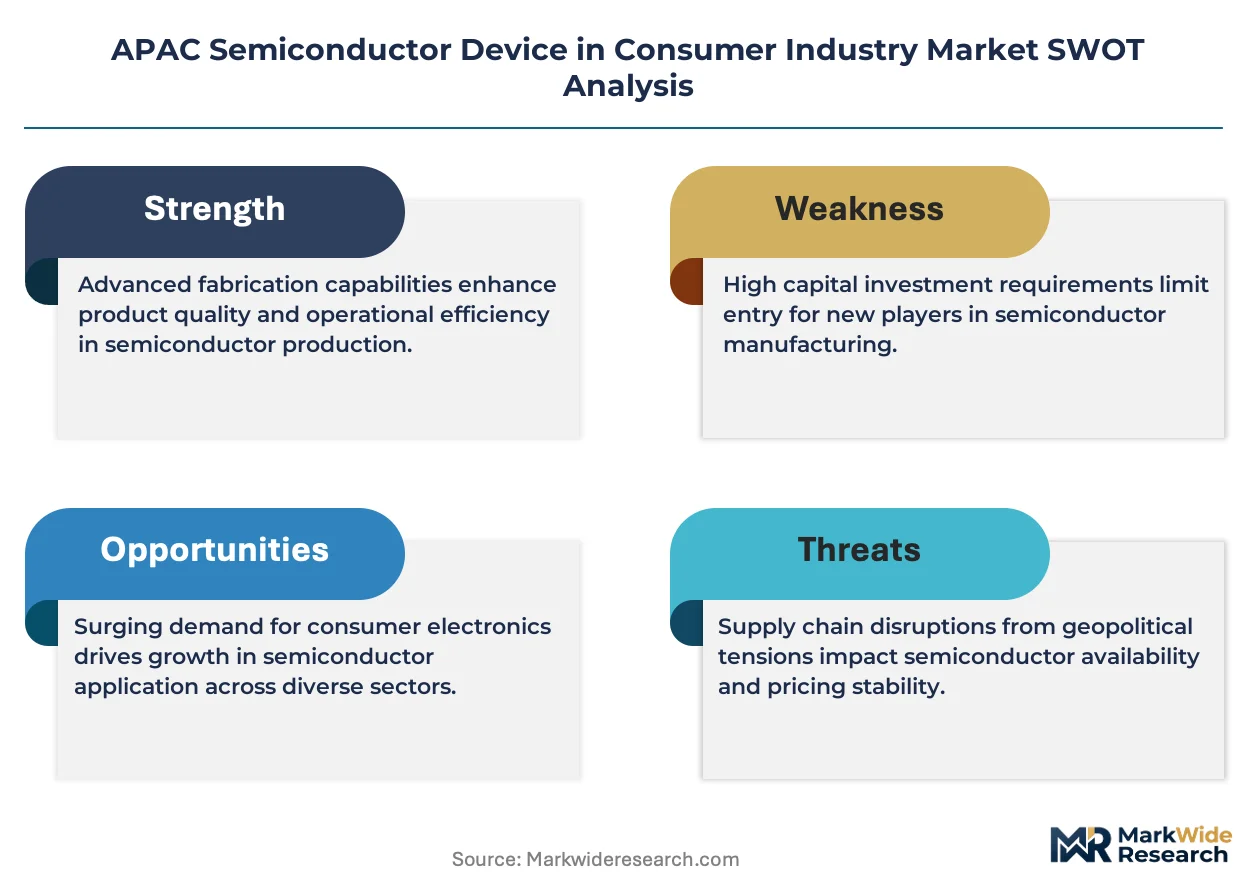
Capability concentration sits with foundry operators commanding EUV lithography access; scale advantage sits with integrated device manufacturers with captive memory fabrication. The market structures around three tiers: pure-play foundries, integrated memory suppliers, and diversified analog-mixed-signal houses. Strategic moves center on die disaggregation partnerships and direct OEM contracting that displaces traditional distribution channels.
Among Taiwan-based pure-play foundries, Taiwan Semiconductor Manufacturing Company Limited anchors advanced node production for fabless consumer chip designers. Samsung Electronics Co. Ltd exemplifies the integrated model with captive memory fabrication sustaining pricing power across smartphone and smart TV verticals. SK Hynix Inc. occupies a position within the high-bandwidth memory specialist tier competing aggressively for wearable and laptop socket wins.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company (TSMC) Limited |
| Samsung Electronics Co. Ltd |
| SK Hynix Inc. |
| Toshiba Corporation |
| STMicroelectronics NV |
| NXP Semiconductors NV |
| Intel Corporation |
| Renesas Electronics Corporation |
| Kyocera Corporation |
| Others |
Pricing and Supply Chain Analysis
Hsinchu Science Park's foundry concentration compresses margin structures for fabless consumer chip designers while amplifying pricing power for EUV-equipped pure-plays serving smartphone OEMs. Taiwan's captive dominance of advanced nodes forces buyers into long-term offtake commitments or spot market exposure, with procurement geography now a primary cost determinant.
Pricing Analysis
Long-term wafer offtake agreements anchor pricing stability for high-volume smartphone and laptop manufacturers, while spot procurement exposes smaller OEMs to 300mm prime-grade silicon substrate volatility. Three-tier pricing structure across premium, standard, and economy levels separates TSMC N3E capacity from Samsung Foundry 4nm and SMIC 28nm respectively. Cost compression in mature nodes is intensifying because Chinese foundry expansion erodes utilization rates at Taiwanese and Japanese competitors. Indian white-goods manufacturers exhibit acute price sensitivity on 40-90nm MCUs, whereas South Korean memory buyers absorb HBM3 premiums with minimal demand elasticity.
Supply Chain Analysis
300mm silicon wafers, EUV lithography systems, and high-purity specialty gases feed from upstream suppliers concentrated in Japan, the Netherlands, and the United States. Taiwan, South Korea, and China house the dominant foundry and memory fabrication capacity, with single-source vulnerability concentrated in Hsinchu Science Park's leading-edge output. Distribution runs through direct foundry contracting that displaces traditional distributor intermediation for 40% of high-volume PMIC and SoC procurement. Tariff exposure escalates as Vietnam and Indonesia assembly migration triggers re-export documentation complexity for North American-bound consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride power transistors threaten silicon MOSFET incumbents in fast-charging applications, forcing legacy suppliers to defend socket position through performance differentiation and cost restructuring.
For Market Incumbents: Entrench advanced packaging capabilities through fan-out wafer-level and hybrid bonding investments in Taiwan and South Korea to offset Chinese foundry competition. Secure captive memory supply agreements with SK Hynix or Samsung Electronics to neutralize HBM pricing volatility for wearable and laptop segments. Deepen backward integration into 300mm silicon wafer sourcing through long-term contracts with Shin-Etsu or SUMCO to buffer substrate cost swings. For New Entrants and Emerging Players: Mid-tier 5G chipset design services for Indian PLI beneficiaries represent the most penetrable entry point, with Dixon and Lava International seeking alternatives to MediaTek dominance. Vietnam-based semiconductor warehousing and last-mile configuration for smartphone OEMs offers asset-light revenue with tariff mitigation value. Pursue direct OEM embedding models in Shenzhen procurement offices rather than traditional distribution channel competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese electronics conglomerates spinning non-core analog and power management divisions. Foundries with 28-40nm BCD process expertise and automotive dual-qualification capability offer durable cash flow visibility across the analysis window. Watch for MIIT enforcement of GB standards accelerating domestic equipment sourcing mandates as inflection signal for China-exposed equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Capacity Reservation | Apple and Qualcomm's TSMC N3E commitments through 2026 lock supply for smartphone application processors. |
| GaN Power Transistor Adoption | Xiaomi and Oppo's 65W-120W charger designs displace silicon MOSFETs and compress BOM costs. |
| Direct Foundry Contracting | ByteDance and Transsion bypass Avnet and Arrow Electronics for 40% of PMIC procurement volume. |
| Dual-Qualified Foundry Partnership | Denso and Panasonic source through Taiwan fabs to satisfy Toyota AEC-Q100 traceability requirements. |
| Renewable-Powered Fabrication | Sichuan and Yunnan hydroelectric surplus attracts foundry investment under China's dual carbon enforcement. |
Research Methodology
A standing panel of foundry operations executives, fabless design house CTOs, smartphone OEM procurement directors, and semiconductor equipment specialists provided ongoing calibration against secondary validation. Primary interviews combined with SEC 10-K filings, customs and trade data, SEMI equipment billings, and foundry capacity announcements enabled bottom-up and top-down triangulation across the APAC consumer semiconductor supply base.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning process node tier, end-use application, and geographic procurement cluster. CAGRs derived from wafer start forecasts, die-per-wafer yield assumptions, and blended average selling price trajectories incorporated foundry utilization rates and equipment lead time inputs specific to EUV and DUV lithography constraints.
Macroeconomic conditions sit as an overlay; deviation in consumer electronics demand cycles, cross-strait geopolitical stability, or Dutch-Japanese export control enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding technology migration timelines and regulatory implementation schedules. Cross-checking against SEMI silicon shipment reports and foundry revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
China MCU Market