
 Europe Shrink and Stretch Sleeve Label Market | 2026-2036
Europe Shrink and Stretch Sleeve Label Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Shrink and Stretch Sleeve Label Market Foresight
Poland is reconfiguring its converting base as several mid-cap film processors add sleeve label capacity to serve Central European beverage bottlers. CCL Industries Inc. leverages backward integration into printed film substrates to secure margin control across the value chain. Huhtamaki Oyj anchors its position through specialized heat-shrink formulations for dairy and juice applications. Amcor Plc competes by extending its preform-to-label systems that reduce line complexity for multinational drinks brands.
Shrink and stretch sleeve labels are full-body decorative and functional wraps, typically manufactured from oriented polyethylene terephthalate glycol or polyolefin films through extrusion, printing, and seaming processes, designed to conform tightly to container contours via heat or elastic recovery while delivering 360-degree graphics and tamper evidence. Shrink labels dominate value capture in carbonated soft drinks and spirits where contour complexity demands high shrink ratios, while stretch labels gain ground in dairy and water segments where elastic recovery and recyclability favor mono-polyethylene constructions. Tamper evident labels command premium positioning in pharmaceutical and premium beverage end uses where regulatory compliance and brand protection justify higher unit economics.
REACH and the EU Green Deal shape material compliance pathways, with ECHA restrictions on PVC additives accelerating converter migration toward PET and polypropylene substrates. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility thresholds that favor sleeve designs compatible with container recycling streams. EFSA migration limits for food-contact layers constrain ink and adhesive selection, particularly for hot-fill and retort beverage applications. Stakeholders must monitor mono-material certification progress and sortation infrastructure investments as sorting technology compatibility becomes the decisive factor for sleeve label specification wins.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to reengineer sleeve constructions around mono-material PET and polyethylene substrates, eliminating multi-layer barrier films that complicate mechanical recycling streams.
Growth Catalysts
- PPWR Recyclability Mandates:Extended producer responsibility thresholds favor sleeve designs compatible with container recycling streams, accelerating specification wins for mono-material constructions across German and French beverage bottling clusters.
- Carbonated Soft Drinks:Contour complexity in premium spirits and CSD bottles demands high-shrink-ratio PETG films, sustaining value capture in applications where 360-degree graphics justify unit economics premiums.
- Munich-Hamburg Bottling Corridor:Concentrated demand from multinational drinks brands around these hubs drives premium sleeve specifications and justifies specialized heat-shrink capacity investments.
Market Restraints
- Ethylene Feedstock Volatility:Polyolefin substrate costs track naphtha and ethylene spreads, compressing converter margins during energy price spikes without contractual pass-through mechanisms.
- PVC Additive Phase-Out:ECHA restrictions on plasticizers and stabilizers eliminate legacy substrate options, forcing capital-intensive equipment retooling for converters with stranded PVC sleeve capacity.
- Mechanical Recycling Sortation Gaps:Near-infrared detection infrastructure remains uneven across Central European material recovery facilities, creating specification uncertainty for labels with proprietary additive packages.
Strategic Opportunities
- Polish Converting Base Expansion:Mid-cap film processors in Wrocław and Łódź are adding sleeve capacity to serve Central European beverage bottlers seeking shorter supply lines than Western European sources.
- Pharmaceutical Tamper Evidence:EMA serialization requirements and brand protection mandates create premium positioning for sleeve labels with integrated tear-band and holographic security features.
- Digital Printing Convergence:Combination of UV inkjet and traditional flexographic lines enables economic short runs for craft beverage brands, opening SKU proliferation strategies previously blocked by plate costs.
Industry Challenges
- Mono-Material Certification Timelines:RecyClass and EPBP approval processes for novel sleeve constructions extend 18-24 months, delaying revenue recognition for R&D investments.
- Hot-Fill Ink Migration Compliance:EFSA food-contact layer constraints require reformulation of UV-cured inks for retort and hot-fill dairy applications, extending qualification cycles with major bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Shrink and Stretch Sleeve Label Market |
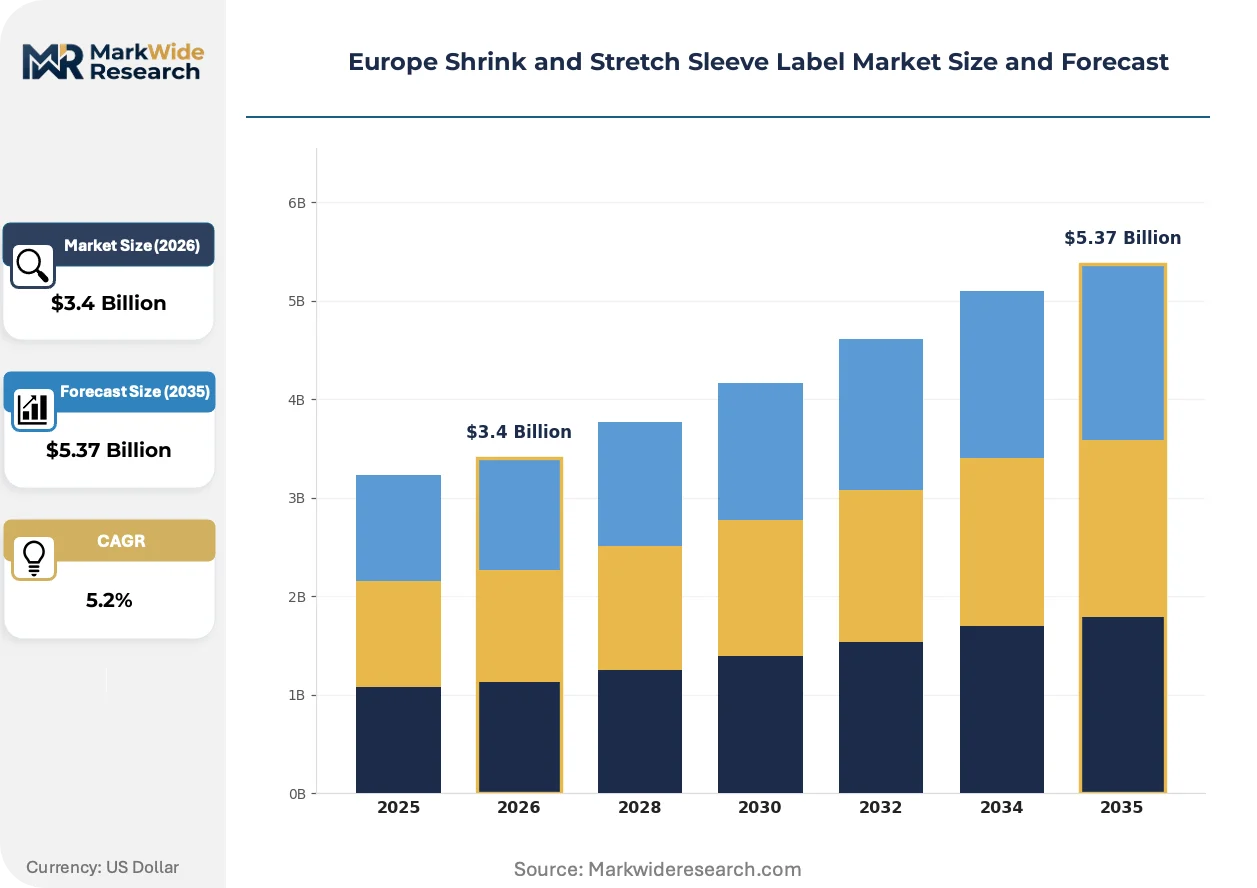
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrink Labels, Stretch Labels, Tamper Evident Labels, Custom Design Labels Material: Polyethylene, Polypropylene, PVC, PET Application: Beverages, Food Packaging, Personal Care, Household Products End User: Food Industry, Beverage Industry, Pharmaceutical, Consumer Goods |
| Companies Covered | CCL Industries Inc., Huhtamaki Oyj, Amcor Plc, Fuji Seal International Inc., Berry Global Group Inc., Klöckner Pentaplast GmbH and Co. KG, Coveris Management GmbH, Multi-Color Corporation, Avery Dennison Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Shrink and Stretch Sleeve Label Market Shifts & Advancements
Digital printing workflows and substrate innovations are compressing minimum order quantities while expanding graphic capabilities, reshaping how converters compete for fragmented beverage brand portfolios.
Laser-perforated tear-band technology is rendering obsolete mechanical punch-and-die tamper-evident features that required dedicated tooling and limited line speed flexibility. Premium spirits brands in Scotland and Cognac are adopting this at pilot scale. The technology is enabling converters to offer security-feature customization without capital equipment changeovers, compressing competitive differentiation cycles.
REACH restrictions on intentionally added microplastics are tightening compliance pathways for sleeve label adhesives and inks, particularly for wash-off labels in PET bottle recycling streams. ECHA guidance documents issued under the EU Green Deal implementation timeline are forcing reformulation of pressure-sensitive adhesive backings. German converters are responding by accelerating water-soluble adhesive qualification programs with major bottlers in the Rhine-Ruhr corridor.
Brand procurement teams are consolidating sleeve label suppliers to capture volume leverage, collapsing the fragmented vendor base that historically served regional bottling operations. Multinational beverage headquarters in Paris and Amsterdam are mandating pan-European master service agreements with technical specification harmonization. This concentration is most visible in the dairy segment, where private-label retailers are forcing standardization across their Central European co-packer networks.
Europe Shrink and Stretch Sleeve Label Market Segmentation
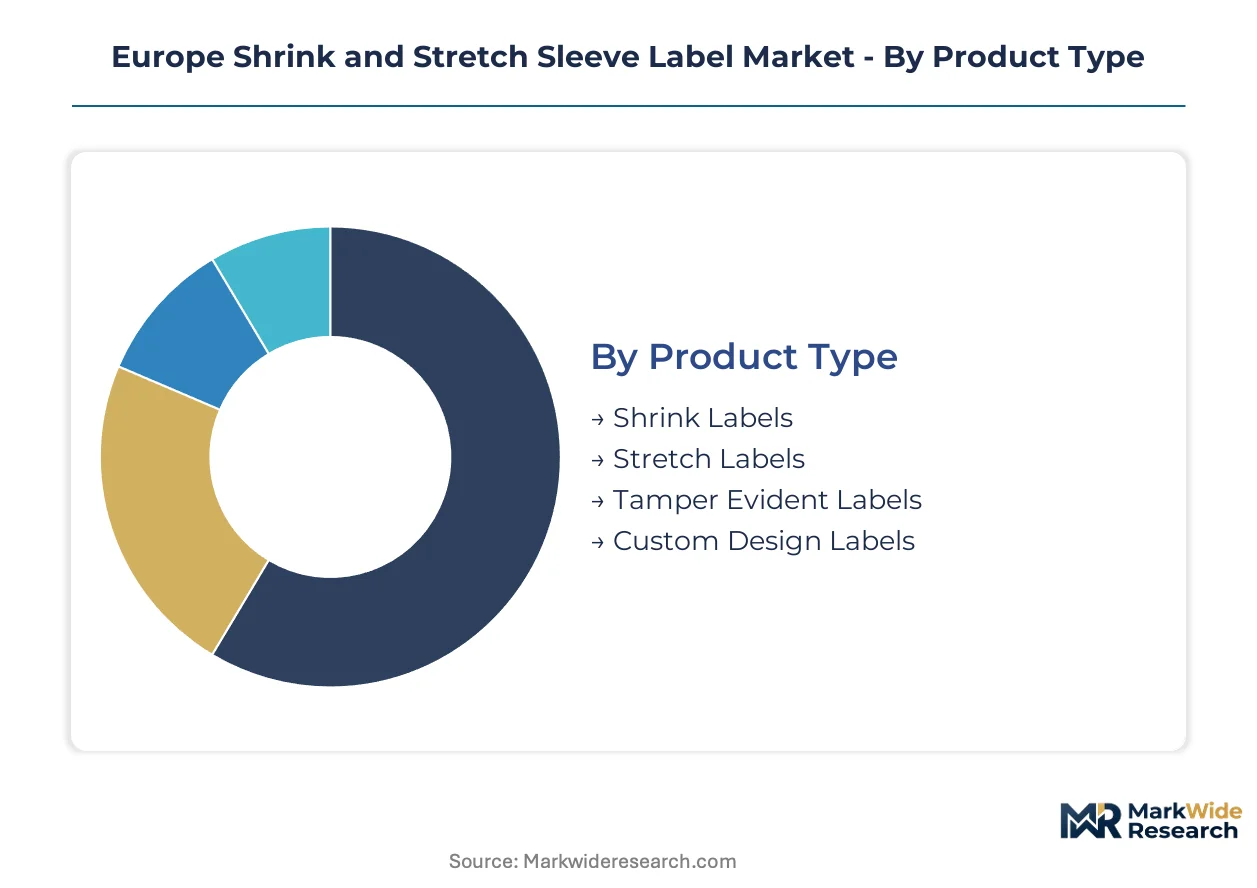
Sleeve label specification cycles vary dramatically across product types and end-use applications, with beverage SKU proliferation driving 6-12 month refresh rates while pharmaceutical formats lock in 3-5 year qualification timelines. Material selection and application requirements further stratify procurement behaviors, creating distinct competitive arenas for converters.
Product Type:
Shrink labels turn over fastest in carbonated soft drinks and premium spirits where seasonal campaigns demand rapid graphic refreshes, while tamper evident formats cycle slowest due to pharmaceutical validation requirements.
- Shrink Labels:Manufactured from oriented PETG or polyolefin films through extrusion, printing, and seaming processes, designed to conform via heat application to complex bottle contours. German and French beverage bottlers specify high-shrink-ratio constructions for 360-degree brand visibility in premium spirits and CSD segments, though ECHA restrictions on legacy additives force substrate migration toward mono-material PET.
- Stretch Labels:Elastic recovery films that apply without heat, favoring mono-polyethylene constructions compatible with mechanical recycling streams. Dairy and water segments in the Rhine-Ruhr corridor specify these for simplified container recovery under EU Packaging and Packaging Waste Regulation thresholds.
- Tamper Evident Labels:Integrated tear-band and holographic security features serving pharmaceutical serialization mandates under EMA requirements.
- Custom Design Labels:Short-run digital printing enables craft beverage brand differentiation without plate cost barriers.
Shrink labels dominate installed base across European beverage packaging. Stretch labels are where expansion concentrates as recyclability mandates harden.
Material:
Cost tiers separate commodity polyolefins from engineered substrates, with feedstock volatility compressing margins on standard grades while certified mono-material constructions capture specification premiums.
- Polyethylene:Linear low-density and high-density grades form the backbone of stretch sleeve applications, with elastic recovery properties enabling cold-application workflows. Polish converters in Wrocław and Łódź are expanding blown film capacity to serve Central European dairy bottlers seeking shorter supply lines.
- PET:Oriented polyethylene terephthalate glycol delivers high shrink ratios for contour-complex containers, though EFSA migration limits constrain ink selection for hot-fill applications. German converters anchor heat-shrink capacity investments around Munich-Hamburg bottling clusters.
- Polypropylene:Clarified grades offer stiffness and clarity for personal care applications where shelf presence drives specification.
- PVC:Legacy substrate facing phased elimination under REACH plasticizer and stabilizer restrictions, stranding converters with dedicated extrusion lines.
PET holds the largest installed base for high-performance applications. Polyethylene is climbing the fastest as mono-material certification timelines accelerate.
Application:
Volume concentration and margin structure diverge sharply across end-use verticals, with beverage scale economies contrasting pharmaceutical premium positioning.
- Beverages:Carbonated soft drinks, spirits, water, and juice segments generate the highest sleeve label volumes, with multinational brand procurement teams consolidating suppliers under pan-European master service agreements. Munich and Hamburg bottling corridors drive premium specification demand.
- Food Packaging:Retort and hot-fill dairy applications impose EFSA food-contact layer constraints, extending ink qualification cycles with major co-packer networks.
- Personal Care:Aesthetic differentiation through 360-degree graphics supports higher unit economics than commodity food applications.
- Household Products:Chemical resistance requirements favor polyolefin substrates for cleaning and laundry formulations.
Beverages command the greatest volume throughput. Food packaging is gaining share fastest as private-label retailers standardize sleeve specifications across Central European networks.
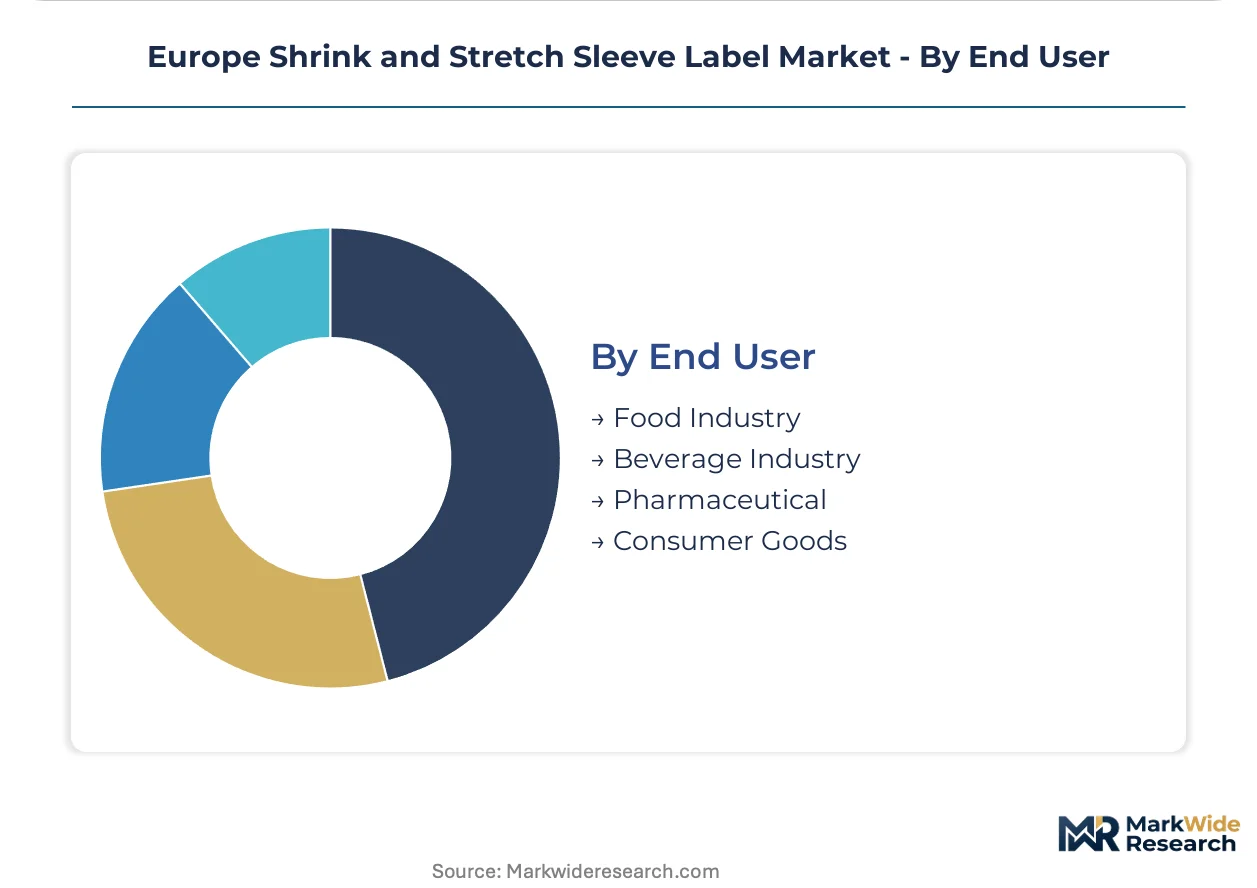
End User:
Customer type determines technical specification depth and contract duration, with pharmaceutical qualification cycles running 18-24 months against beverage annual negotiations.
- Food Industry:Private-label retailers and branded manufacturers specify sleeve labels for sauces, condiments, and prepared meals, with EFSA migration limits constraining adhesive and ink selection for fatty food contact.
- Beverage Industry:Multinational drinks brands headquartered in Paris and Amsterdam mandate technical harmonization across co-packer networks, collapsing fragmented regional vendor bases.
- Pharmaceutical:EMA serialization requirements and brand protection mandates create premium positioning for integrated security features.
- Consumer Goods:Household and personal care brands balance aesthetic differentiation with shelf-life performance requirements.
Beverage industry represents the deepest specification expertise. Pharmaceutical is where margin expansion concentrates despite extended qualification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes sleeve labels at premium specifications for spirits and carbonated beverages, while Poland and Central European markets favor cost-optimized stretch constructions for dairy and water applications. This consumption-mix differential shapes converter capacity investments and material certification priorities across the region.
Germany
Beverage bottlers around Munich and Hamburg drive demand for high-shrink-ratio PETG films in premium spirits and carbonated soft drinks. ECHA restrictions on PVC plasticizers and stabilizers under REACH accelerate substrate migration toward mono-material PET. The Rhine-Ruhr corridor anchors heat-shrink capacity investments as converters qualify water-soluble adhesives for wash-off label compatibility.
France
Multinational drinks brands headquartered in Paris mandate pan-European master service agreements with technical harmonization across co-packer networks. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility thresholds favoring sleeve designs compatible with container recycling streams. Cognac producers pilot laser-perforated tear-band technology for tamper-evident security features without dedicated tooling.
Poland
Mid-cap film processors in Wrocław and Łódź expand blown film capacity to serve Central European dairy bottlers seeking shorter supply lines than Western European sources. EFSA migration limits for food-contact layers constrain ink selection for hot-fill applications. Polish converters capture specification wins as private-label retailers standardize sleeve requirements across their Central European networks.
United Kingdom
Craft beverage brands in England and Scotland drive demand for digitally printed short-run sleeves with SKU proliferation strategies. The UK Environment Agency enforces packaging waste regulations aligned with EU PPWR recyclability mandates. Scottish whisky distillers adopt pilot-scale laser-perforated tamper-evident labels for premium export markets.
Italy
Personal care and household product manufacturers in Lombardy specify clarified polypropylene sleeves for shelf presence differentiation. ECHA guidance on intentionally added microplastics forces adhesive reformulation for wash-off label streams. Northern Italian converters develop specialized heat-shrink formulations for contoured cosmetic containers.
Europe Shrink and Stretch Sleeve Label Market Competitive Landscape
Capability concentration sits with specialized film processors commanding mono-material certification expertise; scale advantage sits with diversified packaging conglomerates integrating sleeve production into broader beverage packaging systems. The market structures around three tiers: global converters with backward integration into printed film substrates, mid-cap regional specialists with flexible digital printing workflows, and commodity film extruders competing on polyolefin substrate cost. Dominant competitive moves include capacity expansion in Central European converting clusters and portfolio diversification toward pharmaceutical tamper-evident applications.
Within the integrated converter tier, CCL Industries Inc. and Huhtamaki Oyj exemplify archetypes combining film substrate production with specialized sleeve printing capabilities. Amcor Plc occupies a position representing preform-to-label system integration for multinational beverage brands. These three companies anchor competitive positioning across the premium specification segment where EFSA compliance and mono-material certification determine procurement decisions.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| Huhtamaki Oyj |
| Amcor Plc |
| Fuji Seal International Inc. |
| Berry Global Group Inc. |
| Klöckner Pentaplast GmbH and Co. KG |
| Coveris Management GmbH |
| Multi-Color Corporation |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Ethylene feedstock volatility compresses converter margins across polyolefin substrate tiers, simultaneously widening price spreads between certified mono-material constructions and commodity grades while forcing supply chain reconfiguration toward backward-integrated film processors with captive resin access.
Pricing Analysis
German converters command 15-25% premiums over Polish competitors for comparable PETG shrink specifications, reflecting Rhine-Ruhr corridor logistics advantages and EFSA compliance certification overhead. Three-tier pricing structure across premium certified-mono-material, standard industrial-grade, and economy polyolefin tiers separates procurement behaviors. Cost compression in standard grades is intensifying because naphtha spreads track energy price spikes without contractual pass-through protection. Private-label beverage bottlers exhibit highest price sensitivity; pharmaceutical serialization mandates render tamper-evident buyers least elastic.
Supply Chain Analysis
Extended payment terms from multinational beverage headquarters strain working capital for mid-cap converters, accelerating adoption of supply-chain finance facilities. Raw material sourcing draws from German PET resin producers, Saudi ethylene feedstock, and domestic Polish blown film capacity. Single-source vulnerability concentrates in specialized heat-shrink adhesive formulations qualified with specific bottler lines. Distribution runs through co-packer networks clustered around Munich, Hamburg, and Paris headquarters with pan-European master service agreement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as PPWR implementation timelines trigger replacement demand for non-compliant legacy sleeve inventories, with beverage SKU proliferation sustaining converter throughput despite macroeconomic headwinds.
For Market Incumbents: Harden mono-material certification moats by accelerating RecyClass approval timelines for novel PET and polyethylene constructions before competitors strand capacity with unqualified substrates. Defend margin position through backward integration into printed film substrates, mirroring CCL Industries' value-chain control model. Prioritize pharmaceutical tamper-evident capacity as EMA serialization mandates create premium positioning insulation from commodity pricing cycles. For New Entrants and Emerging Players: Pursue digitally-enabled short-run craft beverage segments in England and Scotland where SKU proliferation outpaces incumbent plate-cost economics. Target Polish dairy bottlers seeking shorter supply lines than Western European sources, leveraging Wrocław and Łódź converting cluster proximity. Lead with UV inkjet-flexographic hybrid workflows enabling economic personalization without dedicated tooling investments. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation enforcement reshapes the acquisition landscape toward converters with demonstrated mono-material certification pipelines and established bottler qualification relationships. Five-to-ten-year viability favors specialists with regulatory compliance depth over commodity film extruders facing stranded PVC capacity. Monitor RecyClass and EPBP approval velocity as the decisive inflection signal for specification win rates.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | RecyClass approval unlocks PPWR-compliant specification wins with Paris and Amsterdam headquarters. |
| Digital Printing Workflow Integration | UV inkjet-flexographic hybrid lines capture craft beverage SKU proliferation without plate cost barriers. |
| Backward Integration into Film Substrates | Captive PET and polyethylene production secures margin control against ethylene feedstock volatility. |
| Pharmaceutical Tamper-Evident Capacity Expansion | EMA serialization mandates create premium positioning with 18-24 month qualification timeline protection. |
| Central European Converting Base Expansion | Wrocław and Łódź capacity serves dairy bottlers seeking shorter supply lines than Western sources. |
Research Methodology
The analysis maps shrink label, stretch label, tamper-evident, and custom design sub-sectors, each validated through converter operations directors, beverage procurement leads, pharmaceutical regulatory affairs managers, and private-label retailer category buyers. Primary interview intelligence triangulates against secondary sources including ECHA guidance documents, EFSA food-contact migration databases, EU Packaging and Packaging Waste Regulation implementation timelines, and RecyClass certification registries. Bottom-up volume builds from country-level bottling capacity and top-down demand validation from film substrate trade flows ensure cross-verified outputs.
Assumptions hold PPWR enforcement timelines, ECHA additive restrictions, and EFSA migration limits fixed across the projection horizon while varying ethylene feedstock spreads and near-infrared sortation infrastructure deployment rates. Segmentation dimensions model product type, material substrate, application vertical, and end-user procurement behavior. CAGRs derive from regression analysis against historical sleeve label adoption elasticities and beverage volume growth coefficients, with mono-material certification penetration curves and digital printing adoption rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese film exporters or accelerated PVC phase-out timelines would shift outcomes. Macroeconomic deviation, regulatory enforcement acceleration, or breakthrough sortation technology deployment would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Sleeve Label Market
Labels
United States Print Label Market
Labels
Domed Labels Market
Labels
Label Applicator Market
Labels
Global Thermal Transfer Label Market
Labels
Holographic Labels Market
Labels
GHS Labels Market
Labels
Hang Tags Market
Labels
Global Security Labels Market
Labels
Booklet Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Pre-Gummed Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Roll-fed Wraparound Label Substrates Market