
 Safety Labels Market | 2026-2036
Safety Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Labels Market Analytics
E-commerce direct-to-industrial procurement is reshaping how safety labels reach end-users. Brady Corporation leverages its digital catalog infrastructure to serve maintenance departments without distributor intermediaries. 3M Company anchors the high-performance adhesive segment with solvent-free formulations that sustain compliance in extreme environments. Avery Dennison Corporation competes through RFID-integrated smart labels that extend traceability beyond printed barcodes.
Safety labels are pressure-sensitive or adhesive-backed substrates, typically manufactured from polyester, vinyl, or PVC, that convey hazard warnings, handling instructions, or regulatory certifications to protect workers and consumers. Polyester dominates industrial applications where chemical resistance and dimensional stability under thermal stress prove critical. Hazard labels command premium positioning due to stringent color-fastness and pictogram durability requirements under OSHA and ISO standards. Pressure-sensitive adhesive formats lead volume across automotive and healthcare applications because peel-and-apply deployment reduces installation labor and error rates on fast-moving assembly lines.
OSHA hazard communication standards, FDA UDI regulations, and EU MDR labeling mandates collectively dictate substrate durability, legibility thresholds, and multilingual content requirements that manufacturers must embed at the design stage. REACH compliance in Europe and state-level California Proposition 65 enforcement in the United States further constrain adhesive chemistry and pigment selection. Stakeholders must monitor evolving chemical substance restrictions and serialization mandates to align R&D roadmaps with compliance timelines that outpace product development cycles.
Market Dynamics
Serialization mandates from FDA and EU MDR are forcing pharmaceutical and medical device manufacturers to rebuild label procurement around track-and-trace infrastructure rather than static hazard warnings alone.
Growth Catalysts
- FDA UDI Mandates:Medical device manufacturers must embed unique device identifiers on labels, expanding substrate requirements to RFID-ready synthetics across Class II and III devices.
- REACH Chemical Restrictions:European adhesive reformulation to eliminate SVHC substances is accelerating demand for solvent-free, bio-based pressure-sensitive alternatives in industrial corridors.
- Automotive EV Battery Labeling:Thermal runaway warning requirements for lithium-ion transport and installation are multiplying label density per vehicle platform.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester and vinyl substrate costs fluctuate with crude oil derivatives, compressing converter margins on fixed-price annual contracts.
- Adhesive Supply Concentration:North American acrylic emulsion production clusters in Texas and Louisiana, exposing buyers to hurricane-related supply interruptions.
- Digital Hazard Display Substitution:QR-code-linked dynamic safety data sheets threaten static GHS pictogram labels in warehousing and logistics applications.
Strategic Opportunities
- Indian Pharmaceutical Export Labeling:CDSCO alignment with EU MDR and FDA standards creates demand for serialization-capable label suppliers serving Ahmedabad and Hyderabad formulation clusters.
- Wearable Chemical Exposure Monitors:Integration of color-changing nanofibers into worker badges offers real-time hazard detection beyond printed warnings.
- EU Battery Regulation Passports:Mandatory carbon footprint and recycling content disclosure on EV battery labels opens premium substrate tiers with embedded NFC authentication.
Industry Challenges
- Multilingual Content Management:OSHA, ISO, and EU CLP diverge on pictogram sizing and supplementary hazard statements, forcing SKU proliferation or dynamic print-on-demand investments.
- Serialization Equipment Integration:Pharmaceutical lines require label applicators with vision verification and reject systems, extending deployment timelines and validation documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Labels Market |
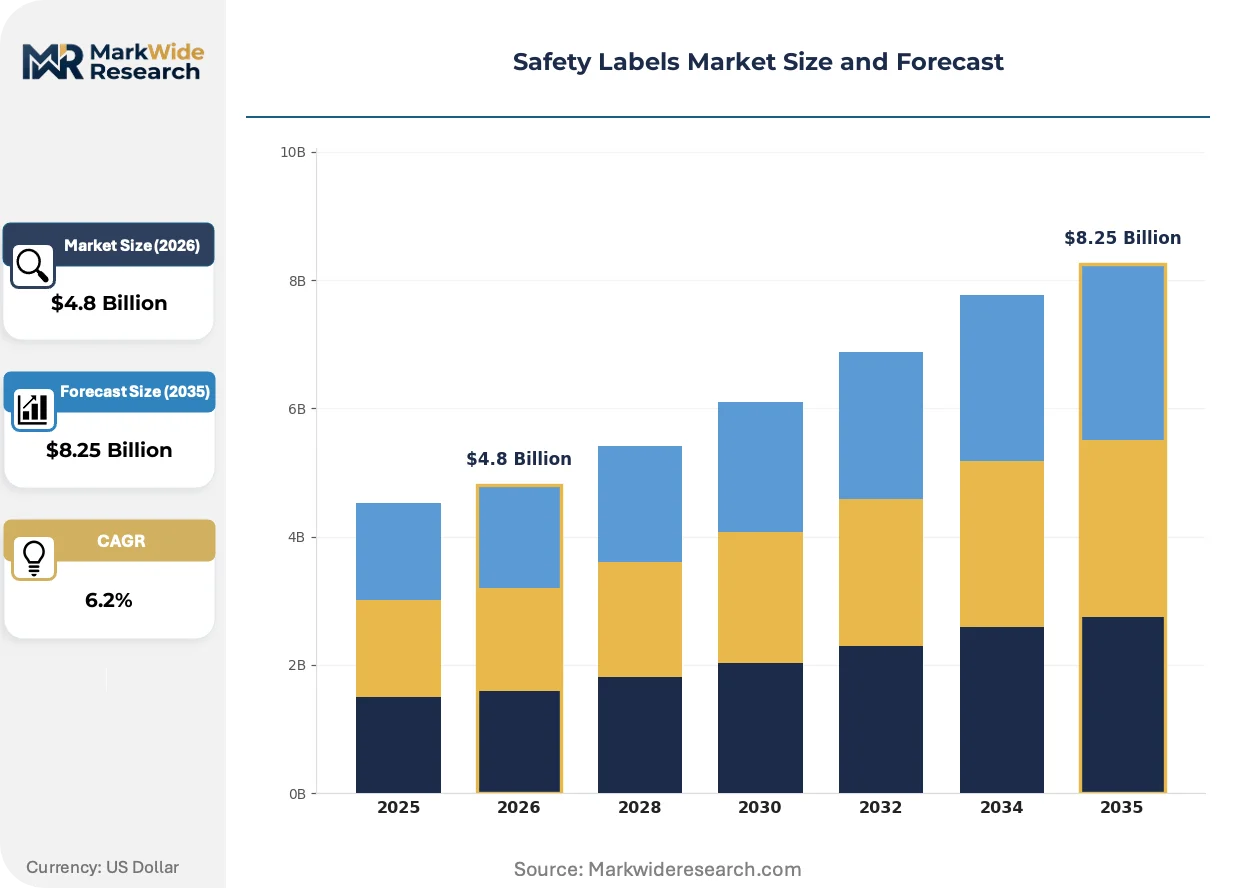
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warning Labels, Instruction Labels, Regulatory Labels, Hazard Labels Material: PVC, Vinyl, Polyester, Paper Application: Industrial, Healthcare, Automotive, Consumer Products Adhesive Type: Permanent, Removable, Repositionable, Pressure-Sensitive |
| Companies Covered | Brady Corporation, 3M Company, Avery Dennison Corporation, Seton, Labelmaster, Accuform, CILS International, Graphic Products, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Labels Market Evolving Landscape
Digital identification technologies are collapsing the distinction between printed warnings and dynamic data access, while regulatory convergence pressures substrate chemistry and content architecture simultaneously.
Laser-activated color-change pigments are collapsing the need for separate printing passes on heat-sensitive industrial labels. Automotive underhood and battery pack manufacturers in Stuttgart and Detroit are specifying these materials to embed permanent batch codes and thermal thresholds without ink degradation. The technology is collapsing equipment footprints and changeover times on high-mix assembly lines.
EU MDR Article 10 and Annex I labeling requirements are mandating symbol-based instructions for use across all member states, eliminating text-only alternatives for medical device exports. Manufacturers serving Mannheim and Munich industrial clusters must redesign legacy label formats to accommodate 23 official language combinations within fixed dimensional constraints. German notified bodies are enforcing dimensional tolerances that disqualify thermal transfer ribbons lacking ISO 2848-1 certification.
Maintenance departments in process industries are bypassing distributor networks to source safety labels through direct digital catalogs with same-day fulfillment. Brady Corporation's platform exemplifies this channel compression, offering ANSI Z535-compliant templates with locked color values that prevent procurement of non-conforming alternatives. This disintermediation concentrates volume with converters possessing digital storefront infrastructure and regional fulfillment nodes.
Safety Labels Market Segmentation
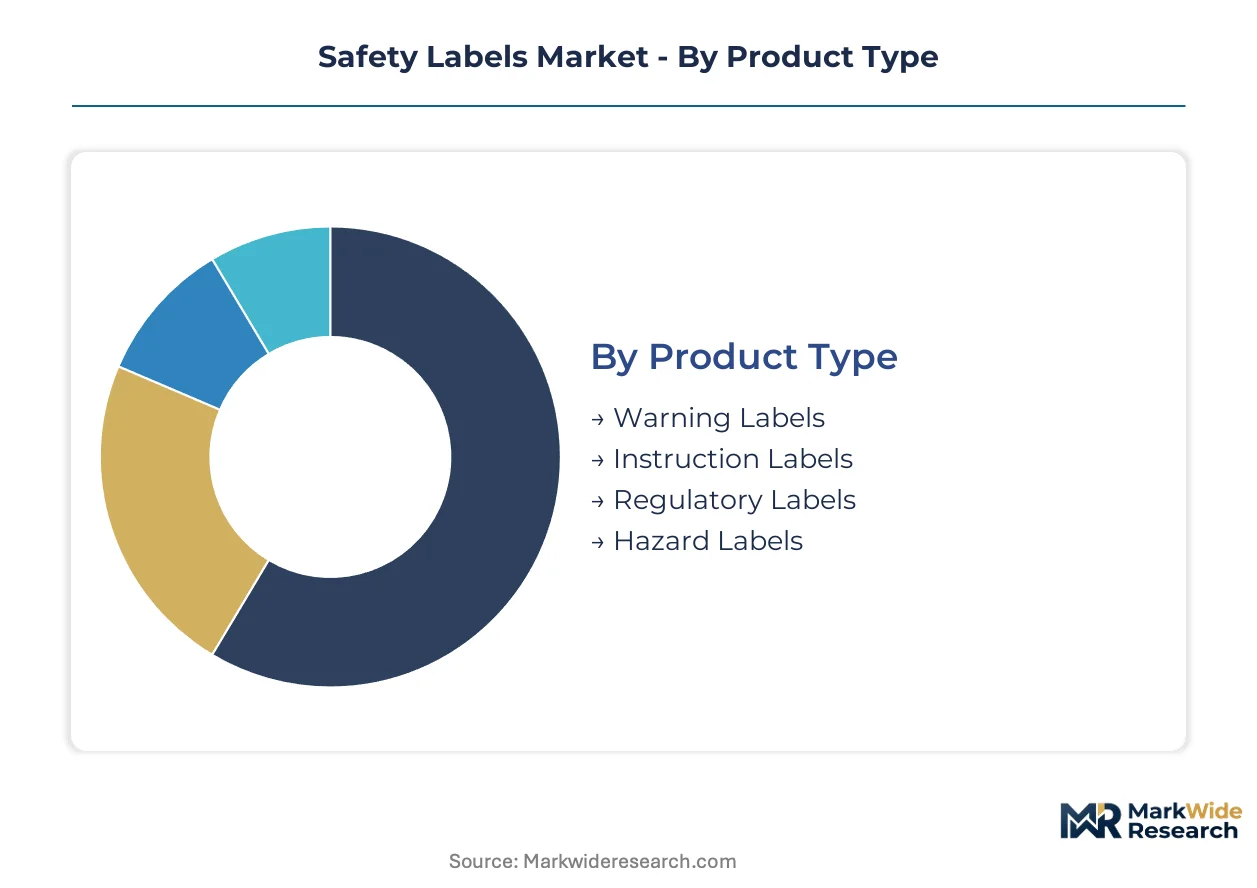
Safety labels serve distinct compliance and operational functions across end-use environments. Material selection, adhesive chemistry, and regulatory content requirements vary sharply by application, forcing converters to maintain segmented production lines and inventory positions.
Product Type:
Cost tier differentiation separates commodity warning labels from premium regulatory formats with embedded serialization capabilities.
- Hazard Labels:OSHA and ISO standards mandate specific color-fastness thresholds and pictogram durability under chemical exposure and UV degradation. Pharmaceutical serialization lines in Germany and medical device manufacturers in Massachusetts are specifying these for EU MDR and FDA UDI compliance, where non-conforming labels trigger batch rejections.
- Regulatory Labels:These carry mandatory certification marks, unique device identifiers, or country-of-origin disclosures required by customs and safety agencies. Demand concentrates in automotive export hubs around Stuttgart and medical technology corridors near Minneapolis, driven by multi-jurisdictional shipment requirements.
- Warning Labels:Standardized GHS pictogram formats for chemical containers and machinery guarding.
- Instruction Labels:Step-by-step procedural guidance for equipment operation and maintenance protocols.
Hazard labels hold installed capacity. Regulatory labels are rotating up the share rankings.
Material:
Application environment dictates substrate selection, with thermal stress and chemical exposure defining performance tiers.
- Polyester:Biaxially oriented polyethylene terephthalate delivers dimensional stability above 150°C and resistance to solvents, acids, and bases. Automotive underhood applications in Detroit and battery pack manufacturers in South Korea specify these for thermal runaway warning durability.
- Vinyl:Plasticized polyvinyl chloride offers conformability to curved surfaces and outdoor weathering resistance. Construction equipment OEMs in Texas and agricultural machinery builders in Iowa specify vinyl for exterior hazard markings subject to rain, snow, and UV cycling.
- PVC:Rigid formulations for indoor industrial signage and electrical panel labeling.
- Paper:Uncoated and coated stocks for temporary shipping labels and indoor consumer product warnings.
Polyester holds installed capacity. Vinyl is rotating up the share rankings.
Application:
End-use sector concentration shapes converter specialization and certification requirements.
- Healthcare:Sterilization-grade labels for surgical instruments, implant packaging, and medication containers must survive autoclave, gamma, and ethylene oxide cycles. Hospital networks in California and pharmaceutical manufacturers in New Jersey are driving demand for ISO 15223-1 compliant symbols and FDA UDI-embedded formats.
- Automotive:Labels for EV battery packs, high-voltage cabling, and thermal management systems carry specific hazard classifications for first responders. OEMs in Germany and South Korea are multiplying label density per platform to meet UN ECE R100 and GB/T standards for lithium-ion transport.
- Industrial:Asset tracking, lockout-tagout, and chemical drum labeling for manufacturing and process industries.
- Consumer Products:Household appliance warnings, toy safety markings, and electronics certification labels.
Healthcare holds installed capacity. Automotive is rotating up the share rankings.
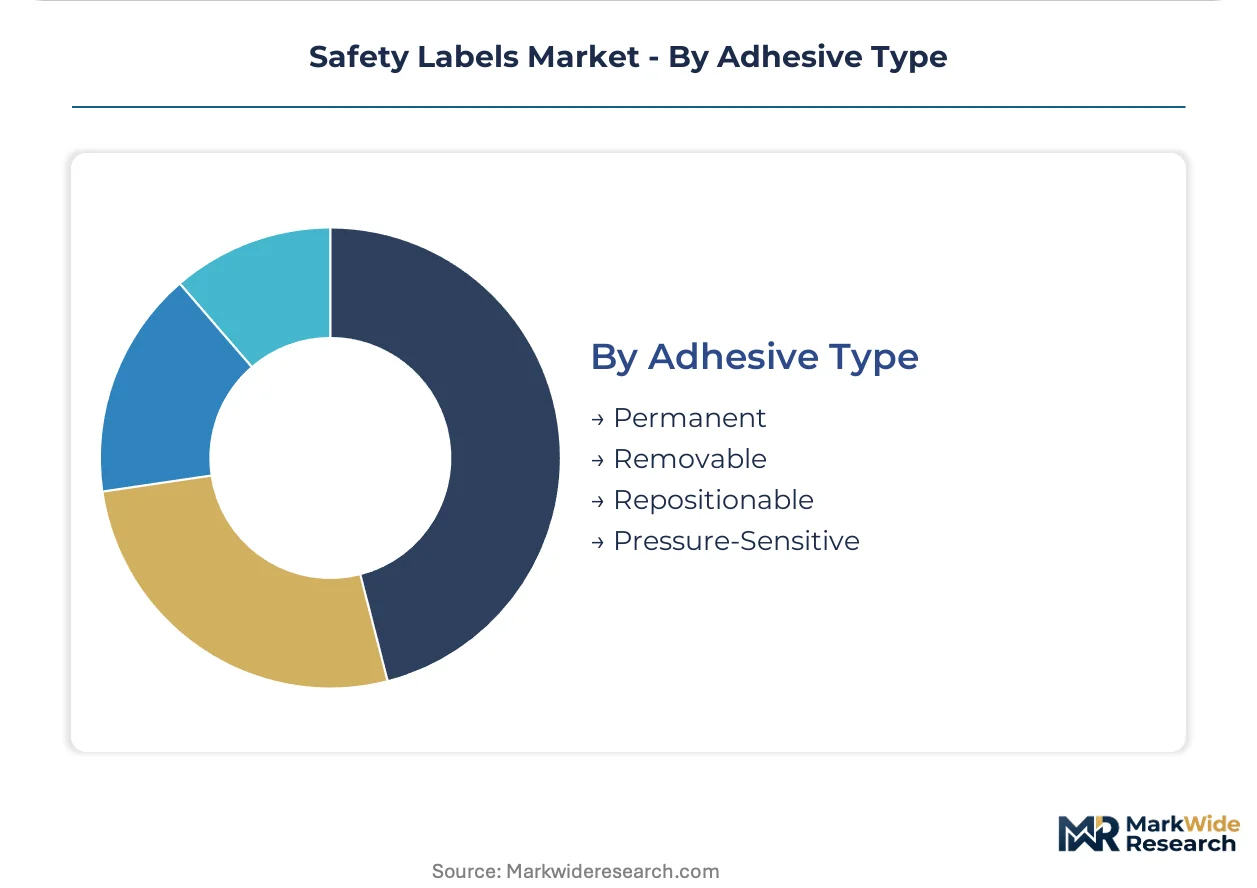
Adhesive Type:
Deployment method and surface chemistry determine adhesive selection, with repositionability commanding price premiums.
- Pressure-Sensitive:Acrylic and rubber-based formulations that bond on contact without heat, water, or solvent activation. High-speed pharmaceutical packaging lines in India and medical device assembly in Ireland specify these for automated applicator compatibility and immediate handling strength.
- Permanent:Aggressive tack and high ultimate adhesion for structural bonding to metal, glass, and engineered plastics.
- Removable:Clean-release formulations for temporary asset tracking and promotional labeling.
- Repositionable:Low initial tack allowing alignment correction before final bond formation.
Pressure-sensitive holds installed capacity. Permanent is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract 15-20% price premiums on EU MDR-compliant serialization labels versus equivalent specifications in Indian pharmaceutical export corridors. This asymmetry reflects regulatory enforcement intensity and validation documentation burdens rather than raw material differentials.
United States
FDA UDI mandates for Class II and III medical devices are expanding substrate requirements to RFID-ready synthetics. OSHA hazard communication standards enforce specific color-fastness thresholds for chemical drum labeling. Pharmaceutical packaging lines in New Jersey and medical device manufacturers in Massachusetts are driving demand for serialization-capable formats with vision verification compatibility.
Germany
EU MDR Article 10 labeling requirements are mandating symbol-based instructions for use across 23 official language combinations. REACH chemical restrictions are accelerating adhesive reformulation to eliminate SVHC substances. Industrial clusters around Stuttgart and Mannheim are specifying laser-activated color-change pigments for automotive underhood and battery pack applications.
China
GB/T standards for lithium-ion battery transport and installation are multiplying label density per EV platform. NMPA alignment with international serialization protocols is reshaping pharmaceutical export labeling requirements. Battery manufacturers in the Yangtze River Delta are procuring thermal runaway warning labels with permanent batch code durability.
India
CDSCO alignment with EU MDR and FDA standards is creating demand for serialization-capable label suppliers. Pharmaceutical formulation clusters in Ahmedabad and Hyderabad are rebuilding procurement around track-and-trace infrastructure. Domestic converters are investing in digital print-on-demand capacity to manage multilingual SKU proliferation.
South Korea
MFDS medical device registration requirements are tightening traceability specifications for export-bound manufacturers. UN ECE R100 compliance for EV battery labeling is driving specification upgrades across automotive supply chains. Battery pack producers near Seoul are specifying polyester substrates with dimensional stability above 150°C for thermal management system warnings.
Safety Labels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive chemistry. The vendor base organizes around three functional layers: full-service converters with digital catalog infrastructure, materials science specialists with solvent-free formulation capabilities, and regional fabricators serving price-sensitive industrial procurement. Consolidation pressure is concentrating volume with players possessing validation documentation capabilities and regional fulfillment nodes. Strategic moves center on backward integration into adhesive production and geographic expansion into Indian pharmaceutical export corridors.
Within the platform integrator tier, Brady Corporation exemplifies the direct-to-industrial procurement model with ANSI Z535-compliant template infrastructure. 3M Company anchors the high-performance adhesive segment with materials science capabilities extending to extreme environment compliance. Avery Dennison Corporation occupies a position in smart label integration, representing the RFID-embedded traceability archetype that extends beyond printed barcodes.
| Leading Market Players |
|---|
| Brady Corporation |
| 3M Company |
| Avery Dennison Corporation |
| Seton |
| Labelmaster |
| Accuform |
| CILS International |
| Graphic Products |
| Tesa SE |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility determines both the spread between configured-to-order and standard pricing tiers and the geographic clustering of converter capacity. Polyester and vinyl substrate costs fluctuate with crude oil derivatives, compressing margins on fixed-price annual contracts while rewarding converters with backward-integrated adhesive production or regional fulfillment nodes that can absorb cost spikes without passing through to buyers.
Pricing Analysis
The customization-premium spread separates serialization-ready hazard labels with embedded RFID and vision-verification compatibility from commodity GHS pictogram formats. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with EU MDR-compliant serialization labels commanding substantial premiums over equivalent specifications in price-sensitive Indian pharmaceutical export corridors. Cost compression in the economy tier is intensifying because domestic converters are investing in digital print-on-demand capacity to manage multilingual SKU proliferation. Pharmaceutical packaging lines demonstrate the least price sensitivity due to batch rejection risks from non-conforming labels, while industrial maintenance departments sourcing through direct digital catalogs exhibit the highest sensitivity.
Supply Chain Analysis
Upstream feedstock for polyester and vinyl substrates draws from petrochemical complexes concentrated in the United States, China, and South Korea, with biaxially oriented polyethylene terephthalate production anchored in integrated chemical corridors. Acrylic emulsion adhesive chemistry hinges on specialty monomer supply from Texas and Louisiana production clusters, creating single-source vulnerability to hurricane-related interruptions. Distribution runs through a bifurcated channel structure: full-service converters with digital catalog infrastructure serve direct-to-industrial procurement, while regional fabricators feed price-sensitive spot buyers through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across FDA UDI, EU MDR, and emerging market serialization protocols fragments demand into specialized niches that favor targeted players over generalists. This fragmentation creates entry points for converters with validation documentation capabilities and regional certification expertise.
For Market Incumbents: Pre-empt margin erosion from digital hazard display substitution by securing backward integration into solvent-free adhesive production and expanding validation documentation capabilities for pharmaceutical serialization lines. Anchor position through ANSI Z535-compliant template infrastructure that locks procurement into conforming alternatives, while building regional fulfillment nodes in Stuttgart and Mannheim industrial clusters to capture EU MDR-driven demand. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian pharmaceutical export corridors where CDSCO alignment with international standards is rebuilding procurement around track-and-trace infrastructure. Target the automotive EV battery labeling segment in South Korea and China, where UN ECE R100 and GB/T standards are multiplying label density per platform. Lead with laser-activated color-change pigment capabilities that collapse equipment footprints for high-mix assembly lines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with digital storefront infrastructure and regional fulfillment nodes over component specialists. Long-term viability rests on validation documentation capabilities and certification breadth across multiple regulatory jurisdictions. Watch for aggressive capacity additions by state-backed Chinese converters serving NMPA-aligned pharmaceutical export requirements as the inflection signal forcing Western incumbent repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Captive supply of solvent-free formulations insulates margins from petrochemical volatility and REACH compliance costs. |
| Digital Print-on-Demand Capacity Expansion | Enables converters to manage multilingual SKU proliferation without inventory risk from OSHA, ISO, and EU CLP divergence. |
| RFID-Embedded Smart Label Development | Extends traceability beyond printed barcodes for FDA UDI and EU MDR serialization mandates in pharmaceutical corridors. |
| Regional Fulfillment Node Establishment | Same-day fulfillment capabilities concentrate volume with converters serving maintenance departments through direct digital catalogs. |
| Laser-Activated Pigment Specification Partnerships | Automotive OEMs in Stuttgart and Detroit specify these materials for permanent batch codes without ink degradation risks. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and industry association technical standards preceded structured interviews with label converter operations directors, pharmaceutical packaging line engineers, automotive OEM procurement specialists, and adhesive formulation chemists. Primary fieldwork with maintenance department purchasing managers and medical device regulatory affairs leads validated secondary findings on direct-to-industrial procurement shifts and serialization equipment integration burdens. Bottom-up volume modeling across material, application, and adhesive type segments was triangulated against top-down market sizing from trade flow analysis.
The analytical framework held regulatory enforcement intensity and petrochemical feedstock cost trajectories as fixed boundary conditions across the projection horizon, while varying adoption rates for RFID-embedded formats and laser-activated pigment specifications. Segmentation dimensions modeled included product type tier, end-use sector concentration, substrate performance grade, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating pharmaceutical serialization line expansion and automotive EV platform label density multipliers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese converters or rapid QR-code substitution in warehousing applications would shift outcomes. Material shifts in REACH SVHC substance restrictions or FDA UDI mandate expansion to additional device classes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
GCC Labels and Release Liners Market
Labels
Foil Labels Market
Labels
Integrated Labeling System Market
Labels
Thermal Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Hot Melt Glue Labeler Market
Labels
Sustainable Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Primary Packaging Labels Market
Labels
Global Security Labels Market
Labels
Sheeted Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Cut and Stack Labels Market
Labels
Sleeve Label Market
Labels
Wrap Around Labels Market
Labels
Global Cryogenic Label Market