
 Global Shrink Sleeve Applicator Market | 2026-2036
Global Shrink Sleeve Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shrink Sleeve Applicator Market Outlook
Digital servo control and machine vision integration is rewriting how shrink sleeve applicators synchronize with upstream filling and downstream inspection equipment. Krones AG leverages its rotary platform architecture to dominate high-speed beverage installations across Europe. Fuji Seal International anchors Asian supply chains through captive film production and regional equipment service networks. PDC International differentiates via precision cutting systems for pharmaceutical tamper-evident applications.
A shrink sleeve applicator is an automated packaging machine that applies heat-sensitive polymer sleeves around containers using controlled thermal energy, typically operating at speeds from 100 to 800 containers per minute depending on configuration, then shrinks the material to conform to product geometry for 360-degree decoration or sealing. Its primary commercial purpose is to deliver full-body labeling, tamper evidence, and moisture protection in single-pass production lines. Automatic systems command the largest installed base due to throughput requirements in carbonated soft drink and bottled water operations, while robotic configurations represent the fastest-expanding segment as converters seek format flexibility without mechanical changeover downtime. Steam shrinking technology leads in cosmetic and pharmaceutical applications where surface temperature uniformity protects sensitive container materials, though electric shrinking gains share in food plants seeking to eliminate boiler infrastructure.
FDA food contact substance regulations and EU REACH compliance frameworks govern film chemistry and adhesive migration limits, directly shaping converter material procurement and equipment validation protocols. The EU F-Gas Regulation and OSHA thermal safety standards further constrain heat system design, pushing manufacturers toward closed-loop steam recovery and infrared element optimization. Stakeholders must monitor evolving extended producer responsibility legislation across multiple jurisdictions to anticipate retrofits and line expansion timing.
Market Dynamics
Digital servo control and machine vision integration is rewriting synchronization protocols between shrink sleeve applicators and upstream filling lines, forcing converters to retool for sub-millisecond timing precision in high-throughput beverage operations.
Growth Catalysts
- EU Green Deal packaging mandates:Retailer sustainability directives in Germany and France are compelling beverage bottlers to install sleeve-labeling capacity compatible with recyclable film substrates.
- Steam shrinking precision:Cosmetic and pharmaceutical manufacturers specify thermal uniformity systems to protect sensitive container materials during heat application.
- Robotic format flexibility:Converters deploying articulated arm configurations eliminate mechanical changeover downtime in short-run craft beverage operations.
Market Restraints
- Polymer resin volatility:PETG and PLA film substrate costs fluctuate with crude oil derivatives, compressing converter margins on fixed-price equipment contracts.
- German equipment concentration:Rotary platform supply chains cluster around Krones AG and Sidel Group installations, creating single-source vulnerability for high-speed line expansions.
- EU F-Gas Regulation compliance:Heat system redesign requirements for closed-loop steam recovery add validation cycles and capital burden to new machine deployments.
Strategic Opportunities
- India beverage packaging:Domestic bottled water and soft drink volume expansion outpaces local applicator manufacturing capacity, creating import substitution openings for European and Japanese suppliers.
- Pharmaceutical tamper-evidence:Precision cutting systems for blister packs and vial sealing represent underserved demand distinct from commodity beverage decoration.
- Infrared electric shrinking:Food plants eliminating boiler infrastructure favor electric heat systems, displacing steam infrastructure in greenfield dairy and sauce installations.
Industry Challenges
- Mechatronics technician scarcity:Servo drive programming and machine vision calibration require hybrid mechanical-electrical skills absent from conventional packaging machinery training pipelines.
- FDA validation timelines:Food contact substance documentation for new film chemistries extends equipment qualification periods, delaying line startup revenue for pharmaceutical and nutritional applicator deployments.
- Legacy Allen-Bradley integration:Brownfield beverage plants running Rockwell Automation PLAs demand custom communication gateways to synchronize new sleeve applicators with existing line control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shrink Sleeve Applicator Market |
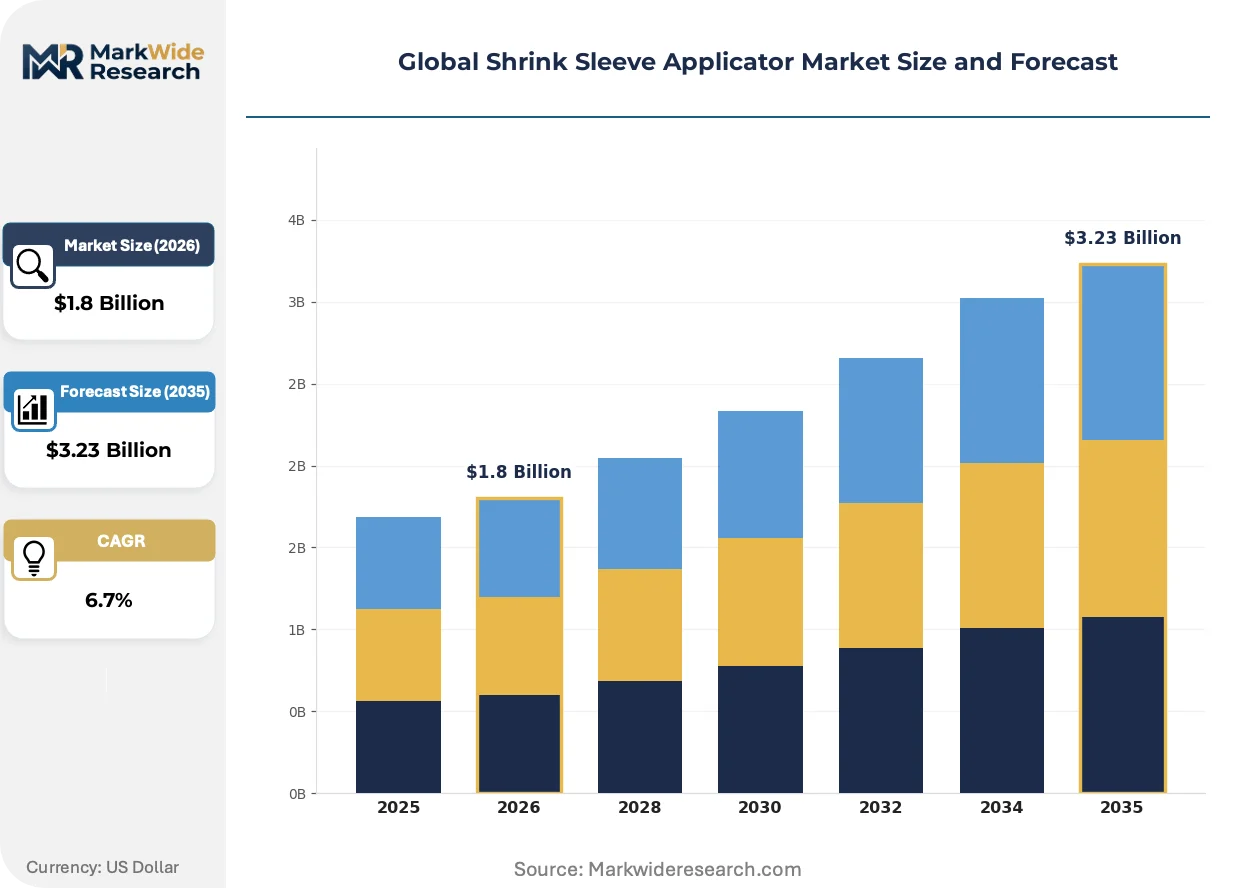
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Robotic End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Container Labeling, Product Branding, Tamper Evidence, Shrink Wrapping Technology: Heat Shrinking, Steam Shrinking, Electric Shrinking, Infrared Shrinking |
| Companies Covered | Krones AG, Fuji Seal International, Pack Leader Machinery Inc., Axon, Sleever International, Accraply, PDC International, Sidel Group, Accutek Packaging Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shrink Sleeve Applicator Market Strategic Shifts
Shrink sleeve applicator architecture is bifurcating between maximum-throughput rotary systems for carbonated beverages and adaptive robotic cells for craft and functional drink variety proliferation.
Machine vision-guided sleeve registration is migrating from mechanical edge-detection sensors to AI-powered pattern recognition. High-speed beverage bottlers in Germany and the United States are retrofitting existing lines with camera-based systems to accommodate micro-lot seasonal label changes. This migration from fixed mechanical timing to adaptive software control compresses format changeover from hours to minutes.
The EU F-Gas Regulation is restricting hydrofluorocarbon-based heat transfer fluids in industrial equipment. Applicator manufacturers serving European cosmetic and pharmaceutical markets are redesigning shrink tunnels around closed-loop steam recovery and infrared ceramic elements. German equipment suppliers face accelerated R&D cycles to maintain CE marking compliance without performance degradation.
Beverage brand owners are consolidating procurement authority from plant-level engineering to corporate sustainability offices. Sleeve applicator selection in North America and Western Europe now prioritizes total carbon footprint documentation and film substrate recyclability certifications over pure speed specifications. This shift is most visible in California and Netherlands operations where extended producer responsibility frameworks assign packaging waste liability upstream to converters.
Global Shrink Sleeve Applicator Market Segmentation
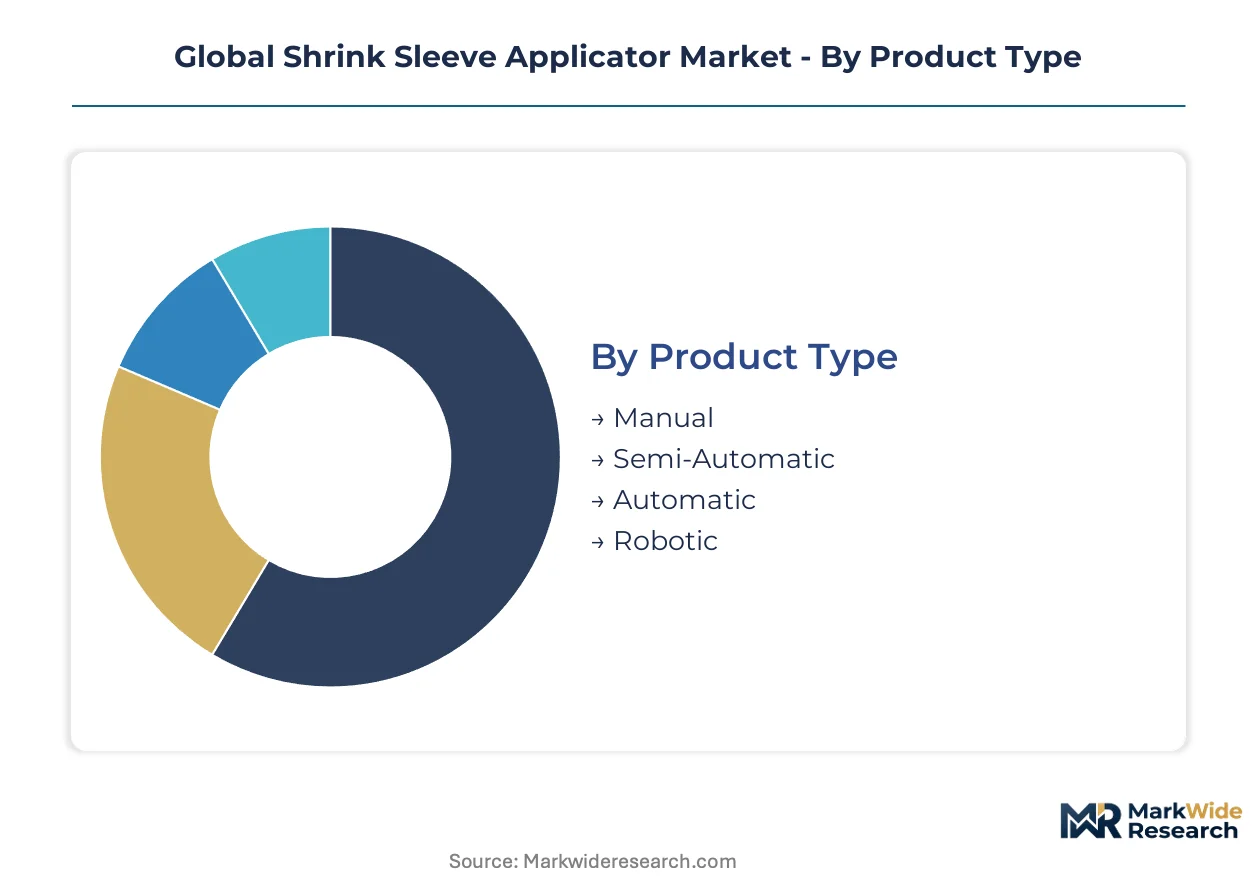
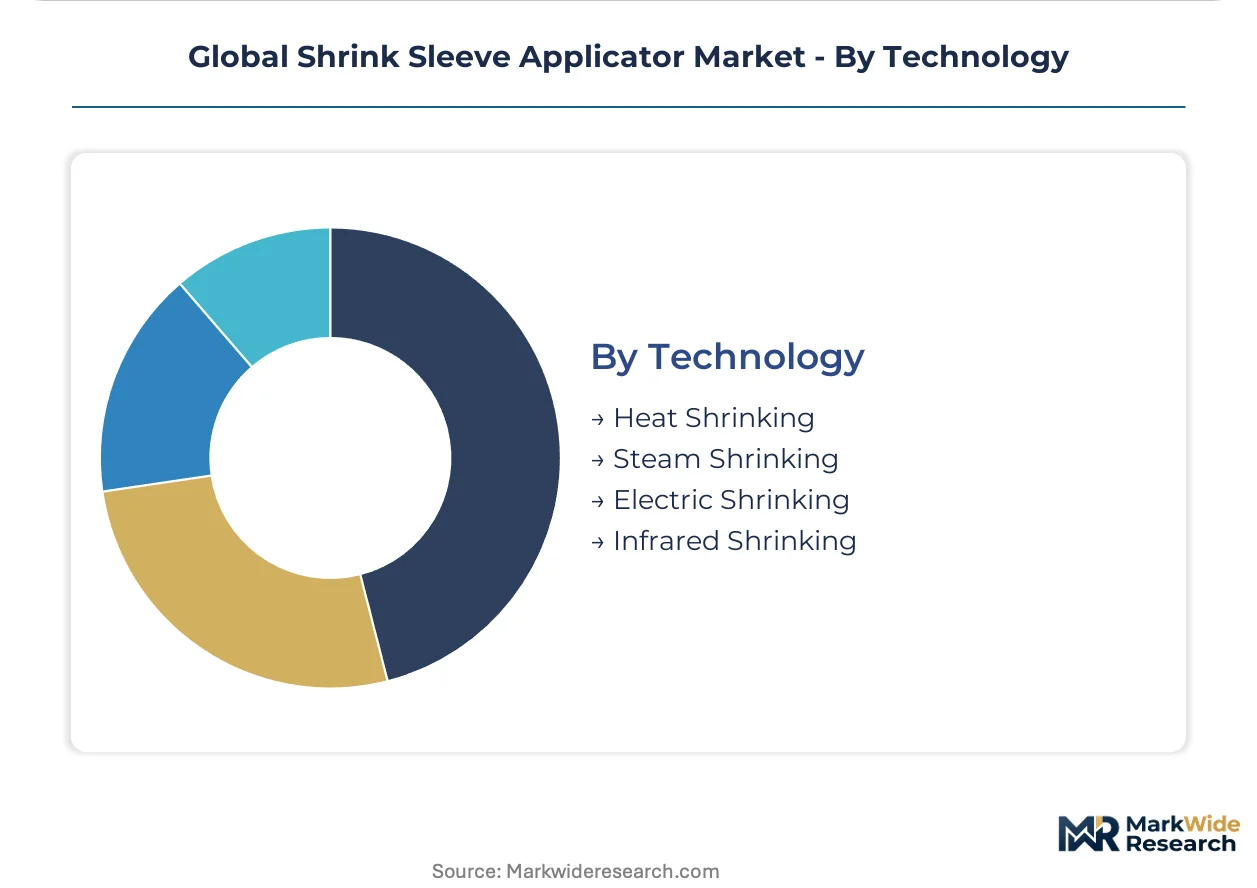
Shrink sleeve applicator segmentation reveals divergent equipment architectures optimized for throughput versus flexibility. Product type and technology choices determine capital intensity, operating cost structure, and regulatory compliance pathways across end-use verticals.
Product Type:
Mature rotary platforms anchor high-volume beverage installations while emerging robotic configurations address craft production fragmentation.
- Automatic:Rotary platform systems deliver 400-800 containers per minute through continuous motion mechanics. Carbonated soft drink bottlers in Germany and the United States specify these for 24/7 production lines where downtime costs exceed equipment depreciation.
- Robotic:Articulated arm configurations with servo-driven end-effectors eliminate mechanical changeover for format flexibility. Craft beverage producers in California and Bavaria deploy these for seasonal SKU proliferation without dedicated line assets.
- Semi-Automatic:Intermittent-motion systems suit mid-volume converters balancing throughput with capital constraints.
- Manual:Benchtop units serve pilot plants and contract packagers handling short runs.
Automatic systems handle the majority of throughput; robotic configurations are expanding most quickly on share.
End User:
Application requirements span commodity decoration to pharmaceutical validation tiers.
- Food & Beverage:Bottled water and carbonated drink producers in North America and Europe drive volume demand. FDA food contact substance regulations and EU REACH compliance govern film chemistry selection for these installations.
- Pharmaceuticals:Tamper-evident sealing for vials and blister packs demands precision cutting systems with validated thermal profiles. German and Swiss manufacturers specify steam shrinking to protect temperature-sensitive container materials.
- Cosmetics:Premium brands in France and Italy prioritize 360-degree decoration with surface uniformity for glass and polymer containers.
- Electronics:Anti-static film handling and ESD protection differentiate this niche from commodity labeling.
Food & Beverage commands installed base dominance; Pharmaceuticals climbs the fastest on compliance-driven replacement cycles.
Application:
Functional purpose determines heat system design and validation protocols.
- Container Labeling:Full-body 360-degree decoration using PETG or PLA films represents the core commercial application. Beverage brand owners in California and Netherlands now prioritize recyclability certifications alongside speed specifications.
- Tamper Evidence:Band application for bottle caps and jar lids requires precise film tension control and clean cutting. Pharmaceutical packagers in Germany and Switzerland face extended FDA validation timelines for new film chemistries.
- Product Branding:Seasonal and promotional label changes favor quick-changeover equipment configurations.
- Shrink Wrapping:Multi-pack collation for retail distribution uses thicker film gauges and higher heat loads.
Container Labeling generates the bulk of equipment shipments; Tamper Evidence shows the steepest expansion trajectory on pharmaceutical security mandates.
Technology:
Heat delivery mechanisms trade thermal uniformity against infrastructure requirements.
- Steam Shrinking:Saturated vapor systems deliver surface temperature uniformity within 2°C for sensitive container materials. Cosmetic and pharmaceutical manufacturers in Germany and France specify these to protect glass and biopolymer packaging.
- Electric Shrinking:Resistive element and ceramic infrared systems eliminate boiler infrastructure. Food plants in the United States favor these for greenfield dairy and sauce installations to reduce capital and maintenance burden.
- Heat Shrinking:Convective hot-air tunnels serve commodity applications with less demanding thermal profiles.
- Infrared Shrinking:Targeted wavelength systems enable zone-specific heat application for complex container geometries.
Steam Shrinking retains pharmaceutical and cosmetic preference; Electric Shrinking gains share fastest on food plant infrastructure simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export rotary platform systems to beverage bottlers across North America and Asia-Pacific, while Japanese and Chinese suppliers capture regional aftermarket service contracts in their home markets.
United States
California and Texas beverage plants drive demand for recyclable film-compatible applicators as brand owners consolidate procurement authority under corporate sustainability offices. FDA food contact substance regulations govern film chemistry validation for dairy and nutritional applicator deployments. The Midwest industrial corridor surrounding Chicago hosts retrofit installations integrating machine vision-guided sleeve registration into legacy Rockwell Automation line architectures.
Germany
Bavarian and North Rhine-Westphalian packaging machinery clusters anchor European supply chains for high-speed rotary platforms serving export markets. EU F-Gas Regulation compliance requirements accelerate closed-loop steam recovery system redesigns among domestic equipment suppliers. The Stuttgart industrial region concentrates precision cutting system development for pharmaceutical tamper-evident applications requiring validated thermal profiles.
China
Domestic bottled water and carbonated soft drink volume expansion outpaces local applicator manufacturing capacity in coastal provinces. NMPA pharmaceutical packaging regulations drive demand for steam shrinking precision systems in biologics manufacturing zones. The Yangtze River Delta industrial corridor around Shanghai hosts import substitution efforts by European and Japanese equipment suppliers establishing regional service networks.
India
Maharashtra and Gujarat beverage packaging growth exceeds indigenous applicator production capabilities, creating openings for imported automatic systems. FSSAI food safety standards and BIS equipment certification requirements extend validation timelines for pharmaceutical and nutritional product line deployments. The Delhi-NCR region concentrates contract packaging operations deploying semi-automatic configurations for seasonal SKU proliferation.
Japan
METI industrial efficiency guidelines promote robotic format flexibility investments among craft beverage producers in the Kansai region. PMDA pharmaceutical packaging regulations mandate precision thermal uniformity for temperature-sensitive container materials in biologics applications. The Nagoya industrial corridor anchors captive film production and integrated equipment service networks serving domestic cosmetic and pharmaceutical manufacturers.
Global Shrink Sleeve Applicator Market Competitive Environment
On the supply side, the industry is consolidating around rotary platform specialists and robotic flexibility providers, with tiered competitive positioning separating high-throughput beverage system suppliers from precision pharmaceutical equipment fabricators. Three strategic archetypes dominate: German-engineered rotary platform manufacturers, Asian integrated film-to-equipment suppliers, and North American precision cutting specialists. Capacity expansion in India and Southeast Asia represents the primary competitive move, while strategic partnerships between equipment suppliers and recyclable film substrate developers reshape procurement relationships.
Within the German-engineered tier, Krones AG and Sidel Group occupy positions as anchor suppliers to high-speed beverage installations across European and North American export markets. Fuji Seal International exemplifies the Asian integrated archetype through captive film production and regional service network density. PDC International represents the North American precision specialist segment, with its geographic positioning serving pharmaceutical and cosmetic applications demanding validated thermal profiles and cutting accuracy.
| Leading Market Players |
|---|
| Krones AG |
| Fuji Seal International |
| Pack Leader Machinery Inc. |
| Axon |
| Sleever International |
| Accraply |
| PDC International |
| Sidel Group |
| Accutek Packaging Equipment |
| Others |
Value Chain & Pricing Dynamics
Polymer resin volatility exposure compresses converter margins on fixed-price equipment contracts while simultaneously widening the spread between premium servo-controlled systems and economy-grade intermittent-motion alternatives. This cost pressure cascades through procurement decisions, pushing beverage bottlers toward long-term film supply agreements and captive substrate production to stabilize unit economics across high-volume rotary installations.
Pricing Analysis
Next-generation robotic format-flexibility systems command substantial premiums over legacy rotary platforms, while prior-generation intermittent-motion equipment faces accelerating price erosion in secondary markets. The dominant model rests on tiered equipment pricing across premium, standard, and economy levels, with differentiation driven by servo-axis count and CE/FDA validation tier. Pricing pressure stems from crude oil derivative fluctuations in PETG and PLA substrates, compressing margins on fixed-price contracts. Craft beverage producers exhibit highest price sensitivity, while pharmaceutical packagers prioritize thermal uniformity certification over capital expenditure minimization.
Supply Chain Analysis
Extended payment terms from German equipment suppliers to Asian film converters have become standard practice, with supply-chain finance facilities bridging working capital gaps for mid-tier applicator manufacturers. Component sourcing draws from Germany for precision servo drives, Japan for machine vision systems, and China for structural fabrication. Critical dependencies include rare-earth magnets for servo motors, optical sensors for registration systems, and specialized ceramic elements for infrared heat tunnels. Single-source vulnerability clusters around Krones AG and Sidel Group rotary platforms for high-speed beverage lines. Distribution runs through direct OEM sales for large bottlers and regional distributor networks for craft and pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure-sensitive adhesive labels and direct-to-container digital printing represent credible substitution threats that incumbent sleeve applicator manufacturers must neutralize through recyclability certification and total-cost-of-ownership documentation.
For Market Incumbents: Harden defensive positions by securing backward integration into recyclable film substrate production and accelerating closed-loop steam recovery system R&D to maintain CE marking compliance under EU F-Gas Regulation. Capacity additions in Maharashtra and Gujarat address import substitution demand while insulating against polymer resin volatility through geographic diversification of service networks.
For New Entrants and Emerging Players: Build out precision cutting system capabilities for pharmaceutical tamper-evident applications, where FDA validation timelines create incumbent vulnerability and pricing power remains intact. The most penetrable white space sits in Indian beverage packaging, where domestic volume expansion outpaces local manufacturing capacity. A go-to-market angle emphasizing robotic format flexibility for seasonal SKU proliferation distinguishes entrants from established rotary platform suppliers.
For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape by elevating equipment suppliers with validated recyclable film compatibility above commodity machinery fabricators. Long-term viability favors specialists with integrated film-to-equipment service networks and pharmaceutical validation expertise. The signal to watch is extended producer responsibility framework adoption across additional US states beyond California, which would accelerate replacement cycles for non-compliant installed base.
| Strategic Initiative | Industry Significance |
|---|---|
| Recyclable Film Substrate Integration | EU Green Deal compliance secures access to sustainability-mandated bottler procurement in Germany and France. |
| Robotic Format Flexibility Development | Articulated arm configurations capture craft beverage seasonal SKU proliferation without dedicated line assets. |
| Pharmaceutical Validation Investment | FDA thermal profile documentation opens tamper-evident sealing demand distinct from commodity beverage decoration. |
| Regional Service Network Expansion | Aftermarket density in India and Southeast Asia defends installed base against Japanese and Chinese competitors. |
| Closed-Loop Steam Recovery Redesign | F-Gas Regulation compliance maintains CE marking for European cosmetic and pharmaceutical equipment sales. |
Study Parameters
A spread of perspectives from packaging machinery plant managers, beverage bottler procurement leads, pharmaceutical validation specialists, and aftermarket service directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed equipment manufacturers, EU F-Gas Regulation implementation documents, and FDA food contact substance guidance. Trade data from German mechanical engineering associations and Japanese packaging machinery export statistics provided cross-border shipment verification. Bottom-up equipment shipment tallies and top-down end-use industry capacity expansion estimates were triangulated to anchor volume projections.
Demand-supply balance framing governed the analytical approach across the projection horizon, with segmentation modeling across product type, technology, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, greenfield capacity addition pipelines, and compliance-driven retrofit demand. Industry-specific forecast inputs included polymer resin price trajectory assumptions and extended producer responsibility framework adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese equipment suppliers establishing European certification capabilities or Indian domestic manufacturers scaling automatic system production would shift outcomes. Macroeconomic deviation in crude oil derivatives, accelerated EU packaging waste directive implementation, or breakthrough direct-to-container digital printing cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Diaper Packaging Machines Market