
 Integrated Labeling System Market | 2026-2036
Integrated Labeling System Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Labeling System Market Intelligence
The substitution of traditional paper substrates with synthetic polymer films like PET is restructuring the cost and performance dynamics for integrated labels. Zebra Technologies specializes in thermal transfer printing technologies essential for these synthetic materials. Avery Dennison Corporation leverages its material science expertise to develop advanced adhesive and facestock combinations for industrial use. ProMach offers a broad portfolio of labeling and coding solutions, competing across multiple end-user segments.
An integrated labeling system combines a print engine with an applicator to automatically create and affix labels onto products or packaging. Engineered for high throughput, these systems use tamp-blow or wipe-on methods and can exceed 100 labels per minute with precise placement. While barcode printing technology is foundational, RFID systems represent a high-growth area for asset tracking in logistics. The pharmaceuticals and electronics applications command the largest share, driven by serialization compliance and component traceability.
Regulatory mandates from bodies like the US FDA and Europe's EMA are primary market catalysts, enforcing unique device identification and drug serialization. Global standards from organizations like ISO for barcode quality and data structure ensure interoperability, influencing system design. The critical decision for end-users now centers on investing in systems with integrated machine vision for real-time label verification and quality control.
Market Dynamics
The market's central dynamic is the tension between the need for high-throughput production and the increasing complexity of regulatory compliance. This friction is forcing manufacturers to adopt intelligent, automated systems that integrate printing, application, and verification functions.
Growth Catalysts
- Regulatory Mandates:Serialization laws like the US DSCSA and EU FMD require unique identifiers in pharmaceuticals, necessitating automated systems for compliance.
- Technology Advancement:The adoption of RFID for high-value asset tracking in logistics creates growth beyond traditional barcode applications.
- Industrial Automation:Germany's automotive industry needs precise component traceability in automated plants, boosting demand for integrated systems.
Market Restraints
- High Capital Cost:The initial investment for high-speed systems with integrated machine vision is a significant barrier for smaller manufacturers.
- Integration Complexity:Linking new labeling systems with legacy ERP and MES software requires costly, custom development, slowing adoption.
- Component Sourcing:A concentrated base of suppliers for critical components like thermal printheads creates potential supply chain bottlenecks.
Strategic Opportunities
- Emerging Applications:Cold-chain logistics for food and pharmaceuticals requires specialized labels, creating a market for systems handling temperature-resistant materials.
- Technology Convergence:Integrating RFID with environmental sensors for temperature or shock on a single label unlocks new supply chain data services.
- Geographic Expansion:Stricter medical device regulations from Brazil's ANVISA and other bodies are opening new markets for compliant labeling systems.
Industry Challenges
- Talent Scarcity:A shortage of technicians skilled in servicing the complex mechatronics of print-and-apply systems hinders operational uptime and increases total cost of ownership.
- Integration Complexity:The absence of a universal data standard between labeling equipment and enterprise software necessitates costly, custom integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Labeling System Market |
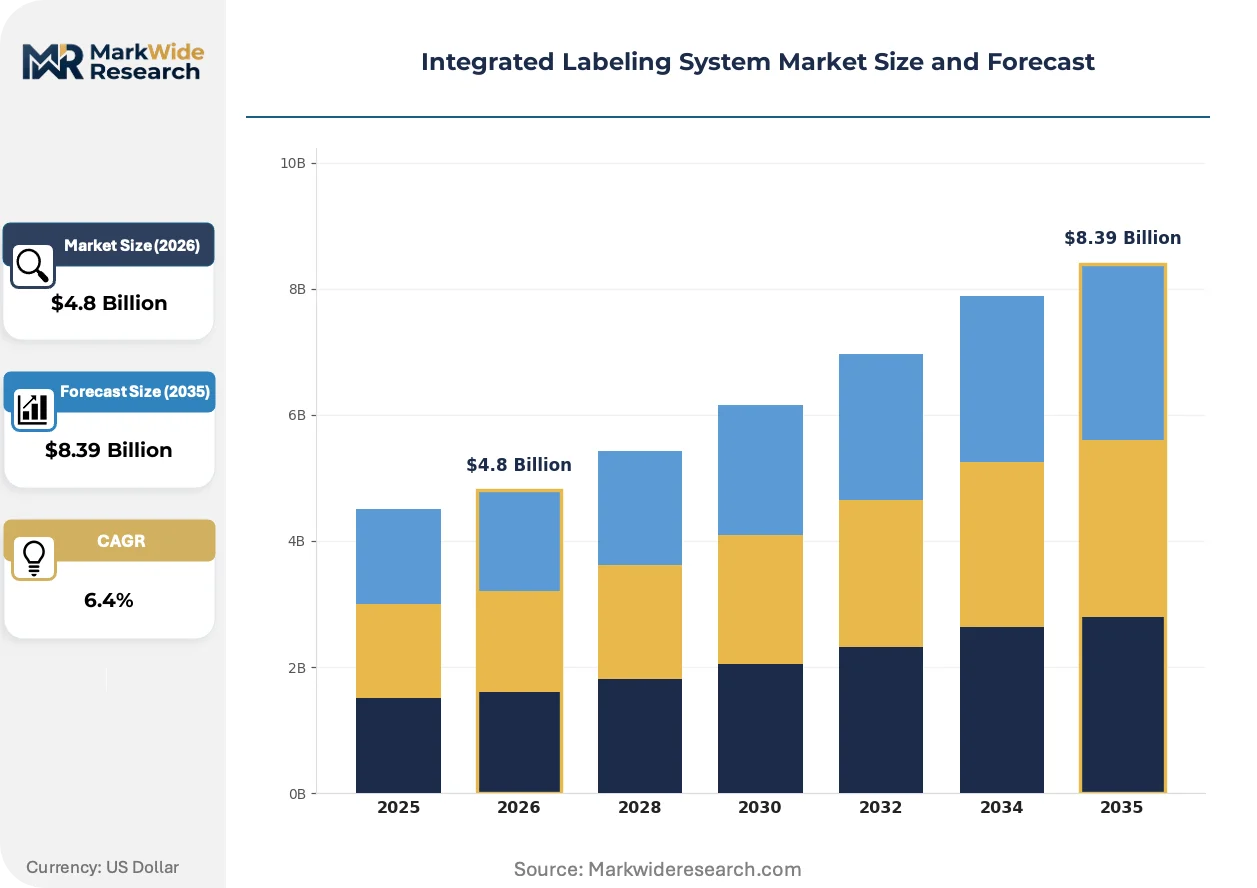
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Standalone, Modular, Automated, Semi-Automated, Networked Technology: RFID, Barcode Printing, Thermal Transfer, Inkjet, Laser Marking, Digital Printing Application: Consumer Goods, Pharmaceuticals, Electronics, Logistics, Food & Beverage, Cosmetics End User: Manufacturers, Packaging Providers, Distributors, Retail Chains, Contract Labelers |
| Companies Covered | Zebra Technologies, Avery Dennison Corporation, Honeywell International, SATO Holdings Corporation, Krones AG, Quadrel Labeling Systems, Label-Aire, ProMach, HERMA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Labeling System Market Strategic Shifts & Innovations
Automation and data integration are reshaping the functionality of labeling systems. The focus is shifting from simple label application to creating intelligent data nodes within the supply chain, providing real-time verification and traceability at the point of packaging.
Machine vision integrated directly into the applicator head performs real-time barcode and text verification. The pharmaceutical and electronics sectors are rapidly adopting these systems to ensure one hundred percent label quality and compliance. This embedded quality control is rewriting the traditional workflow of post-application inspection, significantly reducing product waste and rework.
India's Directorate General of Foreign Trade (DGFT) has established track-and-trace requirements for exported pharmaceuticals. This policy compels manufacturers to implement serialization at multiple packaging levels. The country's medical device sector is most affected, now investing in automated labeling to meet these export mandates.
A notable change in buying behavior shows a preference for modular labeling systems over monolithic machines. Contract manufacturers and 3PL providers drive this trend, needing equipment that can be quickly reconfigured for different product lines. This demand for flexibility is most visible in North America's consumer goods sector.
Integrated Labeling System Market Segmentation
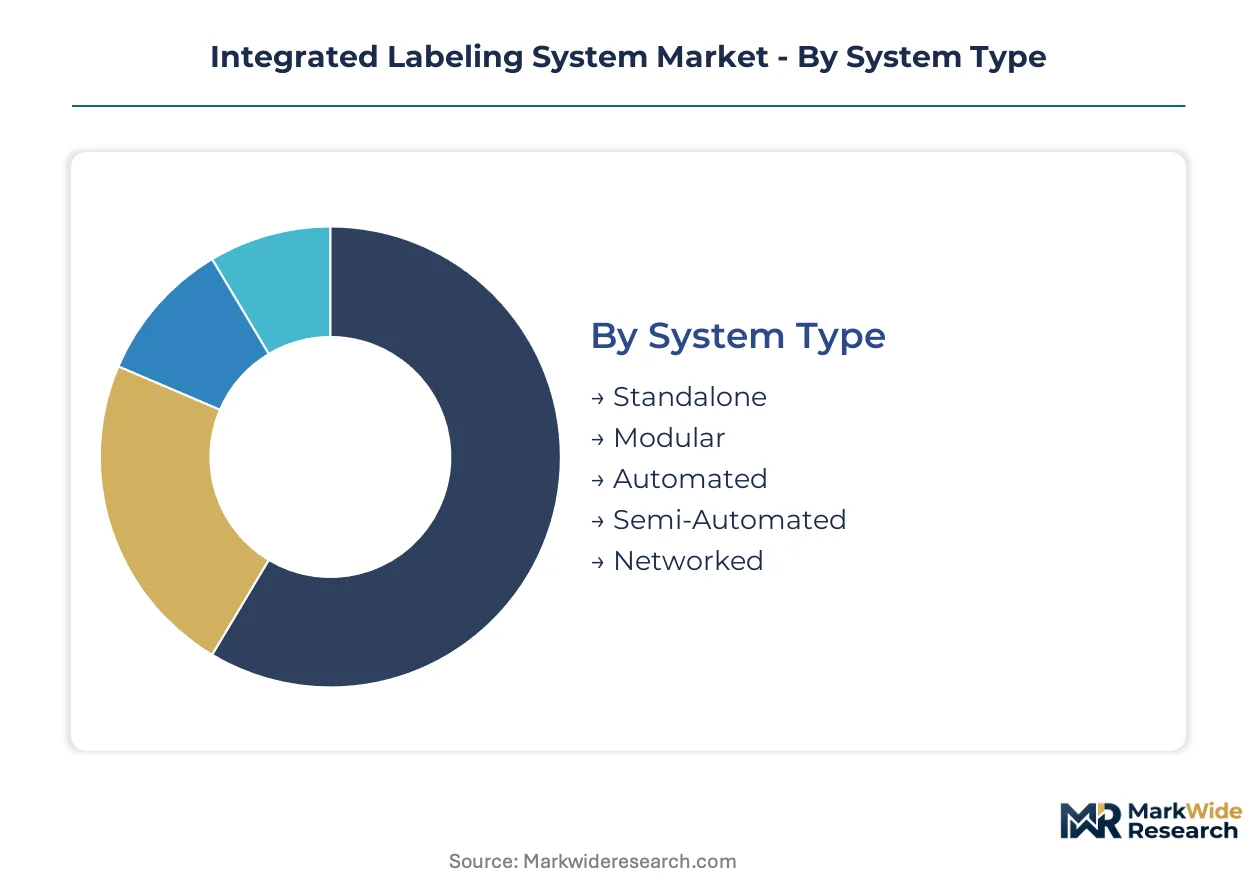
The Integrated Labeling System Market segments reveal distinct operational requirements and technological preferences across various industries. Understanding these segmentations helps manufacturers tailor solutions to specific compliance needs, throughput demands, and material handling challenges.
System Type:
Supply concentration in integrated labeling systems often centers on the complexity and automation level required by high-volume production environments.
- Automated:These systems integrate print engines with applicators, operating at high speeds to label products or packaging without manual intervention. Demand concentrates in the pharmaceuticals sector, driven by stringent serialization mandates from the US FDA and Europe's EMA.
- Modular:Designed for flexibility, modular systems allow components to be reconfigured or upgraded, adapting to diverse product lines and packaging types. Contract manufacturers and 3PL providers in North America's consumer goods sector heavily utilize these systems for rapid changeovers.
- Standalone:These individual units perform specific labeling functions, such as printing or application, independently of a fully integrated line. Smaller enterprises or specialized production runs often deploy standalone units for cost-effective labeling.
- Semi-Automated:Semi-automated systems combine automated label dispensing with manual product placement or label application. Businesses with variable production volumes or complex product geometries often leverage semi-automated solutions.
- Networked:Networked systems connect multiple labeling units to a central control system, enabling synchronized operation and data exchange across a production facility. Large-scale manufacturing operations employ networked systems for centralized data management and quality control.
Today's leader: Automated. Tomorrow's challenger: Modular.
Technology:
Application diversity dictates the selection of labeling technology, influencing data capture capabilities and material compatibility.
- Barcode Printing:This foundational technology generates scannable linear or 2D codes for product identification and tracking. Widespread adoption across all industries makes barcode printing a universal requirement for supply chain visibility.
- RFID:Radio-Frequency Identification systems use electromagnetic fields to automatically identify and track tags attached to objects. Demand for RFID is expanding most quickly in logistics and high-value asset tracking, offering enhanced data capture beyond line-of-sight.
- Thermal Transfer:Thermal transfer printers use a heated printhead to melt resin or wax from a ribbon onto various label materials, including synthetic films. Industrial applications requiring durable, long-lasting labels, like in Germany's automotive sector, frequently specify thermal transfer.
- Inkjet:Inkjet technology applies liquid ink directly onto surfaces or labels, suitable for variable data printing and direct-to-product marking. Packaging providers often use inkjet for flexible packaging and high-resolution graphics.
- Laser Marking:Laser marking systems use focused light beams to engrave or ablate surfaces, creating permanent, high-contrast marks directly on products. Electronics manufacturers employ laser marking for component traceability where durability is critical.
- Digital Printing:Digital printing offers on-demand, high-resolution color label production with variable data capabilities. Consumer goods brands use digital printing for short runs, personalized labels, and rapid design changes.
Barcode Printing holds the largest share, while RFID technology is gaining share fastest.
Application:
Volume requirements and regulatory stringency heavily influence the demand for integrated labeling systems across different applications.
- Pharmaceuticals:This sector requires precise serialization and track-and-trace capabilities to comply with regulations like the US DSCSA and EU FMD. Automated systems with machine vision for verification are critical for drug safety and anti-counterfeiting measures.
- Electronics:Component traceability and inventory management are paramount in electronics manufacturing, necessitating high-precision labeling systems. Germany's highly automated electronics plants use integrated systems for precise placement and data capture.
- Consumer Goods:Labeling in consumer goods focuses on branding, product information, and promotional content, often requiring high-speed application on diverse packaging. North American consumer brands demand flexible, modular systems for rapid product changeovers.
- Logistics:Integrated labeling systems in logistics support efficient parcel sorting, inventory management, and asset tracking across complex supply chains. RFID adoption is growing in logistics for enhanced visibility and reduced manual scanning.
- Food & Beverage:This sector requires systems capable of handling varying environmental conditions, including cold chain, and printing accurate nutritional and expiry data. Specialized labels for temperature-sensitive products are a growing niche.
- Cosmetics:Aesthetic appeal and regulatory ingredient disclosure drive labeling needs in cosmetics, often requiring high-quality graphics and precise application on unique packaging. Digital printing technologies support diverse product lines and seasonal promotions.
Pharmaceuticals and Electronics applications command the largest share, while Logistics shows the steepest expansion trajectory.
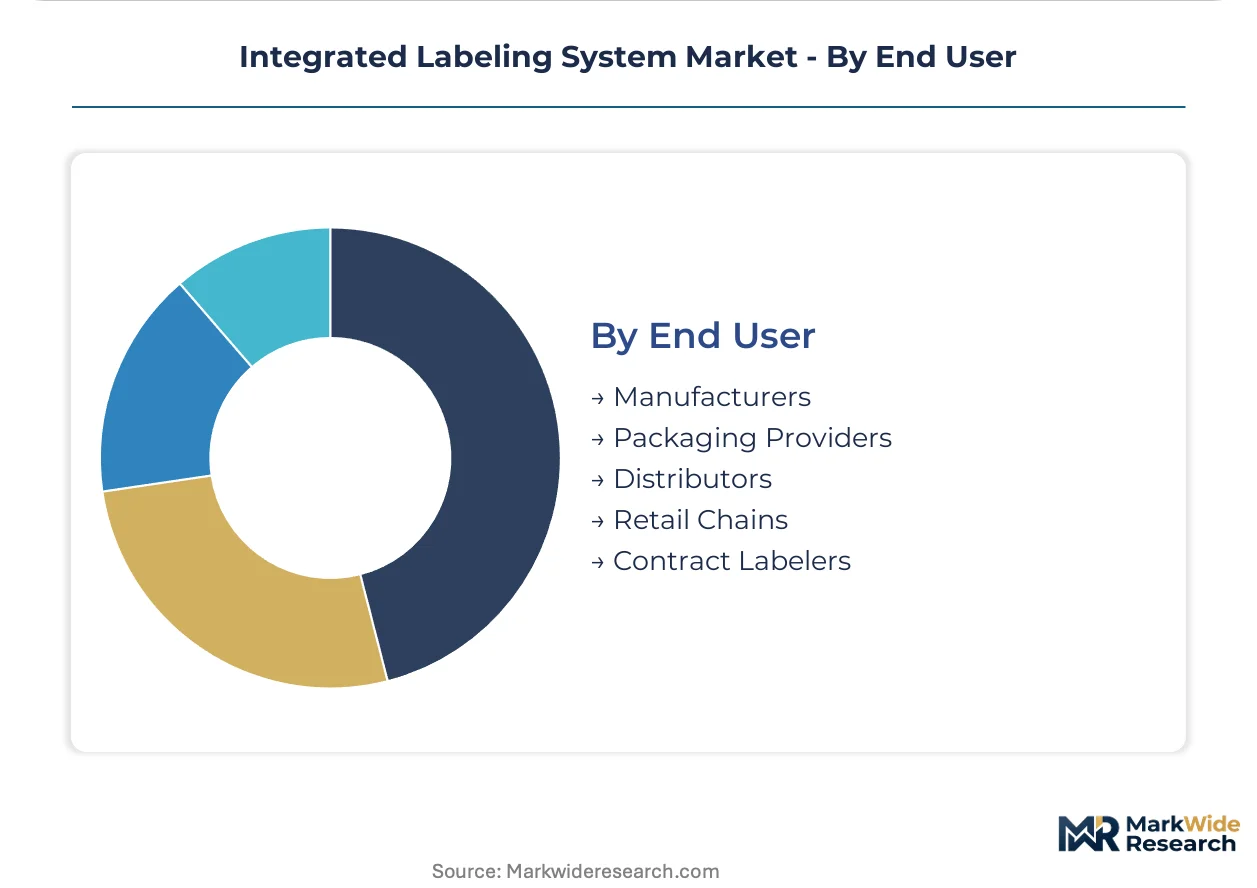
End User:
The maturity of an organization's production processes and its role in the supply chain shape its specific integrated labeling system requirements.
- Manufacturers:Manufacturing companies directly integrate labeling systems into their production lines for in-house printing and application. These users prioritize high throughput, reliability, and seamless integration with existing ERP and MES software.
- Contract Labelers:These specialized service providers offer labeling solutions for multiple clients, requiring highly flexible and reconfigurable systems. Contract labelers in North America drive demand for modular equipment to handle diverse product specifications.
- Packaging Providers:Businesses specializing in packaging solutions often incorporate integrated labeling capabilities to offer a comprehensive service to their clients. They need versatile systems capable of handling various packaging materials and formats.
- Distributors:Distributors utilize labeling systems for inventory management, shipping, and compliance labeling within their warehouses and distribution centers. Efficiency and accurate data capture are essential for streamlining logistics operations.
- Retail Chains:Retailers use labeling systems for in-store pricing, promotional labels, and inventory management, often needing user-friendly systems for variable data printing. Shelf-edge labeling and return logistics benefit from efficient, integrated solutions.
Manufacturers represent the largest segment, while Contract Labelers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's highly automated automotive and electronics manufacturing sectors drive significant demand for integrated labeling systems. Regulatory mandates from bodies like the US FDA and Brazil's ANVISA compel manufacturers to invest in advanced serialization and track-and-trace capabilities. This global regulatory environment shapes regional market development.
Germany
Precision labeling for component traceability in automated plants fuels demand for integrated systems in Germany. The country's automotive and electronics industries require highly accurate print-and-apply solutions. European regulations like the Falsified Medicines Directive (FMD) also mandate serialization for pharmaceuticals. Manufacturers in Bavaria and North Rhine-Westphalia actively adopt thermal transfer technologies for durable labels.
United States
The US market prioritizes compliance with stringent regulations, particularly the FDA's Drug Supply Chain Security Act (DSCSA). This legislation necessitates robust serialization and verification capabilities within the pharmaceutical sector. Logistics and e-commerce expansion also contribute to demand for high-speed labeling systems. Major distribution hubs in states like Texas and California are upgrading infrastructure to handle increased parcel volumes efficiently.
India
India's Directorate General of Foreign Trade (DGFT) mandates track-and-trace requirements for exported pharmaceuticals, driving investment in automated labeling. The medical device sector is particularly affected, requiring new serialization capabilities. Government initiatives supporting domestic manufacturing also encourage the adoption of advanced packaging technologies. Production facilities in Maharashtra and Gujarat are implementing integrated systems to meet global export standards.
Brazil
Stricter medical device regulations from Brazil's ANVISA are opening new markets for compliant labeling systems. The country's growing pharmaceutical and food & beverage industries demand efficient and accurate labeling solutions. Manufacturers seek systems capable of handling variable data printing and high-throughput application. Industrial zones in São Paulo and Minas Gerais are key areas for integrated labeling system adoption.
Integrated Labeling System Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies expand offerings to address varied end-user needs. The market exhibits a tiered structure with established global players alongside specialized regional providers. Strategic partnerships and technology licensing are common competitive moves, enabling broader market reach and enhanced solution capabilities.
Specialists in thermal transfer printing technologies like Zebra Technologies exemplify the importance of material compatibility and print durability. Avery Dennison Corporation, leveraging its material science expertise, anchors the market for advanced adhesive and facestock combinations. ProMach occupies a position as a broad portfolio provider, offering diverse labeling and coding solutions across multiple end-user segments.
| Leading Market Players |
|---|
| Zebra Technologies |
| Avery Dennison Corporation |
| Honeywell International |
| SATO Holdings Corporation |
| Krones AG |
| Quadrel Labeling Systems |
| Label-Aire |
| ProMach |
| HERMA GmbH |
| Others |
Cost & Logistics Intelligence
Vertical integration into material science and print engine manufacturing anchors market supply. This integration allows companies to control component costs and influence pricing power for sophisticated integrated labeling systems.
Pricing Analysis
Input cost pass-through from specialized components like thermal printheads directly influences integrated labeling system prices. Project-based pricing dominates for complex automated systems, reflecting customization and integration services. Price differentiation stems from machine vision capabilities and after-sales support. Pricing pressure stems from rising R&D investments in RFID and advanced automation. Smaller manufacturers exhibit high price sensitivity, unlike pharmaceutical companies driven by compliance.
Supply Chain Analysis
Reverse logistics for integrated labeling systems primarily involves refurbishment and component recycling for high-value print engines. Supply concentration for critical thermal printheads centers on a few specialized manufacturers, often in Asia and Europe. The systems draw from global suppliers for synthetic films and RFID components. Single-source vulnerability for key components presents a structural risk. Distribution runs through direct sales channels and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrated labeling system market presents a geographic-arbitrage play, leveraging differing labor costs and regulatory enforcement levels between regions like India and the US. This allows for cost-effective manufacturing or specialized compliance solutions.
For Market Incumbents: Hedge against integration complexity by acquiring software integration specialists. Incumbents must also invest heavily in AI-powered machine vision for real-time verification to counter emerging niche players. Deepening channel control through partnerships with contract manufacturers and 3PL providers secures market access. This strategy addresses the challenge of linking new systems with diverse legacy ERP and MES software.
For New Entrants and Emerging Players: Online marketplaces for industrial equipment offer a digital channel route for new entrants. Target the underpenetrated cold-chain logistics segment by integrating RFID with environmental sensors. Focus on North America's consumer goods sector with modular systems for rapid changeovers. A subscription-based service model for these flexible solutions provides a compelling go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for industrial technology funds because structural fragmentation exists among specialized component and software providers. The market demonstrates long-term viability, driven by continuous regulatory mandates for serialization and traceability. Target niche specialists in RFID tag manufacturing or advanced machine vision algorithms. Monitor increased M&A activity in software integration firms as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-driven machine vision | Enhances label quality assurance and reduces rework for pharmaceutical manufacturers. |
| Develop modular RFID-sensor labels | Addresses demand for enhanced traceability in cold-chain logistics applications. |
| Form strategic alliances with ERP/MES vendors | Simplifies system integration and lowers adoption barriers for manufacturers. |
| Acquire thermal printhead manufacturers | Mitigates supply chain bottleneck risks for critical components. |
| Expand into Latin American medical device markets | Capitalizes on new regulatory mandates from bodies like Brazil's ANVISA. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The analysis combines in-depth primary interviews with production managers, supply chain directors, and regulatory compliance officers. Secondary validation draws from US FDA filings, EU Falsified Medicines Directive reports, and industry association publications. This approach ensures robust bottom-up and top-down triangulation of market data.
Rate-of-change decomposition analyzes market dynamics by system type, technology, application, end user, and regional regulatory compliance. The analytical framework projects market evolution across the analysis window. Compound annual growth rates are derived from historical trends and projected future demand. Regulatory mandate enforcement timelines and industrial automation investment rates serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for RFID integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and economic growth. Geopolitical trade tensions and rapid shifts in component sourcing represent key risk factors. Practitioners should monitor new legislative proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Industrial Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Braille Labels Market
Labels
Self-Laminating Tags Market
Labels
APAC on-Demand Color Labels Market
Labels
Linerless Labels Market
Labels
High Gloss Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Ethical Label Market
Labels
Coated Wet Glue Label Market
Labels
Ripeness Indicator Labels Market
Labels
Foil Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Print Label Market
Labels
Self-Adhesive Labels Market
Labels
Hot Melt Glue Labeler Market