
 Print Label Market | 2026-2036
Print Label Market Size, Share, and Industry Trends Forecast 2026-2036
Print Label Market Intelligence
Asset-light leasing models for digital press fleets are reconfiguring competitive entry barriers, allowing mid-tier converters to serve brand owners without capital-heavy equipment ownership. Avery Dennison Corporation leverages its materials science portfolio to sustain premium pricing in pressure-sensitive substrates. CCL Industries Inc. anchors its position through backward integration into specialty coatings and film extrusion. Mondi plc competes via fiber-based solutions that align with retailer sustainability mandates.
A print label is a substrate-backed informational or decorative medium, typically 25 to 100 microns in thickness, engineered with adhesives, release liners, and surface coatings for automated or manual application onto products, packaging, or shipping containers. Its primary commercial purpose is to convey traceability data, brand identity, and regulatory compliance information across supply chains. Pressure-sensitive labels dominate volume due to their compatibility with high-speed applicators in food packaging lines, while digital printing represents the fastest-growing technology segment as brand owners reduce minimum order quantities and accelerate SKU proliferation. Shrink sleeve applications command premium margins in beverage and personal care sectors where 360-degree graphics differentiation drives shelf impact.
The US FDA enforces label content accuracy for medical devices and nutritional facts, directly shaping substrate selection and ink migration testing protocols. REACH and the EU F-Gas Regulation govern chemical composition and solvent emissions across European converting operations, raising compliance costs for non-compliant imports. China's SAMR enforces GB standards for food contact materials, affecting export-oriented label specifications. Stakeholders must monitor how fragmented regulatory timelines for extended producer responsibility will reshape substrate economics and regional sourcing strategies.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing label procurement cycles from weeks to days, forcing converters to reconfigure production workflows around digital-first, short-run capabilities.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability requirements for single-use packaging are accelerating demand for wash-off adhesives and fiber-based substrates across European food and beverage exports.
- Pharmaceutical serialization:Track-and-trace regulations in Germany and serialization mandates for medical devices are expanding premium substrate volumes for tamper-evident and temperature-indicating labels.
- Digital inkjet adoption:High-speed single-pass inkjet systems are enabling converters to profitably serve brand owners with sub-5,000 unit runs that flexographic equipment cannot accommodate.
Market Restraints
- Petrochemical input volatility:Pressure-sensitive adhesive formulations depend on acrylic and rubber-based polymers subject to crude oil price swings, compressing margin predictability for mid-tier converters.
- Release liner supply concentration:Silicone-coated glassine and PET liner production clusters in Germany and China, creating geographic single-source risk for converters outside these hubs.
- Migration testing burden:EU F-Gas Regulation and REACH compliance require extensive ink migration testing for food contact applications, extending new product qualification timelines.
Strategic Opportunities
- Indian pharmaceutical export labeling:CDSCO serialization requirements and expanding generic drug manufacturing in Hyderabad and Ahmedabad are creating demand for multi-language, anti-counterfeit label solutions.
- RFID-inlay convergence:Integration of UHF RFID chips with pressure-sensitive labels is opening inventory-automation contracts with third-party logistics providers serving apparel and electronics verticals.
- Extended Producer Responsibility tailwinds:France's AGEC law and similar frameworks are incentivizing brand owners to specify recyclable or recycled-content substrates, rewarding early-mover converters with preferred-supplier status.
Industry Challenges
- Color management expertise scarcity:Digital press operation requires spectrophotometry and ICC profiling skills that traditional flexographic technicians rarely possess, constraining workforce scalability.
- Legacy ERP integration friction:Web-to-print portals and automated prepress workflows must interface with decades-old manufacturing execution systems, delaying digital transformation ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Print Label Market |
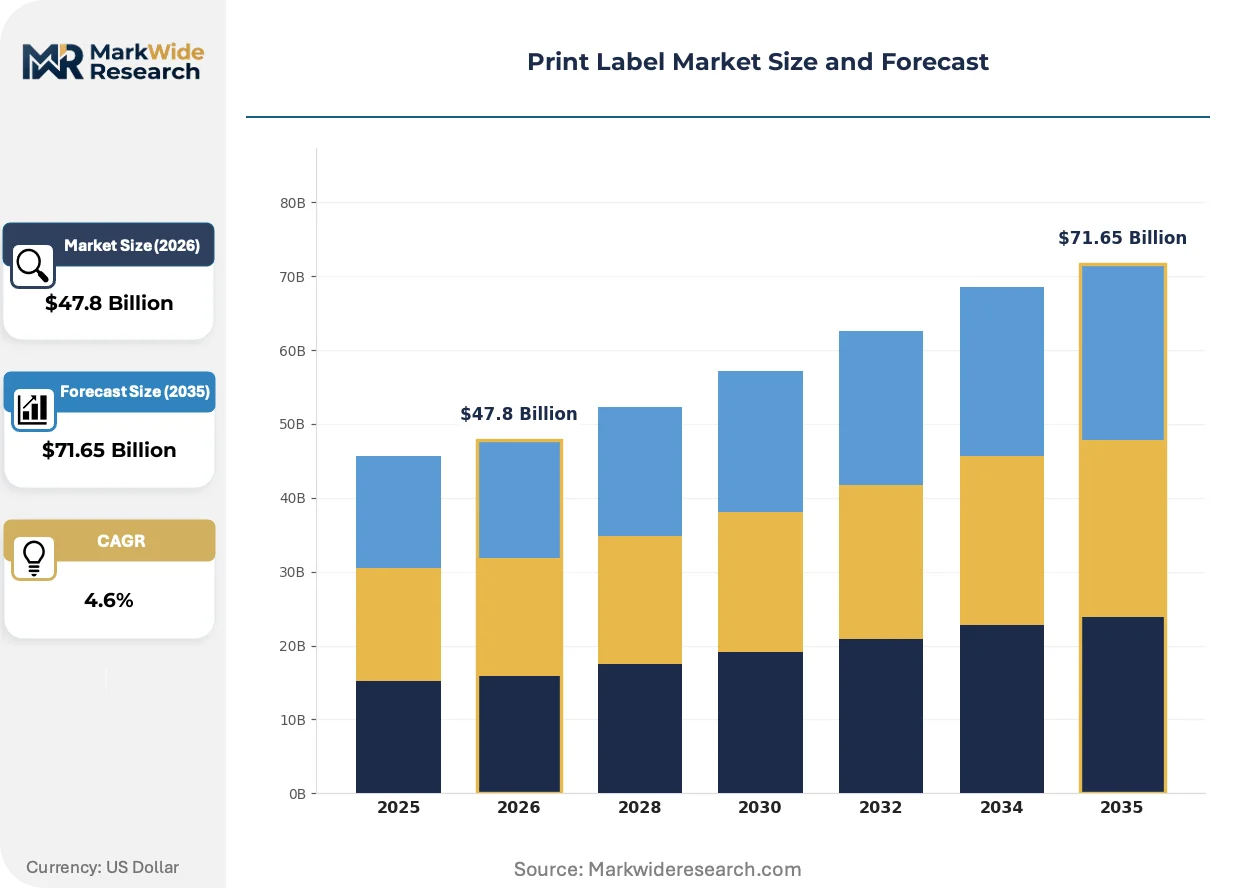
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, In-Mold, Shrink Sleeve, Laser Printable Material: PET, Paper, Vinyl, Polypropylene Application: Food Packaging, Industrial Labeling, Medical Devices, Retail Branding Technology: Digital Printing, Flexography, Lithography, Screen Printing |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Multi-Color Corporation, Mondi plc, Brady Corporation, Fuji Seal International, Inc., 3M Company, Huhtamaki Oyj, Ahlstrom-Munksjö Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Print Label Market Strategic Shifts & Innovations
Water-based ink formulations and linerless label architectures are displacing conventional solvent-based systems, driven by emissions compliance and waste-reduction imperatives across European and North American converting operations.
Single-pass inkjet printing with UV-curable or water-based inks is rendering obsolete traditional thermal transfer and laser marking systems in variable-data applications. Pharmaceutical contract packagers in Germany and medical device manufacturers in the US are adopting these systems to eliminate pre-printed inventory obsolescence. The technology is compressing minimum order quantities from tens of thousands to hundreds while enabling real-time lot-code and expiration-date personalization.
REACH substance restrictions and the EU F-Gas Regulation are eliminating per- and polyfluoroalkyl substances from label coatings and solvent-based adhesives. Converters serving food contact and personal care markets are reformulating surface treatments to maintain grease resistance and printability without fluorinated chemistry. German automotive suppliers and French cosmetics exporters are most affected, accelerating qualification of bio-based barrier coatings.
Brand owners are consolidating label procurement through centralized packaging category managers rather than decentralized plant-level purchasing. This concentration is displacing fragmented, relationship-based supplier networks with formal RFP processes and sustainability scorecards. The shift is most visible among multinational consumer packaged goods companies operating across Benelux and Nordics, where procurement teams now mandate recycled-content minimums and carbon footprint disclosures.
Print Label Market Segmentation
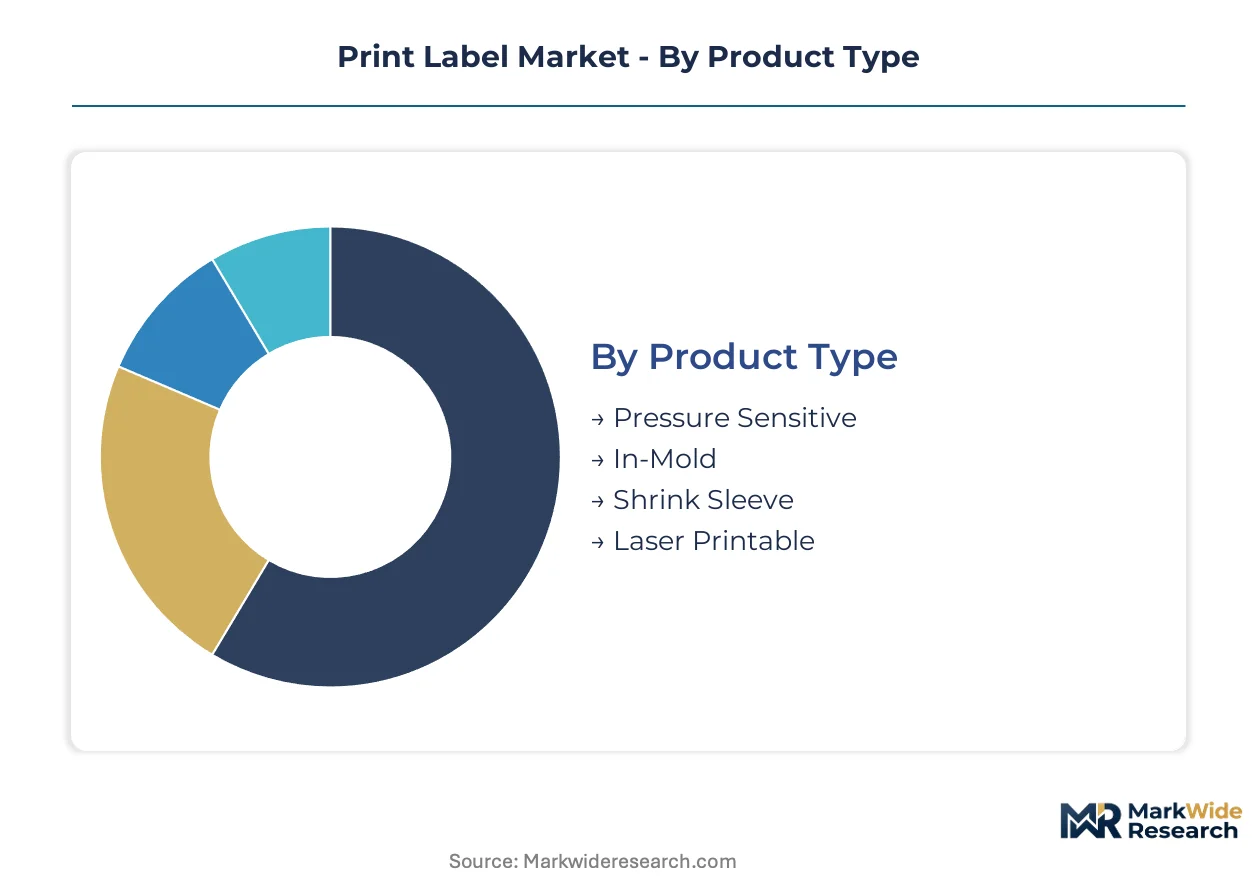
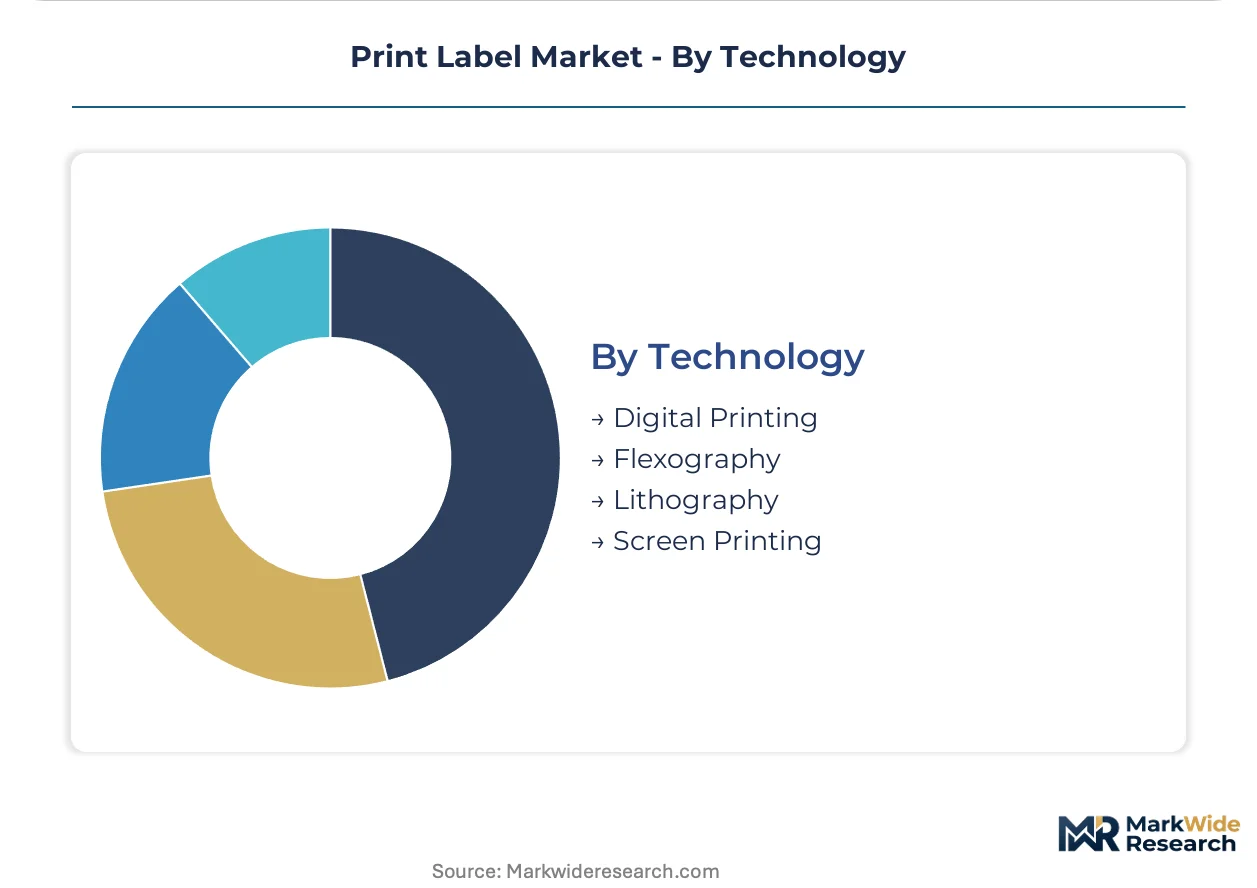
Print label segmentation reveals how substrate selection, application requirements, and production technology intersect to determine margin structures. Converters configure equipment and raw material procurement around specific segment combinations rather than serving the market as a homogeneous whole.
Product Type:
Cost tier differentiation separates commodity pressure-sensitive volumes from premium architectural formats.
- Pressure Sensitive:Self-adhesive constructions with silicone release liners and permanent or removable acrylic adhesives. Food packaging lines in Germany and pharmaceutical exporters in India consume the majority of volume for high-speed automatic application.
- Shrink Sleeve:PETG or PVC films engineered to contract 40-70% when heated, delivering 360-degree graphics coverage. Beverage bottlers and personal care contract manufacturers specify these for shelf differentiation where container shape irregularities prevent conventional label adhesion.
- In-Mold:Polypropylene labels fused directly into injection-molded containers during the blow-molding process. Automotive fluid reservoirs and durable goods packaging in the US specify these for abrasion resistance.
- Laser Printable:Top-coated paper and synthetic substrates optimized for thermal transfer or direct thermal printing. Third-party logistics providers and e-commerce fulfillment centers deploy these for variable shipping information.
Pressure Sensitive commands the established base. The steepest expansion runs through Shrink Sleeve.
Material:
Application durability requirements and recyclability mandates drive material selection across converting operations.
- PET:Biaxially oriented polyester films offering dimensional stability and chemical resistance. Medical device manufacturers and industrial chemical producers specify PET for harsh environment labeling where moisture and solvent exposure degrades paper alternatives.
- Paper:Uncoated, coated, and thermal transfer grades derived from wood pulp or recycled fiber. E-commerce shipping labels and short-life consumer goods packaging concentrate demand in cost-sensitive applications.
- Vinyl:PVC and PVC-free flexible films with conformability to curved and irregular surfaces. Outdoor signage and marine equipment labeling in coastal manufacturing clusters specify vinyl for UV and saltwater resistance.
- Polypropylene:Oriented and cast films balancing moisture resistance with lower density than PET. Food contact applications and refrigerated supply chains favor polypropylene for its compliance with FDA and EFSA migration limits.
Paper retains the volume anchor. Polypropylene is gaining share fastest.
Application:
End-use regulatory intensity and SKU velocity create divergent procurement patterns across customer verticals.
- Food Packaging:Labels engineered for direct or indirect food contact with migration-tested inks and adhesives. EU Green Deal recyclability requirements and FSSAI labeling mandates in India are accelerating wash-off adhesive adoption.
- Medical Devices:Sterilization-resistant constructions with tamper-evidence and temperature-indicating features. FDA UDI serialization and EU MDR traceability requirements expand premium substrate specifications.
- Industrial Labeling:Chemical-resistant and outdoor-durable formats for asset tracking and safety compliance. OSHA hazard communication standards and REACH substance restrictions shape ink and substrate selection.
- Retail Branding:Promotional and primary package labels prioritizing shelf impact and brand equity. CPG procurement consolidation in Benelux and Nordics is imposing recycled-content minimums on supplier qualifications.
Food Packaging anchors procurement volumes. Medical Devices is climbing the fastest.
Technology:
Production method determines minimum order economics, color gamut, and variable-data capabilities.
- Digital Printing:Inkjet and electrophotographic systems eliminating plate costs and enabling lot-size-one production. Pharmaceutical contract packagers in Germany adopt single-pass inkjet to eliminate pre-printed inventory obsolescence.
- Flexography:Rotary relief printing with photopolymer plates and UV or solvent-based inks. High-volume food and beverage packaging lines rely on flexography for unit economics at runs above 10,000 units.
- Lithography:Offset printing with metal plates and rubber blankets delivering fine-line detail and color consistency. Premium spirits and cosmetics packaging specify lithography for metallic effects and tight registration.
- Screen Printing:Stencil-based deposition of thick ink films for opacity and durability. Industrial nameplates and automotive under-hood labels specify screen printing for chemical and abrasion resistance.
Flexography commands the established base. Digital Printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical exporters and e-commerce fulfillment operators concentrate procurement power across Germany, the United States, India, China, and Japan. Label converters in these markets face diverging regulatory timelines for recyclability mandates and serialization requirements.
Germany
Automotive fluid reservoir manufacturers and pharmaceutical contract packagers drive demand for sterilization-resistant and abrasion-proof substrates. The EU MDR traceability requirements and F-Gas Regulation emissions controls force converters to reformulate adhesives and eliminate fluorinated coatings. The Baden-Württemberg and Bavaria industrial corridors host dense clusters of medical device and automotive suppliers qualifying multi-language, tamper-evident labels.
United States
FDA UDI serialization for medical devices and nutritional facts enforcement expand premium substrate specifications. Third-party logistics providers and e-commerce fulfillment centers compress procurement cycles to same-day turnaround for variable shipping data. The Midwest manufacturing belt and Southeast distribution hubs concentrate digital press installations serving pharmaceutical and consumer goods verticals.
India
Generic drug manufacturing in Hyderabad and Ahmedabad creates demand for CDSCO-compliant serialization labels with multi-language anti-counterfeit features. FSSAI food contact mandates accelerate wash-off adhesive adoption for export-oriented beverage and dairy packaging. The Gujarat and Maharashtra industrial zones anchor converter capacity for pharmaceutical and processed food exports.
China
SAMR enforcement of GB standards for food contact materials shapes export-oriented label specifications. Domestic e-commerce platforms drive volume for laser-printable shipping substrates in fulfillment centers. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate pressure-sensitive converting capacity serving electronics and consumer goods exporters.
Japan
PMDA pharmaceutical serialization and METI sustainability guidelines push converters toward recyclable film substrates. Precision electronics and automotive component manufacturers specify high-durability labels for harsh environment applications. The Kansai and Chubu industrial regions host specialty coating operations serving medical device and industrial equipment exporters.
Print Label Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where materials science capabilities separate premium pricing from commodity volumes. The vendor base clusters around three archetypes: integrated materials-converters commanding substrate-coating-printing value chains, pure-play converters leasing digital capacity to serve brand owners, and specialty coating suppliers enabling third-party label constructions. Dominant competitive moves include backward integration into release liner and adhesive production, plus asset-light partnerships with e-commerce logistics platforms.
Within the integrated materials tier, Avery Dennison Corporation and CCL Industries Inc. exemplify archetypes combining substrate formulation with converting operations. Mondi plc occupies a position bridging fiber-based substrate innovation with sustainability-mandated procurement channels. These entities represent how materials science depth converts into preferred-supplier status under retailer and regulatory sustainability frameworks.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Multi-Color Corporation |
| Mondi plc |
| Brady Corporation |
| Fuji Seal International, Inc. |
| 3M Company |
| Huhtamaki Oyj |
| Ahlstrom-Munksjö Oyj |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta converting cluster anchors global pressure-sensitive capacity, and its silicone-coated liner production dominance transmits directly into pricing leverage for converters serving European pharmaceutical exporters. Cost compression in mid-tier commodity substrates intensifies as digital press leasing models erode volume-based economies of scale.
Pricing Analysis
Certification level creates the primary spread across the print label market, with FDA-grade serialization substrates commanding substantial premiums over standard food-contact grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by migration-testing burden and release liner quality. Price erosion runs through commodity pressure-sensitive volumes as asset-light digital entrants compress minimum-order economics. E-commerce fulfillment centers exhibit highest price sensitivity due to velocity-driven procurement cycles, while pharmaceutical contract packagers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Acrylic and rubber-based polymer feedstock supply draws from petrochemical complexes concentrated in Germany, China, and the United States. Silicone-coated glassine and PET release liner production rests on specialized coating operations in Baden-Württemberg and the Pearl River Delta. Single-source vulnerability in liner substrates exposes converters outside these hubs to geographic concentration risk. Distribution runs through converter-direct relationships with brand owner procurement teams, increasingly consolidated under centralized packaging category managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Print label procurement is undergoing a platform-economics inflection as web-to-print portals and automated prepress workflows force interoperability investments across legacy ERP systems. This interoperability imperative rewards converters with API-first infrastructure.
For Market Incumbents: Build regulatory compliance moats through captive migration-testing laboratories and REACH-certified adhesive formulation capabilities. Pharmaceutical serialization mandates and EU F-Gas Regulation reformulation requirements create defensive barriers against digital-native entrants lacking chemistry expertise. Backward integration into specialty coatings secures substrate supply against silicone liner concentration.
For New Entrants and Emerging Players: Indian pharmaceutical export labeling represents the most penetrable entry point, with CDSCO serialization requirements and Hyderabad-Ahmedabad manufacturing expansion creating demand for multi-language anti-counterfeit solutions. RFID-inlay convergence with pressure-sensitive labels offers a go-to-market angle through third-party logistics provider contracts in apparel and electronics verticals.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with hybrid digital-flexographic asset bases capable of serving both SKU-proliferating brand owners and high-volume food packaging lines. Acquisition targets should demonstrate qualified wash-off adhesive portfolios aligned with EU Green Deal recyclability mandates. Monitor extended producer responsibility legislation rollout across France and Benelux as inflection indicator for substrate specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captive supply of REACH-compliant chemistry insulates margin from petrochemical volatility. |
| Digital Press Fleet Leasing Partnerships | Asset-light models enable mid-tier converters to serve brand owners without capital-heavy equipment ownership. |
| RFID-Inlay Convergence Development | UHF chip integration opens inventory-automation contracts with third-party logistics providers. |
| Wash-Off Adhesive Qualification | EU Green Deal recyclability mandates reward early-mover converters with preferred-supplier status. |
| Web-to-Print Portal Deployment | API-first infrastructure captures e-commerce fulfillment velocity requirements compressing procurement cycles. |
Research Approach
Initial hypotheses were tested against primary input from converter operations managers, brand owner packaging procurement leads, and regulatory affairs specialists at adhesive suppliers, then refined through secondary validation. Primary fieldwork encompassed technical directors at digital press manufacturers and sustainability officers at multinational consumer packaged goods companies. Secondary sources included FDA UDI submission databases, ECHA REACH registration dossiers, and customs trade data tracking pressure-sensitive substrate flows. Bottom-up capacity modeling and top-down demand triangulation anchored value estimates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, material substrate, end-use application, and production technology. CAGRs were derived from growth driver intensity scoring applied to base-year consumption estimates. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate implementation timelines and e-commerce fulfillment center expansion trajectories.
Practitioners should monitor regulatory timeline shifts for extended producer responsibility and petrochemical price volatility for early signals of forecast revision. Cross-checking against ECHA substance restriction announcements and SAMR GB standard updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Future-Proof Pharma Labels Market
Labels
Global QR Code Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Integrated Labeling System Market
Labels
Syringe Labels Market
Labels
Wrap Around Labels Market
Labels
Self-Laminating Labels Market
Labels
Global Automotive Labels Market
Labels
Global Sensormatic Labels Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Printable Tags Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Global Laminated Labels Market