
 Indicative Seals Market | 2026-2036
Indicative Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Indicative Seals Market Foresight
Asian polymer compounders is pivoting toward high-performance engineered resins for indicative seal production. TruSeal leverages captive resin formulation to sustain margin control across pharmaceutical and food-grade product lines. MM Megafortris anchors European demand through specialized metal seal manufacturing for customs and border applications. Tyden Group competes in North American logistics with extended distribution networks serving freight and rail carriers.
Indicative seals are single-use mechanical devices engineered to provide visual evidence of tampering or unauthorized access, typically manufactured from acrylonitrile butadiene styrene, polypropylene, or zinc-plated steel with tensile ratings calibrated to application-specific break thresholds. Their primary commercial purpose is to secure cargo containers, pharmaceutical packaging, and utility meters while enabling immediate field inspection without specialized equipment. Plastic seals dominate volume in food and beverage logistics where cost-per-unit and disposability govern procurement decisions, while metal seals command premium positioning in high-security transportation and customs applications where ISO 17712 compliance is mandatory. Composite seals represent the fastest-growing structural category as manufacturers blend polymer housings with metal locking inserts to bridge performance and cost requirements across pharmaceutical cold-chain packaging.
FDA serialization mandates and EU Falsified Medicines Directive compliance requirements are forcing pharmaceutical supply chain participants to upgrade tamper-evidence standards, directly expanding demand for traceable indicative seals with embedded barcodes or RFID compatibility. REACH substance restrictions and ECHA candidate list screenings are reshaping polymer formulations as compounders eliminate phthalate plasticizers and heavy-metal pigments from seal production. Stakeholders must monitor evolving pharmacopeial tamper-evidence standards and customs security protocols to align product development with procurement specifications before regulatory deadlines harden.
Market Dynamics
Pharmaceutical serialization mandates are compressing procurement cycles for traceable tamper-evidence hardware, forcing seal manufacturers to reconfigure production lines around barcode-embedded and RFID-compatible formats before regulatory deadlines harden.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace requirements for prescription packaging are expanding pharmaceutical demand for serialized indicative seals with unique identifiers.
- Laser-marking technology:Permanent, non-removable surface encoding is displacing printed labels in cold-chain logistics where adhesive degradation threatens chain-of-custody documentation.
- German pharmaceutical exporters:Concentrated upgrading of seal procurement standards at logistics hubs serving EU-wide distribution networks is pulling premium metal-composite formats.
Market Restraints
- Engineered resin cost volatility:Acrylonitrile butadiene styrene and high-performance polypropylene compounds face price pressure from petrochemical feedstock fluctuations.
- Asian polymer compounder concentration:Captive resin formulation capabilities are consolidating among a narrow supplier base, constraining margin control for downstream seal fabricators.
- ISO 17712 certification friction:Mandatory third-party testing for high-security seal classifications extends product development timelines and elevates compliance overhead.
Strategic Opportunities
- India pharmaceutical cold-chain expansion:CDSCO serialization rollout and domestic vaccine distribution infrastructure are creating demand for temperature-resistant indicative seals.
- RFID-NFC convergence:Near-field communication chip integration with traditional mechanical seals is enabling real-time location tracking without specialized scanning equipment.
- EU Falsified Medicines Directive enforcement gaps:Secondary packaging compliance deadlines in member states with lagging implementation create near-term procurement windows.
Industry Challenges
- Polymer formulation chemistry expertise:REACH substance restrictions and ECHA candidate list screenings require specialized regulatory affairs capabilities that smaller fabricators struggle to staff.
- Legacy serialization infrastructure integration:Pharmaceutical contract packagers face technical friction retrofitting existing lines to accommodate seal-mounted barcode verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indicative Seals Market |
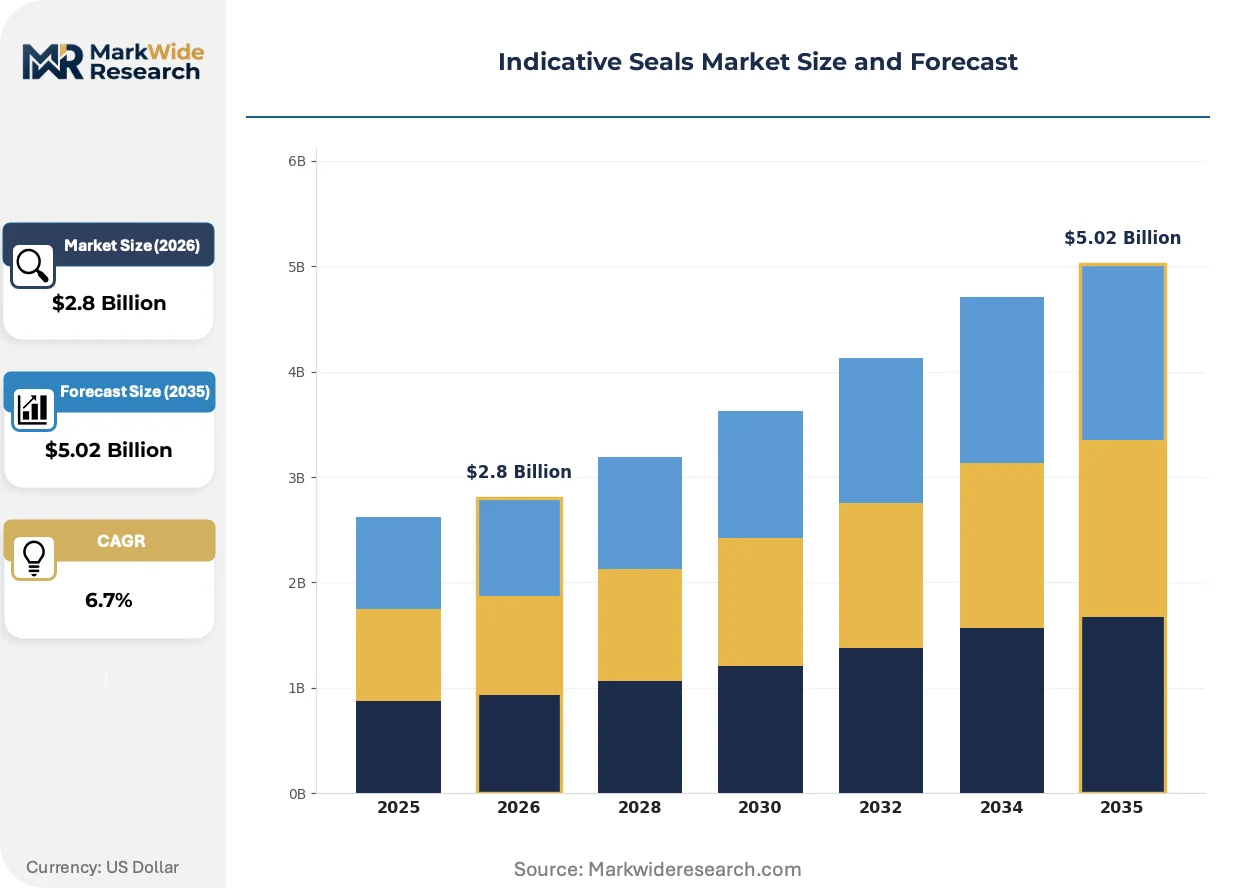
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Seals, Metal Seals, Composite Seals, Specialty Seals Industry Vertical: Pharmaceutical, Food & Beverage, Logistics, Manufacturing Application: Packaging, Transportation, Security, Inventory Management End User: Retailers, Distributors, Manufacturers, Logistics Providers |
| Companies Covered | TruSeal, MM Megafortris, Tyden Group, Cathay Seal, Leghorn Group, HSA International Group, Unisto, Hoefon Security Seals, ITW Envopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indicative Seals Market Shifts & Advancements
Digital traceability architectures are displacing visual-only tamper evidence across pharmaceutical and high-value logistics applications, compressing the viable product set toward intelligent seal formats.
Radio-frequency identification is integrating with zinc-plated steel locking mechanisms to create hybrid security devices that transmit location and integrity data without physical inspection. Cold-chain pharmaceutical distributors in Germany and the Netherlands are adopting these formats at scale to satisfy EU Good Distribution Practice documentation requirements. The technology is integrating previously separate mechanical security and electronic tracking functions into single-unit procurement decisions.
REACH substance restrictions are eliminating phthalate plasticizers and heavy-metal pigments from seal polymer formulations, forcing compounders to certify alternative stabilizer packages. ECHA candidate list screenings now cover colorants previously standard in food-grade indicative seals. European medical device and pharmaceutical packaging sectors are responding by demanding full material disclosure documentation upstream.
Buyer consolidation among third-party logistics providers is compressing supplier rosters and elevating performance-based contract terms over unit-price negotiations. Large freight forwarders in North American and European corridors are unbundling seal procurement from broader packaging supply agreements to secure dedicated technical support. This pattern is most visible in trans-Atlantic pharmaceutical lanes where customs pre-clearance programs reward standardized tamper-evidence protocols.
Indicative Seals Market Segmentation
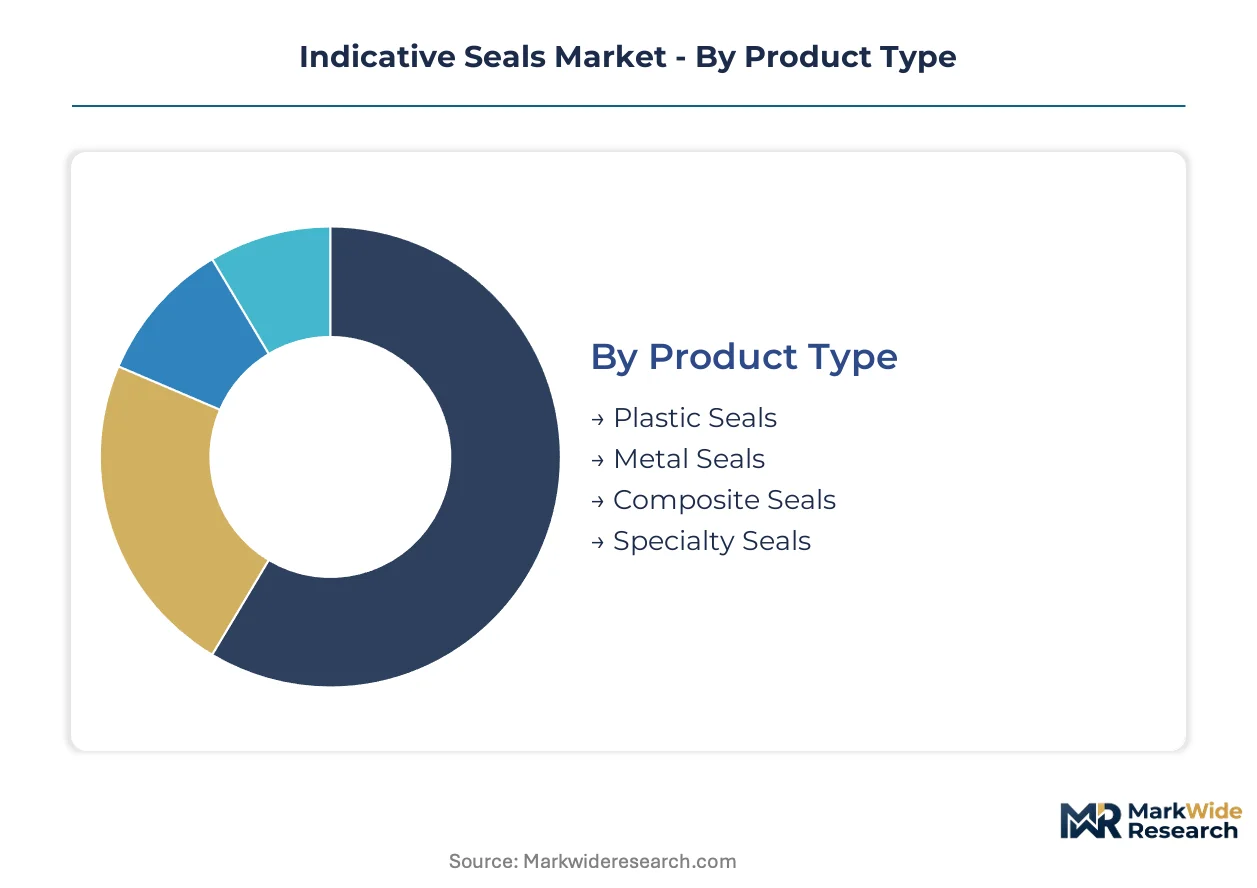
Indicative seal procurement decisions split across material performance tiers and regulatory compliance thresholds. Buyers calibrate specifications against break-strength requirements, environmental exposure, and serialization mandates rather than unit cost alone.
Product Type:
Material composition determines tensile strength, weather resistance, and regulatory acceptance across deployment environments.
- Plastic Seals:Injection-molded acrylonitrile butadiene styrene and polypropylene variants dominate food and beverage logistics where single-use disposability and cost-per-unit govern procurement. German pharmaceutical exporters are upgrading from standard plastic to laser-markable grades to satisfy EU Falsified Medicines Directive serialization requirements before compliance deadlines harden.
- Metal Seals:Zinc-plated steel locking mechanisms with ISO 17712 high-security certification command premium positioning in customs and cross-border freight applications. Demand concentrates at Rotterdam and Hamburg logistics hubs where customs pre-clearance programs reward standardized tamper-evidence protocols.
- Composite Seals:Hybrid polymer housings with metal locking inserts bridge performance and cost requirements.
- Specialty Seals:Temperature-resistant and RFID-embedded formats serve pharmaceutical cold-chain packaging with embedded barcodes or NFC compatibility.
Mature deployment sits with plastic seals in food logistics. Newer deployment is concentrated in composite and specialty formats for pharmaceutical serialization.
Industry Vertical:
End-use sector dictates specification intensity, from basic tamper evidence to integrated digital traceability.
- Pharmaceutical:FDA Drug Supply Chain Security Act and EU Falsified Medicines Directive mandates are compressing procurement cycles for traceable seals with unique identifiers. Cold-chain distributors in Germany and the Netherlands are adopting RFID-steel hybrids at scale to satisfy EU Good Distribution Practice documentation requirements.
- Logistics:Freight forwarders and third-party logistics providers are unbundling seal procurement from broader packaging agreements to secure dedicated technical support. North American rail and intermodal carriers specify ISO 17712-compliant metal seals for high-value cargo security.
- Food & Beverage:Cost-driven plastic seal consumption dominates where adhesive degradation and temperature cycling threaten label integrity.
- Manufacturing:Utility metering and industrial asset tracking applications favor standardized mechanical formats without electronic augmentation.
Specification intensity peaks in pharmaceutical verticals. Volume concentration remains in food and beverage logistics.
Application:
Functional use case determines whether visual tamper evidence suffices or integrated electronic tracking becomes mandatory.
- Transportation:Container and trailer sealing across trans-Atlantic pharmaceutical lanes demands hybrid mechanical-electronic formats. Large freight forwarders are standardizing on RFID-compatible seals to enable real-time location tracking without specialized scanning equipment.
- Packaging:Secondary pharmaceutical packaging compliance deadlines in EU member states with lagging implementation create near-term procurement windows for barcode-embedded indicative seals.
- Security:Customs and border applications require ISO 17712 high-security classification with mandatory third-party testing extending product development timelines.
- Inventory Management:Warehouse and distribution center applications favor cost-optimized plastic formats with basic sequential numbering.
Electronic integration is expanding fastest in transportation applications. Basic mechanical formats persist in inventory management.
End User:
Buyer scale and technical capability determine whether procurement emphasizes unit price or performance-based contract terms.
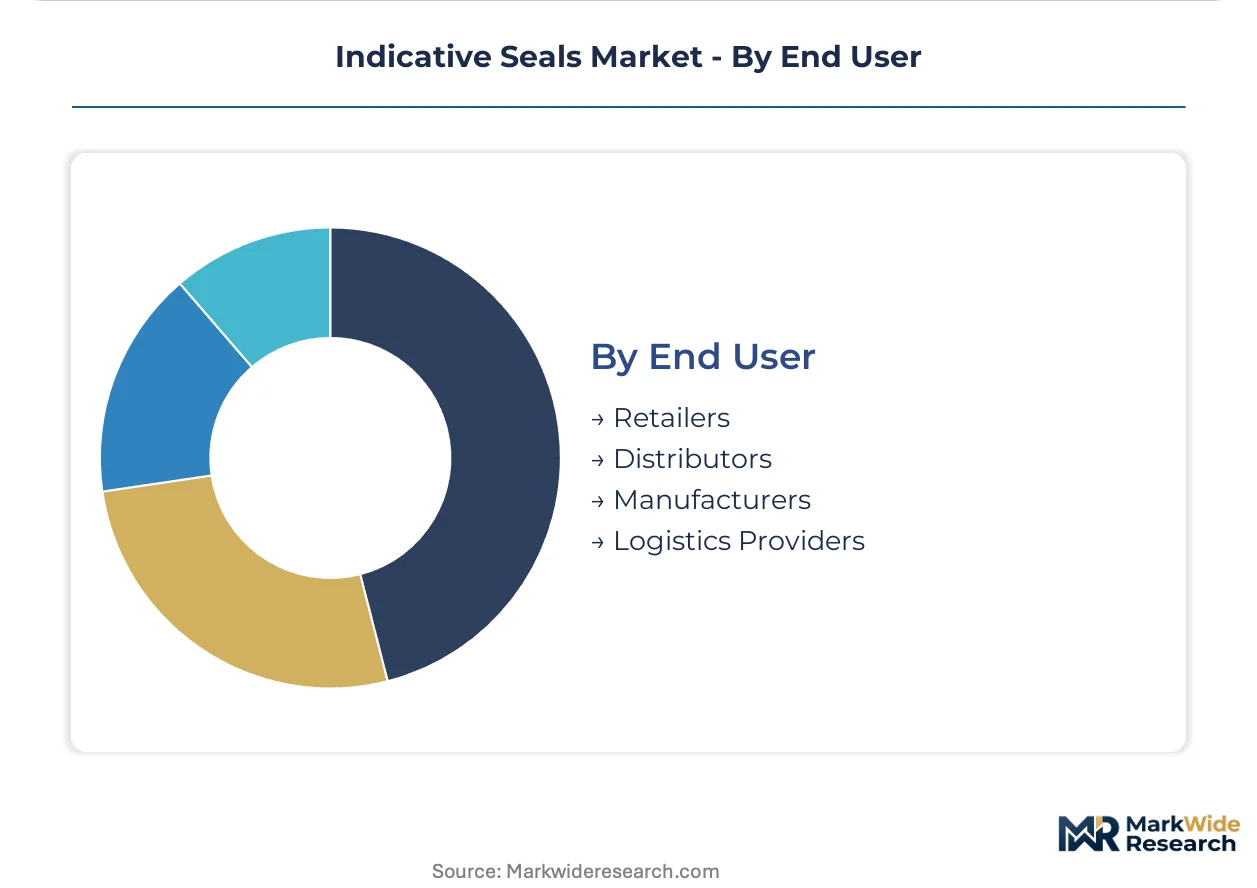
- Logistics Providers:Consolidation among third-party logistics providers is compressing supplier rosters and elevating dedicated technical support requirements over unit-price negotiations. Buyer concentration at major freight forwarders enables volume-based standardization across pharmaceutical and high-value cargo lanes.
- Distributors:Pharmaceutical and medical device distributors face REACH substance restrictions and ECHA candidate list screenings demanding full material disclosure documentation upstream from seal suppliers.
- Manufacturers:Captive resin formulation capabilities among Asian polymer compounders constrain margin control for downstream seal fabricators serving manufacturing end users.
- Retailers:Food and beverage retail chains prioritize cost-per-unit and disposability in private-label logistics operations.
Contract sophistication concentrates with logistics providers. Price sensitivity dominates retailer procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock concentration along the US Gulf Coast and German Rhine-Ruhr corridor anchors polymer compounder positioning for seal resin supply. Seal fabricators co-locate near these feedstock zones to compress logistics costs and accelerate formulation iteration cycles.
United States
FDA Drug Supply Chain Security Act serialization deadlines are pulling pharmaceutical distributors toward RFID-embedded indicative seals with permanent laser marking. Houston-area polymer compounders supply acrylonitrile butadiene styrene formulations to domestic seal fabricators serving cold-chain vaccine distribution networks. The Port of Long Beach and Port of New York logistics clusters are standardizing on ISO 17712-compliant metal seals for customs pre-clearance cargo security.
Germany
EMA serialization requirements and EU Falsified Medicines Directive enforcement are compressing procurement cycles for traceable tamper-evidence hardware. The Hamburg logistics hub and Frankfurt pharmaceutical distribution corridor are upgrading seal specifications toward composite polymer-metal formats with embedded barcodes. REACH substance restrictions are forcing compounders in the Rhine-Ruhr industrial zone to eliminate phthalate plasticizers from seal formulations.
China
NMPA track-and-trace mandates for domestic pharmaceutical packaging are expanding demand for serialized indicative seals with unique identifiers. Yangtze River Delta polymer compounders in Shanghai and Jiangsu province dominate captive resin formulation for cost-optimized plastic seal exports. The Pearl River Delta manufacturing cluster is pivoting toward high-performance engineered resins to serve pharmaceutical cold-chain specifications.
India
CDSCO serialization rollout and domestic vaccine distribution infrastructure are creating procurement windows for temperature-resistant indicative seals. Gujarat and Maharashtra pharmaceutical manufacturing zones are upgrading tamper-evidence standards to align with EU export requirements. Mumbai logistics hubs are adopting laser-markable seal grades to satisfy documentation requirements under EU Good Distribution Practice.
Netherlands
Rotterdam's customs pre-clearance programs reward standardized tamper-evidence protocols for trans-Atlantic pharmaceutical freight. ECHA candidate list screenings are reshaping polymer formulations as compounders certify alternative stabilizer packages for food-grade seal production. The Randstad distribution corridor is concentrating demand for RFID-steel hybrid seals among cold-chain logistics providers serving Benelux pharmaceutical networks.
Indicative Seals Market Competitive Landscape
Global majors compete with regional champions across material formulation expertise and regulatory certification capabilities. The vendor base stratifies between polymer compounders with captive resin capabilities and specialized metal seal fabricators serving customs applications. Three archetypes dominate: vertically integrated resin-to-seal manufacturers, ISO 17712 certification specialists, and logistics-focused distributors with technical support capabilities. Competitive positioning hinges on M&A activity consolidating polymer formulation assets and strategic partnerships embedding RFID technology into mechanical seal platforms.
Among European-based fabricators, TruSeal and MM Megafortris occupy distinct positioning archetypes. TruSeal exemplifies the vertically integrated resin-to-seal model with captive formulation capabilities sustaining margin control across pharmaceutical and food-grade product lines. MM Megafortris anchors specialized metal seal manufacturing for customs and border applications where ISO 17712 compliance is mandatory. Tyden Group represents the North American logistics-focused distributor archetype with extended networks serving freight and rail carriers. These three companies illustrate how geographic origin and structural approach segment competitive positioning without overlapping capability claims.
| Leading Market Players |
|---|
| TruSeal |
| MM Megafortris |
| Tyden Group |
| Cathay Seal |
| Leghorn Group |
| HSA International Group |
| Unisto |
| Hoefon Security Seals |
| ITW Envopak |
| Others |
Supply & Pricing Matrix
Acrylonitrile butadiene styrene spot indices on the US Gulf Coast and German Rhine-Ruhr corridor cascade through three distinct pricing tiers, with pharmaceutical-grade laser-markable compounds commanding premiums over food-grade polypropylene variants and unmarked economy seals serving bulk logistics procurement.
Pricing Analysis
Warranty-backed ISO 17712 certification and technical support bundling separate premium metal-composite seals from unbundled economy plastic formats. Three-tier pricing structure across premium, standard, and economy levels reflects break-strength ratings, serialization compatibility, and REACH compliance documentation depth. Price differentiation hinges on laser-marking capability and RFID-NFC chip integration, with cost compression in standard plastic tiers intensifying due to Asian polymer compounder consolidation. Retail food chains exhibit highest price sensitivity, while German pharmaceutical exporters prioritize performance-based contracts over unit-cost negotiations.
Supply Chain Analysis
Returns and refurbishment flows for metal locking mechanisms concentrate in Rotterdam and Hamburg logistics hubs, where customs pre-clearance programs standardize seal reuse protocols. Manufacturing gravity centers on China, Germany, and India, with Yangtze River Delta compounders feeding cost-optimized plastic exports and Rhine-Ruhr formulators serving pharmaceutical-grade specifications. Raw material dependencies span ABS petrochemical feedstocks, zinc-plated steel coils, and NFC chip components. Single-source vulnerability in Asian captive resin formulation threatens margin stability for downstream fabricators. Distribution runs through third-party logistics provider networks with unbundled seal procurement agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indicative Seals Market functions as a cost-of-compliance arena where ISO 17712 certification and REACH substance documentation erect barrier-to-entry moats favoring incumbents with established regulatory affairs capabilities.
For Market Incumbents: Hedge against Asian polymer compounder consolidation by securing captive resin formulation partnerships or backward integration into ABS compounding. Defensive moves center on accelerating RFID-NFC convergence R&D and pre-empting FDA serialization mandate deadlines with barcode-embedded product lines. Threats emerge from vertically integrated Chinese exporters undercutting European metal-seal premiums. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian pharmaceutical cold-chain applications offers white-space penetration potential. Target temperature-resistant laser-markable grades for CDSCO serialization rollout and domestic vaccine distribution infrastructure. Go-to-market execution should leverage Mumbai logistics hub relationships and EU export alignment consulting. For Investors and Strategic Acquirers: The window for entry favors ISO 17712 certification specialists with established third-party testing relationships and polymer formulation expertise. Long-term viability rests on regulatory compliance capabilities deepening as ECHA candidate list screenings expand. Monitor EU Falsified Medicines Directive enforcement gaps across lagging member states as inflection indicators for near-term procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive ABS compounding insulates margin control from petrochemical feedstock volatility. |
| RFID-NFC Convergence Product Launch | Hybrid mechanical-electronic formats satisfy EU Good Distribution Practice documentation requirements. |
| Laser-Marking Technology Licensing | Permanent surface encoding displaces adhesive labels in cold-chain pharmaceutical logistics. |
| ISO 17712 Certification Expansion | Third-party testing capabilities unlock customs pre-clearance program participation at Rotterdam and Hamburg. |
| Joint Venture with Asian Compounders | Partnerships with Yangtze River Delta formulators secure cost-optimized plastic seal supply for food logistics. |
Research Methodology
Independent corroboration across seal fabricator procurement directors, polymer compounder technical R&D leads, pharmaceutical logistics compliance officers, and customs brokerage operations managers underwrites the qualitative findings. Primary interviews with freight forwarder category buyers and cold-chain distributor warehouse operators combined with secondary validation from FDA DSCSA guidance documents, EMA serialization directives, ECHA candidate list publications, and customs trade data. Bottom-up demand modeling across material grades and top-down macroeconomic triangulation anchored volume projections.
Rate-of-change decomposition across the analysis window disaggregated growth into regulatory mandate compliance, technology substitution effects, and end-user consolidation patterns. Segmentation dimensions modeled include material composition tiers, industry vertical specification intensity, application functional requirements, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted demand curves incorporating REACH substance restriction timelines and ISO certification adoption curves.
Inputs from ECHA regulatory filings and customs pre-clearance program documentation were available through the study window; gaps in real-time polymer compounder capacity utilization data introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding FDA and EMA serialization enforcement rigor. Practitioners should monitor CDSCO implementation pace and EU member state FMD compliance deadlines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Thermal Transfer Label Market
Labels
Retro-Reflective Labels Market
Labels
Global Laminated Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Hang Tags Market
Labels
Self-Laminating Tags Market
Labels
Booklet Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Sustainable Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Glue-Applied Labels Market
Labels
Multi-Part Labels Market
Labels
Global Sensormatic Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Wire Marking Labels Market
Labels
Thermal Labels Market