
 Shower Curtain Market | 2026-2036
Shower Curtain Market Size, Share, and Industry Trends Forecast 2026-2036
Shower Curtain Market Analytics
Subscription-based home décor replenishment is expanding how shower curtain inventory moves through retail channels. Amazon.com Inc. leverages its Prime ecosystem to sustain recurring purchases through bundled bathroom accessory sets. Walmart Inc. competes on price-point density across vinyl and fabric SKUs in its store-brand portfolio. Inter IKEA Holding B.V. differentiates through Scandinavian design language and flat-pack logistics that reduce last-mile costs.
A shower curtain is a water-resistant or waterproof hanging barrier, typically constructed from vinyl, polyester, PEVA, or woven fabric treated with polyurethane coatings, designed to contain water spray within bathing enclosures. Its primary commercial purpose spans residential bathrooms, hospitality guest rooms, and institutional facilities where moisture control and sanitation protocols govern fixture selection. Fabric and PEVA categories command margin premiums as consumers migrate away from phthalate-laden vinyl alternatives. The hospitality end-user segment leads volume throughput due to standardized replacement schedules across hotel chains, while custom sizing captures project-based architectural specification work.
The EPA oversees VOC emissions from vinyl curtain manufacturing under Clean Air Act provisions, while REACH restricts phthalate plasticizers in European imports, directly channeling R&D spend toward PEVA and TPU-coated textiles. State-level California Proposition 65 enforcement has created a de facto national compliance floor for U.S. distributors, forcing reformulation across entire product lines regardless of destination market. Stakeholders must monitor evolving chemical disclosure regimes and decide whether to front-run biopolymer development or optimize existing polyester supply chains for cost resilience.
Market Dynamics
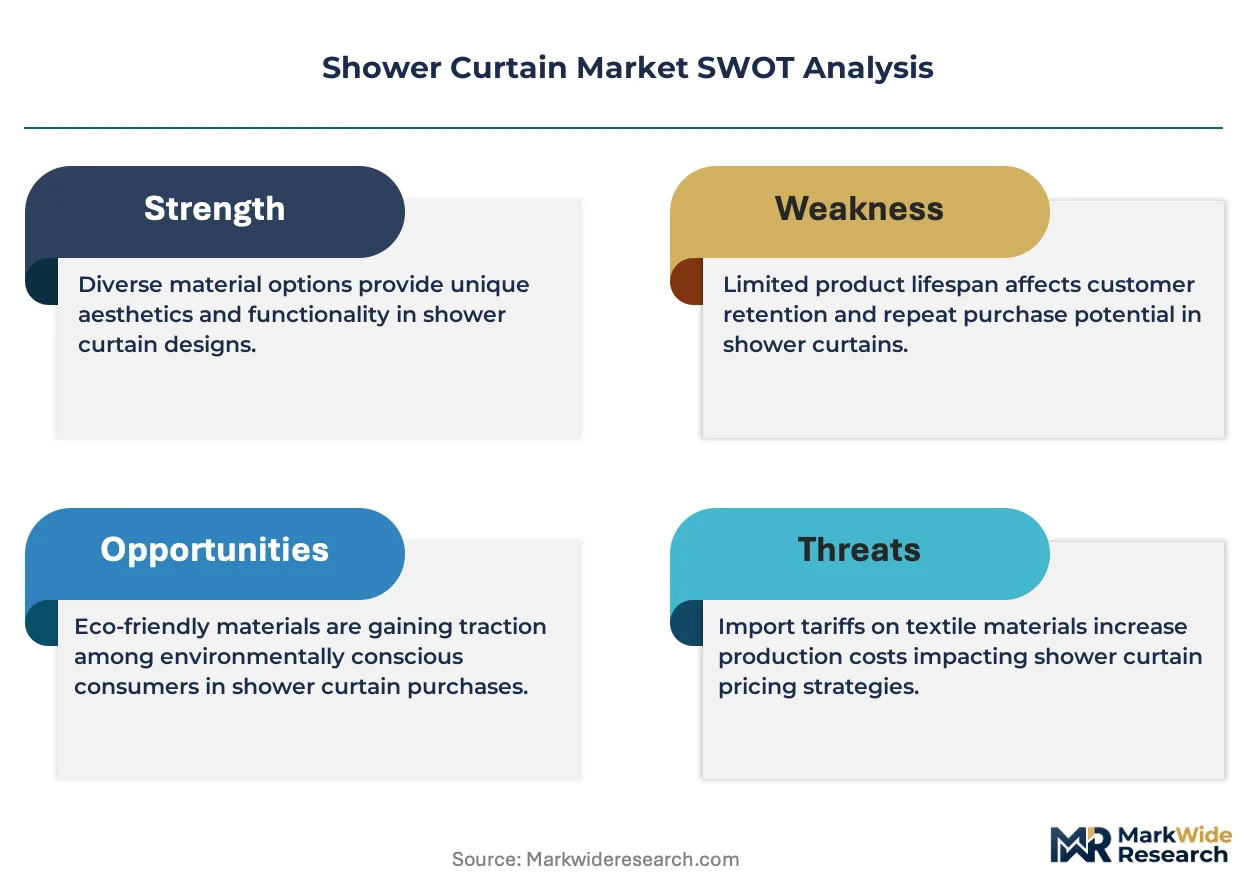
Material substitution away from phthalate-laden vinyl toward PEVA and certified polyester substrates is compressing legacy supply chains while elevating compliance costs across manufacturing clusters in Nantong, Shaoxing, and regional textile hubs.
Growth Catalysts
- REACH Phthalate Restrictions:ECHA enforcement in Europe is redirecting procurement spend toward PEVA and polyurethane-coated textiles, opening margin premiums for compliant suppliers.
- Hospitality Replacement Schedules:Hotel chains operate standardized refresh cycles that generate predictable volume throughput regardless of consumer discretionary pressure.
- Nantong Manufacturing Concentration:China's textile cluster economies enable private-label programs to achieve cost competitiveness at scale for global retail distribution.
Market Restraints
- Petrochemical Input Volatility:Ethylene and chlorine derivatives expose vinyl and PEVA producers to feedstock price swings that compress margin predictability.
- Single-Region Supply Concentration:China's dominance in woven polyester substrate production creates geopolitical and logistics risk for brands without alternative sourcing.
- California Proposition 65:State-level enforcement creates compliance friction that forces reformulation across entire product lines, elevating R&D overhead.
Strategic Opportunities
- Subscription Replenishment Channels:Amazon Prime's bundled bathroom accessory sets enable recurring revenue capture that traditional retail cannot replicate.
- Biopolymer Development:PLA and starch-based alternatives offer regulatory front-running potential as jurisdictions tighten petrochemical disclosure regimes.
- Flat-Pack Logistics Optimization:IKEA's compressed packaging reduces last-mile costs and opens direct-to-consumer penetration in dense urban markets.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise for TPU and bio-based coatings concentrates in legacy textile regions, constraining R&D expansion.
- Multi-Jurisdiction Certification Timelines:EPA VOC testing, REACH SVHC screening, and state-level disclosure requirements create staggered product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shower Curtain Market |
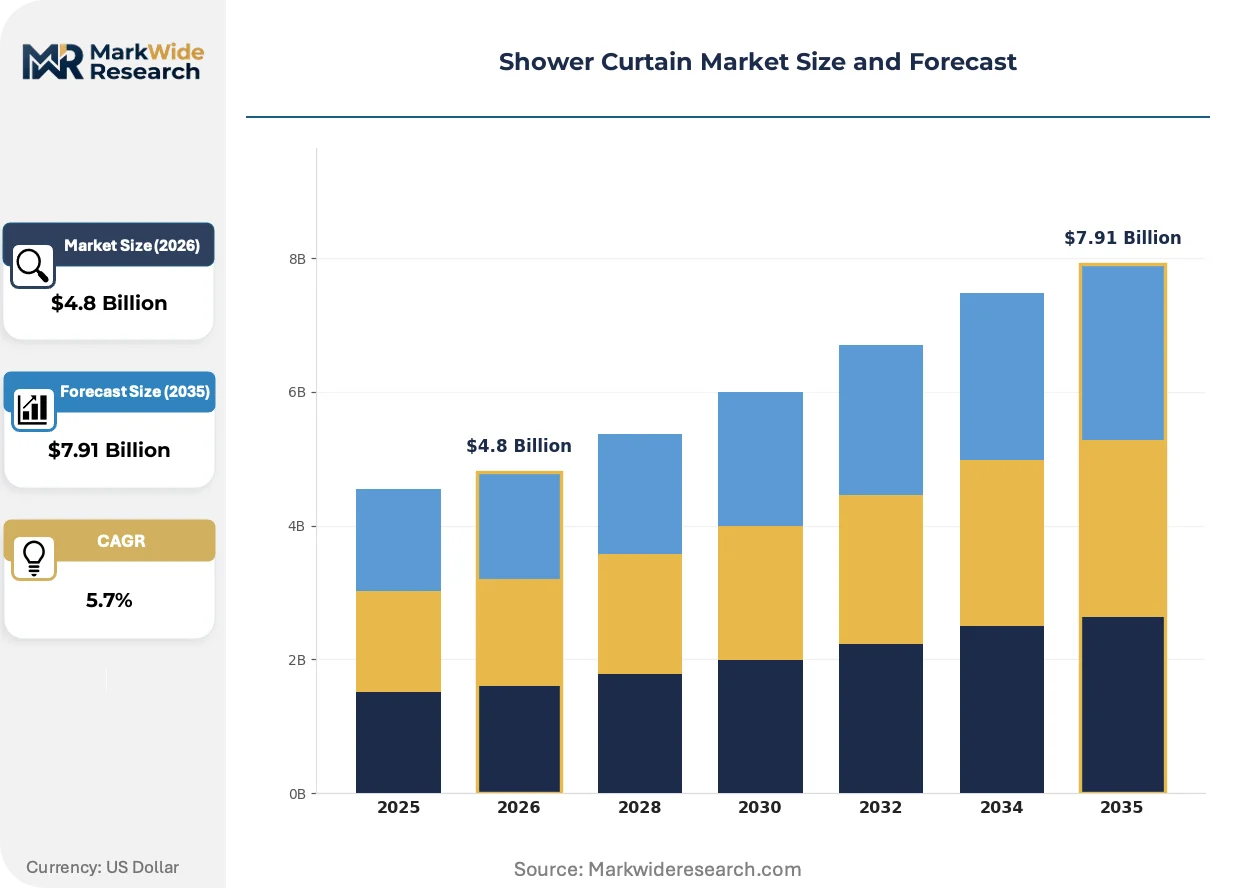
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric, Vinyl, Polyester, PEVA Design Style: Modern, Vintage, Patterned, Solid Color End User: Residential, Commercial, Hospitality, Institutional Size: Standard, Extra Wide, Extra Long, Custom |
| Companies Covered | Amazon.com Inc., The Home Depot Inc., Bed Bath & Beyond Inc., Walmart Inc., Target Corp., Lowe's Co. Inc., Chayi Textiles (Nantong) Co., Ltd., Moen, Inter IKEA Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shower Curtain Market Evolving Landscape
Digital printing and on-demand manufacturing are collapsing minimum order quantities while antimicrobial additive integration is rewriting performance specifications across institutional procurement.
PEVA substrate technology is rewriting competitive positioning in the vinyl-alternative segment. Hospitality procurement teams specify PEVA for guest room installations at accelerating rates. The material's chlorine-free composition enables compliance positioning that commands 15-30% shelf price premiums over legacy PVC.
EPA Clean Air Act oversight of VOC emissions from vinyl curtain manufacturing is elevating capital requirements for U.S.-based production. Fabricators must install thermal oxidizers or switch to water-based coating systems. California's Air Resources Board enforcement creates the strictest operational floor, forcing nationwide reformulation.
Bundled bathroom accessory sets through e-commerce channels are compressing traditional wholesale distribution. Amazon Prime's subscription infrastructure captures recurring replacement demand that big-box retail loses. This pattern concentrates most visibly in North American residential renovation activity where convenience outweighs price comparison.
Shower Curtain Market Segmentation
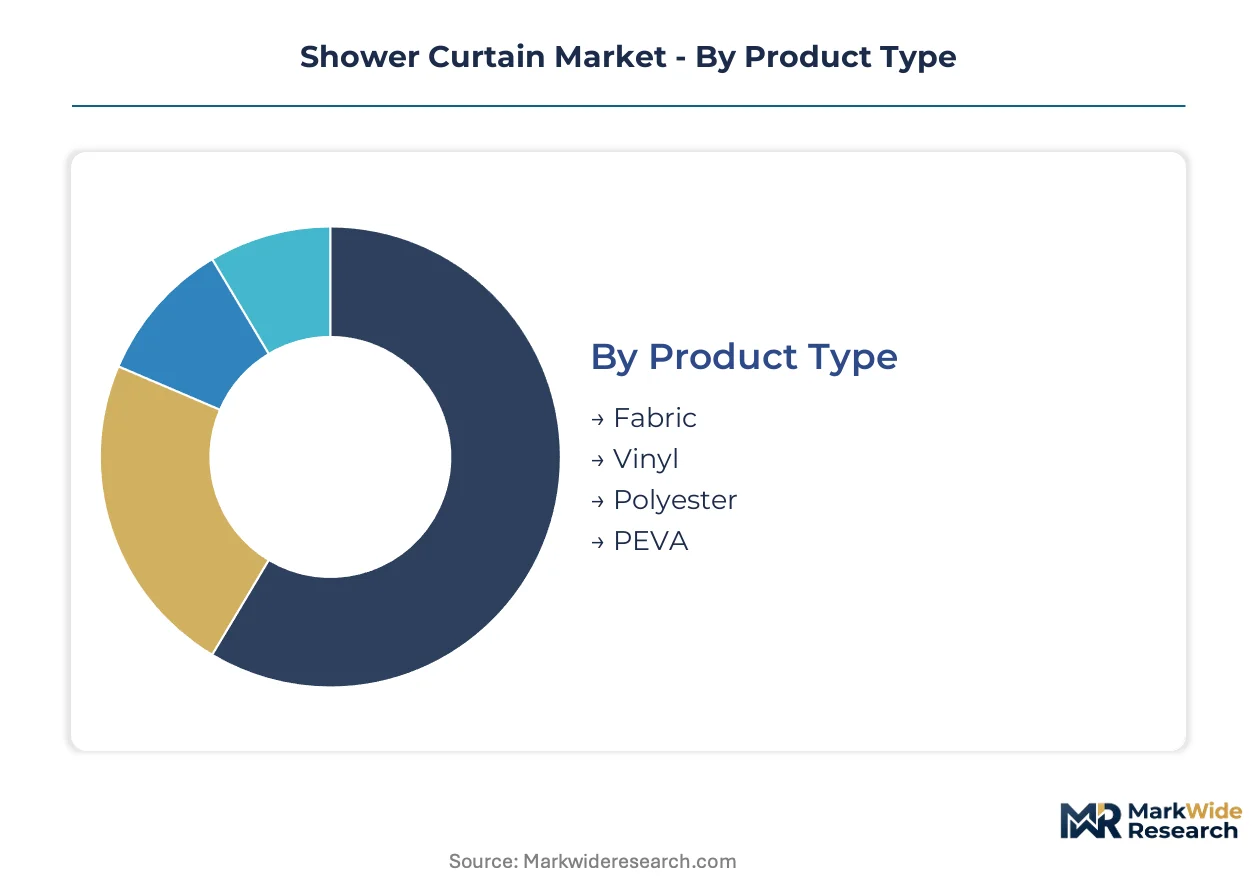
Shower curtain procurement patterns diverge sharply across material chemistry, aesthetic positioning, and facility type. Each segmentation axis carries distinct margin structures and compliance burdens that reshape supplier priorities.
Product Type:
Cost tier separates mass-market vinyl from premium-certified alternatives that command shelf price premiums.
- PEVA:Chlorine-free polymer substrate enables REACH and California Proposition 65 compliance without phthalate plasticizers. Hospitality procurement teams in Germany and France specify PEVA for guest room installations at accelerating rates, paying 15-30% shelf price premiums over legacy PVC alternatives.
- Fabric:Woven polyester or cotton substrates treated with polyurethane coatings deliver tactile warmth and machine-washable durability. North American residential renovation channels favor fabric for master bathroom upgrades where aesthetic integration with towel and rug collections drives purchase decisions.
- Vinyl:Legacy PVC construction remains entrenched in budget retail channels despite regulatory pressure; EPA Clean Air Act VOC enforcement elevates capital requirements for domestic manufacturing.
- Polyester:Synthetic woven base without coating offers entry-level water resistance at lowest unit cost; Shaoxing textile clusters supply global private-label programs at scale.
PEVA leads volumes today; fabric is gaining share fastest.
Design Style:
Application context dictates whether buyers prioritize visual neutrality or statement aesthetics.
- Solid Color:Minimalist palettes align with Scandinavian and Japanese interior trends; hospitality chains specify white, grey, and beige for brand-consistent guest room environments across properties.
- Modern:Geometric prints and abstract patterns target urban residential renovations; digital printing collapse minimum order quantities for boutique hospitality concepts.
- Patterned:Floral, nautical, and novelty motifs capture seasonal replenishment cycles in North American big-box retail; inventory risk concentrates with trend misjudgment.
- Vintage:Retro-inspired designs serve niche restoration projects and boutique hotel concepts seeking differentiated guest experiences.
Solid color leads volumes today; modern is expanding most quickly.
End User:
Volume predictability varies dramatically between scheduled replacement programs and discretionary consumer purchase.
- Hospitality:Hotel chains operate standardized refresh cycles—typically 12-24 months—that generate predictable procurement volume regardless of consumer discretionary pressure. Procurement teams negotiate multi-year supply agreements with Nantong manufacturers.
- Residential:Replacement demand ties to bathroom renovation activity and seasonal redecoration impulses; Amazon Prime subscription bundles capture recurring replenishment that traditional retail loses.
- Commercial:Office fitness centers and corporate wellness facilities specify antimicrobial-treated substrates under facility management protocols.
- Institutional:Hospitals, nursing homes, and correctional facilities prioritize infection control and durability over aesthetics; procurement runs through group purchasing organizations with stringent performance specifications.
Hospitality leads volumes today; residential is climbing the fastest.
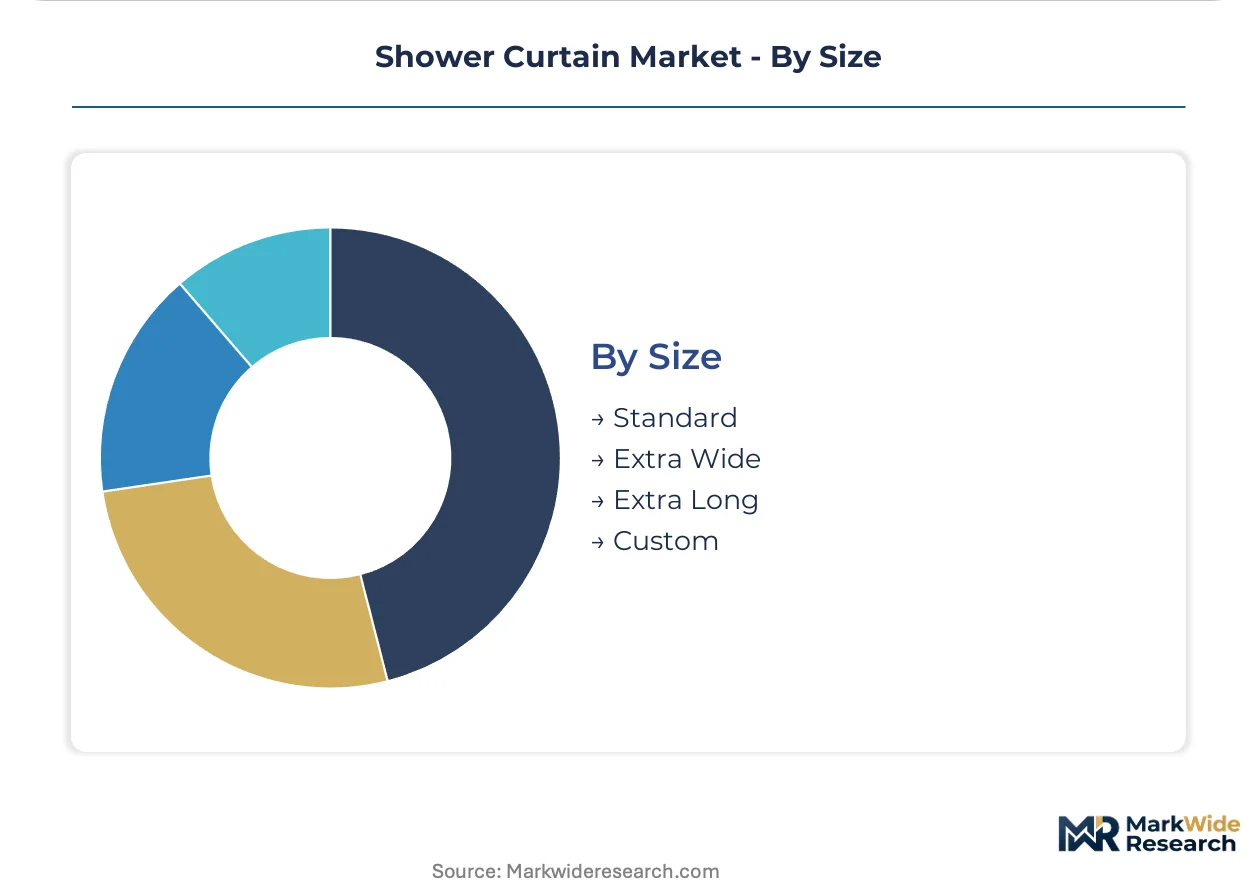
Size:
Customer type separates standard off-the-shelf purchases from project-based specification work with extended lead times.
- Standard:72x72 inch dimensions serve conventional bathtub enclosures; retail inventory concentrates here with highest turnover velocity and lowest working capital requirements.
- Custom:Architectural specification work for curved enclosures, ceiling-suspended installations, and hospitality wet rooms commands margin premiums but extends order-to-delivery cycles.
- Extra Wide:108+ inch widths accommodate clawfoot tubs and open shower designs gaining traction in luxury residential construction.
- Extra Long:84+ inch drops serve high-ceiling bathrooms and European wet room configurations; limited retail availability drives e-commerce penetration.
Standard leads volumes today; custom shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters supply global private-label volume, while the United States drives premium consumption through renovation channels. Germany enforces the strictest chemical compliance standards in Europe. India's emerging middle class is accelerating bathroom fixture upgrades.
United States
Residential bathroom renovation activity accelerates replacement cycles across California, Texas, and Florida. EPA Clean Air Act oversight of VOC emissions elevates capital requirements for domestic vinyl fabricators. Nantong-based exporters dominate supply to big-box retailers through long-term procurement agreements.
Germany
REACH phthalate restrictions redirect hospitality procurement toward PEVA alternatives in Frankfurt and Munich hotel markets. ECHA enforcement creates compliance premiums for certified suppliers. Berlin-based distributors coordinate private-label programs sourcing from Shaoxing textile clusters.
China
Manufacturing concentration in Nantong and Shaoxing enables cost competitiveness at scale for global retail distribution. MEE environmental standards tighten wastewater discharge requirements for textile coating operations. Yangtze River Delta logistics hubs consolidate export consolidation for North American and European buyers.
India
Urban residential construction in Maharashtra and Karnataka expands addressable market for mid-tier fabric curtains. BIS textile standards govern water-resistance certification for imported substrates. Gujarat chemical producers supply polyurethane coating intermediates to domestic converters.
United Kingdom
London and Southeast England renovation activity favors design-forward fabric categories over basic vinyl. UKCA marking requirements post-Brexit create parallel certification tracks to EU CE standards. Manchester-based importers maintain inventory positions for rapid-turn hospitality replenishment.
Shower Curtain Market Competitive Landscape
Top-tier vendors anchor mass retail distribution, while mid-tier specialists capture premium positioning through material innovation. The market structure stratifies across three tiers: global retailers controlling private-label volume, specialized textile converters serving hospitality specification, and regional fabricators competing on turnaround speed. Two strategic archetypes dominate: subscription-enabled e-commerce platforms and flat-pack logistics optimizers. Capacity expansion in Chinese manufacturing clusters and compliance-driven material reformulation represent the dominant competitive moves.
Among mass retail anchors, Amazon.com Inc. and Walmart Inc. exemplify the platform-versus-price dichotomy, with the former leveraging subscription infrastructure and the latter optimizing store-brand SKU density. Inter IKEA Holding B.V. occupies a distinct position through compressed packaging logistics and Scandinavian design positioning. Chayi Textiles (Nantong) Co., Ltd. represents the manufacturing-cluster archetype, anchoring private-label supply for global retail programs from its Yangtze River Delta base.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| The Home Depot Inc. |
| Bed Bath & Beyond Inc. |
| Walmart Inc. |
| Target Corp. |
| Lowe's Co. Inc. |
| Chayi Textiles (Nantong) Co., Ltd. |
| Moen |
| Inter IKEA Holding B.V. |
| Others |
Value Network & Pricing Analysis
Hospitality procurement teams operating standardized refresh cycles anchor the dominant contract-based long-term offtake pricing model. Their volume predictability enables manufacturers in Nantong and Shaoxing to optimize production scheduling and compress unit economics for global private-label programs.
Pricing Analysis
Capacity additions in Shaoxing textile clusters are reshaping price floors across polyester substrate tiers. Three-tier pricing structure across premium, standard, and economy levels separates PEVA-certified hospitality specifications from vinyl budget retail and uncoated polyester entry points. Cost compression in vinyl runs through EPA Clean Air Act compliance investments that elevate domestic manufacturing capital requirements. Budget retail channels exhibit highest price sensitivity, while hospitality procurement teams accept 15-30% premiums for REACH-compliant PEVA alternatives.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given shower curtain unit economics, though institutional procurement programs increasingly specify durable fabric substrates with extended replacement intervals. Manufacturing gravity centers on China, with Nantong and Shaoxing anchoring global private-label supply, while India and Bangladesh capture emerging fabric curtain assembly. Feedstock exposure spans ethylene derivatives for PEVA, chlorine for legacy vinyl, and polyurethane intermediates for coated textiles. Single-region concentration in Yangtze River Delta manufacturing creates geopolitical and logistics vulnerability for brands lacking alternative sourcing. Distribution runs through Amazon Prime subscription infrastructure, Walmart store-brand networks, and IKEA flat-pack direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shower curtain procurement functions as a regulatory compounder where REACH phthalate restrictions and California Proposition 65 enforcement continuously elevate compliance thresholds and redirect material R&D spend toward certified alternatives.
For Market Incumbents: Deploy backward integration into polyurethane coating operations to capture margin premiums on fabric substrates. Incorporate antimicrobial additive capabilities to meet institutional procurement specifications. Consolidate supply agreements with Nantong manufacturers before emerging regional players secure capacity. Biopolymer development from PLA and starch-based alternatives threatens incumbent petrochemical supply chains. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector, bypassing entrenched big-box retail shelf-space barriers. Target residential renovation segments in Texas and Florida where bathroom fixture upgrade cycles accelerate replacement demand. Pursue digital-native positioning with on-demand manufacturing and collapsed minimum order quantities for custom sizing applications. For Investors and Strategic Acquirers: Private-label program operators are the most active acquirer in this space, consolidating manufacturing-cluster capacity to serve Amazon and Walmart procurement volumes. Five-to-ten year viability hinges on biopolymer transition timing and regulatory front-running capabilities. Monitor ECHA enforcement patterns and MEE wastewater discharge tightening as inflection indicators for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PEVA Capacity Expansion | REACH compliance positioning captures hospitality procurement premiums in Germany and France. |
| Backward Integration into Coatings | In-house polyurethane application secures margin control over fabric substrate value chain. |
| Subscription Channel Launch | Amazon Prime bundling infrastructure captures recurring replacement demand traditional retail loses. |
| Antimicrobial Certification Investment | Institutional procurement through GPOs requires infection-control performance specifications. |
| Flat-Pack Logistics Optimization | IKEA's compressed packaging reduces last-mile costs in dense urban residential markets. |
Research Methodology
Bottom-up hospitality and residential modeling reconciled against top-down Nantong and Shaoxing manufacturing tracking forms the analytical core of this study. Primary interviews with hospitality procurement directors, textile plant managers, big-box retail category buyers, coating R&D leads, and institutional GPO contract managers combined with secondary validation from customs records, EPA enforcement disclosures, ECHA SVHC screening databases, and SEC retail channel filings. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped material flows from ethylene and chlorine derivatives through coating operations to finished curtain distribution. Segmentation dimensions modeled include material chemistry tier, design style positioning, end-user facility type, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted replacement cycle analysis and renovation activity correlation across the projection horizon. Forecast inputs incorporated REACH enforcement trajectory and California Air Resources Board implementation timing.
The model assumes a particular technology adoption path; alternative pathways for biopolymer substrate development would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and petrochemical feedstock availability. Practitioners should monitor ECHA substance restriction proposals and MEE environmental standard tightening for early signals of material substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market