
 Bathroom Sink Market | 2026-2036
Bathroom Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Sink Market Analysis
Vietnam's ceramic manufacturing corridor is reshaping cost structures for mid-range bathroom sink production. Kohler Co. leverages captive porcelain firing capacity across its Asia-Pacific plants to sustain margin control on vessel and undermount lines. TOTO Ltd. anchors its competitive position through ceramic engineering R&D intensity, particularly in hydrophilic glaze technologies that reduce cleaning frequency. Duravit AG differentiates through design-forward wall-mounted collections that command positioning in European boutique hospitality specifications.
A bathroom sink is a fixed plumbing fixture comprising a water-retaining bowl, drain assembly, and overflow channel, typically manufactured through vitreous china firing, cast stone molding, or stainless steel drawing processes, serving as the primary hand-washing and grooming station in residential and commercial washrooms. Porcelain remains the dominant material category by volume, though stone and glass variants capture disproportionate margin pools in luxury residential and hospitality segments where aesthetic differentiation commands price premiums. Wall-mounted and vessel sink formats are gaining specification share in compact urban residential projects where floor-space efficiency drives installation preferences, while undermount configurations maintain steady demand in commercial settings prioritizing countertop hygiene and maintenance access.
The US EPA WaterSense program and California Title 24 building efficiency standards constrain faucet flow rates and basin specifications, compelling manufacturers to engineer integrated sink-faucet systems that maintain user experience within regulatory limits. The EU Ecodesign Directive and REACH chemical restrictions on glaze formulations further shape material choices and cross-border market access for ceramic producers. Stakeholders must monitor evolving state-level plumbing codes and green building certification thresholds that increasingly specify recycled content in stone composite and metal sink products.
Market Dynamics
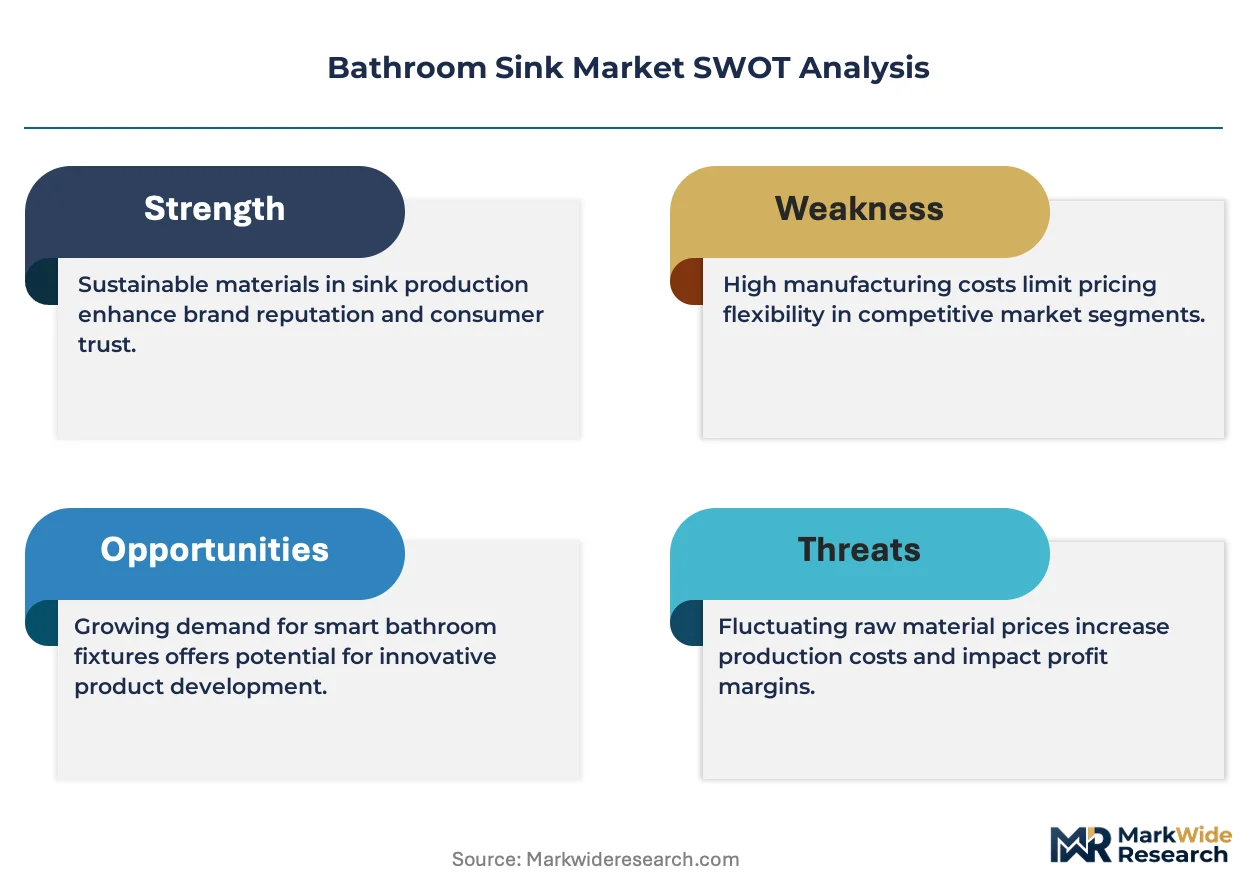
WaterSense certification mandates from the US EPA are compressing faucet flow tolerances and forcing integrated sink-faucet engineering that preserves user experience within regulatory limits. This regulatory pressure cascades through material selection, glaze chemistry, and basin geometry across residential and commercial specifications.
Growth Catalysts
- Hospitality Renovation Cycles:Luxury hotel chains in the United States and Western Europe are compressing replacement timelines for guest bathroom fixtures, creating concentrated demand spikes for premium vessel and undermount configurations.
- REACH Chemical Restrictions:The EU Ecodesign Directive and ECHA restrictions on heavy-metal glaze formulations are accelerating ceramic engineering investment in hydrophilic and self-cleaning surface technologies.
- Urban Residential Density:China's Tier-1 city developers are specifying wall-mounted and compact-format sinks in new condominium projects where floor-space efficiency commands price premiums.
Market Restraints
- Energy Cost Volatility:Natural gas prices for porcelain firing kilns in Vietnam and China's ceramic manufacturing corridors create margin compression for mid-range vitreous china producers.
- Supply Concentration Risk:Kaolin clay deposits and feldspar supply chains concentrate in specific Brazilian and Turkish mining districts, exposing manufacturers to geopolitical and logistics disruptions.
- Technical Limitation:Hydrophilic glaze durability remains inconsistent across high-alkalinity water chemistries, limiting warranty terms in hard-water regions of the American Southwest and Gulf Coast states.
Strategic Opportunities
- Underpenetrated Secondary Cities:India's Tier-2 and Tier-3 urban centers show rising specification of premium sanitaryware as BIS certification standards elevate quality baselines for new residential construction.
- Regulatory Tailwind:California Title 24 building efficiency standards are creating first-mover advantage for manufacturers engineering integrated sink-faucet systems that exceed federal WaterSense thresholds.
- Technology Convergence:Antimicrobial copper-alloy drain assemblies and touchless sensor faucets are converging in healthcare and food-service specifications where hygiene protocols drive replacement cycles.
Industry Challenges
- Ceramic Engineering Talent Scarcity:Specialized glaze chemists and kiln-fire control technicians remain concentrated in legacy European and Japanese manufacturing centers, constraining R&D velocity for new market entrants.
- Certification Timeline Compression:US EPA WaterSense and state-level plumbing code updates require parallel testing protocols that extend product launch schedules by 8-14 months for multi-jurisdiction distribution.
- Legacy Inventory Integration:Distributors and big-box retailers face SKU rationalization friction when introducing low-flow integrated systems alongside existing high-volume faucet inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Sink Market |
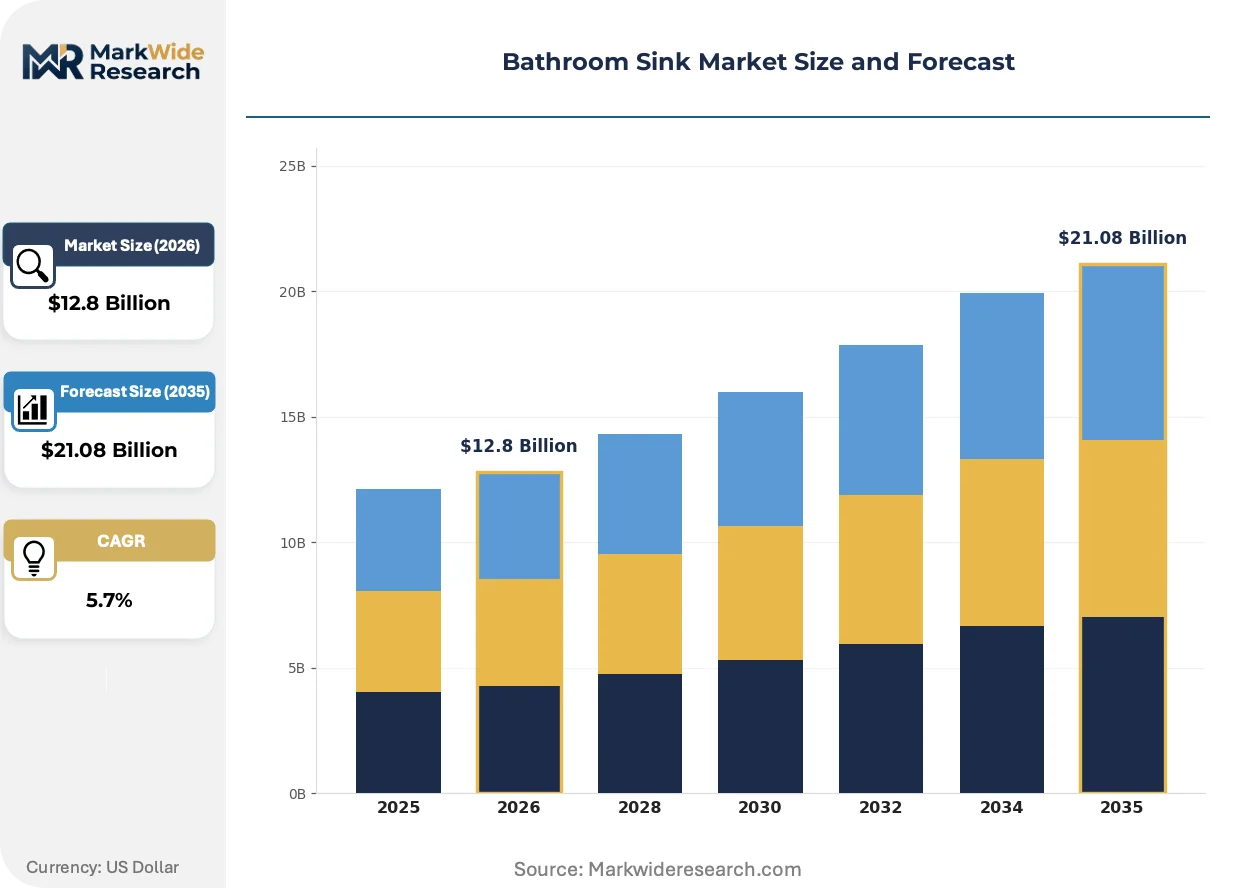
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedestal Sink, Wall-Mounted Sink, Vessel Sink, Undermount Sink Material: Porcelain, Glass, Stone, Stainless Steel Installation Type: Drop-In, Floating, Console, Integrated End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Kohler Co., American Standard, TOTO Ltd., Duravit AG, LIXIL Group Corporation, Roca Sanitario, S.A., Villeroy & Boch AG, Moen Incorporated, CERA Sanitaryware Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Sink Market Emerging Trajectories
Sensor-integrated and IoT-enabled fixtures are digitizing user interaction patterns and maintenance protocols across commercial washroom specifications. This convergence of plumbing hardware and data infrastructure is compressing traditional replacement cycles and reshaping procurement criteria for facility managers.
Touchless infrared sensor technology embedded in faucet bases and soap dispensers is digitizing hand-washing compliance tracking in healthcare, aviation, and food-processing facilities. Hospital systems in the United States are specifying these systems at accelerating rates to satisfy Joint Commission hygiene audits. The technology is digitizing facility management workflows by enabling predictive maintenance alerts and water-usage analytics that reduce operational downtime.
The US EPA WaterSense program and California Title 24 amendments are mandating maximum 1.2 gallons-per-minute flow rates for public lavatory faucets. These constraints force manufacturers to redesign aerator geometries and basin slopes that maintain user satisfaction within tighter hydraulic parameters. Hospitality chains operating across multiple US states are consolidating specifications around dual-certification products that satisfy both federal and California standards through single-SKU procurement.
Facility managers in commercial real estate are consolidating vendor relationships around full-fixture packages that bundle sinks, faucets, drains, and sensor systems under unified warranty terms. This specification consolidation displaces the traditional component-by-component procurement model that dominated institutional purchasing through 2020. The shift is most visible in Class-A office renovations across Manhattan, London, and Singapore where landlord-tenant improvement allowances incentivize premium integrated systems.
Bathroom Sink Market Segmentation
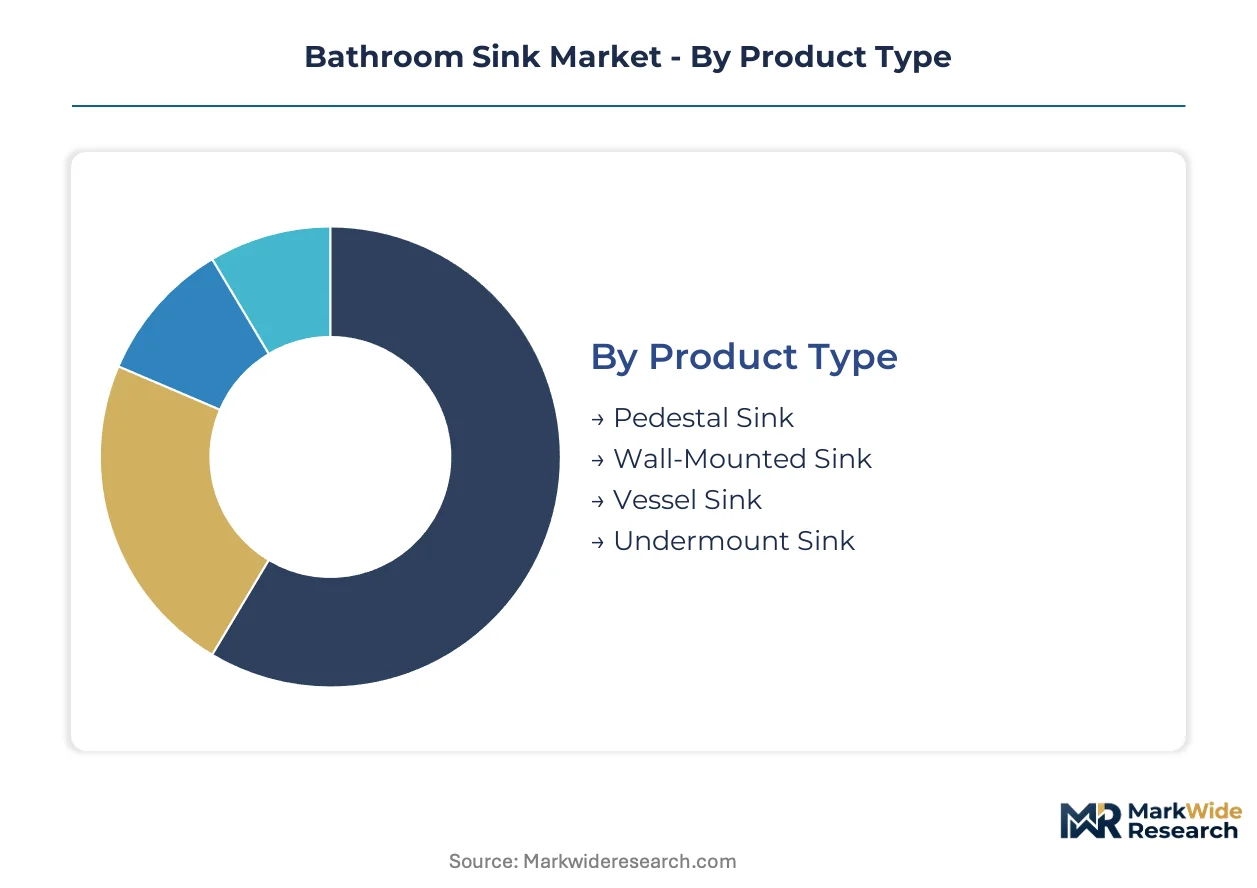
Sink specification diverges sharply across end-use environments, with hospitality procurement prioritizing design differentiation while healthcare and food-service operators emphasize infection control and durability under chemical cleaning protocols. Material selection and installation geometry determine maintenance burden, water efficiency compliance, and renovation flexibility across these distinct demand pools.
Product Type:
Mature formats dominate replacement cycles, though emerging configurations are capturing specification share in space-constrained urban developments.
- Pedestal Sink:Freestanding ceramic column supporting a wall-anchored basin, eliminating cabinet costs and simplifying floor cleaning access. Demand concentrates in budget-conscious residential renovations across the American Southeast and Midwest where plumbing rough-in configurations resist modification.
- Wall-Mounted Sink:Cantilevered basin anchored directly to structural wall framing, maximizing floor area in compact powder rooms and commercial washrooms. China's Tier-1 city developers specify these formats in new condominium projects where square-meter efficiency commands price premiums.
- Vessel Sink:Above-counter basin resting atop vanity surface, enabling artistic material expression in glass, stone, or hand-fired ceramic.
- Undermount Sink:Basin rim sealed beneath countertop substrate, creating seamless surface hygiene and simplified wipe-down maintenance.
Pedestal configurations retain volume leadership in replacement markets; wall-mounted sinks hold the steepest expansion curve.
Material:
Cost tiers separate commodity volume from premium margin capture, with raw material scarcity and firing energy intensity driving stratification.
- Porcelain:Vitreous china fired above 1200°C, yielding non-porous, stain-resistant surfaces with standardized glaze chemistry. Vietnam's ceramic manufacturing corridor has compressed unit economics for mid-range vitreous china, though EPA WaterSense certification requirements add engineering overhead for US-bound production.
- Glass:Tempered or cast glass formed through kiln-slumping or mold-blowing processes, delivering translucent aesthetic effects. Hospitality renovation cycles across luxury hotel chains in Dubai and Miami specify glass vessel basins where Instagram-visible design differentiation supports nightly rate positioning.
- Stone:Carved or composite-cast natural stone including marble, granite, and engineered quartz blends.
- Stainless Steel:Drawn or fabricated alloy basins with brushed, polished, or PVD-coated finishes.
Porcelain commands absolute volume; glass climbs fastest in hospitality specification.
Installation Type:
Application context dictates geometry selection, with maintenance access and countertop integration driving divergence between residential and commercial procurement.
- Drop-In:Self-rimming basin with flange overlapping countertop cutout, enabling rapid retrofit without substrate replacement. Big-box retail distribution channels in the United States concentrate inventory around drop-in configurations for contractor-driven residential renovation.
- Floating:Wall-anchored installation concealing carrier systems within wall cavity, delivering minimalist visual weight. European boutique hospitality specifications in Paris and Berlin favor floating installations where design-forward positioning justifies premium procurement.
- Console:Basin supported by visible metal or wood framework, blending vintage aesthetic with exposed structural expression.
- Integrated:Monolithic countertop-basin cast from solid surface, quartz, or cultured marble.
Drop-In maintains installed-base dominance; Floating gains share fastest in design-specified commercial projects.
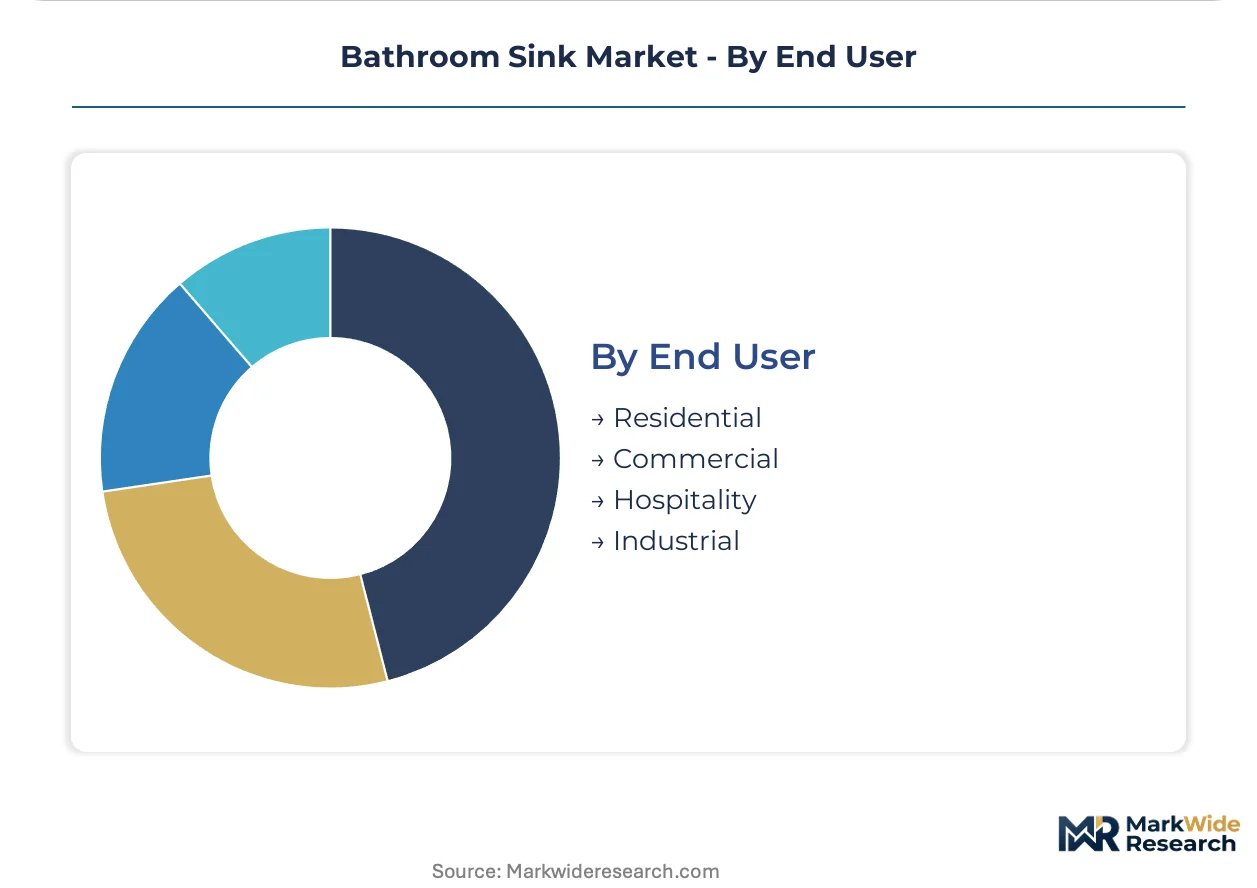
End User:
Customer type determines performance requirements, warranty terms, and replacement cycle compression.
- Residential:Owner-occupied and rental property installations prioritizing cost containment and style longevity. India's Tier-2 urban centers show rising specification of premium sanitaryware as BIS certification standards elevate quality baselines for new construction.
- Commercial:Office, retail, and institutional facilities emphasizing durability under high-traffic use and standardized maintenance protocols. Class-A office renovations across Manhattan and London consolidate vendor relationships around full-fixture packages bundling sinks, faucets, and sensor systems.
- Hospitality:Hotels, resorts, and cruise lines where guest-facing aesthetics drive renovation frequency and brand consistency.
- Industrial:Manufacturing, laboratory, and food-processing environments requiring chemical resistance and heavy-duty construction.
Residential absorbs greatest absolute volume; Hospitality shows the steepest replacement cycle compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors European sanitaryware distribution networks, while Vietnam's Cai Mep-Thi Vai deepwater port complex funnels ceramic exports toward North American and European retail channels.
United States
Luxury hotel renovation cycles in Miami and Manhattan generate concentrated demand spikes for vessel and undermount configurations. The US EPA WaterSense program mandates maximum 1.2 gallons-per-minute flow rates, compressing faucet engineering tolerances. California's Title 24 building efficiency standards exceed federal thresholds, creating first-mover certification advantages for integrated sink-faucet systems.
Germany
European boutique hospitality specifications in Berlin and Paris favor floating wall-mounted installations where design-forward positioning commands premium procurement. The EU Ecodesign Directive and ECHA REACH restrictions on heavy-metal glaze formulations accelerate ceramic engineering investment. Bavaria's industrial clusters host specialized kiln-fire control technician training programs that sustain R&D velocity.
China
Tier-1 city developers in Shanghai and Shenzhen specify wall-mounted and compact-format sinks in new condominium projects where floor-space efficiency drives price premiums. The country's dual carbon goals constrain natural gas firing intensity in ceramic manufacturing corridors. The Yangtze River Delta concentration of vitreous china producers exports mid-range volumes under compressed unit economics.
Vietnam
The ceramic manufacturing corridor from Binh Duong to Dong Nai reshapes cost structures for mid-range bathroom sink production. Natural gas price volatility for porcelain firing kilns creates margin compression for export-oriented vitreous china producers. Ho Chi Minh City's logistics infrastructure connects these plants to trans-Pacific shipping routes serving North American big-box retail distribution.
India
Tier-2 urban centers including Pune and Ahmedabad show rising specification of premium sanitaryware as BIS certification standards elevate quality baselines for new residential construction. The Bureau of Indian Standards mandates stricter glaze durability testing for imported ceramic products. Gujarat's ceramic belt clusters domestic producers serving price-sensitive replacement markets across western states.
Bathroom Sink Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material and firing technology. The vendor base stratifies across three tiers: captive porcelain producers with kiln ownership, design-forward European houses, and Asian contract manufacturers serving private-label retail. Two strategic archetypes dominate competitive positioning: vertically integrated ceramic engineers controlling glaze chemistry R&D, and specification designers capturing hospitality procurement through architect relationships. Capacity expansion in Vietnam's ceramic corridor and strategic partnerships between sensor-technology firms and fixture integrators represent the dominant competitive moves.
Among premium-tier European houses, Duravit AG and Villeroy & Boch AG exemplify design-forward positioning through wall-mounted collections. TOTO Ltd. anchors the ceramic engineering archetype through hydrophilic glaze technology investment. These three companies represent distinct competitive vectors: German design specification, Japanese surface engineering, and integrated system integration for commercial washroom projects.
| Leading Market Players |
|---|
| Kohler Co. |
| American Standard |
| TOTO Ltd. |
| Duravit AG |
| LIXIL Group Corporation |
| Roca Sanitario, S.A. |
| Villeroy & Boch AG |
| Moen Incorporated |
| CERA Sanitaryware Ltd. |
| Others |
Supply Flow & Price Mechanics
Kaolin clay deposit concentration in Brazilian and Turkish mining districts creates single-source vulnerability that widens pricing spreads between premium vitreous china and economy-grade ceramic imports while compressing mid-range margins through input cost volatility. This feedstock dependency forces manufacturers to absorb freight surcharges or pass them through to hospitality and commercial buyers with limited substitution options.
Pricing Analysis
Volume-discount tiering structures separate project-scale hospitality procurement from retail replacement purchases. Three-tier pricing stratifies across premium vessel configurations with hydrophilic glaze certification, standard undermount lines for commercial renovation, and economy pedestal formats for residential retrofit. Price differentiation hinges on WaterSense certification overhead and brand-specified architect relationships. Pricing pressure intensifies in mid-range vitreous china as Vietnam's ceramic corridor floods export channels. Hospitality chains show lowest price sensitivity; budget residential contractors exhibit highest.
Supply Chain Analysis
Upstream feedstock flows concentrate kaolin extraction in Brazil's Minas Gerais belt and feldspar mining in Turkey's Aegean region, with secondary deposits in China's Jiangxi province. Ceramic engineering depends on these inputs for glaze chemistry consistency and firing stability. Natural gas price volatility for kiln operations in Vietnam and China creates margin compression risk. Distribution runs through Ho Chi Minh City's port infrastructure for trans-Pacific routes and Hamburg's container terminals for European wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bathroom sink demand sits in early-cycle expansion as IoT-enabled sensor integration penetrates healthcare and aviation specifications, compressing replacement timelines and expanding addressable spend per fixture installation.
For Market Incumbents: Build captive glaze chemistry R&D moats through hydrophilic surface technology patents that lock hospitality specification relationships. Consolidate kiln-fire control technician training in legacy European and Japanese centers to constrain competitor R&D velocity. Acquire sensor-technology partnerships to defend integrated system bundling against component disaggregation. Address emerging threat from Asian contract manufacturers eroding mid-range share through Vietnam capacity expansion. For New Entrants and Emerging Players: India's Tier-2 urban centers present white-space penetration opportunity as BIS certification elevates quality baselines and premium sanitaryware specification rises. Target wall-mounted compact formats for China's condominium density projects where floor-space efficiency commands design premiums. Pursue private-label distribution through North American big-box retail channels to bypass incumbent architect-specification relationships. Leverage Vietnam contract manufacturing partnerships for cost-competitive vitreous china entry. For Investors and Strategic Acquirers: California Title 24 building efficiency standard tightening reshapes the acquisition landscape toward integrated sink-faucet system engineers with dual-certification capability. Long-term viability favors vertically integrated ceramic producers with kiln ownership and captive raw material sourcing. Target acquisition archetype: mid-scale European design houses with boutique hospitality relationships and underexploited Asian manufacturing partnerships. Monitor WaterSense certification timeline compression as inflection signal for regulatory compliance moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Binh Duong corridor plants capture trans-Pacific export share under compressed unit economics. |
| Backward Integration into Kaolin Sourcing | Turkish and Brazilian mining partnerships reduce glaze chemistry input volatility exposure. |
| Sensor-Technology Partnership | Touchless faucet convergence enables healthcare specification compliance and predictive maintenance revenue. |
| Dual-Certification Product Engineering | WaterSense and Title 24 compliance opens California and federal procurement through single-SKU consolidation. |
| Design-Forward Collection Launch | Wall-mounted floating formats capture European boutique hospitality and Manhattan Class-A office renovation demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ceramic engineering directors, hospitality procurement managers, facility maintenance heads, and big-box retail category buyers; and secondary validation through US EPA WaterSense certification databases, EU ECHA REACH restriction filings, BIS sanitaryware standards documentation, and customs trade flow records. Bottom-up unit shipment estimates triangulated against top-down construction spending and renovation cycle indicators.
Forecast inputs incorporated product type segmentation across pedestal, wall-mounted, vessel, and undermount configurations; material tiers spanning porcelain, glass, stone, and stainless steel; installation geometry including drop-in, floating, console, and integrated formats; and end-use environments from residential through hospitality and industrial. CAGRs derived from regression analysis of historic replacement cycles, regulatory compliance deadline impacts, and urban density trends across the projection horizon. Industry-specific inputs included natural gas firing cost indices and kaolin freight rate volatility.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, luxury hospitality occupancy recovery, or trans-Pacific shipping capacity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and ceramic engineering talent mobility. Cross-checking against national building permit databases and hotel renovation pipeline tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
US Faucet Market