
 Pullout Faucets Market | 2026-2036
Pullout Faucets Market Size, Share, and Industry Trends Forecast 2026-2036
Pullout Faucets Market Insights
Stainless steel is expanding its share in pullout faucet construction as manufacturers seek durability without the volatile cost structure of brass. Moen Incorporated leverages vertical integration to control raw material quality across its supply chain. Kohler Co. anchors its position through captive foundry capacity and proprietary finishing technologies. Grohe AG differentiates via precision-machined ceramic disc cartridges that extend product lifespan under high-frequency use.
A pullout faucet integrates a retractable spray head connected to a flexible hose within a fixed spout body, typically rated for flow rates between 1.5 and 2.2 gallons per minute depending on certification tier. Touchless product variants are gaining share fastest as sensor reliability improves and hygiene sensitivity persists in residential kitchens, though single-handle units still occupy the largest installed base due to simpler installation and lower price points. Deck mounted installation dominates new construction, while wall mounted configurations capture premium renovation segments seeking cleaner counter aesthetics.
EPA WaterSense standards constrain maximum flow rates in the United States, forcing manufacturers to engineer aerator and spray-head geometries that preserve user-perceived pressure. The EU Green Deal and REACH compliance requirements in Europe restrict lead content and mandate recycled material disclosure, raising formulation costs for brass-dependent producers. Stakeholders must monitor how dual regulatory trajectories on water efficiency and material chemistry reshape supplier qualification criteria and regional sourcing strategies.
Market Dynamics
EPA WaterSense flow-rate ceilings are compressing manufacturer margins while forcing aerator redesigns that preserve user-perceived pressure, creating a technical arms race around spray-head geometries and ceramic disc valve precision.
Growth Catalysts
- Touchless sensor integration:Hygiene-sensitive residential buyers are specifying infrared-activated units in kitchen renovations, displacing single-handle configurations in premium housing stock turnover.
- REACH material disclosure mandates:EU Green Deal compliance requirements are accelerating stainless steel substitution for lead-bearing brass alloys across export-oriented production lines.
- Aging-in-place remodeling:United States housing demographics favor accessible-height deck-mounted installations with extended-reach hoses for mobility-limited homeowners.
Market Restraints
- Brass alloy cost volatility:Copper and zinc price swings on London Metal Exchange benchmarks destabilize input cost forecasting for traditional foundry-dependent producers.
- Sensor module supply concentration:Infrared and capacitive touch components concentrate among Taiwanese and South Korean semiconductor packaging houses, exposing lead-time risk.
- Dual certification burden:Simultaneous EPA WaterSense and EU CE marking compliance forces parallel testing tracks that extend product launch timelines.
Strategic Opportunities
- Wall-mounted premium renovation:Cleaner counter aesthetics in high-end United States kitchen redesigns create pull-through demand for concealed-body configurations previously limited to commercial specification.
- Voice-activated convergence:Integration with Amazon Alexa and Google Home ecosystems opens specification channels through smart home contractors and IoT-focused distributors.
- IRA efficiency rebates:Inflation Reduction Act residential energy improvement credits subsidize WaterSense-certified replacement cycles in owner-occupied housing.
Industry Challenges
- Plumber installer skill gap:Touchless sensor calibration and battery-backup configuration require electrical competency beyond traditional pipe-fitting trade training.
- Legacy deck-drilling incompatibility:Wall-mounted retrofit demand confronts existing countertop substrate limitations and structural backing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pullout Faucets Market |
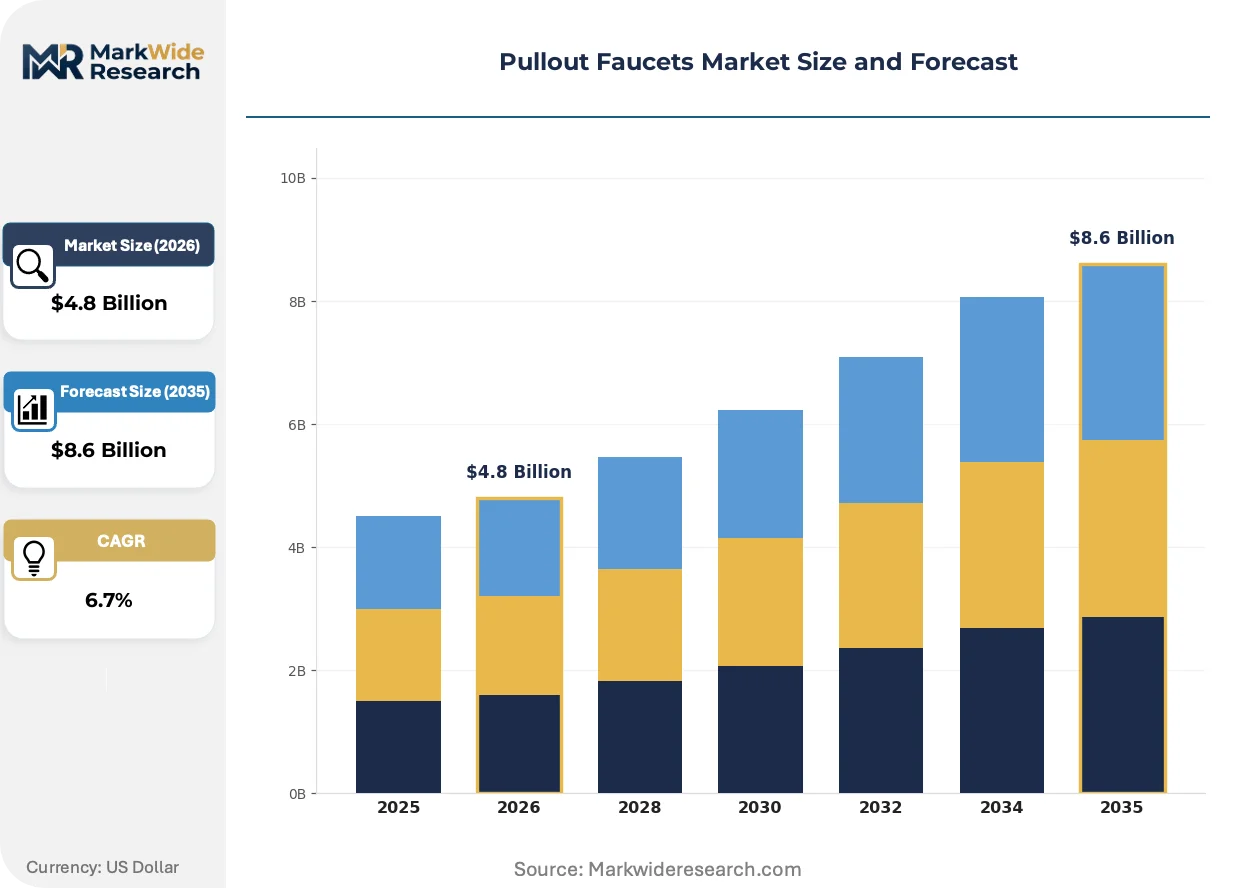
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Handle, Dual-Handle, Touchless, Pull-Down Material: Stainless Steel, Brass, Plastic, Bronze Installation Type: Deck Mounted, Wall Mounted, Freestanding, Under-Mount Design Style: Modern, Traditional, Industrial, Contemporary |
| Companies Covered | Delta Faucet Company, Moen Incorporated, Kohler Co., Grohe AG, Hansgrohe SE, American Standard Brands, Pfister Faucets, Blanco GmbH, TOTO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pullout Faucets Market Trends and Innovations
Sensor reliability improvements and material chemistry constraints are simultaneously elevating electronic content and compressing traditional metalworking margins across pullout faucet portfolios.
Modular spray-head assemblies with field-replaceable aerator cartridges and hose quick-connect fittings are modularizing service economics for residential end-users. Home improvement retailers report accelerating attachment rates for replacement cartridge SKUs, compressing traditional full-faucet replacement cycles and shifting margin capture toward consumable components.
EPA WaterSense certification tiers now differentiate maximum flow-rate allowances between 1.5 and 2.2 gallons per minute, forcing manufacturers to maintain dual aerator geometries within single product families. California Title 20 builds additional state-level stringency that pre-empts federal baselines, requiring SKU proliferation for compliant distribution.
Builder procurement consolidation toward national production home chains is compressing distributor intermediation in new construction channels. Direct specification relationships between Moen, Kohler, and Lennar or D.R. Horton procurement desks bypass traditional wholesale plumbing supply houses, reallocating margin and service obligations upstream to manufacturer captive installation support teams.
Pullout Faucets Market Segmentation
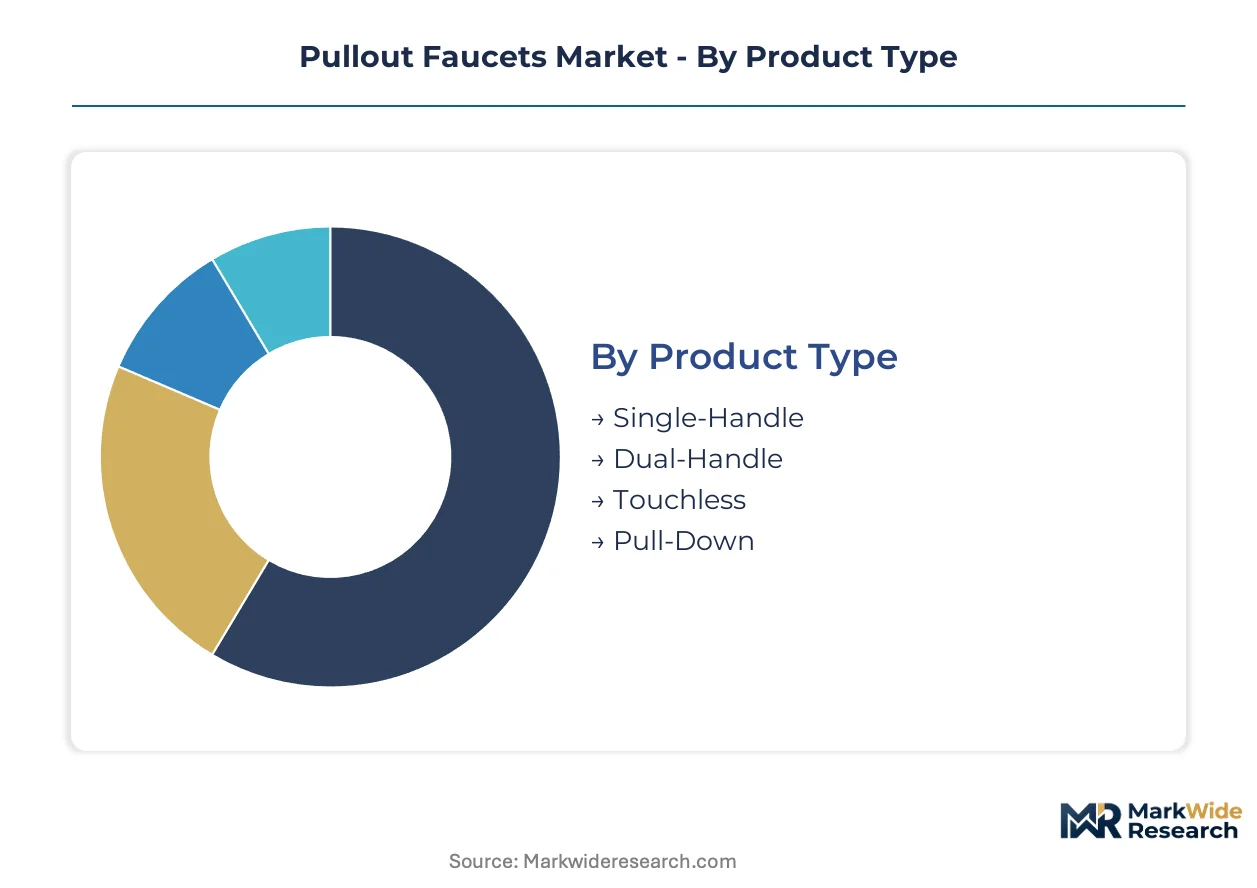
Pullout faucet purchasing decisions cascade through four distinct lenses—product functionality, material durability, mounting constraints, and aesthetic alignment—each filtering which manufacturers capture specification in residential renovation versus new construction channels.
Product Type:
Supply concentration among sensor module packagers in Taiwan and South Korea directly shapes which product variants achieve reliable volume production.
- Single-Handle:Combines temperature and flow control through one lateral motion axis, typically rated for 1.5 to 2.2 gallons per minute under EPA WaterSense tiers. Demand concentrates in United States starter-home replacement cycles where plumber familiarity and lower installed cost override feature sophistication.
- Touchless:Deploys infrared or capacitive sensors for hands-free activation, requiring battery or AC adapters with backup power systems. United States aging-in-place renovations specify these fastest as hygiene sensitivity and accessibility needs reshape kitchen specification in owner-occupied housing.
- Dual-Handle:Separates hot and cold controls for precise temperature mixing, retaining preference in traditional design schemes and regions with legacy plumbing codes.
- Pull-Down:Features a downward-retracting spray head with magnetic or weight-based docking, competing directly with pullout configurations for counter space efficiency.
Today's leader: Single-Handle. Tomorrow's challenger: Touchless.
Material:
Cost tier stratification follows raw material volatility on London Metal Exchange benchmarks, with stainless steel gaining ground as brass alloy pricing destabilizes.
- Stainless Steel:Offers corrosion resistance without lead content concerns, typically 304 or 316 grade for residential applications. REACH compliance mandates across EU member states accelerate substitution away from lead-bearing alloys in export-oriented production.
- Brass:Provides machinability and thermal conductivity for valve bodies, though copper-zinc price swings compress margin predictability for foundry-dependent producers.
- Plastic:Delivers cost efficiency in spray-head housings and aerator components, rarely specified for visible surfaces in premium segments.
- Bronze:Supplies patina aesthetics and marine-grade durability, capturing niche specification in coastal United States markets with salt-air exposure.
Stainless steel climbs fastest as regulatory chemistry constraints displace traditional alloys.
Installation Type:
Application context—new construction versus renovation—determines which mounting configurations achieve specification density.
- Deck Mounted:Secures through pre-drilled sink or countertop substrate, dominating United States production home construction where national builder procurement standardizes around proven configurations.
- Wall Mounted:Requires concealed supply lines and structural backing, capturing premium United States kitchen redesigns seeking cleaner counter planes.
- Freestanding:Anchors to floor or side deck for island configurations without overhead cabinetry, gaining share in open-plan residential layouts.
- Under-Mount:Positions functional hardware below counter surface, reserved for specialized commercial-to-residential conversion aesthetics.
Deck mounted commands volume. Wall mounted captures margin.
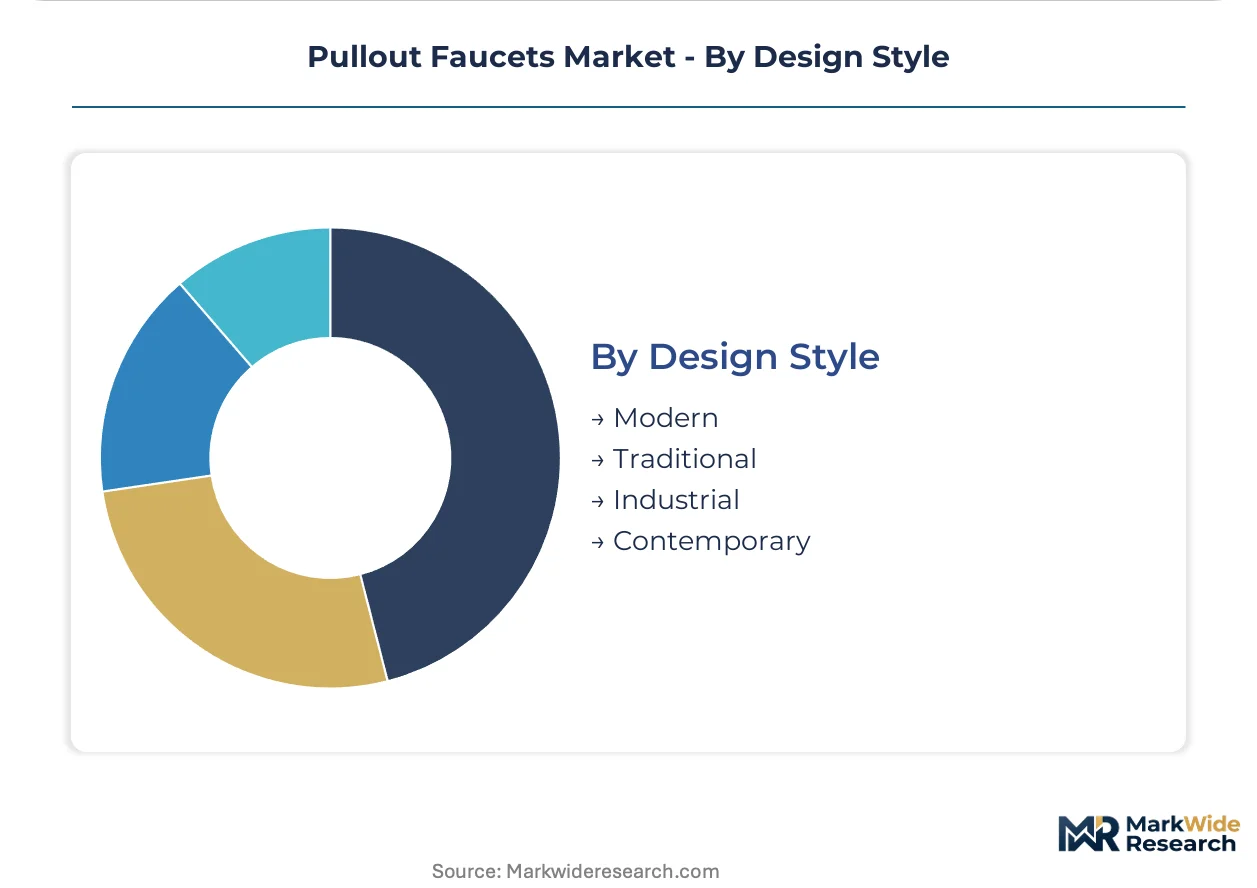
Design Style:
Customer type differentiation—production builder versus custom renovator—maps directly to aesthetic specification, with regional housing stock age influencing preference clusters.
- Modern:Emphasizes geometric minimalism and matte black or brushed nickel finishes, aligning with United States metropolitan infill construction and contemporary kitchen cabinetry.
- Traditional:Features curved spout arches and oil-rubbed bronze or polished chrome, persisting in Northeast and Midwest United States housing stock with pre-war architectural heritage.
- Industrial:Exposes spring-coil hoses and raw metal textures, resonating in loft conversions and adaptive reuse projects across United States urban cores.
- Contemporary:Blends transitional elements between modern and traditional, capturing renovation flexibility where homeowners avoid stark aesthetic commitments.
Modern leads new construction specification. Traditional anchors replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors production capacity for pullout faucet assembly, with Foshan and Kaiping municipal clusters supplying die-cast components to North American and European importers. Regional demand trajectories diverge sharply between mature replacement markets and emerging first-time buyer economies.
United States
Housing stock turnover in Sun Belt metros and aging-in-place renovations in Northeast corridor suburbs drive specification volume. EPA WaterSense flow-rate ceilings compress margins while forcing aerator redesigns that preserve user-perceived pressure. The Chicago-Joliet-Naperville corridor concentrates distribution infrastructure serving national home improvement retail chains.
China
Urban residential kitchen upgrades in tier-two cities accelerate touchless adoption as middle-class hygiene sensitivity rises. GB standards on water efficiency and lead content tighten formulation requirements for export-oriented manufacturers. The Yangtze River Delta manufacturing belt around Ningbo and Wenzhou specializes in stainless steel precision casting for premium export lines.
Germany
REACH compliance mandates and EU Green Deal material disclosure requirements accelerate stainless steel substitution for traditional brass alloys. Precision machining competencies in the Black Forest region supply ceramic disc valve cartridges to pan-European faucet assemblers. Berlin-Brandenburg renovation activity favors wall-mounted configurations in historic building stock conversions.
Japan
Compact residential kitchen dimensions in Tokyo-Osaka megacities favor space-efficient pullout geometries over bulkier pull-down alternatives. METI energy efficiency labeling programs extend to water-consuming fixtures, creating tiered certification premiums. Nagoya-based industrial clusters integrate sensor module sourcing from domestic electronics suppliers for touchless product lines.
India
Urban middle-class housing construction in Mumbai and Bangalore metropolitan regions introduces pullout configurations to first-time premium kitchen buyers. BIS plumbing fixture standards remain less stringent than EPA or EU benchmarks, permitting broader flow-rate product ranges. Gujarat-based brass foundry capacity serves both domestic assembly and export markets across South Asia and Middle East.
Pullout Faucets Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers add stainless steel casting lines to reduce brass alloy exposure. The vendor base stratifies into three tiers: multinational plumbing fixture conglomerates with captive foundry capacity, mid-scale specialists in sensor-integrated electronic faucets, and regional fabricators serving price-sensitive replacement demand. Strategic archetypes include vertically integrated material controllers, technology licensors from semiconductor-adjacent industries, and private-label contractors for home improvement retail chains. M&A activity concentrates on sensor module suppliers and regional distribution assets.
Within the multinational tier, Moen Incorporated, Kohler Co., and Grohe AG exemplify divergent competitive positions. Moen leverages backward integration into raw material quality control across its supply chain. Kohler anchors its market presence through captive foundry capacity and proprietary finishing technologies. Grohe occupies a precision-engineering position via ceramic disc cartridge specialization for high-frequency residential use. These three entities collectively represent the dominant competitive anchors shaping technology licensing terms and distribution access for mid-tier challengers.
| Leading Market Players |
|---|
| Delta Faucet Company |
| Moen Incorporated |
| Kohler Co. |
| Grohe AG |
| Hansgrohe SE |
| American Standard Brands |
| Pfister Faucets |
| Blanco GmbH |
| TOTO Ltd. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into raw material quality control anchors both supply security and pricing power for leading manufacturers navigating volatile brass alloy markets. Moen Incorporated and Kohler Co. leverage captive foundry capacity to buffer London Metal Exchange copper-zinc swings while commanding premium positioning against assembler-dependent competitors.
Pricing Analysis
Input-cost pass-through from copper and zinc benchmarks destabilizes margin forecasting for brass-dependent producers while stainless steel alternatives gain cost predictability. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA WaterSense certification tier and sensor integration complexity. Pricing pressure stems from national builder procurement consolidation bypassing traditional wholesale intermediation. Production home chains exhibit highest price sensitivity; custom renovators absorb premium for wall-mounted configurations and voice-activated convergence.
Supply Chain Analysis
Domestic-content mandates under EPA WaterSense and California Title 20 pre-emption reshape sourcing toward North American assembly for compliant SKUs. Component concentration centers on Guangdong Province die-casting clusters, Taiwanese semiconductor packaging houses for sensor modules, and German Black Forest precision machining for ceramic disc cartridges. Raw material dependencies rest on copper-zinc alloys, 304/316 grade stainless steel, and infrared sensor electronics. Single-source vulnerability concentrates in Taiwanese and South Korean sensor module suppliers. Distribution runs through national home improvement retail chains and direct specification relationships with production builder procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pullout faucets market functions as a regulatory compounder where EPA WaterSense flow-rate ceilings and EU REACH material mandates continuously reshape product qualification requirements and replacement demand cycles.
For Market Incumbents: Lock in sensor module supply agreements with Taiwanese and South Korean packaging houses before capacity constraints harden. Deepen captive stainless steel casting investments to reduce brass alloy exposure while positioning for REACH compliance acceleration. Defend specification relationships with Lennar and D.R. Horton procurement desks through dedicated installation support teams. For New Entrants and Emerging Players: Enter via voice-activated convergence partnerships with Amazon Alexa and Google Home ecosystems, targeting smart home contractor channels underserved by traditional plumbing fixture marketing. White-space concentrates in wall-mounted premium renovation segments where cleaner counter aesthetics command margin premiums. Pursue private-label contracts with home improvement retail chains seeking modular spray-head consumable SKUs. For Investors and Strategic Acquirers: Roll-up economics work for regional sensor-integrated specialists because certification burden and dual-testing tracks favor scaled compliance infrastructure over fragmented assembler operations. Long-term viability hinges on regulatory trajectory rather than cyclical housing demand. Target acquisition archetype: mid-scale electronic faucet specialists with EPA WaterSense pre-approval and established IoT distributor relationships. Signal to watch: California Title 20 stringency spreading to additional state-level pre-emption.| Strategic Initiative | Industry Significance |
|---|---|
| Stainless Steel Casting Capacity Expansion | Reduces brass alloy cost volatility exposure while satisfying EU REACH lead-content restrictions. |
| Sensor Module Supply Agreement | Secures infrared component allocation from Taiwanese packaging houses facing lead-time risk. |
| Voice-Activated Platform Integration | Opens specification channels through Amazon Alexa and Google Home smart home contractor networks. |
| Wall-Mounted Product Line Development | Captures premium renovation demand for concealed-body configurations in high-end kitchen redesigns. |
| Replacement Cartridge SKU Proliferation | Shifts margin capture toward consumable components as home improvement retailers report accelerating attachment rates. |
Research Methodology
Multiple input streams — structured interviews with plumbing fixture procurement managers, sensor module supplier technical directors, and home improvement retail category buyers — were reconciled against customs records, EPA WaterSense certification databases, and SEC 10-K filings from publicly traded parent entities. Secondary validation drew from London Metal Exchange price benchmarks, housing start permits from metropolitan statistical areas, and EU ECHA REACH substance restriction updates. Bottom-up SKU-level volume estimates and top-down construction expenditure allocations were triangulated to constrain forecast variance.
Cross-referencing historical replacement cycle patterns against panel input from national builder procurement desks and distributor inventory managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type functionality, material chemistry grade, installation configuration, and design style alignment with regional housing stock age. CAGRs were derived from housing turnover velocity, regulatory compliance deadlines, and technology substitution curves for touchless sensor reliability improvements. Industry-specific inputs incorporated EPA WaterSense tier adoption rates and IRA efficiency rebate utilization patterns.
The model holds under stable regulatory enforcement intensity and continued housing stock turnover velocity; deviation in interest rate sensitivity for renovation financing or sensor module supply disruption would shift replacement cycle timing and product mix assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market