
 Germany Bathroom Furniture Market | 2026-2036
Germany Bathroom Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Bathroom Furniture Market Foresight
Asset-light leasing models for bathroom fixture packages is narrowing the capital barrier for mid-tier retailers and regional developers. Duravit AG leverages its captive ceramics production to sustain margin control across integrated vanity lines. KEUCO GmbH & Co. KG anchors premium positioning through specialized hospital and hotel channel relationships. Burgbad GmbH dominates modular cabinet systems with manufacturing scale that competes on delivery speed for large residential projects.
Germany bathroom furniture encompasses fixed and movable storage, washing, and grooming installations engineered for moisture resistance, typically employing water-repellent MDF cores, laminated surfaces, and corrosion-resistant hardware rated for sustained humidity exposure above 80%. These products organize residential and commercial washroom spaces while supporting plumbing integration and hygiene maintenance. Vanities lead volume throughput as the central functional and aesthetic anchor in residential renovations, while shelving units capture expanding demand in compact urban bathrooms where floor space constraints favor vertical storage. MDF material grades command the largest share of unit economics due to cost-efficient formability, though certified solid wood segments extract premium pricing from sustainability-driven consumers in specialty store channels.
KBA and CE marking frameworks govern structural stability and electrical safety for mirrored cabinets with integrated lighting, while REACH restricts formaldehyde emissions from composite board substrates used in mass-market production. The EU Green Deal's embodied carbon reporting requirements through CSRD-aligned supply chain disclosures are reshaping procurement criteria for hotel and wellness center developers. Stakeholders must monitor how Germany's building energy efficiency regulations cascade into bathroom renovation mandates that could accelerate replacement timelines beyond organic wear cycles.
Market Dynamics
The EU Green Deal's embodied carbon reporting through CSRD-aligned disclosures is forcing German manufacturers to restructure procurement around certified wood sourcing and low-emission MDF production, compressing margins for non-compliant suppliers.
Growth Catalysts
- Residential renovation mandates:Building energy efficiency regulations in Bavaria and North Rhine-Westphalia are accelerating replacement cycles for vanities and cabinets beyond organic wear timelines.
- REACH formaldehyde restrictions:Stricter emission limits on composite board substrates are differentiating compliant German producers from lower-standard imports, creating procurement preference in hotel and wellness center development.
- Metropolitan housing stock modernization:Housing clusters around Munich, Hamburg, and Berlin are outpacing national averages for bathroom refurbishment, concentrating demand volume in premium moisture-resistant fixture categories.
Market Restraints
- Certified timber input cost volatility:FSC and PEFC-certified wood sourcing carries 15-25% premiums over conventional alternatives, squeezing unit economics for mid-market cabinet lines.
- Supply concentration in captive ceramics:Integrated vanity production depends on in-house or contracted ceramic basin supply, with limited third-party alternatives creating bottleneck risk for non-vertically integrated assemblers.
- Technical limitation in moisture-rated hardware:Corrosion-resistant hinge and slide mechanisms rated for sustained 80%+ humidity exposure remain concentrated among specialized Austrian and Italian component suppliers.
Strategic Opportunities
- Asset-light leasing models:Fixture package leasing for regional developers and mid-tier retailers narrows capital barriers and creates recurring revenue streams in project-based segments.
- CSRD-aligned supply chain services:Embodied carbon auditing and certified material documentation for hotel developers represents adjacent service revenue beyond product sales.
- Vertical storage systems:Compact urban bathrooms in Berlin and Hamburg favor wall-mounted shelving and mirrored cabinets over floor-standing vanities, opening modular product architectures.
Industry Challenges
- Cross-functional certification timelines:KBA structural stability approval for mirrored cabinets with integrated lighting extends product development cycles by 4-6 months.
- CE marking complexity:Electrical safety validation for LED-integrated storage units requires coordination across multiple notified bodies, fragmenting compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Bathroom Furniture Market |
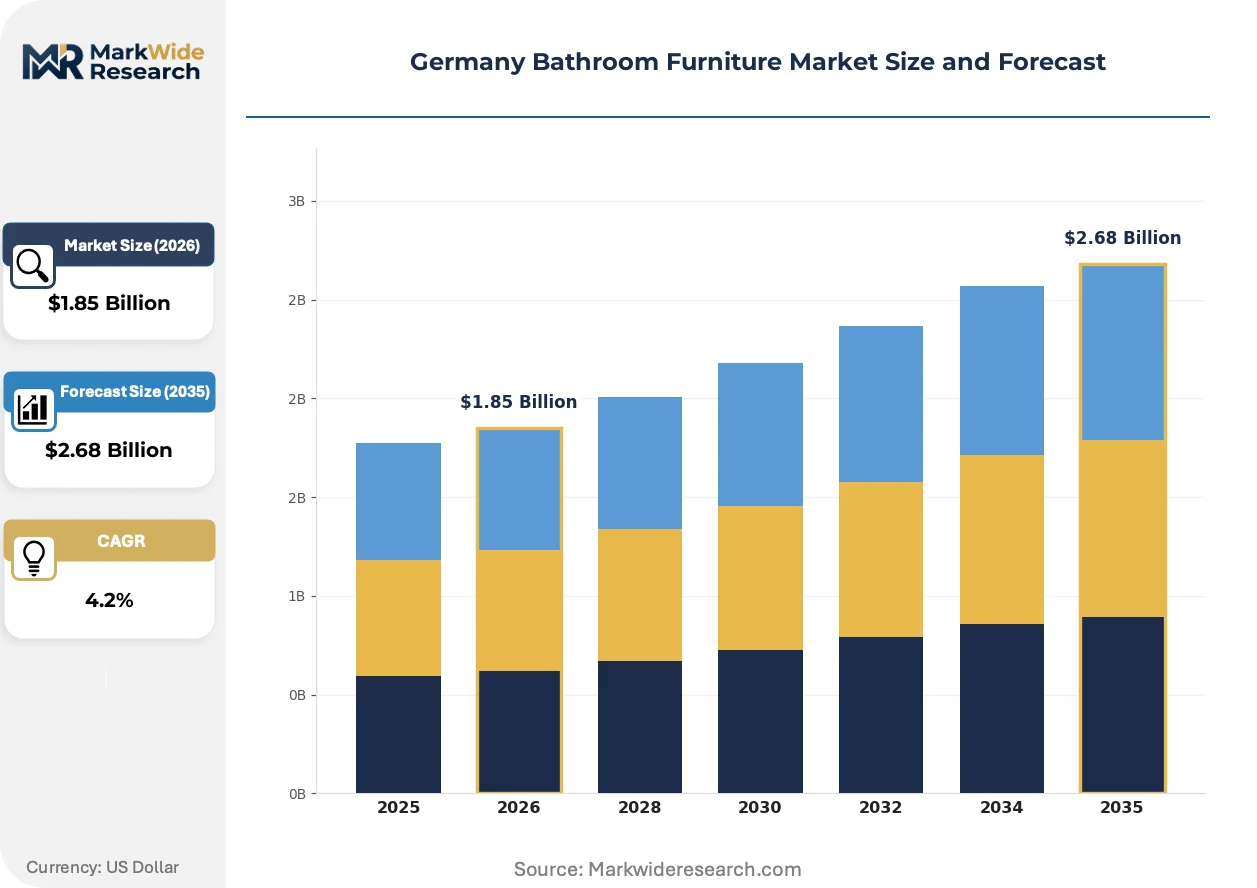
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanities, Cabinets, Mirrors, Shelving Units, Laundry Hampers Material: Wood, MDF, Metal, Glass, Plastic, Stone Application: Residential Homes, Hotels, Wellness Centers, Office Restrooms Distribution Channel: Specialty Stores, Online Retailers, Home Improvement Centers, Direct Sales |
| Companies Covered | IKEA, Hansgrohe SE, Duravit AG, KEUCO GmbH & Co. KG, Artiqua GmbH, Villeroy & Boch AG, Geberit AG, Alape GmbH, Burgbad GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Bathroom Furniture Market Shifts & Advancements
Digital specification tools and material traceability platforms are compressing the traditional architect-to-manufacturer communication loop, while regulatory pressure on embodied carbon is reshaping how German suppliers document and verify supply chain inputs.
Water-repellent MDF core technology is migrating from standard laminated surfaces toward engineered stone and ceramic composite facings. Premium residential developers in Stuttgart and Frankfurt are specifying these hybrid constructions for high-humidity wellness applications. This migration from conventional laminates is compressing the price gap between mass-market and specialty-grade vanity systems.
CSRD supply chain disclosure requirements are mandating granular carbon accounting from tier-three timber suppliers. German bathroom furniture manufacturers must now document harvest-to-mill emissions for every MDF batch. Hotel and commercial developers are prioritizing suppliers with pre-audited certification packages, shifting procurement criteria from price-per-unit to verified lifecycle metrics.
Architects and interior designers are consolidating specification authority through centralized procurement platforms. Regional developers in North Rhine-Westphalia are bypassing traditional wholesale distributors for direct manufacturer relationships. This channel compression is most visible in large residential projects where delivery speed and batch customization outweigh distributor inventory convenience.
Germany Bathroom Furniture Market Segmentation
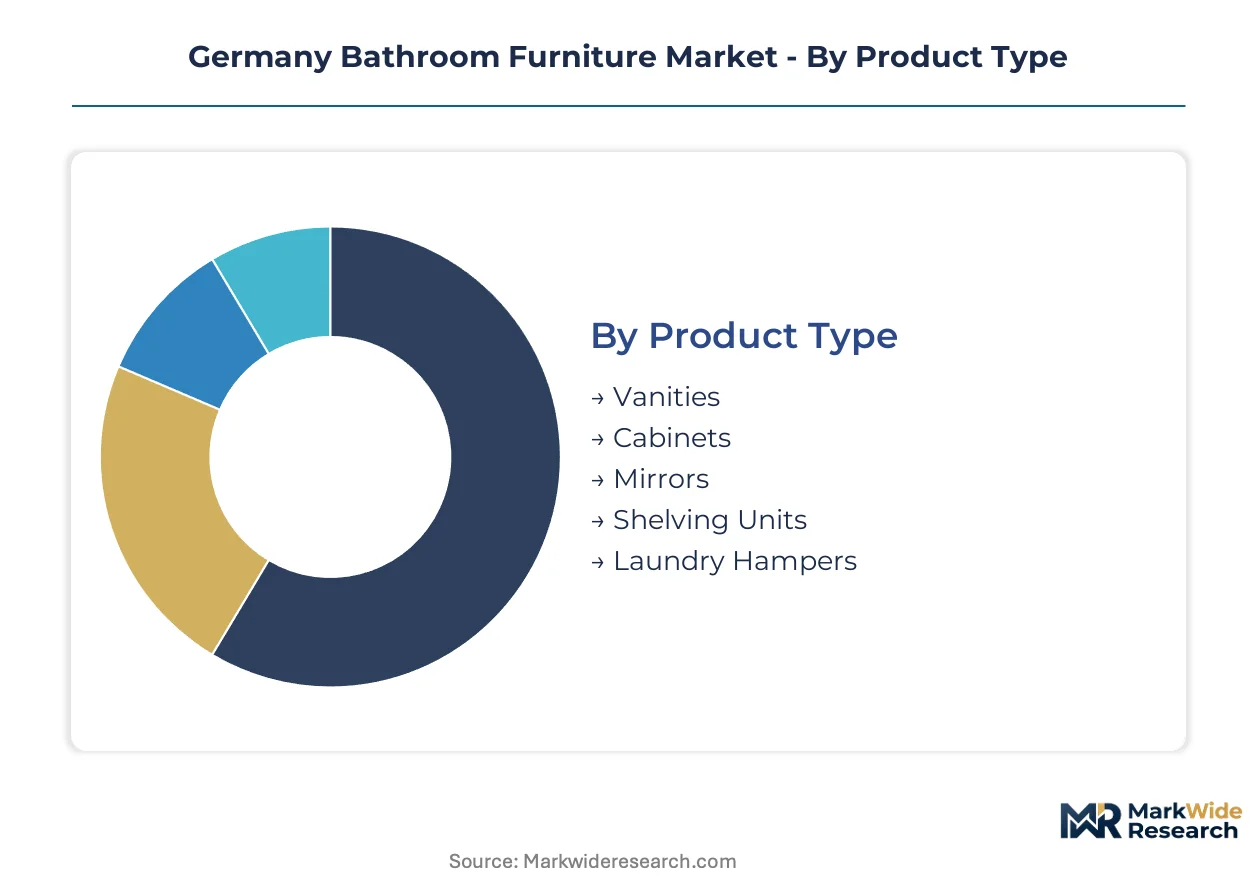
Segmentation in Germany bathroom furniture reveals how moisture resistance requirements, embodied carbon regulations, and metropolitan renovation patterns concentrate demand across distinct product configurations. Each dimension exposes different margin structures and compliance burdens for manufacturers serving Bavarian residential developers versus Hamburg hotel operators.
Product Type:
After-sales service intensity varies sharply across fixture categories, with integrated electrical components in mirrored cabinets demanding specialized technician networks that vanity suppliers rarely maintain.
- Vanities:Central functional anchors in residential renovations combine water-repellent MDF cores with ceramic or engineered stone basin integration. Demand clusters in Munich and Berlin metropolitan housing stock modernization where replacement cycles accelerate beyond organic wear timelines.
- Mirrors:LED-integrated mirrored cabinets require KBA structural stability approval and CE electrical safety validation, extending development cycles by 4-6 months. Wellness centers in Stuttgart and Frankfurt specify these for high-humidity applications where corrosion-resistant hardware rated for sustained 80%+ humidity exposure is mandatory.
- Cabinets:Modular systems dominate large residential projects in North Rhine-Westphalia where delivery speed and batch customization outweigh distributor inventory convenience.
- Shelving Units:Wall-mounted vertical storage captures expanding demand in compact urban bathrooms across Hamburg and Berlin where floor space constraints favor space-efficient configurations.
- Laundry Hampers:Moisture-resistant enclosures with ventilation engineering serve wellness center and hotel channel requirements in Bavaria.
By volume, Vanities leads. By growth pace, Shelving Units is expanding most quickly.
Material:
Cost tier stratification separates certified sustainable inputs from conventional alternatives, with FSC and PEFC-certified wood commanding 15-25% premiums that squeeze mid-market cabinet economics.
- MDF:Water-repellent core technology dominates unit economics through cost-efficient formability for laminated surfaces. REACH formaldehyde emission restrictions differentiate compliant German producers from lower-standard imports, creating procurement preference in hotel and wellness center development.
- Wood:Certified solid wood segments extract premium pricing from sustainability-driven consumers in specialty store channels. CSRD-aligned supply chain disclosures mandate granular carbon accounting from tier-three timber suppliers, forcing harvest-to-mill documentation for every batch.
- Metal:Corrosion-resistant hardware components concentrate among specialized Austrian and Italian suppliers, creating bottleneck risk for non-vertically integrated assemblers.
- Glass:Tempered and frosted variants serve premium aesthetic specifications in Frankfurt and Stuttgart residential developments.
- Plastic:Polymer composites address cost-sensitive segments in mass-market distribution through Hamburg and Berlin home improvement centers.
- Stone:Engineered stone facings migrate into hybrid constructions for high-humidity wellness applications, compressing the price gap between mass-market and specialty-grade systems.
By revenue contribution, MDF leads. By margin expansion, Wood is climbing the fastest.
Application:
Customer type determines specification authority concentration, with architects and interior designers consolidating control through centralized procurement platforms that bypass traditional wholesale distributors.
- Residential Homes:Renovation mandates under building energy efficiency regulations in Bavaria and North Rhine-Westphalia accelerate replacement cycles for vanities and cabinets. Metropolitan clusters around Munich, Hamburg, and Berlin outpace national averages for bathroom refurbishment.
- Hotels:Commercial developers prioritize suppliers with pre-audited CSRD certification packages, shifting procurement criteria from price-per-unit to verified lifecycle metrics. Embodied carbon auditing represents adjacent service revenue beyond product sales.
- Wellness Centers:High-humidity specifications demand corrosion-resistant hinge and slide mechanisms with sustained performance above 80% humidity exposure.
- Office Restrooms:Volume-driven specifications through facility management procurement favor standardized modular configurations with rapid delivery timelines.
By project volume, Residential Homes leads. By specification complexity, Hotels is gaining share fastest.
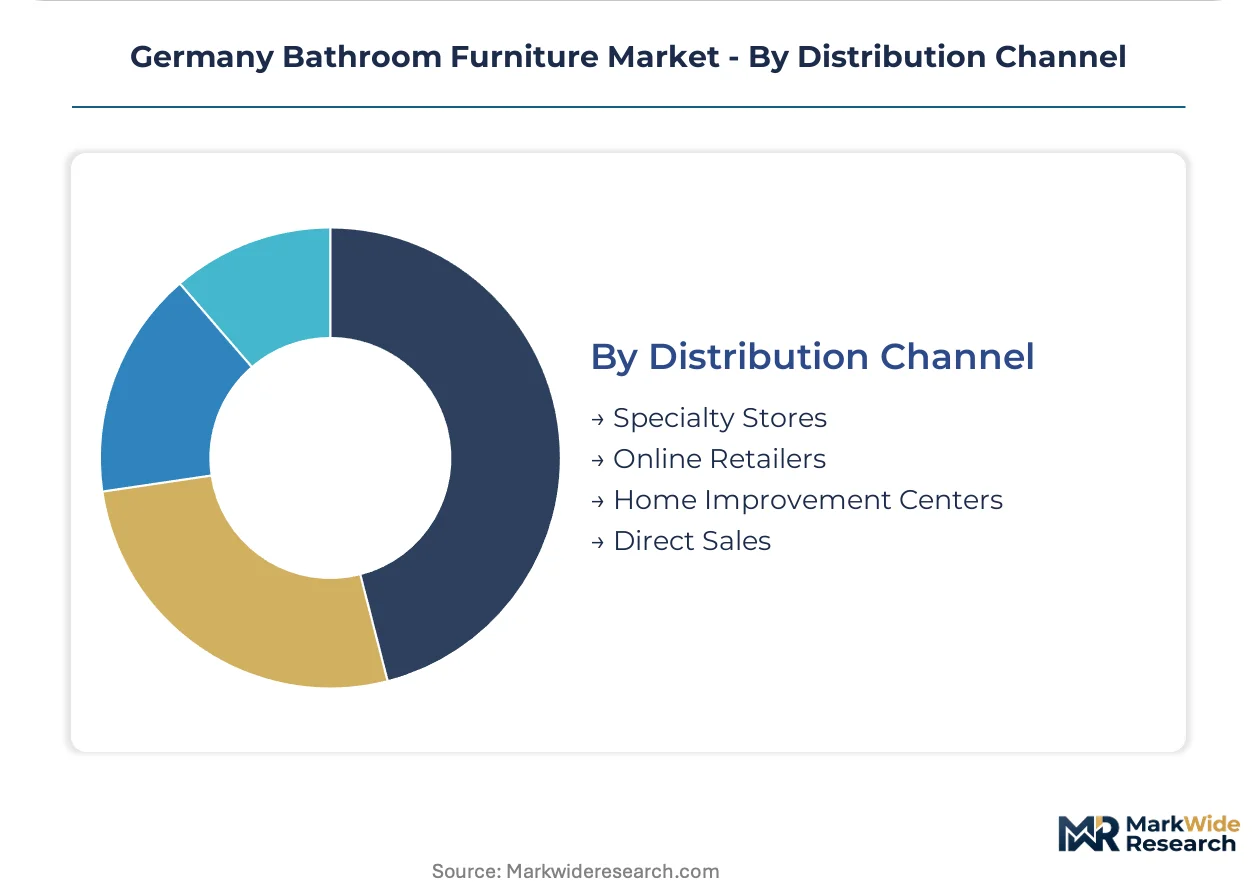
Distribution Channel:
Supply concentration shapes channel power, with regional developers in North Rhine-Westphalia establishing direct manufacturer relationships where delivery speed and customization outweigh distributor inventory convenience.
- Specialty Stores:Sustainability-driven consumers seeking certified solid wood segments drive premium positioning through consultative sales environments in Munich and Stuttgart.
- Online Retailers:Digital specification tools compress the traditional architect-to-manufacturer communication loop, enabling batch customization for project-based segments.
- Home Improvement Centers:Mass-market MDF and plastic-composite lines serve price-sensitive residential renovation in Berlin and Hamburg metropolitan areas.
- Direct Sales:Large residential projects and hotel developers bypass intermediaries for integrated vanity lines with captive ceramics production and documented supply chain emissions.
By transaction volume, Home Improvement Centers leads. By margin profile, Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embodied carbon reporting requirements through CSRD-aligned disclosures are reshaping procurement criteria across German states, accelerating bathroom renovation mandates in jurisdictions with stricter building energy efficiency regulations.
Bavaria
Residential renovation activity in Munich and surrounding metropolitan clusters is accelerating replacement cycles for vanities and cabinets beyond organic wear timelines. The state's building energy efficiency regulations mandate thermal envelope upgrades that cascade into bathroom refurbishment requirements. Wellness center developers in the Alpine foothills prioritize suppliers with pre-audited CSRD certification packages.
North Rhine-Westphalia
Housing stock modernization in Cologne-Düsseldorf corridor concentrates demand volume for modular cabinet systems where delivery speed outweighs distributor inventory convenience. REACH formaldehyde emission restrictions on composite board substrates differentiate compliant regional producers from lower-standard imports. Regional developers are establishing direct manufacturer relationships, bypassing traditional wholesale distributors for large residential projects.
Baden-Württemberg
Stuttgart's premium residential developers specify engineered stone and ceramic composite facings for high-humidity wellness applications, compressing the price gap between mass-market and specialty-grade vanity systems. KBA structural stability approval requirements for mirrored cabinets with integrated lighting extend product development cycles. Specialty store channels in the region extract premium pricing from sustainability-driven consumers seeking certified solid wood segments.
Berlin-Brandenburg
Compact urban bathrooms across Berlin favor wall-mounted shelving and mirrored cabinets over floor-standing vanities, opening modular product architectures for vertical storage systems. The metropolitan housing stock modernization pace outstrips national averages for bathroom refurbishment. Digital specification tools are compressing the traditional architect-to-manufacturer communication loop in this cluster.
Hamburg
Floor space constraints in Hamburg's dense urban core drive expanding demand for space-efficient vertical storage configurations. Home improvement centers in the metropolitan area serve price-sensitive residential renovation with mass-market MDF and plastic-composite lines. Corrosion-resistant hinge and slide mechanisms rated for sustained humidity exposure remain concentrated among specialized Austrian and Italian component suppliers serving this market.
Germany Bathroom Furniture Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification authority in project-based segments. The vendor base clusters around three strategic archetypes: vertically integrated ceramics producers, modular cabinet specialists, and premium fixture developers. Consolidation pressure is intensifying as CSRD-aligned supply chain disclosure requirements favor scale players with pre-audited certification infrastructure. Competitive moves center on backward integration into captive ceramics production and direct-to-developer channel compression.
Within the integrated-manufacturing tier, Duravit AG and Villeroy & Boch AG exemplify archetypes combining captive ceramics production with vanity line integration. KEUCO GmbH & Co. KG occupies a position anchoring premium positioning through specialized channel relationships. Among modular-system specialists, Burgbad GmbH represents scale-driven manufacturing competing on delivery speed for large residential projects.
| Leading Market Players |
|---|
| IKEA |
| Hansgrohe SE |
| Duravit AG |
| KEUCO GmbH & Co. KG |
| Artiqua GmbH |
| Villeroy & Boch AG |
| Geberit AG |
| Alape GmbH |
| Burgbad GmbH |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility feeds directly into landed cost spreads for Austrian and Italian corrosion-resistant hardware, amplifying price differentiation between vertically integrated vanity producers and modular cabinet assemblers dependent on third-party component sourcing.
Pricing Analysis
Certification level under REACH and KBA frameworks creates the primary spread between mass-market MDF lines and premium solid wood segments. Three-tier pricing structure across premium, standard, and economy levels reflects FSC/PEFC-certified timber premiums versus conventional alternatives. Cost compression in mid-market cabinet lines is intensifying because CSRD-aligned supply chain documentation requirements add audit overhead without commensurate price recovery. Mass-market residential renovators through Berlin and Hamburg home improvement centers exhibit highest price sensitivity, while hotel developers prioritizing pre-audited certification packages accept premium positioning.
Supply Chain Analysis
Tariff exposure between Germany and Chinese MDF substrate suppliers dominates input cost planning for non-vertically integrated assemblers. Manufacturing gravity centers on Germany, Austria, and Italy for moisture-rated hardware and ceramic basin integration. Raw material dependencies rest on FSC-certified timber harvests from Nordic and Baltic sources, water-repellent MDF cores from Central European mills, and corrosion-resistant hinge mechanisms from specialized Alpine component suppliers. Single-source vulnerability concentrates in captive ceramics production for integrated vanity lines. Distribution runs through direct manufacturer relationships for large residential projects and hotel developers, bypassing traditional wholesale channels where delivery speed and batch customization outweigh inventory convenience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among architects and interior designers leveraging centralized procurement platforms, fragmenting traditional distributor influence and compressing margin capture for non-integrated suppliers.
For Market Incumbents: Insulate margin position through backward integration into captive ceramics production and CSRD-aligned supply chain auditing services that create switching costs with hotel developers. The threat of asset-light leasing models from regional competitors erodes capital barrier advantages. Certification investment in tier-three timber traceability represents the critical defensive lever. For New Entrants and Emerging Players: Modular vertical storage systems for compact Berlin and Hamburg urban bathrooms represent the most penetrable entry point, exploiting floor space constraints that favor wall-mounted configurations over established floor-standing vanity incumbents. CSRD documentation services for mid-tier regional developers offer adjacent revenue with lower capital requirements than manufacturing entry. Direct digital specification tools enable batch customization without distributor infrastructure. For Investors and Strategic Acquirers: Pre-audited CSRD certification infrastructure specialists with established tier-three timber traceability systems command scarcity premiums as disclosure mandates expand. Long-term viability hinges on regulatory enforcement trajectories across the EU Green Deal implementation window. The signal to watch is building energy efficiency regulation cascade into mandatory bathroom renovation timelines beyond organic replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Aligned Supply Chain Certification | Pre-audited carbon documentation creates procurement preference with Stuttgart and Frankfurt hotel developers. |
| Backward Integration into Captive Ceramics | In-house basin production insulates margin control against third-party supply bottlenecks for integrated vanity lines. |
| Asset-Light Fixture Leasing Models | Recurring revenue streams narrow capital barriers for mid-tier retailers serving North Rhine-Westphalia residential projects. |
| Modular Vertical Storage Expansion | Wall-mounted systems capture Berlin-Brandenburg demand where floor space constraints favor space-efficient configurations. |
| Direct-to-Developer Digital Platforms | Channel compression bypasses wholesale distributors where delivery speed outweighs inventory convenience. |
Research Methodology
The analysis maps vanity systems, mirrored cabinets, modular storage, and vertical shelving configurations, each validated through procurement directors at hotel developers, residential project architects, specialty store category managers, and ceramic basin production engineers. Primary fieldwork combined structured interviews with secondary validation against EU Green Deal implementation timelines, REACH formaldehyde emission databases, KBA structural approval registries, and Bavarian building energy efficiency regulation filings. Bottom-up project pipeline assessment and top-down housing stock modernization trajectories were triangulated for volume estimation.
Assumptions held fixed include EU Green Deal enforcement trajectories and REACH emission limit progression, while variable inputs encompassed metropolitan renovation pace differentials and certified timber premium volatility. Segmentation modeling incorporated product type, material grade tier, application by customer type, and distribution channel structure across the projection horizon. CAGRs derived from regression analysis against housing stock age profiles and regulatory mandate cascade timelines, with CSRD disclosure adoption curves and wellness center development permits serving as industry-specific forecast inputs.
Practitioners should monitor building energy efficiency regulation expansion into additional German states and REACH formaldehyde limit tightening proposals for early signals of demand acceleration or supply restructuring. Forecasts reflect these assumptions without guarantee of regulatory implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Toilet Partition Market