
 Sanitary Ware and Bathroom Accessories Market | 2026-2036
Sanitary Ware and Bathroom Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Ware and Bathroom Accessories Market Analysis
Premium vitreous china specifications is rotating through the specification channel as architects and hotel operators tighten surface-porosity and thermal-shock tolerances. TOTO leverages captive ceramic engineering in Japan to sustain its position in automated bidet-toilet systems. Kohler anchors North American project pipelines through vertically controlled foundry and enameling operations. Duravit competes in European design-led hospitality by specializing in thin-wall, rimless bowl geometries.
Sanitary ware and bathroom accessories comprise engineered ceramic, metal, and glass fixtures designed for hygiene, water conveyance, and personal cleansing in built environments; vitreous china products achieve impermeability through feldspathic glaze fired above 1,200°C, yielding surfaces resistant to chemical staining and mechanical abrasion. Porcelain and ceramic materials dominate value capture in replacement cycles due to durability premiums and established installer familiarity. The hospitality end-user segment commands elevated margin pools as branded property mandates require certified water-efficiency ratings and coordinated accessory suites across room categories.
EPA WaterSense labeling, the EU Ecodesign Directive, and China's GB water-efficiency standards collectively restrict maximum flush volumes and mandate fixture testing protocols, forcing manufacturers to redesign trapways and valve mechanisms. Compliance costs favor scaled producers with in-house metrology laboratories and regulatory affairs teams. Stakeholders must monitor tightening alignment between green building certification schemes and national plumbing codes, as divergent test methods threaten to fragment product portfolios and raise regional adaptation expenses.
Market Dynamics
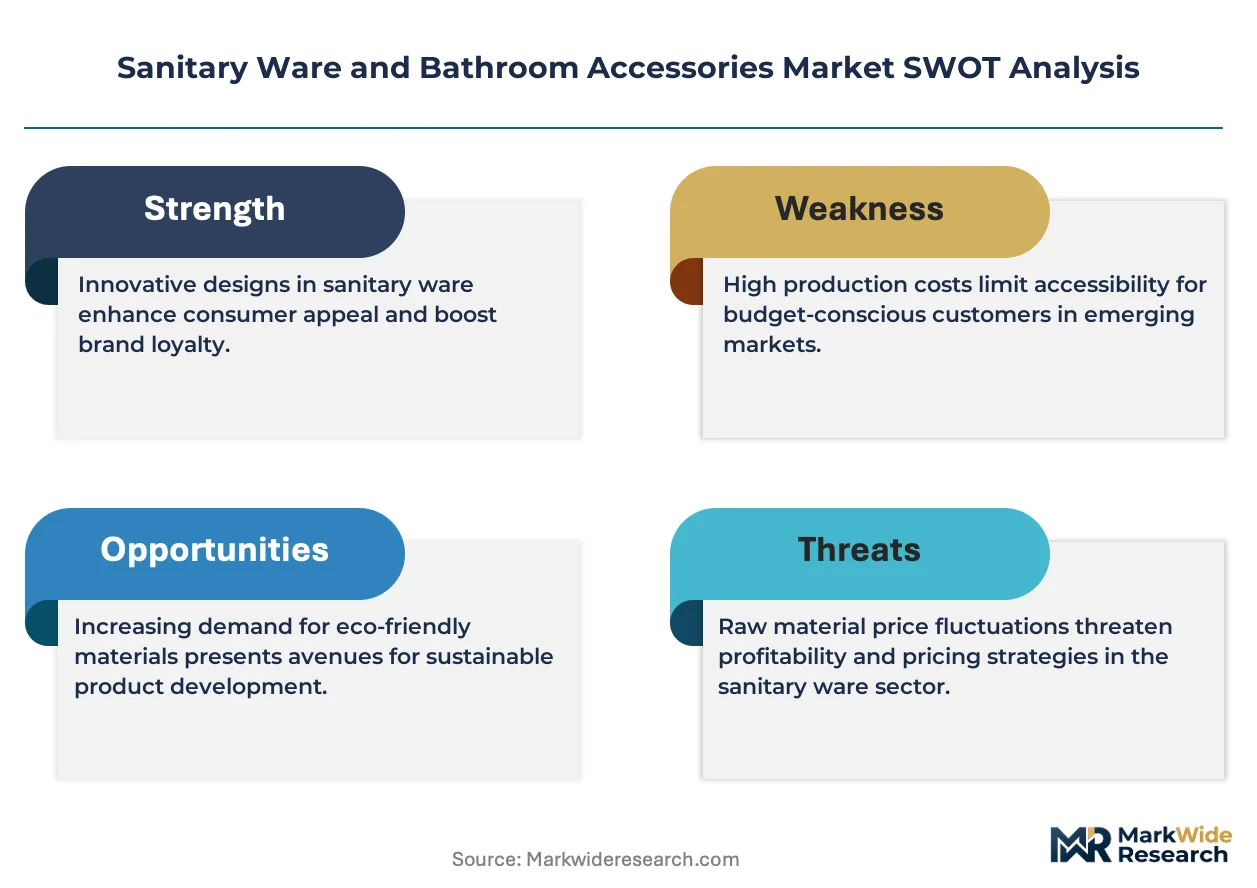
Water-efficiency mandates from EPA WaterSense and the EU Ecodesign Directive are compressing flush-volume tolerances and forcing wholesale redesign of trapway geometries and valve mechanisms across product portfolios.
Growth Catalysts
- EPA WaterSense Labeling:Certified fixtures command specification preference in US federal building projects and hospitality procurement, pulling volume toward dual-flush and pressure-assist technologies.
- Guangdong Manufacturing Cluster:Integrated kiln-to-showroom operations in China's Pearl River Delta compress lead times for both domestic property development and export channels.
- Hospitality Renovation Cycles:Branded property mandates in Dubai and Singapore require coordinated accessory suites and certified efficiency ratings, elevating specification-grade ceramic volumes.
Market Restraints
- Feldspathic Glaze Input Volatility:Energy-intensive firing above 1,200°C ties production costs to natural gas price swings in ceramic heartlands.
- Guangdong Supply Concentration:Over-reliance on a single provincial manufacturing base creates vulnerability to regional power rationing and logistics bottlenecks.
- EU Ecodesign Testing Fragmentation:Divergent flush-performance protocols between member states force redundant metrology investments and delay product launches.
Strategic Opportunities
- India Affordable Housing:Government sanitation expansion programs and urban infrastructure investment create volume demand for cost-optimized vitreous china.
- Sensor-Integrated Hygiene Convergence:Touchless actuation and occupancy-sensing technologies merge with traditional fixture categories, opening premium positioning.
- EU Green Building Certification Alignment:Tighter coupling of Ecodesign compliance with BREEAM and LEED scoring creates specification pull for labeled products.
Industry Challenges
- Certified Plumbing Installer Scarcity:Specialized training for pressure-assist and rimless bowl installation lags product innovation, creating service-quality risk.
- Legacy Trapway Retrofit Complexity:Water-efficient valve mechanisms often require rough-in modifications that conflict with existing drainage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Ware and Bathroom Accessories Market |
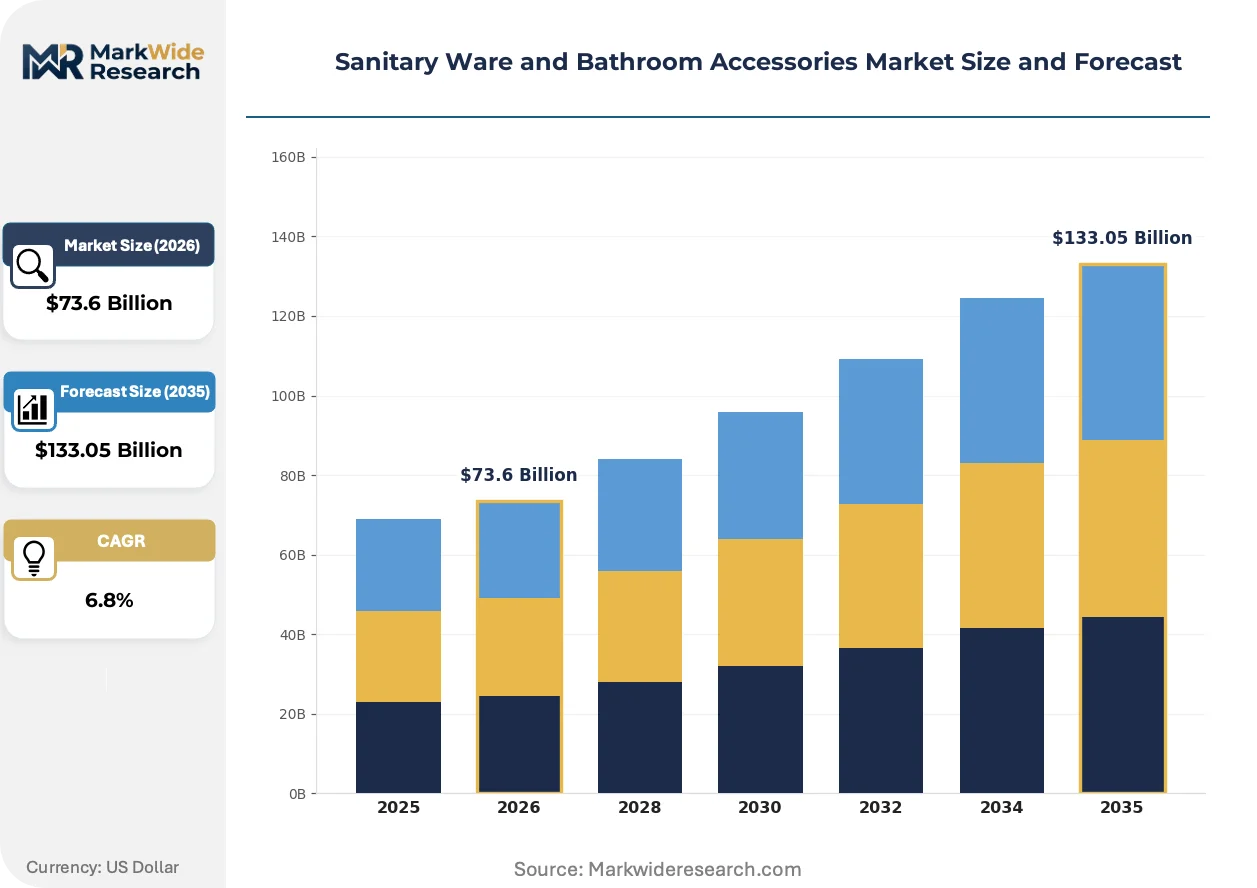
| Market Size in 2026 | $73.6 Billion |
| Market Size in 2035 | $133.05 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Sinks, Showers, Bathtubs Material: Porcelain, Ceramic, Glass, Stainless Steel Style: Modern, Classic, Minimalist, Vintage End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Roca, American Standard, TOTO, Duravit, Villeroy & Boch, Kohler, Hansgrohe, Geberit, Grohe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Ware and Bathroom Accessories Market Emerging Trajectories
Electromechanical integration and material science advances are redefining fixture performance boundaries, while procurement patterns shift toward bundled specification and lifecycle accountability.
Sensor-embedded actuation systems are miniaturizing valve housings and enabling concealed installation profiles that preserve architectural clean lines. Luxury hospitality operators in Singapore and Dubai specify these packages for guestroom refresh cycles. The technology is compressing mechanical component counts and shifting supplier value toward firmware and calibration services.
REACH substance restrictions and the EU F-Gas Regulation are eliminating certain sealant chemistries and refrigerant-based cooling from manufacturing processes. Ceramic producers reformulate glaze compositions and accelerate water-based binder adoption. European design-led hospitality faces compressed reformulation timelines to maintain CE marking continuity.
Architect-led specification bundles now consolidate fixture, accessory, and surface material selection under single-source accountability, displacing fragmented trade purchasing. Design-build contractors in North American commercial construction adopt these consolidated procurement packages most aggressively. Hotel operators in Dubai increasingly mandate this approach to streamline renovation cycle management and warranty alignment.
Sanitary Ware and Bathroom Accessories Market Segmentation
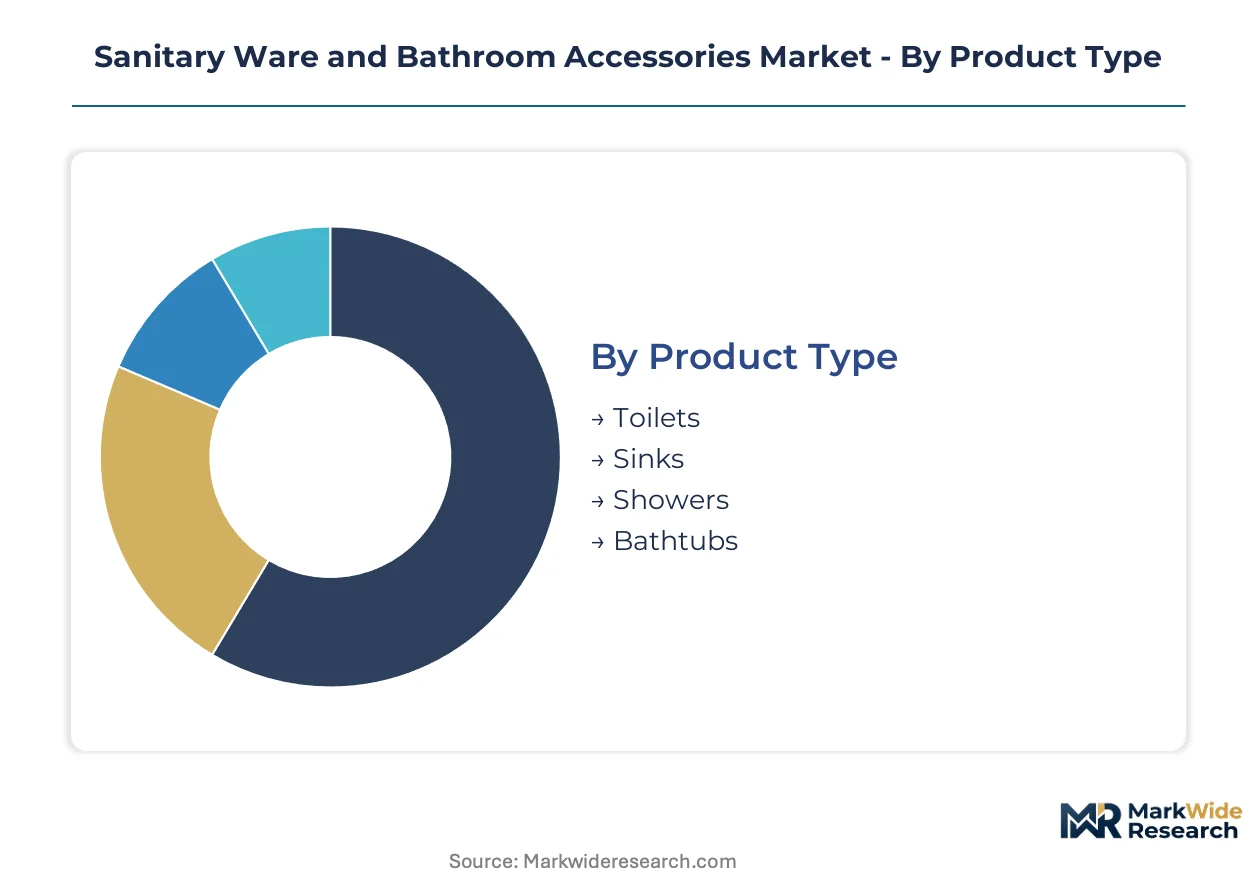
Segmentation in sanitary ware reflects divergent compliance pathways across EPA WaterSense, EU Ecodesign, and China's GB standards. Material specifications and end-use certification requirements fragment procurement criteria, forcing manufacturers to maintain parallel product portfolios.
Product Type:
EPA WaterSense and EU Ecodesign testing protocols apply differential flush-volume limits and trapway performance standards across fixture categories, creating distinct compliance burdens.
- Toilets:Dual-flush and pressure-assist mechanisms dominate specification channels as certified efficiency ratings become mandatory for federal building projects. Demand concentrates in US hospitality renovation pipelines where WaterSense labeling commands procurement preference.
- Sinks:Vitreous china and solid-surface basins achieve specification through thermal-shock tolerance and surface-porosity thresholds. Singapore and Dubai hotel operators mandate coordinated sink-to-faucet suites across guestroom categories, elevating design-led volumes.
- Showers:Thermostatic mixing valves and low-flow head assemblies align with tightening water-efficiency mandates.
- Bathtubs:Acrylic and enameled-steel formats serve replacement cycles in residential channels.
Established volume favors toilets; emerging adoption favors showers as sensor-integrated hygiene convergence accelerates.
Material:
Cost tiers separate specification-grade vitreous china from commodity alternatives, with firing energy intensity creating margin pressure across ceramic categories.
- Porcelain:Feldspathic glaze fired above 1,200°C yields impermeable surfaces resistant to chemical staining. China's Guangdong cluster dominates volume through integrated kiln-to-showroom operations serving both domestic property development and export channels.
- Ceramic:Lower firing temperatures reduce energy costs but compress durability premiums in commercial applications. India's affordable housing expansion programs pull cost-optimized ceramic volumes for sanitation infrastructure deployment.
- Glass:Tempered and frosted variants serve vanity and shower enclosure segments.
- Stainless Steel:Industrial and healthcare applications favor corrosion-resistant specifications.
Specification margins concentrate in porcelain; volume scaling favors ceramic as India infrastructure programs expand.
Style:
Architect-led specification bundles now consolidate aesthetic selection under single-source accountability, displacing fragmented trade purchasing.
- Modern:Clean lines and concealed installation profiles align with sensor-embedded actuation systems. Singapore luxury hospitality operators specify these packages for guestroom refresh cycles, compressing mechanical component counts.
- Minimalist:Rimless bowl geometries and thin-wall constructions reduce material content while maintaining structural integrity. Duravit specializes in these design-led European hospitality specifications.
- Classic:Traditional pedestal and console forms persist in residential replacement markets.
- Vintage:Reproduction fixtures serve heritage building renovation requirements.
Design premiums attach to modern; replacement stability underpins classic.
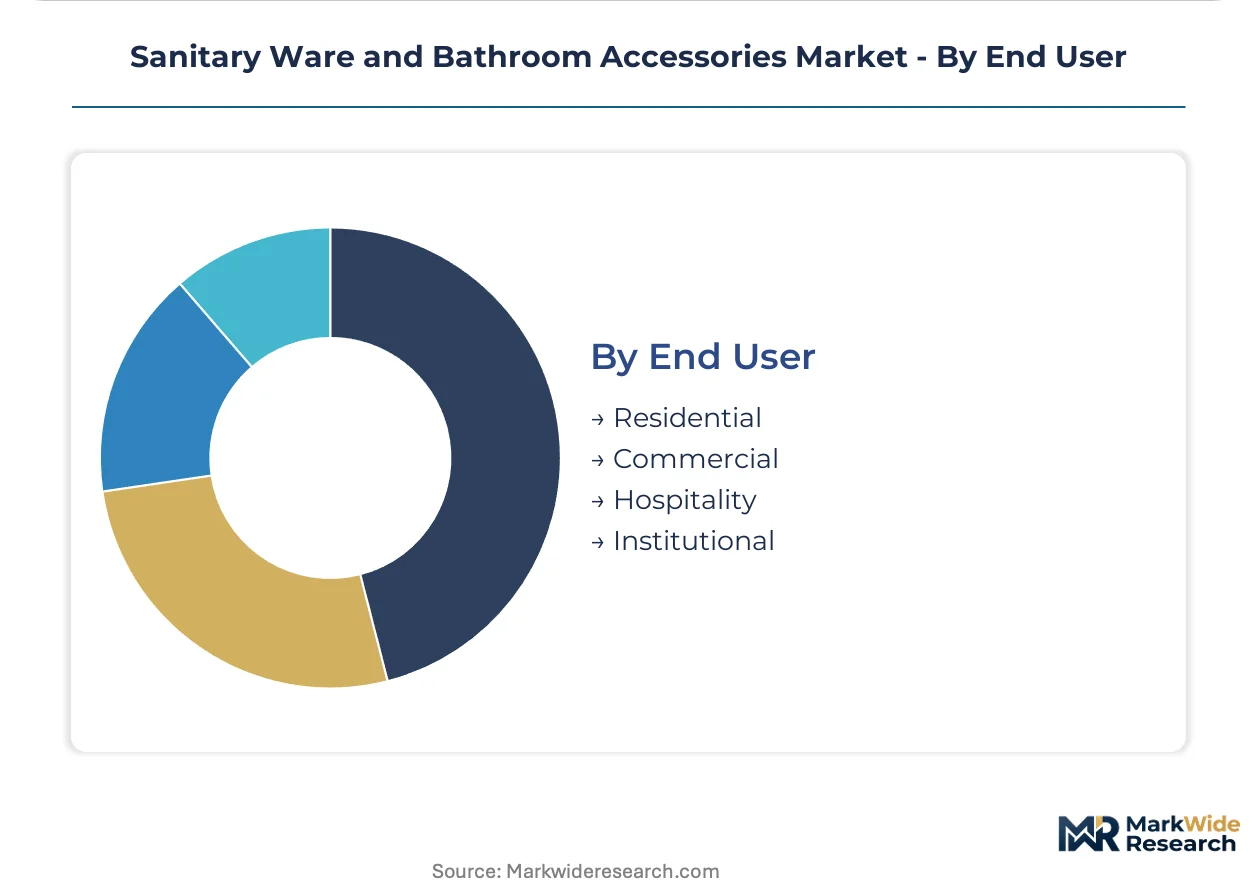
End User:
Customer type determines certification stringency, with hospitality and institutional segments mandating water-efficiency ratings that residential channels often bypass.
- Hospitality:Branded property mandates in Dubai and Singapore require certified efficiency ratings and coordinated accessory suites across room categories. TOTO leverages captive ceramic engineering to sustain position in automated bidet-toilet systems for this segment.
- Residential:Replacement cycles drive volume through established installer familiarity and durability premiums. Kohler anchors North American project pipelines through vertically controlled foundry and enameling operations.
- Commercial:Office and retail fit-outs prioritize vandal-resistant specifications and maintenance accessibility.
- Institutional:Healthcare and education facilities require antimicrobial surface treatments and ADA compliance.
Margin concentration sits with hospitality; volume depth resides in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated kiln-to-showroom operations in China's Guangdong province compress lead times for export channels. Manufacturing clusters in Japan and Germany sustain premium specification-grade output through captive ceramic engineering. Hospitality renovation mandates in Dubai and Singapore pull volumes toward certified water-efficiency ratings.
China
Domestic property development and export manufacturing concentrate in Guangdong's Pearl River Delta cluster. GB water-efficiency standards mandate maximum flush volumes and fixture testing protocols that reshape procurement criteria. Foshan and Chaozhou house vertically integrated operations serving both local construction and international distribution.
United States
Federal building projects and hospitality procurement channels pull volume toward EPA WaterSense certified fixtures. The EPA labeling program commands specification preference for dual-flush and pressure-assist technologies. Kohler anchors North American project pipelines through foundry and enameling operations in Wisconsin.
Germany
Design-led hospitality specifications across Europe concentrate margin pools in thin-wall, rimless bowl geometries. The EU Ecodesign Directive compresses flush-volume tolerances and forces trapway redesign across product portfolios. Duravit specializes in these geometries from manufacturing bases in the Hornberg region.
Japan
Automated bidet-toilet systems sustain premium positioning through electromechanical integration and sensor-embedded actuation. METI energy-efficiency guidelines and JIS standards govern fixture performance and water consumption thresholds. TOTO leverages captive ceramic engineering from Kitakyushu operations to serve luxury hospitality operators in Singapore and Dubai.
India
Government sanitation expansion programs and urban infrastructure investment create volume demand for cost-optimized vitreous china. The Bureau of Indian Standards enforces water-efficiency testing that aligns with international protocol convergence. Manufacturing activity clusters in Gujarat and Haryana to serve affordable housing deployment timelines.
Sanitary Ware and Bathroom Accessories Market Vendor Landscape
Concentration sits with integrated ceramic specialists and vertically controlled foundry operators. The vendor base stratifies across three tiers: premium design-led European houses, scale-driven North American manufacturers, and cost-optimized Asian exporters. Strategic moves center on portfolio diversification into sensor-integrated hygiene systems and geographic expansion through specification channel penetration in hospitality renovation cycles.
Among European design-led fabricators, Duravit and Villeroy & Boch exemplify premium-tier positioning through thin-wall ceramic specialization. TOTO anchors the electromechanical integration archetype from its Japanese engineering base. These three represent distinct competitive vectors: European aesthetics, Japanese automation, and North American vertical scale.
| Leading Market Players |
|---|
| Roca |
| American Standard |
| TOTO |
| Duravit |
| Villeroy & Boch |
| Kohler |
| Hansgrohe |
| Geberit |
| Grohe |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Guangdong kiln operators and Dubai hospitality procurement desks lock in ceramic volume commitments while capping glaze material cost pass-through. These arrangements stabilize foundry utilization rates across China's Pearl River Delta and compress price volatility for specification-grade vitreous china. Buyers gain supply visibility; producers secure capacity absorption against property development cyclicality.
Pricing Analysis
EPA WaterSense dictates the pricing tier structure across North American specification channels, separating certified dual-flush mechanisms from uncertified commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in economy ceramic tiers is intensifying because India's affordable housing programs pull volume toward basic vitreous china. Residential replacement buyers show highest price sensitivity; Dubai hospitality operators demonstrate lowest sensitivity due to branded property mandates.
Supply Chain Analysis
China and India anchor global sanitary ware manufacturing, with Guangdong province housing vertically integrated kiln-to-showroom operations and Gujarat serving cost-optimized ceramic output. Production draws from feldspathic glaze minerals, natural gas for firing energy, and precision valve components. Single-source vulnerability concentrates in Guangdong's provincial power grid exposure. Distribution runs through project-based specification channels for hospitality, wholesale plumbing distributors for residential replacement, and direct OEM supply for institutional fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality renovation cycles in Dubai and Singapore signal cyclical recovery momentum as deferred property upgrades release pent specification demand. Water-efficiency mandate tightening across EPA WaterSense and EU Ecodesign accelerates replacement timelines.
For Market Incumbents: Secure captive ceramic engineering capabilities against emerging sensor-integrated hygiene specialists. Expand metrology laboratory investments to compress EU Ecodesign compliance timelines. Anchor North American project pipelines through backward integration into foundry and enameling operations.
For New Entrants and Emerging Players: EPA WaterSense fast-track certification opens specification access in US federal building procurement. Target India's affordable housing sanitation expansion as the most penetrable volume segment. Pursue design-build contractor partnerships as the primary go-to-market angle for bundled fixture-accessory suites.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically controlled ceramic specialists with in-house regulatory affairs teams. Long-term viability favors producers with demonstrated compliance across EPA WaterSense, EU Ecodesign, and China's GB standards. Monitor alignment between green building certification schemes and national plumbing codes as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Hygiene Convergence | Merges touchless actuation with traditional fixtures for Singapore luxury hospitality specifications. |
| Backward Integration into Feldspathic Glaze Supply | Reduces input cost volatility for Guangdong kiln operators facing natural gas price swings. |
| EU Ecodesign Compliance Acceleration | Compresses product launch timelines for Duravit and European design-led competitors. |
| India Affordable Housing Volume Capture | Aligns cost-optimized ceramic output with government sanitation infrastructure deployment. |
| Architect-Led Specification Bundle Consolidation | Streamlines Dubai hotel renovation procurement under single-source accountability frameworks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA WaterSense certification registries, EU Ecodesign directive filings, and hospitality procurement databases. Interviews with ceramic plant managers, specification channel distributors, hotel procurement directors, and plumbing contractor associations ground demand-side validation. Bottom-up volume triangulation across product type, material grade, and end-user segment converges with top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include fixture category, vitreous china quality tier, style archetype, and hospitality versus residential end-use across the projection horizon. CAGRs derive from regression analysis of historical replacement cycle timing, regulatory mandate phase-in schedules, and property development pipeline data. Firing energy cost trajectories and glaze material price indices inform ceramic segment forecasts.
Underlying assumptions cover hospitality renovation cycle continuity, regulatory protocol convergence, and Guangdong manufacturing base stability, with deviation risk concentrated in regional power rationing events and divergent EU member state testing fragmentation. Recalibration cycles align with material shifts in water-efficiency mandate tightening and green building certification scheme alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market