
 Bath Fittings and Accessories Market | 2026-2036
Bath Fittings and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Fittings and Accessories Market Outlook
EU Ecodesign requirements for water-using products is repositioning procurement criteria across European hospitality and residential development. Kohler Co. leverages its captive foundry network to control brass alloy quality for premium faucet lines. TOTO Ltd. dominates sensor-activated fixture engineering for commercial restroom specifications. Hansgrohe SE differentiates through precision-machined spray technologies that command specification loyalty among architects.
Bath fittings and accessories encompass plumbed and non-plumbed hardware installed in residential, commercial, and institutional washrooms, typically manufactured through gravity die-casting of brass alloys, CNC machining of stainless steel billets, or injection molding of engineered polymers, with functional parameters governed by flow-rate limits, pressure tolerance, and surface finish durability against chloride exposure. Faucets and showerheads anchor the value pool given their mechanical complexity and replacement frequency, while vessel and freestanding installations in the hospitality segment attract disproportionate margin concentration due to custom specification requirements. Stainless steel and brass materials sustain premium positioning against plastic alternatives in renovation-driven replacement cycles.
EPA WaterSense certification shapes US market access by mandating maximum flow rates of 1.5 gallons per minute for bathroom faucets, while China's GB standards enforce local testing protocols for imported ceramic valve cartridges. India's BIS marking requirement for sanitary fittings creates compliance friction for unbranded imports. Stakeholders must monitor divergence between regional water-efficiency thresholds and material content restrictions as specification sheets fragment across export destinations.
Market Dynamics
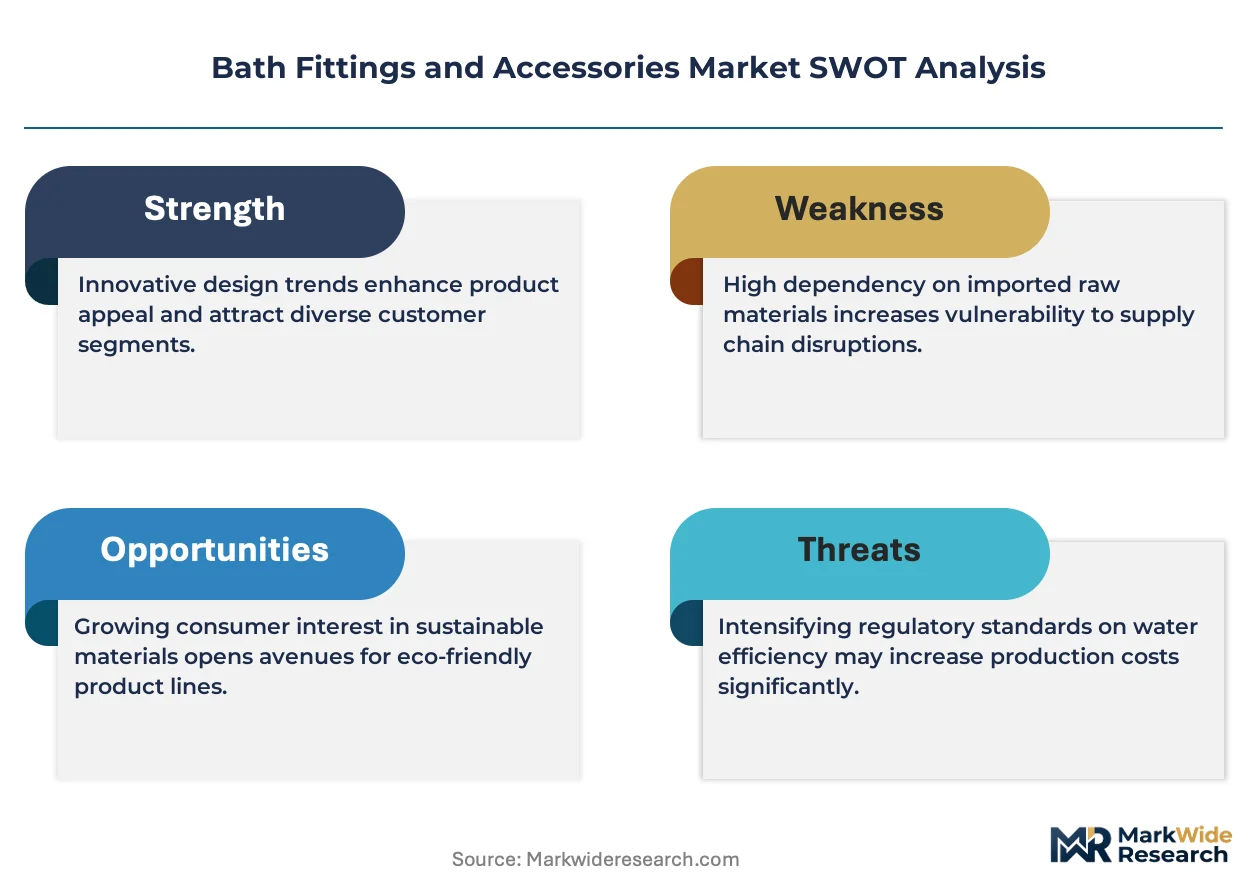
Water-efficiency mandates from EPA WaterSense and EU Ecodesign are forcing fixture manufacturers to redesign valve architectures and recalibrate foundry output, compressing margins on legacy high-flow product lines while opening specification slots for engineered low-flow alternatives.
Growth Catalysts
- EPA WaterSense certification thresholds:Federal procurement preference for 1.5 GPM bathroom faucets drives municipal and hospitality retrofit specifications toward compliant manufacturers.
- Urban renewal infrastructure replacement:China's tier-one cities are demolishing aging residential towers, creating synchronized demand for complete plumbing fixture packages.
- Sensor-activated engineering:Touchless valve systems reduce water waste in commercial restrooms while lowering maintenance frequency for facility managers.
Market Restraints
- Brass alloy cost volatility:Copper and zinc price swings compress foundry margins and destabilize premium faucet pricing.
- Import certification friction:India's BIS marking requirement for sanitary fittings blocks unbranded Chinese imports from budget distribution channels.
- Ceramic disc cartridge supply concentration:Precision-machined valve components rely on a narrow supplier base in Zhejiang and Guangdong provinces.
Strategic Opportunities
- EU Ecodesign compliance services:Testing and documentation support for water-using products creates recurring revenue streams for certification laboratories.
- Modular shower system convergence:Digital thermostatic controls paired with precision-machined spray heads enable premium upgrade paths in renovation markets.
- Southeast Asia hospitality expansion:Luxury hotel chains in Thailand and Vietnam are elevating bathroom specification budgets to differentiate guest experience.
Industry Challenges
- Dual certification timeline compression:Manufacturers must secure EPA WaterSense validation and EU Ecodesign conformity simultaneously for transatlantic product launches.
- Legacy plumbing infrastructure incompatibility:Low-flow fixtures require minimum pressure thresholds that aging residential distribution systems cannot guarantee.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath Fittings and Accessories Market |
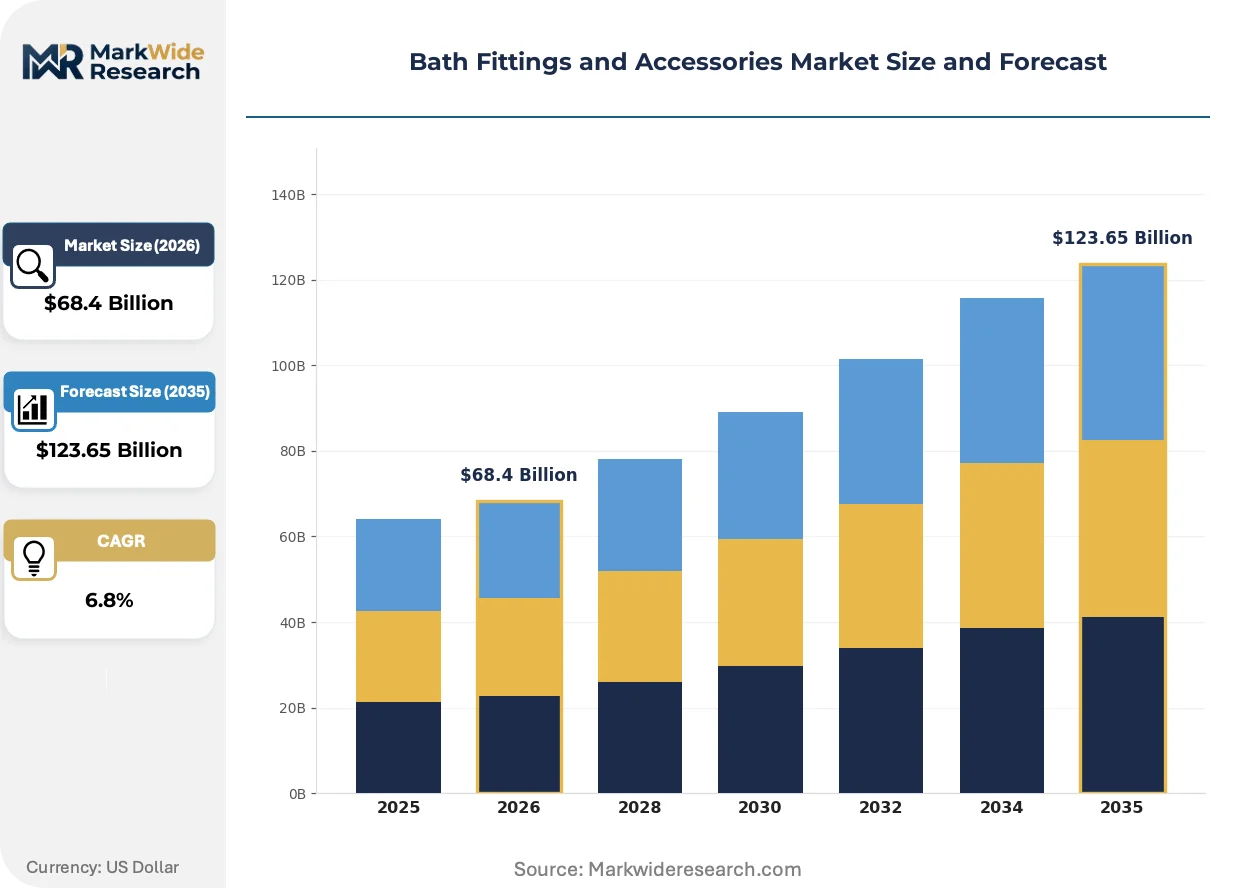
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showerheads, Faucets, Sinks, Bathtubs Material: Stainless Steel, Brass, Plastic, Ceramic Installation Type: Wall-Mounted, Deck-Mounted, Freestanding, Vessel End User: Residential, Commercial, Hospitality, Institutions |
| Companies Covered | Moen, TOTO Ltd., Kohler Co., Delta Faucet Company, Grohe AG, LIXIL Group, Jaquar Group, Hansgrohe SE, Masco Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Fittings and Accessories Market Strategic Shifts
Digital integration and material science advances are redefining fixture functionality, with sensor systems and engineered polymers displacing mechanical brass assemblies across price tiers.
Thermostatic digital shower controls are expanding into mid-market residential renovation specifications. Homeowners replacing aging pressure-balanced valves now demand programmable temperature presets and flow monitoring. This convergence of plumbing hardware with IoT connectivity is expanding into adjacent fixture categories including sensor-activated faucets and leak-detection shutoff systems.
EU Ecodesign requirements for water-using products now mandate maximum flow rates and minimum performance efficiency indices across member states. Manufacturers must redesign spray geometries and aerator architectures to maintain user satisfaction at reduced volumes. Germany and France lead enforcement stringency, with national market surveillance authorities rejecting non-compliant imports at border inspection points.
Architect specification influence is consolidating around certified performance documentation rather than brand heritage alone. Design firms now require third-party flow-rate verification and lifecycle durability testing before including fixtures in commercial project submissions. This documentation-driven selection process is most visible in US hospitality and healthcare verticals where LEED and WELL certification credits depend on verified water performance metrics.
Bath Fittings and Accessories Market Segmentation
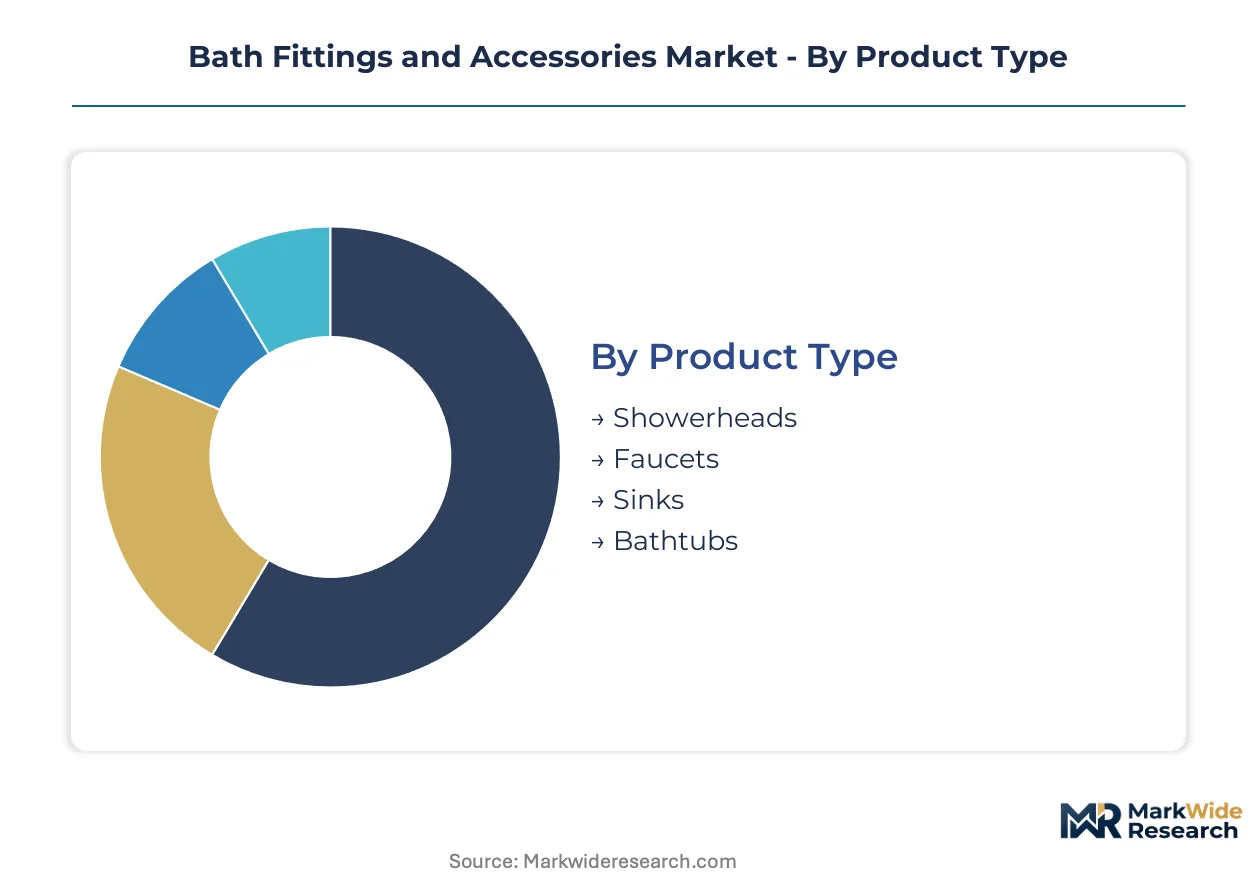
Segmentation in bath fittings reveals how specification requirements diverge across pressure tolerances, surface finish durability, and regulatory compliance thresholds. Understanding these divisions exposes where margin concentrates versus where volume flows.
Product Type:
Standalone fixtures dominate renovation-driven replacement cycles, while integrated shower systems command premium specification in new construction.
- Faucets:Mechanical complexity centers on ceramic disc cartridges and aerator engineering. China's tier-one cities drive synchronized demand through urban renewal demolition of aging residential towers. EPA WaterSense mandates at 1.5 GPM maximum flow reshape valve architectures.
- Showerheads:Precision-machined spray geometries differentiate premium positioning. Southeast Asia luxury hotel chains specify custom thermostatic controls for guest experience differentiation. EU Ecodesign flow-rate limits force spray pattern redesigns.
- Sinks:Vessel and undermount configurations anchor hospitality margin pools through custom specification requirements.
- Bathtubs:Freestanding installations attract disproportionate margin concentration in high-end residential and boutique hotel verticals.
Faucets lead volumes today; showerheads are gaining share fastest through digital thermostatic convergence.
Material:
Cost tier stratification separates specification-grade metals from commodity polymers in both residential replacement and commercial new-build channels.
- Brass:Gravity die-casting of copper-zinc alloys sustains premium faucet positioning through foundry-controlled alloy quality. Copper price volatility compresses margins and destabilizes pricing across European and North American distribution.
- Stainless Steel:CNC machining of billets delivers chloride resistance for coastal hospitality specifications. India's BIS marking requirements create compliance friction for unbranded imports in budget channels.
- Plastic:Injection-molded engineered polymers displace metal in economy-tier volume plays.
- Ceramic:Vitreous china and fireclay dominate sink basins and vessel applications through surface hardness and stain resistance.
Brass dominates revenue contribution; stainless steel is climbing the fastest on coastal corrosion specifications.
Installation Type:
Application context determines mounting geometry, with concealed plumbing driving wall-mounted specification and statement design favoring freestanding visibility.
- Wall-Mounted:Concealed rough-in plumbing dominates commercial restroom specifications for maintenance access. Sensor-activated engineering integrates most naturally with wall-hung configurations in airport and healthcare verticals.
- Freestanding:Exposed supply lines and floor-mounted drains command architect specification loyalty in luxury residential and boutique hospitality. Custom fabrication requirements concentrate margin with specialized foundry networks.
- Deck-Mounted:Countertop integration suits vanity-centric residential renovation where existing cabinetry constrains rough-in relocation.
- Vessel:Above-counter bowl configurations attract disproportionate specification in design-forward hospitality and high-end residential segments.
Wall-mounted fixtures anchor commercial volumes; freestanding installations show steepest expansion trajectory in premium hospitality.
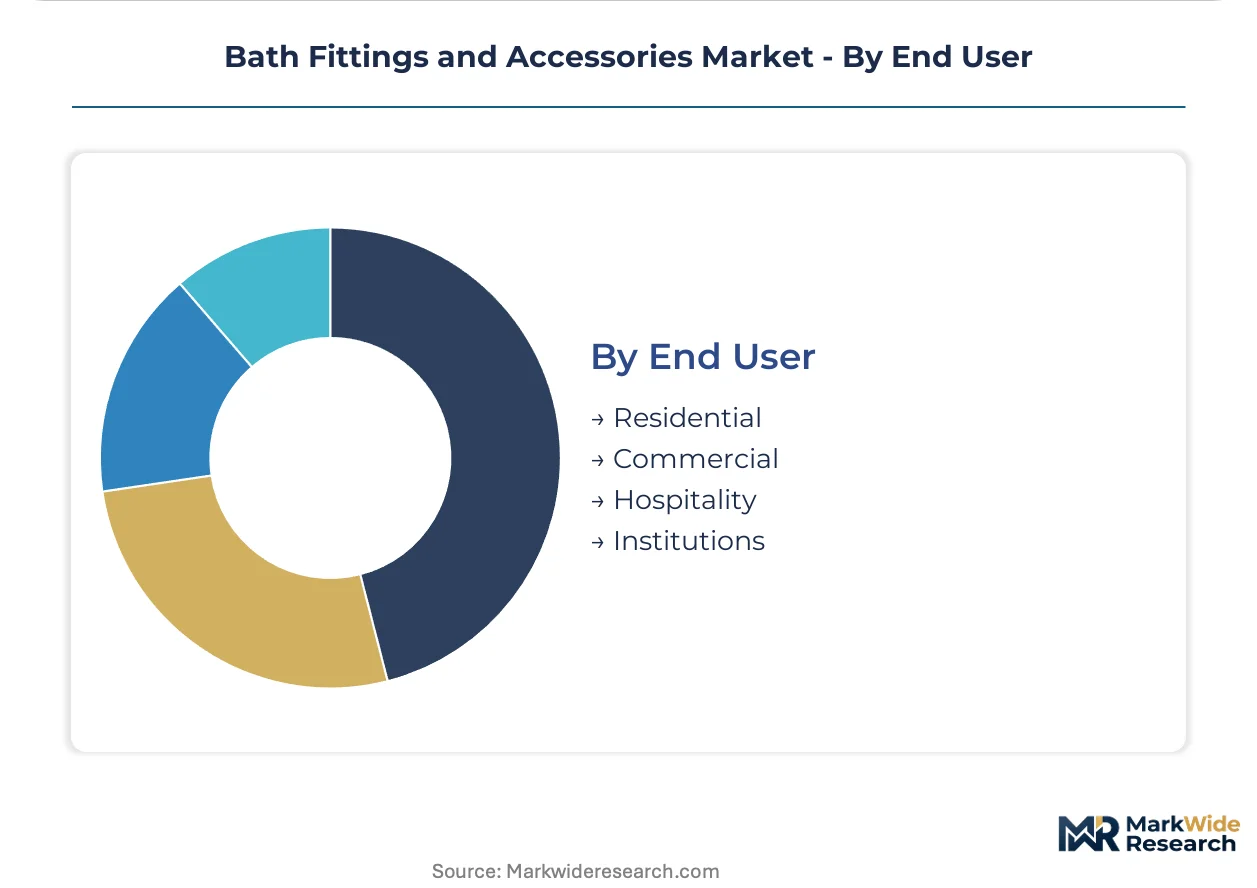
End User:
Customer type dictates certification burden, replacement frequency, and specification influence pathways from procurement to installation.
- Residential:Renovation-driven replacement cycles favor DIY-accessible SKUs through retail distribution. Aging infrastructure incompatibility constrains low-flow fixture adoption in pre-1980 housing stock across US and European markets.
- Hospitality:Luxury hotel chains in Thailand and Vietnam elevate bathroom specification budgets for guest experience differentiation. LEED and WELL certification credits demand verified water performance documentation.
- Commercial:Facility managers prioritize sensor-activated systems for water waste reduction and maintenance frequency compression.
- Institutions:Healthcare and education procurement runs through formal specification processes with extended validation timelines.
Residential channels move the highest unit volumes; hospitality is expanding most quickly on experience-differentiation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brass foundry operations trace their industrial lineage to European metalworking centers established during the nineteenth century, with subsequent manufacturing gravity shifting toward Asian casting clusters. Contemporary demand patterns reflect this dual heritage: European precision engineering maintains specification influence while Asian production networks dominate volume fabrication.
United States
Renovation-driven replacement cycles in pre-1980 housing stock sustain steady faucet and showerhead demand, though aging plumbing infrastructure limits low-flow fixture compatibility. EPA WaterSense certification at 1.5 GPM maximum flow shapes municipal and hospitality procurement specifications. The Southeast manufacturing corridor from Georgia through the Carolinas hosts gravity die-casting operations serving North American distribution networks.
Germany
Precision-machined spray technologies command architect specification loyalty across commercial and hospitality verticals, with thermostatic engineering expertise concentrated in southwestern industrial clusters. EU Ecodesign enforcement through national market surveillance authorities rejects non-compliant imports at border inspection points. The Rhine-Main manufacturing belt anchors foundry-to-finish production integration for premium faucet lines.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen drive synchronized demand through urban renewal demolition of aging residential towers. GB standards enforce local testing protocols for imported ceramic valve cartridges, creating compliance friction for foreign suppliers. Zhejiang and Guangdong provinces concentrate precision-machined valve component fabrication, with Ningbo and Foshan clusters supplying global OEM networks.
India
Budget distribution channels face supply constraints as BIS marking requirements for sanitary fittings block unbranded Chinese imports. Residential renovation in Mumbai, Delhi-NCR, and Bangalore sustains steady replacement demand for economy and mid-tier fixtures. Gujarat's brass foundry belt near Jamnagar supplies alloy castings to domestic fabricators and export-oriented manufacturers.
Thailand
Luxury hotel chains in Bangkok and Phuket elevate bathroom specification budgets to capture premium guest experience differentiation. Hospitality procurement runs through design-forward specification processes with extended validation timelines. Eastern seaboard industrial estates near Rayong host metal finishing and assembly operations serving Southeast Asian distribution.
Bath Fittings and Accessories Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered market positions, with captive foundry networks anchoring premium positioning and contract manufacturers serving volume tiers. The vendor base stratifies around three archetypes: vertically integrated brass alloy specialists, precision-engineering houses with architect specification loyalty, and scale-driven assemblers of standardized SKUs. Dominant competitive moves include backward integration into ceramic valve cartridge supply and geographic expansion through regional distribution partnerships.
Within the precision-engineering tier, Hansgrohe SE exemplifies specification-driven positioning through southwestern German manufacturing heritage. Kohler Co. and TOTO Ltd. anchor contrasting strategic approaches: the former through captive foundry control over alloy quality, the latter through sensor-activated fixture engineering for commercial restroom specifications. These three entities occupy positions that illustrate how technical differentiation and supply chain configuration translate into distinct competitive vectors across price tiers and end-use segments.
| Leading Market Players |
|---|
| Moen |
| TOTO Ltd. |
| Kohler Co. |
| Delta Faucet Company |
| Grohe AG |
| LIXIL Group |
| Jaquar Group |
| Hansgrohe SE |
| Masco Corp. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap brass foundries in Germany and Italy anchor premium-tier pricing discipline through generational control of alloy formulations and architect relationships. Their captive supply of precision-machined valve components insulates margin pools from commodity volatility while forcing contract manufacturers in Asian casting clusters to compete on volume scale alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade brass fixtures from injection-molded polymer alternatives. Price differentiation centers on EPA WaterSense certification attainment and foundry-controlled copper-zinc alloy quality. Pricing pressure stems from copper and zinc commodity swings compressing margins at European and North American foundries. Budget residential renovation channels exhibit highest price sensitivity, while Southeast Asia luxury hospitality procurement prioritizes performance documentation over unit cost.
Supply Chain Analysis
Skilled die-casting technicians in Zhejiang and Guangdong provinces supply precision-machined ceramic valve cartridges to global OEM networks. Raw material draws from Chilean copper concentrates, Australian zinc ingots, and domestic Chinese rare-earth processing for sensor components. Supply chain risk concentrates in single-source dependency on Ningbo and Foshan clusters for critical valve architectures. Distribution runs through regional plumbing wholesalers in North America, specification-driven merchant houses in Europe, and project-direct channels for Southeast Asia hospitality developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through engineered low-flow fixture adoption displacing legacy high-flow inventories, with EPA WaterSense and EU Ecodesign compliance creating pricing power for certified manufacturers.
For Market Incumbents: Deepen backward integration into ceramic disc cartridge supply to reduce dependency on Zhejiang and Guangdong component clusters. Expand captive foundry capacity in the Southeast US manufacturing corridor to compress logistics costs for municipal retrofit specifications. Sensor-activated engineering expertise at TOTO Ltd. represents the benchmark for commercial restroom automation that threatens mechanical valve specialists. For New Entrants and Emerging Players: Begin with India's BIS-compliant economy-tier faucet lines targeting Mumbai and Delhi-NCR residential renovation channels blocked to unbranded Chinese imports. Sensor-activated commercial restroom fixtures in Thailand and Vietnam hospitality verticals offer specification entry points with extended validation timelines favoring patient capital. Partner with Eastern seaboard industrial estates near Rayong for metal finishing and regional distribution access. For Investors and Strategic Acquirers: Plumbing fixture conglomerates pursuing platform consolidation are the most active acquirer in this space, targeting precision-engineering houses with architect specification loyalty in southwestern Germany. Long-term viability hinges on digital thermostatic convergence and IoT-enabled leak detection expanding addressable market beyond mechanical replacement cycles. Watch for divergence between regional water-efficiency thresholds fragmenting specification sheets across export destinations as inflection indicator for certification-heavy versus certification-light strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Valve Cartridge Backward Integration | Captive supply of precision-machined components from Zhejiang clusters reduces single-source vulnerability for premium faucet lines. |
| EPA WaterSense Certification Investment | Federal procurement preference at 1.5 GPM maximum flow opens municipal and hospitality retrofit specifications. |
| Southeast Asia Hospitality Direct Sales | Bangkok and Phuket luxury hotel chains elevate bathroom budgets for guest experience differentiation. |
| Digital Thermostatic Platform Development | Programmable temperature presets and flow monitoring expand mid-market residential renovation addressable demand. |
| EU Ecodesign Compliance Documentation | German and French market surveillance authorities reject non-compliant imports at border inspection points. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brass foundry operations managers, hospitality procurement directors, commercial facility maintenance heads, and architect specification consultants with secondary validation from EPA WaterSense certification databases, EU Ecodesign registration portals, US customs import records, and China GB standards compliance filings. Bottom-up demand modeling across installation types and end-use segments triangulated against top-down market sizing from trade association publications.
Segment-weighting across product type, material grade, installation geometry, and end-use vertical drove value distribution assumptions over the projection horizon. CAGRs derived from regression analysis of replacement cycle frequencies, urban renewal demolition schedules in China's tier-one cities, and hospitality construction pipelines in Thailand and Vietnam. Copper and zinc price volatility indices, ceramic cartridge import volumes from Zhejiang and Guangdong, and BIS marking enforcement trends in India informed scenario boundaries.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting brass alloy trade flows, sovereign debt crises halting Southeast Asia hospitality developments, and breakthrough polymer formulations displacing metal fixtures in specification-grade applications. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and commodity price band stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market