
 Smart Curtain Market | 2026-2036
Smart Curtain Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Curtain Market Insights
Hospitality operators are rotating toward smart curtain systems faster than traditional residential buyers, driven by guest experience differentiation and operational efficiency targets. Somfy leverages its European distribution network to sustain leadership in motorized shading for premium hotel chains. Lutron Electronics anchors the North American commercial segment through deep specification relationships with architectural firms. Hunter Douglas competes on design-forward automated blinds that integrate with luxury interior portfolios.
Smart curtains are motorized window coverings equipped with embedded drive mechanisms, wireless communication modules, and light or temperature sensors that enable automated positioning based on environmental inputs or user-programmed schedules. The systems typically operate via low-voltage DC motors with torque ratings between 0.5 and 3 Nm, depending on fabric weight and track length, and serve primarily to optimize daylight harvesting, thermal insulation, and occupant comfort in built environments. Motorized curtains dominate current volume as the most established retrofit-friendly category, while smart shades capture disproportionate margin growth through tighter integration with whole-building automation platforms. Wi-Fi technology leads residential penetration for its smartphone-native setup, though Zigbee is gaining fastest in commercial and hospitality deployments where mesh reliability and gateway consolidation matter more than standalone simplicity.
FCC certification requirements govern wireless transmission modules in the US market, while CE marking and the EU Green Deal's building performance standards shape product compliance trajectories across Europe. REACH restrictions on certain flame retardants and plasticizers increasingly influence fabric and component sourcing decisions for manufacturers serving both jurisdictions. BIS certification for electrical safety applies to products entering India, where the national smart cities mission is creating new specification channels. Stakeholders must monitor how fragmented national building codes evolve around automated shading integration, as regulatory alignment—or its absence—will determine which technology platforms achieve cross-border scale.
Market Dynamics
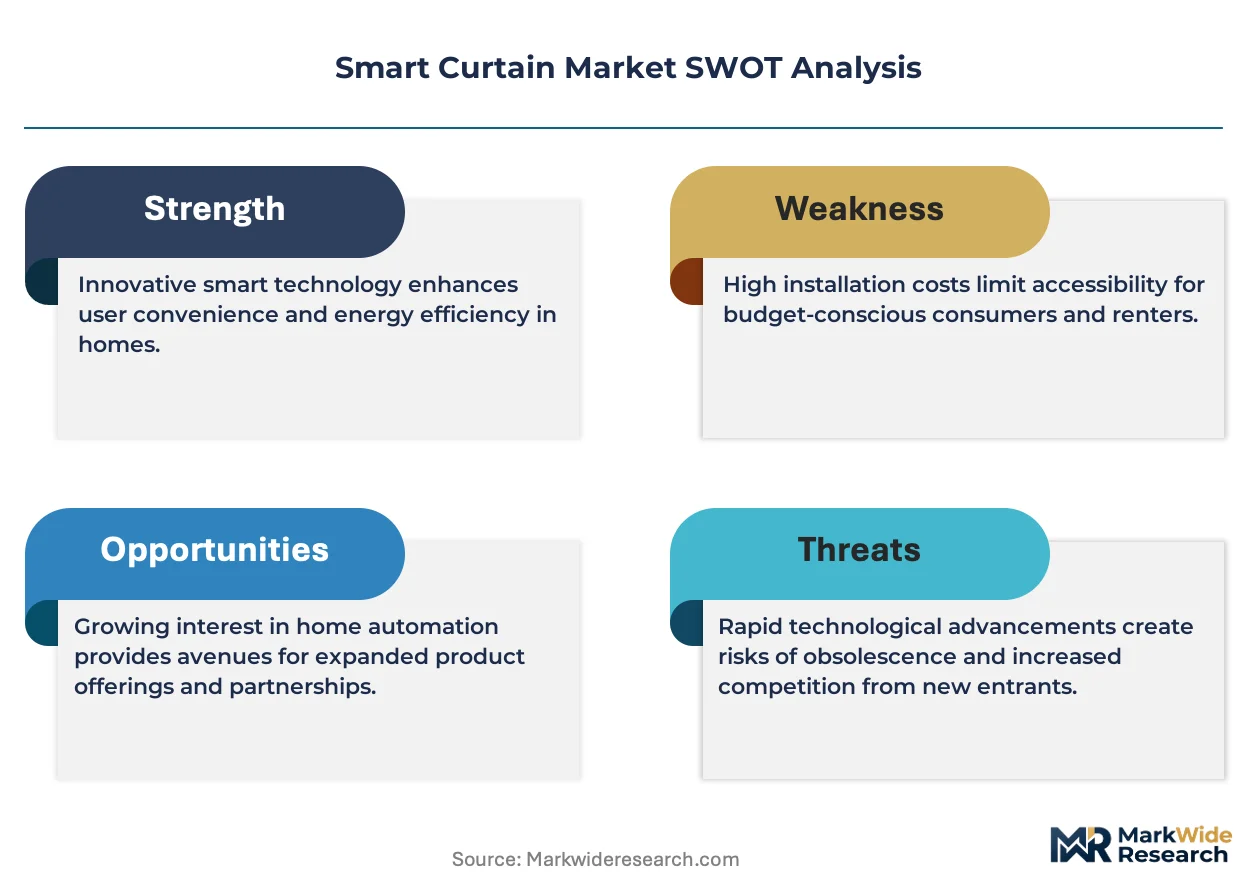
The EU Green Deal's building efficiency mandates are compressing specification timelines across commercial real estate, forcing developers to integrate automated shading systems earlier in project cycles than traditional construction schedules permit.
Growth Catalysts
- Hospitality Retrofit Cycles:Hotel chains are replacing manual window treatments with motorized systems to reduce housekeeping labor and enable centralized energy management across property portfolios.
- REACH Compliance Migration:Fabric suppliers are reformulating flame-retardant chemistries to meet ECHA restrictions, opening specification pathways for European manufacturers with certified material streams.
- Mesh Network Reliability:Zigbee's protocol stability is displacing Wi-Fi in commercial deployments where gateway consolidation and building-wide automation integration take priority over consumer-grade simplicity.
Market Restraints
- DC Motor Supply Concentration:Torque-rated motor production clusters in East Asian manufacturing hubs, exposing European and North American assemblers to extended lead times and freight cost volatility.
- FCC Certification Friction:Wireless module testing timelines for the US market create 4-6 month product launch delays that compress revenue recognition windows for new entrants.
- Manual Shade Substitution:Cordless spring-loaded alternatives satisfy basic safety regulations at one-third the installed cost, limiting smart curtain penetration in price-sensitive residential retrofits.
Strategic Opportunities
- India Smart Cities Mission:BIS-certified motorized shading systems qualify for municipal procurement tenders across urban redevelopment zones, creating first-mover specification advantages.
- Daylight Harvesting Convergence:Integration between light sensors and building management systems enables utility-backed demand response programs that subsidize hardware installation costs.
- Direct-to-Developer Channels:Bypassing traditional window treatment distributors to sell specification-grade systems directly to commercial general contractors captures margin and reduces channel conflict.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers with combined wireless protocol and low-power motor control expertise extends product development cycles and inflates compensation costs.
- Legacy BAS Integration Complexity:Proprietary communication stacks in existing building automation systems require custom middleware development, increasing deployment cost and failure risk.
- Multi-Jurisdiction Certification Overlap:Divergent electromagnetic emission limits between FCC, CE, and BIS regimes force hardware variants that fragment production scale and inventory efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Curtain Market |
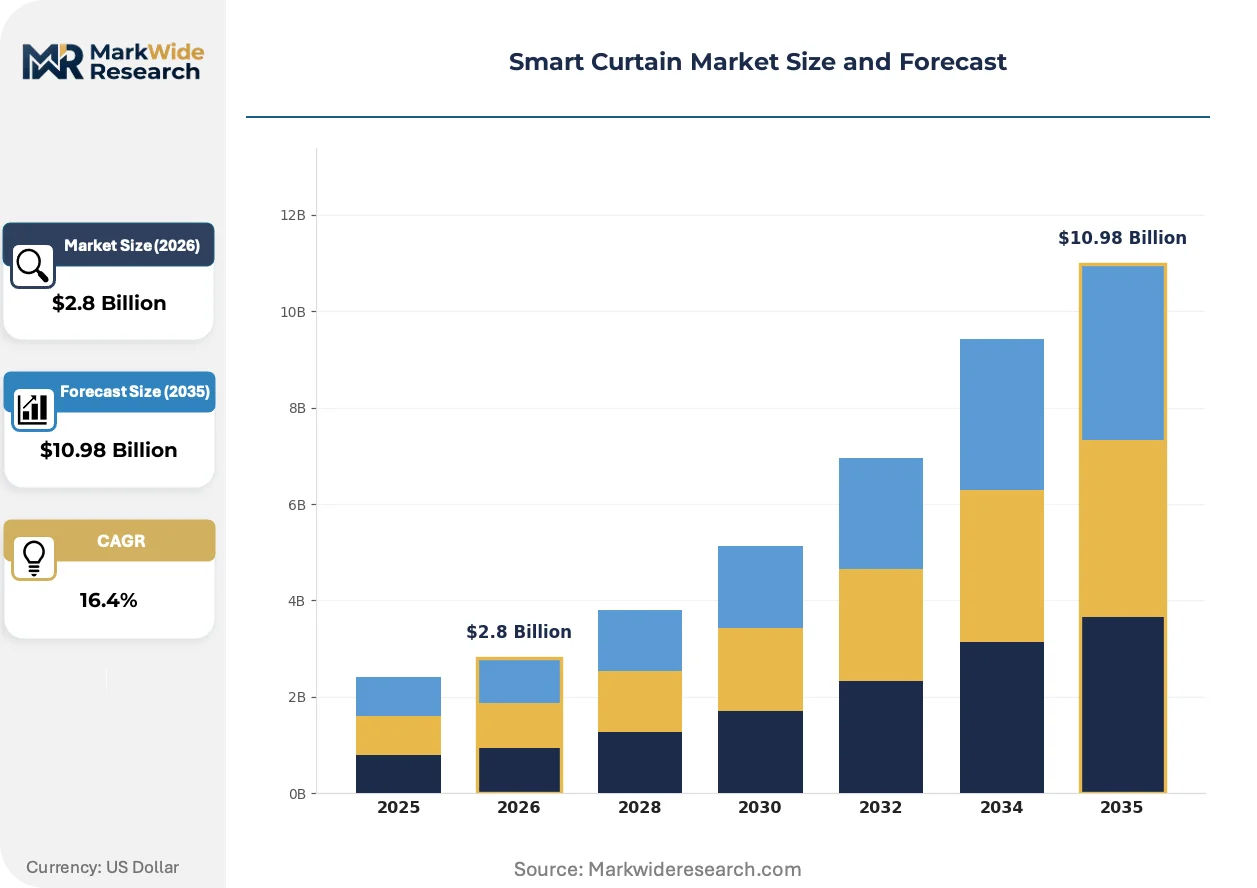
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Curtains, Automated Blinds, Smart Shades, Touch-Controlled Curtains Technology: Wi-Fi, Zigbee, Bluetooth, Infrared End User: Residential, Commercial, Hospitality, Healthcare Installation Type: Wall-Mounted, Ceiling-Mounted, Window Frame, Portable |
| Companies Covered | Somfy, Lutron Electronics, Hunter Douglas, Silent Gliss, Dooya, Xiaomi, SwitchBot, IKEA, ShadeCraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Curtain Market Trends and Innovations
Wireless connectivity architectures and sensor fusion capabilities are splitting the product landscape into two distinct performance tiers, with implications for pricing power and channel strategy across buyer segments.
Sensor-integrated drive mechanisms are bifurcating the installed base. Light-level and temperature-responsive motors now automate positioning without cloud dependency, appealing to hospitality operators with stringent data governance requirements. Premium hotel chains specify these edge-computing variants for guest room retrofits, compressing demand for cloud-dependent alternatives that require persistent internet connectivity and subscription revenue models.
REACH restrictions on halogenated flame retardants are accelerating fabric chemistry transitions. ECHA's substance evaluation process has delisted several legacy compounds used in blackout linings, forcing textile mills to validate phosphorus-based alternatives through extended burn-testing protocols. German commercial developers now require REACH-compliant material declarations as standard specification documents, shifting procurement preference toward vertically integrated manufacturers with captive textile operations.
Specification authority is migrating from interior designers to building automation consultants. Large-format commercial projects now route shading decisions through controls integrators who prioritize BACnet compatibility and API documentation over aesthetic samples. This channel rotation is most visible in North American Class A office developments, where LEED certification requirements and utility incentive programs have elevated energy performance metrics above traditional design criteria in vendor selection processes.
Smart Curtain Market Segmentation
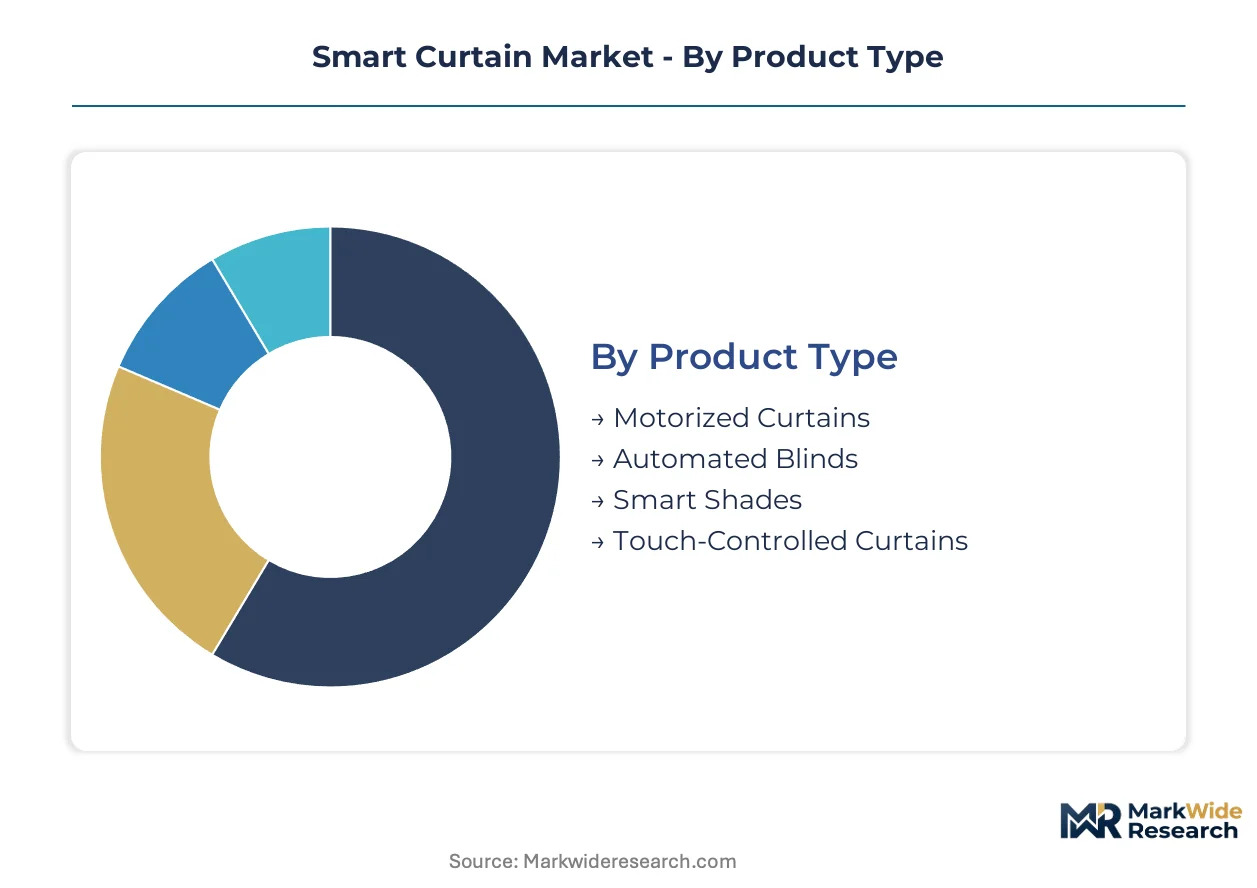
Segmentation in smart curtains reveals how hardware specifications, connectivity protocols, and installation constraints fragment addressable demand across price tiers and buyer sophistication levels. Manufacturers must align R&D roadmaps with the divergent reliability, aesthetic, and integration requirements of residential retrofits versus commercial new construction.
Product Type:
Motorized curtains command the deepest margin pools due to established supply chains and retrofit-friendly installation economics, while smart shades capture premium pricing through tighter building automation integration.
- Motorized Curtains:Track-based systems with DC motor drives (0.5–3 Nm torque ratings) and rail-mounted carriers handle fabric weights up to 15 kg across spans exceeding 10 meters. Hospitality operators in Germany specify these for guest room retrofits where centralized energy management and housekeeping labor reduction justify hardware investment.
- Smart Shades:Roller and honeycomb configurations with integrated light sensors and edge-computing positioning algorithms operate without persistent cloud connectivity. Premium hotel chains with stringent data governance requirements are rotating specifications toward these sensor-integrated variants, compressing demand for subscription-dependent alternatives.
- Automated Blinds:Slatted systems with tilt and lift automation serve residential retrofits where cost sensitivity limits full curtain replacement.
- Touch-Controlled Curtains:Capacitive panel interfaces bypass smartphone dependency for elderly users and accessibility-focused installations.
Motorized curtains hold installed capacity. Smart shades are rotating up the share rankings.
Technology:
Protocol selection fractures along residential-commercial lines, with mesh architectures commanding specification authority in multi-unit deployments where gateway consolidation outweighs standalone simplicity.
- Wi-Fi:Direct router connectivity enables smartphone-native setup without dedicated hubs, dominating North American residential penetration where consumer-grade simplicity drives purchase decisions.
- Zigbee:Mesh network topology with self-healing node redundancy achieves 99.9% uptime in commercial buildings spanning 50,000+ square meters. BACnet compatibility and API documentation now dominate vendor selection in Class A office developments where LEED certification requirements elevate energy performance metrics above aesthetic criteria.
- Bluetooth:Low-energy beacon integration supports proximity-based automation for single-room deployments with limited IT infrastructure.
- Infrared:Line-of-sight control persists in legacy hospitality installations where replacement cycles lag technology refresh timelines.
Wi-Fi commands residential volume concentration. Zigbee is climbing the fastest through commercial specification channels.
End User:
Buyer archetypes diverge sharply on integration depth, with hospitality and healthcare demanding edge-computing autonomy while residential segments prioritize standalone affordability.
- Hospitality:Centralized property management system integration enables portfolio-wide energy optimization and guest experience standardization across 500+ room counts. Hotel chains retrofitting manual treatments cite operational efficiency targets and guest differentiation as joint investment drivers.
- Commercial:Building automation consultants now route shading decisions through controls integrators who prioritize daylight harvesting algorithms and utility-backed demand response program eligibility.
- Residential:Price sensitivity limits penetration to premium retrofits and new construction above median home values.
- Healthcare:Patient room applications require HIPAA-aligned data handling and infection-control compatible surface materials.
Commercial holds specification authority concentration. Hospitality is gaining share fastest through retrofit cycle acceleration.
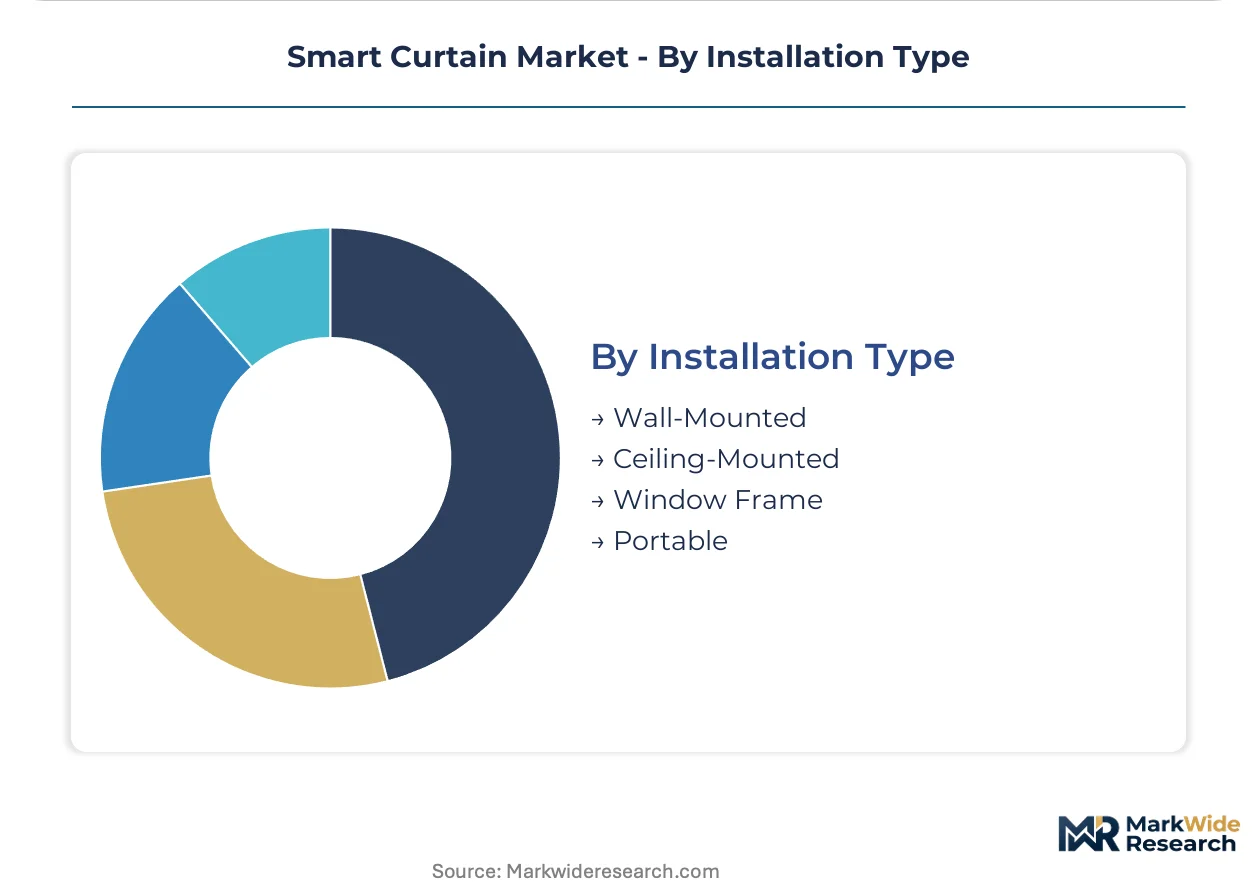
Installation Type:
Mounting geometry determines labor economics and retrofit feasibility, with wall and ceiling configurations dominating new construction while portable alternatives address rental market constraints.
- Wall-Mounted:Bracket systems affixed to vertical surfaces above window openings support the heaviest fabric loads and longest track spans. German commercial real estate developers prioritize these for smart building certification compliance where automated shading integration is mandatory.
- Ceiling-Mounted:Recessed track housings preserve clean sightlines in luxury interior portfolios where Hunter Douglas competes on design-forward automation integration.
- Window Frame:Integrated headrail systems reduce installed depth for shallow European window reveals common in historic building retrofits.
- Portable:Battery-powered units with suction or clamp mounting serve rental markets and temporary installations where permanent modification is prohibited.
Wall-mounted retains the largest installed base. Ceiling-mounted is expanding most quickly through premium commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution networks for motorized shading components. Frankfurt's air cargo hub connects East Asian motor suppliers to German assembly plants. Dubai's Jebel Ali port anchors Middle Eastern re-export corridors for hospitality retrofit projects.
Germany
Commercial real estate developers in Frankfurt and Munich prioritize smart building certifications that mandate automated shading integration. The EU Green Deal's building efficiency directives compress specification timelines for new construction projects. Bavaria's manufacturing corridor hosts precision motor suppliers serving Somfy's European assembly operations.
United States
Class A office developments in Manhattan and Chicago route shading decisions through building automation consultants seeking BACnet compatibility. FCC certification requirements for wireless transmission modules create 4-6 month product launch delays for new entrants. California's Title 24 energy codes accelerate daylight harvesting system specifications in commercial retrofits.
China
Dual carbon goals drive municipal procurement of energy-efficient building envelopes in Shanghai and Shenzhen. MIIT standards for smart home interoperability shape domestic product development roadmaps. Zhejiang province's motor manufacturing clusters supply torque-rated DC drives to global assemblers.
India
The Smart Cities Mission creates specification channels for BIS-certified motorized shading in urban redevelopment zones. Central Electricity Authority building codes increasingly reference automated daylight control for commercial efficiency compliance. Maharashtra's Mumbai-Pune corridor concentrates hospitality development driving guest room retrofit demand.
United Arab Emirates
Hospitality operators in Dubai retrofit guest rooms with automated shading to reduce cooling loads and differentiate guest experience. Emirates Authority for Standardization and Metrology (ESMA) regulations govern electrical safety for imported building automation components. Jebel Ali's free zone warehousing supports rapid deployment across Gulf Cooperation Council hotel portfolios.
Smart Curtain Market Competitive Landscape
Listed leaders compete with private specialists across distribution architecture and specification channel depth. The vendor base organizes into three tiers: European incumbents with captive textile operations, Asian scale manufacturers leveraging motor supply proximity, and venture-backed entrants targeting direct-to-consumer bypass. Consolidation pressure concentrates among mid-cap fabricators lacking vertical integration into drive mechanism production. Dominant competitive moves include strategic partnerships with building automation integrators and geographic expansion through hospitality specification channels.
Within the European incumbent tier, Somfy and Hunter Douglas exemplify archetypes differentiated by distribution control versus design-forward positioning. Somfy anchors specification authority through deep relationships with architectural firms and controls integrators across commercial and hospitality segments. Hunter Douglas occupies a position emphasizing aesthetic integration with luxury interior portfolios, competing on visual samples rather than technical documentation. Among Asian scale manufacturers, Dooya represents the motor-supply-proximity archetype, leveraging Zhejiang province's component ecosystem for cost positioning in volume-driven residential retrofits.
| Leading Market Players |
|---|
| Somfy |
| Lutron Electronics |
| Hunter Douglas |
| Silent Gliss |
| Dooya |
| Xiaomi |
| SwitchBot |
| IKEA |
| ShadeCraft |
| Others |
Pricing and Supply Chain Analysis
Phosphorus-based flame retardant substitution for delisted halogenated compounds simultaneously shifts textile sourcing toward REACH-certified European mills and compresses margin structures for manufacturers dependent on Asian fabric streams. This chemistry migration redistributes cost premiums across the value chain while German commercial developers mandate certified material declarations as baseline specification documents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Premium tiers capture BACnet-compatible systems with edge-computing autonomy specified by hospitality operators, while economy segments face cost compression from cordless spring-loaded alternatives. Price differentiation hinges on REACH compliance documentation and torque-rated motor performance tiers. Residential retrofits exhibit highest price sensitivity, whereas commercial new construction absorbs premium positioning for smart building certification compliance.
Supply Chain Analysis
Strait of Malacca transit routes anchor East Asian component flows to European assembly plants, with Zhejiang province motor clusters and Guangdong textile hubs feeding global production networks. Torque-rated DC drives, wireless communication modules, and sensor-integrated fabrics constitute critical input categories. Single-source vulnerability concentrates in precision motor manufacturing, exposing assemblers to freight cost volatility and extended lead times. Distribution runs through building automation consultants and direct-to-developer channels that bypass traditional window treatment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality retrofit cycles position this market in early recovery phase, with hotel chain capital expenditure normalization driving specification volume acceleration across property portfolios.
For Market Incumbents: Consolidate specification authority through captive textile operations that guarantee REACH-compliant material streams, insulating margin structures from chemistry transition costs. Deepen backward integration into torque-rated motor production to reduce East Asian supply concentration exposure. Prioritize BACnet certification investment to defend channel position against controls integrators elevating technical documentation over aesthetic samples.
For New Entrants and Emerging Players: BIS certification fast-track for India's Smart Cities Mission tenders creates first-mover specification advantages in municipal procurement channels. Target healthcare patient room applications requiring HIPAA-aligned data handling and infection-control surface materials. Pursue direct-to-developer sales models that capture margin from commercial general contractors bypassing traditional distribution.
For Investors and Strategic Acquirers: The market sits at a retrofit-acceleration phase that favors vertically integrated specialists with captive motor and textile operations. Five-to-ten year viability hinges on regulatory alignment across FCC, CE, and BIS emission regimes that currently fragment production scale. Monitor EU Green Deal building efficiency mandate enforcement intensity as the primary inflection signal for specification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Certification | European textile mills with validated phosphorus-based alternatives capture German commercial specification authority. |
| Direct-to-Developer Channel Establishment | Bypassing traditional distributors captures margin and reduces channel conflict in commercial new construction. |
| Sensor-Integrated Edge Computing Development | Cloud-independent positioning algorithms satisfy hospitality data governance requirements without subscription dependency. |
| Zigbee Mesh Network Specialization | Self-healing node redundancy achieves specification dominance in Class A office developments exceeding 50,000 square meters. |
| BIS Certification Investment for India | Municipal procurement tender qualification creates first-mover advantages in urban redevelopment zones. |
Research Methodology
Cross-validation between primary interviews with building automation consultants, controls integrators, textile procurement managers, and hospitality operations executives anchors the qualitative findings. Secondary validation draws from EU Green Deal implementation tracking, FCC equipment authorization databases, BIS certification registries, and commercial real estate development pipeline data. Bottom-up segment sizing triangulates against top-down market boundary analysis.
Sensitivity analysis frames the projection horizon across product type, connectivity protocol, end-user archetype, and installation geometry dimensions. CAGRs derive from segment-level growth rate reconciliation with macro building construction indicators and regulatory compliance timeline assumptions. Forecast inputs incorporate hospitality retrofit cycle intensity, REACH substance evaluation progression, and mesh network adoption curves in commercial deployments.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and hospitality capital expenditure normalization assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as electromagnetic emission limit harmonization negotiations and flame retardant chemistry validation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Frame for Painting Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Flush Door Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Digital Printed Wallpaper Market