
 India Shower Cubicle Market | 2026-2036
India Shower Cubicle Market Size, Share, and Industry Trends Forecast 2026-2036
India Shower Cubicle Market Foresight
Tempered glass is broadening its share against acrylic and PVC alternatives in mid-to-premium shower cubicle lines due to superior scratch resistance and optical clarity. Jaquar leverages its integrated manufacturing at its Manesar facility to control cost and quality across the value chain. HSIL sustains dominant brand recognition in tier-two and tier-three cities through its extensive dealer network. Kohler differentiates via imported hardware systems and premium positioning in metropolitan showrooms.
A shower cubicle is a self-contained bathing enclosure fabricated from tempered safety glass, acrylic, or PVC panels mounted on aluminum or stainless-steel framing, designed to prevent water egress and provide thermal insulation in residential and commercial bathrooms. Frameless configurations command higher margin pools due to specialized hardware and precision glass edge-polishing requirements, while framed variants occupy volume leadership across mass-market residential projects. The hospitality end-user segment represents the fastest-growing demand channel as hotel chains renovate properties and specify walk-in enclosures.
BIS mandates IS 2553 certification for tempered glass used in bathroom applications, compelling manufacturers to upgrade testing protocols and supplier qualification processes. The Indian Green Building Council's water-efficiency ratings for residential developments are steering specification toward enclosed shower systems that reduce splash loss and heating loads. Stakeholders must monitor evolving state-level real estate regulations and municipal plumbing codes that increasingly mandate leak-proof bathroom assemblies in new construction.
Market Dynamics
Real estate premiumization across Maharashtra and Karnataka is compressing specification cycles for bathroom fixtures, as developers compete on amenity density rather than unit count alone. This structural pull is forcing upstream glass fabricators and hardware importers to synchronize production with construction timelines that now average fourteen months from foundation to possession.
Growth Catalysts
- Indian Green Building Council water-efficiency ratings:Enclosed shower systems earn credits that improve project certification tiers, steering developer specification toward cubicle assemblies that reduce splash loss and heating loads in high-rise residential towers.
- Hospitality renovation wave:Hotel chains across Mumbai, Bangalore, and Goa are replacing bathtub configurations with walk-in enclosures to maximize usable floor area and reduce housekeeping labor per room turnover.
- BIS IS 2553 tempered glass mandate:Compulsory certification for bathroom safety glass is filtering out unorganized fabricators, consolidating volume with qualified suppliers capable of sustaining testing protocols and traceable batch records.
Market Restraints
- Float glass import dependency:Domestic production of optical-grade tempered substrate remains insufficient, exposing fabricators to freight cost volatility and currency fluctuation on shipments from Southeast Asian float lines.
- Hardware concentration in European suppliers:Premium frameless systems rely on hinge and channel mechanisms sourced from Germany and Italy, creating lead time fragility and margin pressure during euro appreciation cycles.
- Acrylic substitution in mass housing:Budget residential projects below fifteen lakh rupees per unit increasingly specify polymer panels that sacrifice optical clarity for forty percent lower installed cost.
Strategic Opportunities
- Tier-three city underpenetration:Cities such as Indore, Kochi, and Chandigarh exhibit shower cubicle penetration below eight percent of bathroom renovations, presenting first-mover advantage for organized brands with dealer financing programs.
- PLI scheme for specialty glass:Production-linked incentives for value-added glass manufacturing could attract capital expenditure toward domestic tempering and edge-polishing capacity, reducing import exposure.
- Smart bathroom convergence:Integration of digital shower controls, anti-fog mirror systems, and chromotherapy lighting into enclosure frames is creating bundled specification opportunities with home automation integrators.
Industry Challenges
- Skilled installation technician shortage:Precision frameless assembly demands certified glaziers capable of silicon-free sealing and structural load calculations, a workforce segment concentrated in Mumbai and Bangalore with limited migration to emerging markets.
- BIS certification timeline compression:Laboratory queue congestion for IS 2553 testing extends product launch cycles by four to six months, delaying revenue recognition for new SKU introductions.
- Project finance contagion:Developer liquidity stress in the National Capital Region and Pune is stretching payment cycles to ninety days, forcing fabricators to absorb working capital costs or sacrifice margin for cash flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Shower Cubicle Market |
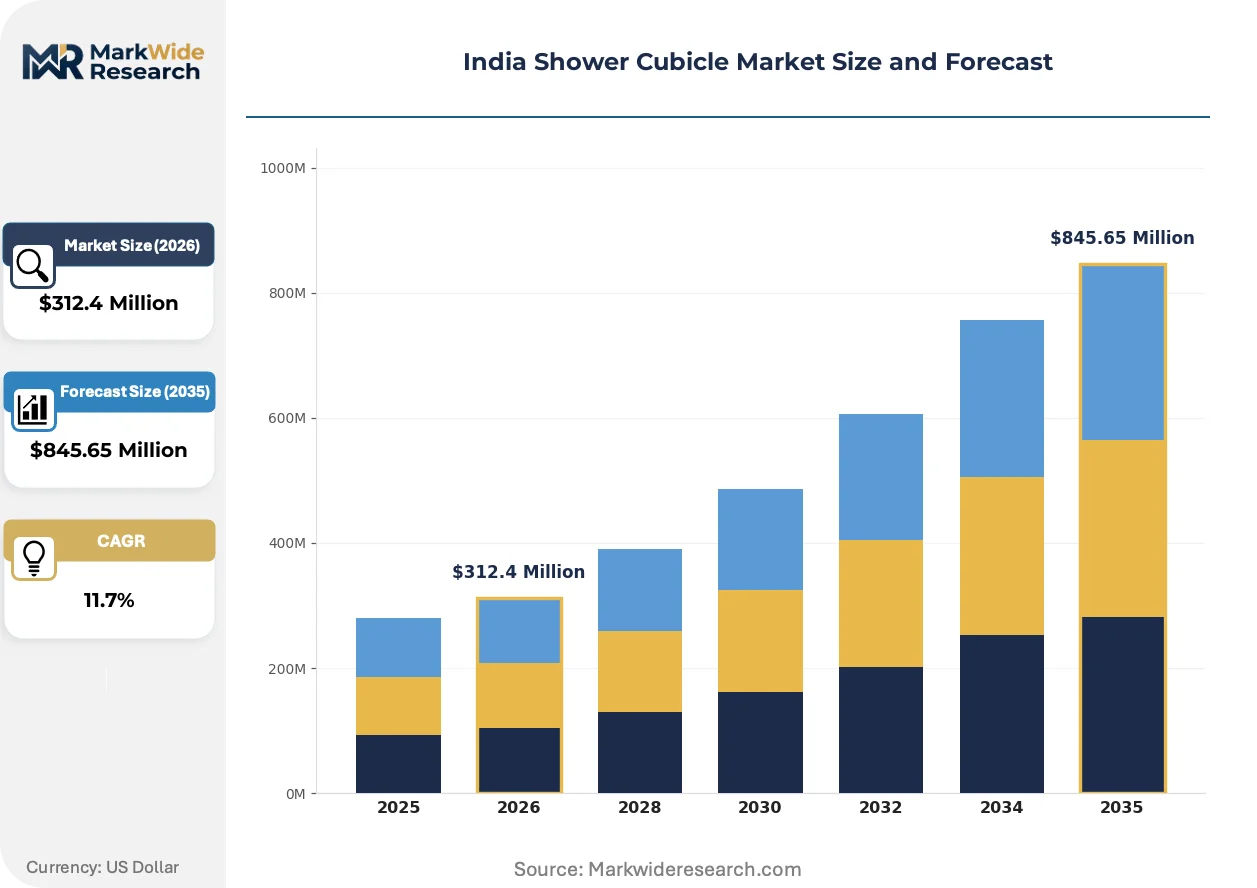
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Framed, Frameless, Bi-fold, Quadrant Material: Glass, Acrylic, PVC, Aluminum Design Style: Modern, Traditional, Minimalist, Rustic End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Parryware, Hindustan Sanitaryware & Industries (HSIL), Jaquar, Dornbracht India, H & R Johnson, Kohler, Cera Sanitaryware Limited, TOTO Sanitary India, Saint Gobain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Shower Cubicle Market Shifts & Advancements
Shower enclosure specification is fragmenting into three distinct technical trajectories: structural minimalism, regulatory compliance automation, and procurement channel digitization. Each trajectory is compressing legacy supply relationships and forcing capability investments at different tiers of the value chain.
Ultra-clear low-iron glass is unifying premium segment specification by eliminating the green tint inherent in standard float substrates, enabling frameless designs that maximize visual spaciousness in compact urban bathrooms. Luxury residential developers in Mumbai's Worli and Lower Parel corridors specify this material in eighty percent of master bathroom configurations. The technology is unifying hardware and glass sourcing decisions under single-source fabricators capable of precision edge polishing and hole drilling.
BIS has tightened IS 2553 enforcement protocols for tempered glass fragmentation patterns and surface compression stress, compelling manufacturers to upgrade furnace calibration and implement automated optical inspection. Fabricators without in-house testing laboratories now face third-party certification costs exceeding twelve percent of material value. The regulatory pressure concentrates most acutely on mid-tier suppliers serving Delhi-NCR and Hyderabad markets, where municipal plumbing inspectors are cross-referencing batch certificates against installation permits.
Builder procurement teams are consolidating vendor panels and demanding integrated bathroom packages that combine sanitaryware, faucets, and enclosures under single project contracts. This specification bundling displaces the historical model of architect-directed fragmentation across specialized suppliers. The behavioral shift is most visible in Bangalore's Whitefield and Electronic City corridors, where technology campus residential towers specify turnkey bathroom modules fabricated off-site and craned into structural shells.
India Shower Cubicle Market Segmentation
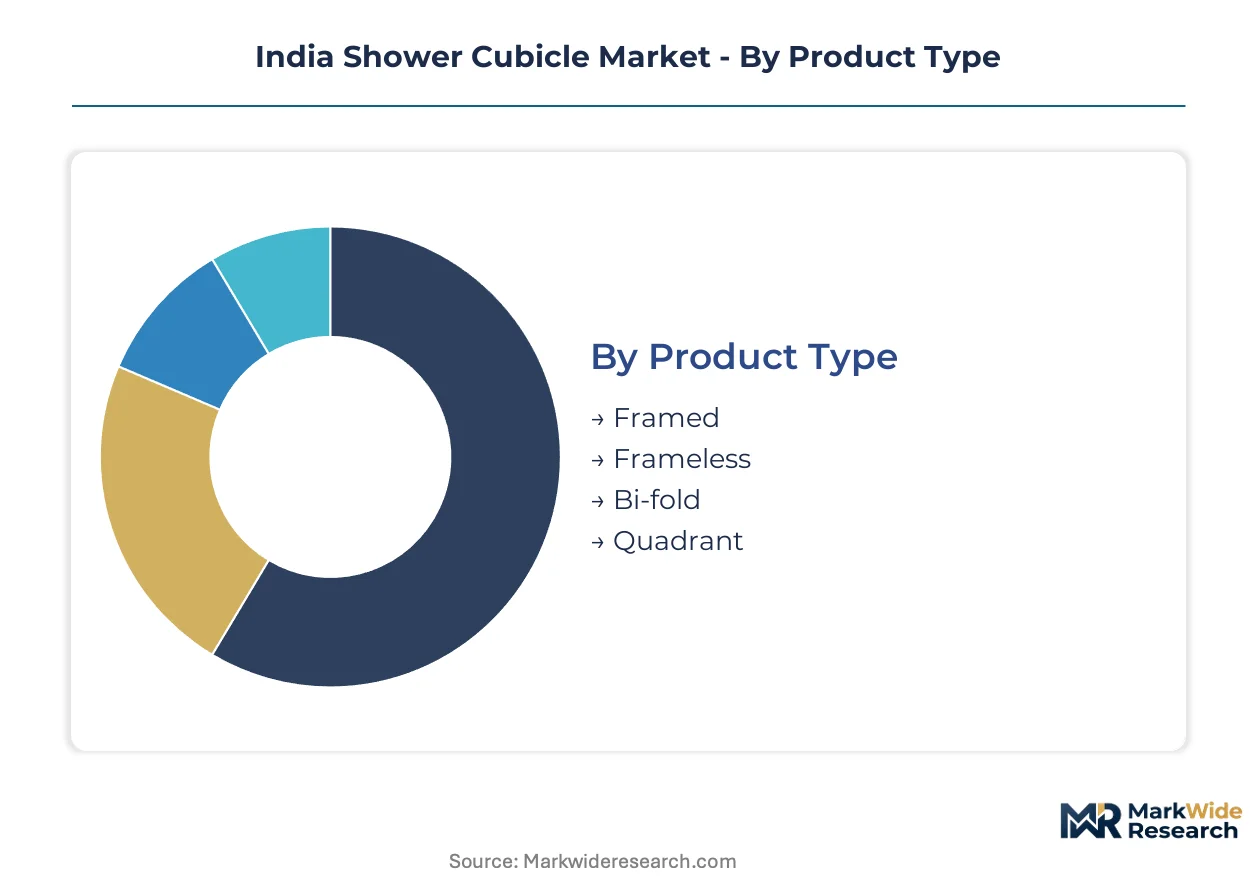
Shower cubicle specification in India fragments across technical configuration, substrate material, aesthetic positioning, and end-use application. Each dimension carries distinct margin profiles, certification requirements, and channel access patterns that determine supplier competitiveness.
Product Type:
Buyers differentiate primarily by installation complexity tolerance and visual weight preferences in compact bathroom footprints.
- Framed:Aluminum or stainless-steel perimeter frames support glass or polymer panels, delivering structural stability at lower installed cost. Mass residential developers in Pune and Chennai specify framed systems for standardized tower bathrooms where repeatability trumps customization. Volume leadership rests here due to forgiving installation tolerances and shorter procurement cycles.
- Frameless:Precision-edge tempered glass panels mount via drilled holes and specialized hardware, eliminating visual obstruction. Luxury residential towers in Mumbai's BKC corridor and Bangalore's Koramangala cluster specify these for master bathrooms where spatial perception commands premium pricing. Hardware sourcing from European suppliers extends lead times and concentrates margin pools with qualified fabricators.
- Bi-fold:Hinged folding panels retract against wall planes, optimizing clearance in narrow bathroom layouts common in Mumbai's older residential stock.
- Quadrant:Curved front profiles maximize enclosed floor area within corner installations, preferred for secondary bathrooms in mid-tier apartment configurations.
Volume sits with Framed; growth tilts toward Frameless.
Material:
Substrate selection hinges on optical clarity requirements, impact resistance specifications, and BIS compliance pathways.
- Glass:Tempered safety glass meeting IS 2553 fragmentation standards dominates premium specification. Maharashtra and Karnataka developers increasingly mandate low-iron ultra-clear variants for frameless master bathroom installations. BIS laboratory queue congestion filters supply toward fabricators with captive testing capabilities.
- Acrylic:Thermoformed polymer panels deliver forty percent lower installed cost with superior impact resistance, capturing budget residential projects in tier-three cities where optical clarity is secondary to durability.
- PVC:Extruded polymer systems serve temporary or rental housing applications with lowest capital outlay and rapid replacement cycles.
- Aluminum:Framing substrate for hybrid configurations, with domestic extrusion capacity concentrated in Gujarat and Rajasthan reducing freight exposure for northern markets.
Glass commands premium positioning; Acrylic captures volume expansion in emerging cities.
Design Style:
Aesthetic specification tracks developer brand positioning and architect design language rather than functional differentiation.
- Modern:Clean lines, matte black or brushed nickel hardware, and clear glass dominate technology campus residential towers in Bangalore's Whitefield corridor. Specifications bundle with smart bathroom systems and home automation integration.
- Minimalist:Concealed hardware and frameless configurations maximize visual spaciousness in Mumbai's compact luxury apartments where every square foot commands measurable price premium.
- Traditional:Ornate framing profiles and patterned glass serve heritage hotel renovations in Rajasthan and Kerala where architectural continuity overrides contemporary trends.
- Rustic:Industrial metal finishes and textured glass appeal to boutique hospitality properties in Goa and Himachal Pradesh targeting experience-driven travelers.
Modern and Minimalist specifications are expanding most quickly; Traditional retains niche hospitality presence.
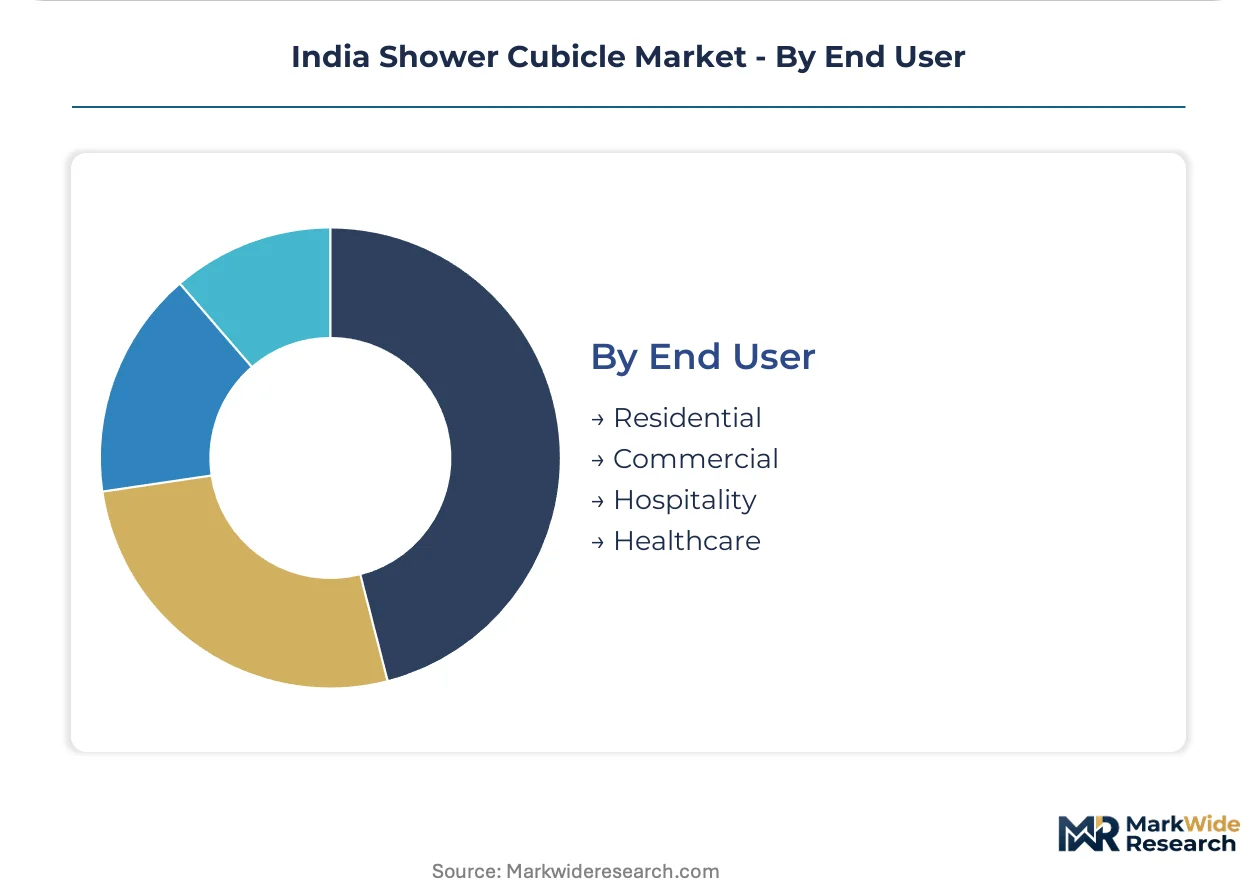
End User:
Procurement behavior diverges sharply between project-based volume buyers and fragmented retail replacement demand.
- Residential:Apartment developers specify standardized configurations across tower inventories, with payment terms stretching to ninety days during liquidity stress. Mumbai and Bangalore premium projects drive frameless adoption.
- Hospitality:Hotel chains renovating Mumbai, Bangalore, and Goa properties are replacing bathtubs with walk-in enclosures to reduce housekeeping labor and maximize usable floor area. This segment is climbing the fastest as renovation cycles compress post-pandemic.
- Commercial:Office building washroom fit-outs prioritize durability and vandal resistance over aesthetic differentiation, with acrylic and framed glass dominating specifications.
- Healthcare:Hospitals and eldercare facilities require anti-ligature hardware and accessibility-compliant thresholds, creating specialized fabrication requirements with limited supplier pools.
Residential anchors volume; Hospitality delivers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shower cubicle demand concentrates in Maharashtra and Karnataka, where premium real estate development drives specification of frameless glass enclosures. Developer competition on amenity density compresses procurement cycles to fourteen months from foundation to possession. BIS IS 2553 certification requirements filter supply toward qualified fabricators with captive testing capabilities.
Maharashtra
Mumbai's luxury residential corridors in Worli, Lower Parel, and BKC specify ultra-clear low-iron glass in eighty percent of master bathroom configurations. BIS mandates IS 2553 certification for tempered safety glass, compelling fabricators to upgrade furnace calibration and automated optical inspection. The Thane-Aurangabad industrial belt hosts glass tempering and edge-polishing facilities serving western India markets.
Karnataka
Bangalore's Whitefield and Electronic City technology campus towers demand turnkey bathroom modules with integrated shower enclosures and smart home systems. The Indian Green Building Council's water-efficiency ratings steer developer specification toward enclosed shower systems that reduce splash loss. Mysuru and Hubli-Dharwad emerge as secondary fabrication hubs for southern markets.
Gujarat
Surat and Ahmedabad mass residential projects sustain demand for framed aluminum systems with standardized repeatability across tower inventories. Domestic aluminum extrusion capacity concentrated in Gujarat reduces freight exposure for northern markets. The state's ceramics and sanitaryware cluster supports integrated bathroom package procurement.
Tamil Nadu
Chennai's mid-tier apartment developers specify framed configurations for cost-controlled tower bathrooms with shorter procurement cycles. CDSCO and state municipal plumbing codes increasingly mandate leak-proof bathroom assemblies in new construction. Coimbatore's engineering base supplies hardware components to regional fabricators.
Delhi-NCR
Gurugram and Noida premium projects face stretched payment cycles to ninety days during developer liquidity stress, forcing fabricators to absorb working capital costs. BIS laboratory queue congestion for IS 2553 testing extends product launch cycles by four to six months. Faridabad hosts assembly operations serving the northern corridor.
India Shower Cubicle Market Competitive Landscape
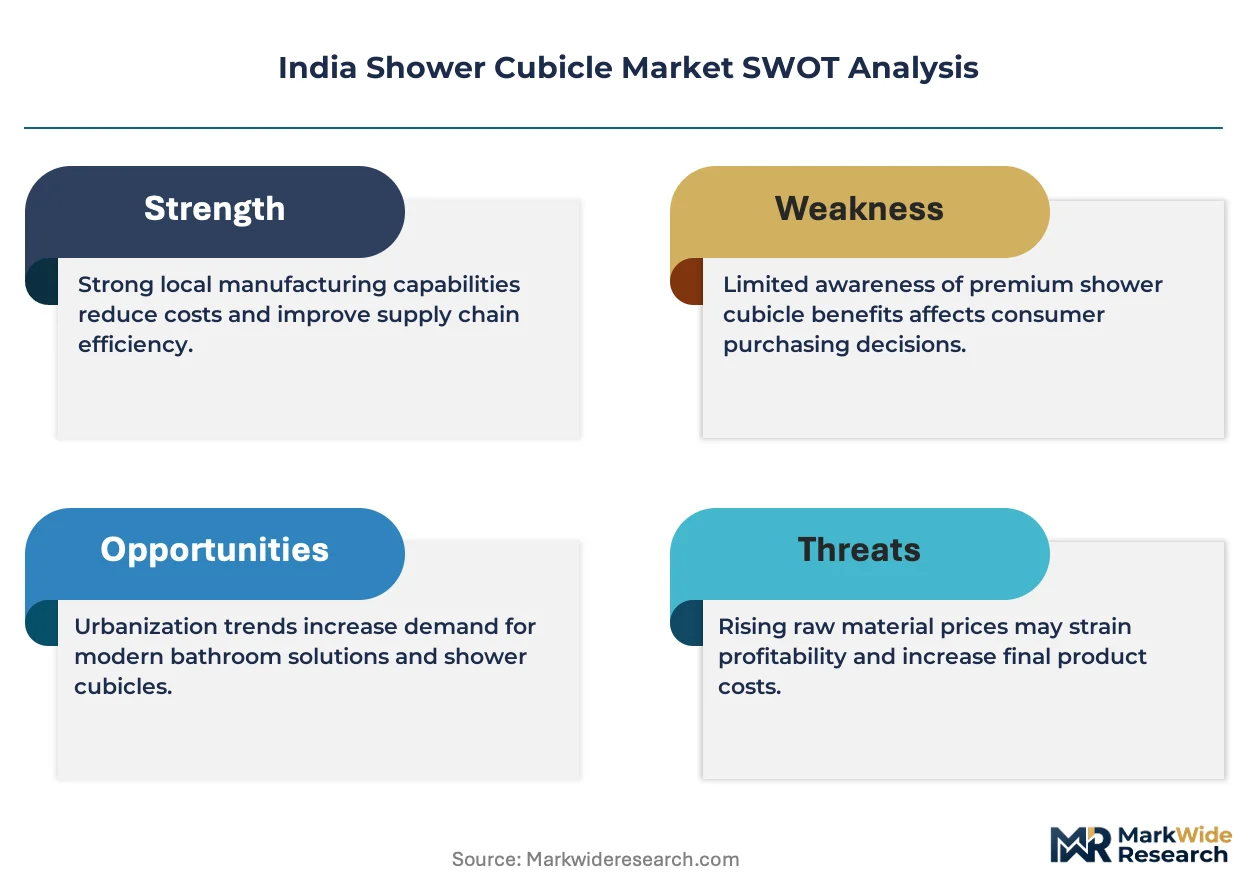
Branded specialists and contract manufacturers split share differently across segments, with organized players consolidating volume in premium metropolitan markets while regional fabricators serve mass housing. The vendor base exhibits tiered concentration: integrated manufacturers with captive glass tempering, import-dependent specialists sourcing European hardware, and unorganized local fabricators competing on installed cost. Three archetypes dominate: scale-driven integrated producers, design-forward premium importers, and price-competitive regional assemblers. Competitive moves center on backward integration into glass tempering capacity and strategic partnerships with real estate developers for project-level bundling.
Among India-based integrated manufacturers, Jaquar and HSIL exemplify contrasting positioning archetypes. Jaquar leverages its Manesar manufacturing facility to control cost and quality across the value chain, representing the backward-integrated specialist model. HSIL sustains dominant brand recognition through extensive dealer networks penetrating tier-two and tier-three cities, occupying the distribution-depth archetype. Kohler India, as an import-dependent premium player, anchors the design-forward positioning through metropolitan showroom presence and European hardware sourcing. These three collectively illustrate the strategic segmentation defining competitive dynamics.
| Leading Market Players |
|---|
| Parryware |
| Hindustan Sanitaryware & Industries (HSIL) |
| Jaquar |
| Dornbracht India |
| H & R Johnson |
| Kohler |
| Cera Sanitaryware Limited |
| TOTO Sanitary India |
| Saint Gobain |
| Others |
Supply & Pricing Matrix
Float glass price volatility from Southeast Asian suppliers cascades through Indian fabrication tiers, compressing margins on frameless enclosures while pushing mass-market framed systems toward acrylic substitution. BIS IS 2553 certification costs and euro-denominated hardware imports amplify pricing stratification between premium glass specialists and regional assemblers.
Pricing Analysis
Volume leadership sits with framed aluminum systems capturing mass residential projects, while frameless configurations command superior margin pools through specialized hardware and precision edge-polishing requirements. Price differentiation hinges on BIS certification tier and European hardware sourcing, with premium fabricators absorbing euro appreciation cycles through project bundling. Cost compression in the mid-tier intensifies as acrylic panels undercut tempered glass by forty percent on installed cost. Budget residential developers below fifteen lakh rupees per unit exhibit highest price sensitivity; luxury Mumbai developers show lowest sensitivity due to amenity-density competition.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale residential tower demand, while dealer networks penetrate tier-two and tier-three renovation markets. Raw material supply concentrates in China, Thailand, and Indonesia for float glass substrate, with domestic tempering capacity clustered in Maharashtra and Karnataka. The chain draws from German and Italian hinge mechanisms for frameless systems, creating single-source vulnerability during euro volatility. Distribution runs through project-level bundling with sanitaryware suppliers, consolidating procurement decisions under builder vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around BIS-compliant fabricators as certification costs and testing queue congestion filter out unorganized competitors. Weak players without captive tempering capacity or dealer financing programs face exit pressure.
For Market Incumbents: Acquire captive glass tempering furnaces in the Thane-Aurangabad belt to insulate margin from float glass import volatility and BIS testing delays. Strengthen project-level bundling partnerships with Maharashtra and Karnataka developers before hardware shortages from European suppliers intensify. The threat of acrylic substitution in mass housing demands defensive certification investment to maintain specification access. For New Entrants and Emerging Players: Enter via dealer financing programs in Indore, Kochi, and Chandigarh where shower cubicle penetration sits below eight percent of bathroom renovations. Target hospitality renovation cycles in Goa and Bangalore as hotel chains replace bathtubs with walk-in enclosures. The most penetrable segment is tier-three city retail replacement demand served through localized installation technician training. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier fabricators with BIS IS 2553 compliance and established Karnataka or Maharashtra project relationships. Long-term viability centers on backward integration into tempering capacity and smart bathroom convergence capabilities. Watch PLI scheme announcements for specialty glass manufacturing as the inflection signal for domestic supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tempering Capacity | Captive furnace investment insulates margin from Southeast Asian float glass price volatility and BIS testing queue delays. |
| Smart Bathroom Convergence Partnerships | Integration with home automation integrators in Bangalore's Whitefield corridor creates bundled specification pull-through. |
| Dealer Financing Program Expansion | Credit access unlocks tier-three city penetration in Indore and Kochi where organized brand presence remains thin. |
| European Hardware Supplier Diversification | Dual-sourcing hinge mechanisms from Italy and Germany reduces euro appreciation exposure on frameless systems. |
| Project-Level Bundling with Developers | Single-contract bathroom packages displace architect-fragmented procurement in Mumbai and Bangalore premium towers. |
Research Methodology
Multi-period observation of real estate construction timelines, BIS certification queue lengths, and hospitality renovation cycles anchored the trend analysis, supplemented by interviews with glass fabricator operations heads, real estate developer procurement managers, sanitaryware distributor principals, municipal plumbing inspectors, and hotel FF&E consultants. Secondary validation drew from BIS notification archives, Indian Green Building Council certification databases, state-level real estate regulatory authority filings, and customs records for float glass imports. Bottom-up project pipeline tracking across Maharashtra, Karnataka, Gujarat, Tamil Nadu, and Delhi-NCR triangulated against top-down manufacturer shipment estimates.
Segment-weighting applied product type, material substrate, design aesthetic, and end-use application dimensions across the projection horizon. CAGRs derived from construction cycle compression analysis, renovation spend patterns, and regulatory mandate implementation timelines. Forecast inputs included PLI scheme uptake trajectories for specialty glass and hospitality sector occupancy recovery curves affecting FF&E replacement budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged euro appreciation or acute float glass supply disruption from Southeast Asian producers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market