
 India Steam Rooms Market | 2026-2036
India Steam Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
India Steam Rooms Market Foresight
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is unwinding competitive stability in the India steam rooms sector. Steam Smith Systems leverages captive metal fabrication to control input costs across its installation network. Kohler sustains premium positioning through imported control systems and established hospitality relationships. Woven Gold India anchors its presence in South Indian commercial projects with localized acrylic sourcing and faster turnaround cycles.
Steam rooms are thermally insulated enclosures equipped with steam generators that maintain temperatures between 43°C and 48°C at near-100% humidity for therapeutic and relaxation purposes. The core system combines a sealed generator vessel, electronic controls, and vapor-tight wall assemblies engineered to prevent moisture intrusion into building structures. Traditional steam rooms dominate current installations due to lower upfront costs and familiar maintenance protocols, while infrared steam rooms capture expanding residential interest where energy efficiency and reduced humidity matter. Spa and wellness centers represent the highest-margin end user segment, though fitness clubs drive volume through standardized repeat specifications.
BIS electrical safety standards and state-level building codes in Maharashtra and Karnataka shape generator certification and installation licensing requirements. The CEA mandates energy efficiency disclosures for commercial heating equipment above specified load thresholds, pushing manufacturers toward inverter-based generator designs. Stakeholders must monitor evolving municipal water quality regulations and the pace of green building certification adoption across Tier-1 and Tier-2 cities.
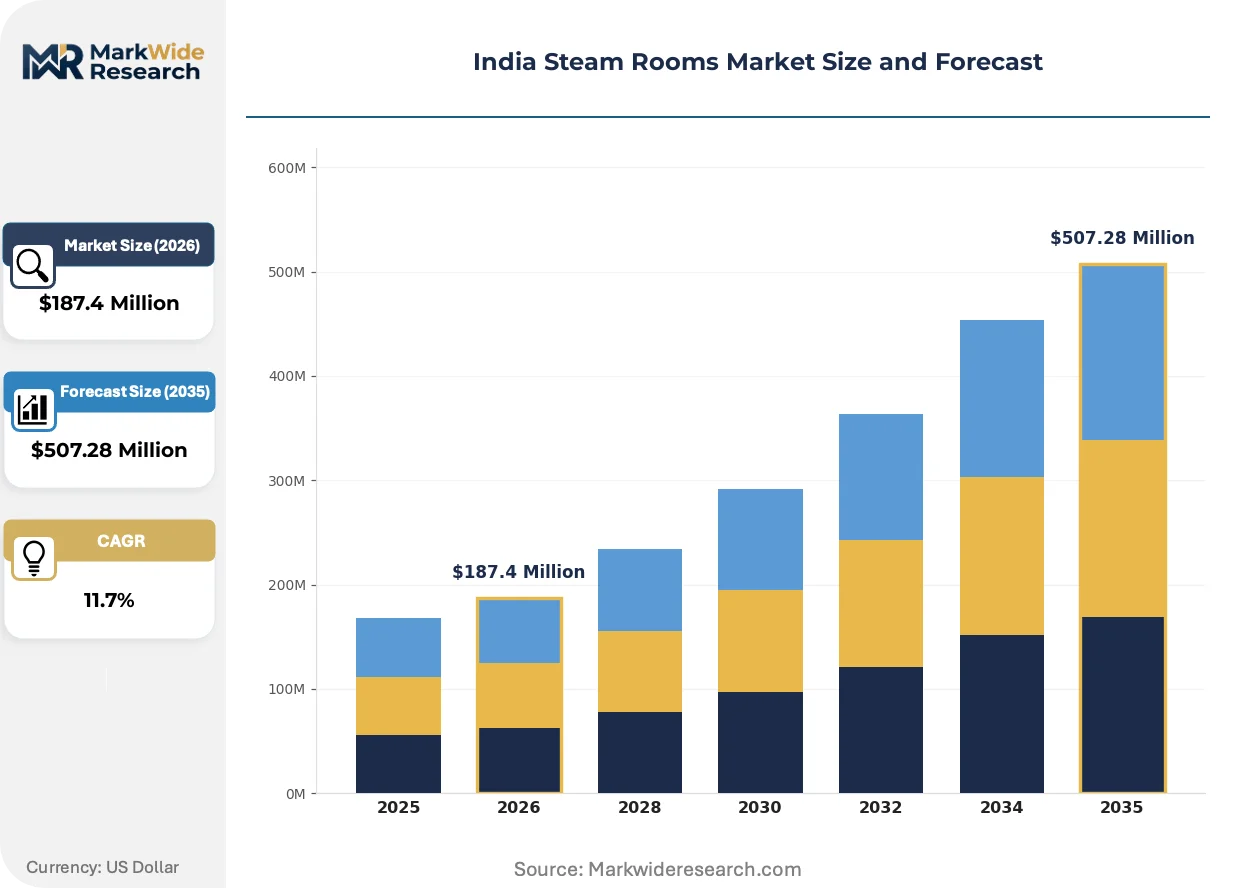
Market Dynamics
BIS certification tightening for electrical heating components is compressing vendor margins while elevating entry barriers, forcing domestic manufacturers toward captive metal fabrication or imported control system partnerships to maintain commercial viability.
Growth Catalysts
- CEA energy efficiency mandates:Commercial heating equipment disclosure requirements above specified load thresholds are accelerating inverter-based generator adoption across Maharashtra and Karnataka fitness club installations.
- Premium residential wellness integration:High-rise developments in Mumbai and Delhi are specifying steam rooms as standard amenities, creating pull-through demand for modular generator systems with faster installation cycles.
- Luxury hospitality expansion:Five-star hotel chains are doubling spa infrastructure investment, specifying vapor-tight wall assemblies with 10-year moisture intrusion warranties.
Market Restraints
- Stainless steel price volatility:Generator vessel fabrication costs fluctuate with nickel alloy input prices, squeezing integrated manufacturers with captive foundry operations.
- Imported control system dependency:Premium positioning requires EU-sourced electronic modules subject to extended lead times and currency exposure.
- Acrylic panel substitution threat:Infrared sauna cabins using ceramic emitters compete for residential wellness budgets with lower humidity maintenance requirements.
Strategic Opportunities
- Tier-2 city green building adoption:Pune and Hyderabad commercial developments are pursuing IGBC certification, creating specification pull for low-energy steam generator systems.
- Medical wellness convergence:Ayurvedic therapy centers are integrating steam protocols for respiratory treatment, opening institutional procurement channels outside hospitality.
- PLI scheme component localization:Domestic heating element manufacturing incentives could reduce import dependency for electronic control modules.
Industry Challenges
- Certified installation technician scarcity:BIS-licensed electrical contractors with vapor-sealing expertise concentrate in Mumbai and Delhi, limiting expansion into secondary markets.
- Legacy building integration complexity:Retrofit projects in aging hospitality properties require structural moisture remediation before generator installation, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Steam Rooms Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Steam Rooms, Infrared Steam Rooms, Portable Steam Rooms, Customized Steam Rooms End User: Residential Users, Spa & Wellness Centers, Fitness Clubs, Hospitality Industry Installation Type: Indoor Installation, Outdoor Installation, Mobile Installation, Permanent Installation Material: Glass, Wood, Acrylic, Fiberglass |
| Companies Covered | Steam Smith Systems, Kohler, Woven Gold India, Orion Bathing Concepts, Omega Bath Solutions, Quantum Solutions India, Hi Tech Bath Solutions, Bath Systems India, Steamers India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Steam Rooms Market Shifts & Advancements
Steam room technology is bifurcating between traditional high-humidity systems and hybrid infrared-steam configurations, with regulatory pressure and buyer sophistication accelerating specification divergence across end-use verticals.
Modular generator architecture is fragmenting the installed base. These systems separate heating vessels from control electronics, enabling field replacement without full unit decommissioning. Boutique fitness chains in Bengaluru are specifying swap-compatible generators to minimize downtime. The technology is fragmenting vendor service revenue models away from preventive maintenance contracts toward component-level replacement schedules.
BIS electrical safety standards are tightening conformance testing for commercial steam generators. Third-party laboratory certification timelines have extended from 8 weeks to 14 weeks, compressing product launch windows for manufacturers. Maharashtra state electrical inspectors are rejecting installations lacking BIS-marked heating elements, forcing hospitality contractors toward pre-certified component sourcing.
Facility managers are unbundling after-sales service from equipment procurement, negotiating direct maintenance contracts with specialized HVAC technicians rather than generator OEMs. This pattern concentrates in Delhi NCR luxury hotel properties where engineering heads prioritize response time over brand-aligned service networks. Independent service providers with BIS electrical licensing are capturing recurring revenue previously retained by equipment suppliers.
India Steam Rooms Market Segmentation
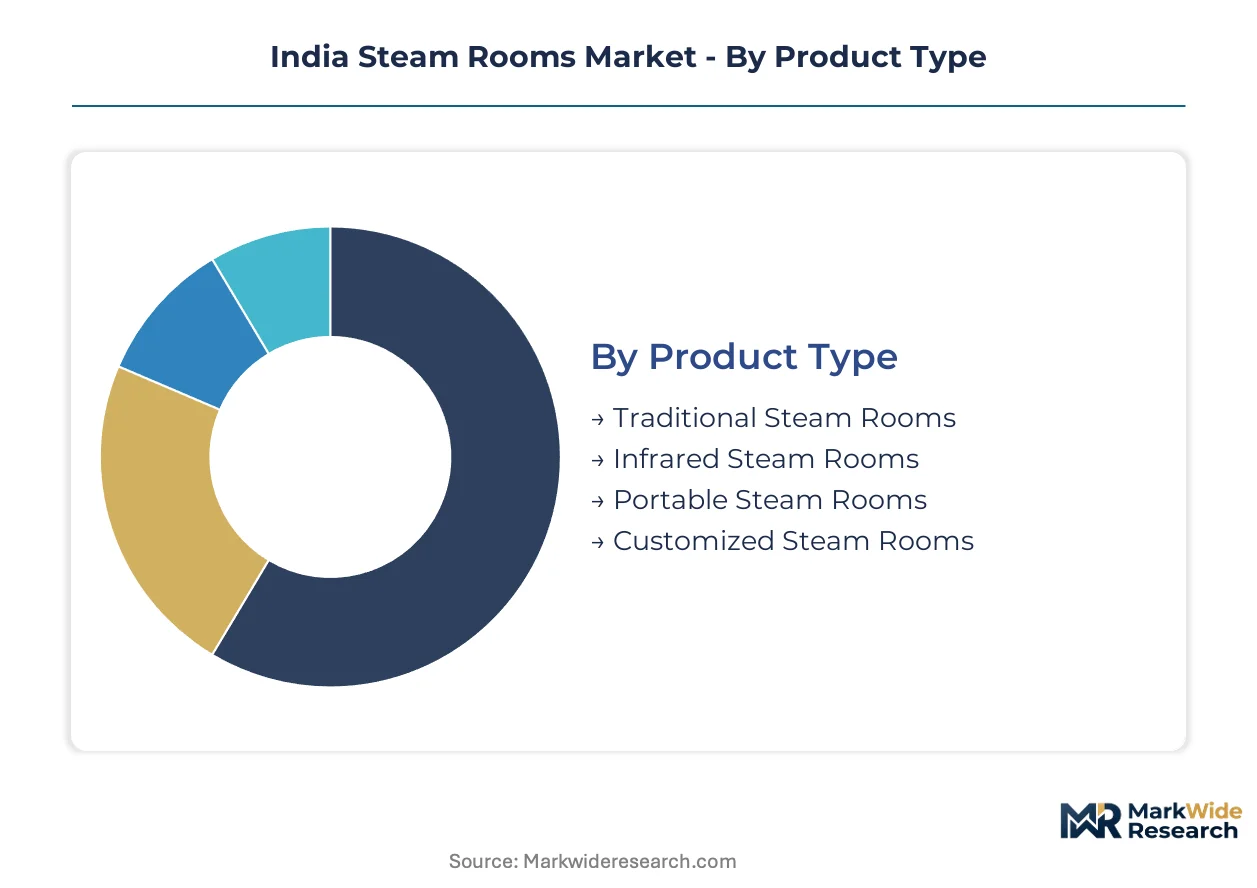
Segmentation in the India steam rooms market reveals how BIS electrical standards and state-level building codes reshape procurement patterns across product tiers and installation environments. Distinct regulatory thresholds separate commercial hospitality specifications from residential wellness integrations.
Product Type:
BIS certification requirements for electrical heating components create divergent compliance burdens across generator architectures, favoring established designs with proven certification pathways while challenging novel configurations.
- Traditional Steam Rooms:These systems utilize sealed generator vessels with resistive heating elements to produce saturated steam at 43-48°C with near-100% humidity. Maharashtra and Karnataka fitness clubs specify these for standardized maintenance protocols and familiar technician training. BIS-marked heating element mandates reinforce their commercial viability against unproven alternatives.
- Infrared Steam Rooms:Hybrid configurations combine ceramic infrared emitters with controlled steam injection, reducing humidity loads while maintaining therapeutic temperatures. Mumbai and Delhi premium residential towers favor these for energy efficiency disclosures under CEA commercial equipment mandates and reduced structural moisture risk.
- Portable Steam Rooms:Modular tent-style enclosures with detachable steam generators serve temporary wellness installations and event hospitality.
- Customized Steam Rooms:Architect-integrated vapor-tight assemblies with bespoke dimensions dominate luxury hotel spa renovations requiring 10-year moisture intrusion warranties.
Established volume favors Traditional Steam Rooms; emerging adoption favors Infrared Steam Rooms.
End User:
Margin concentration varies sharply across customer types, with hospitality procurement commanding premium pricing for warranty-backed installations while fitness clubs drive standardized volume through repeat specifications.
- Residential Users:High-rise developers in Mumbai and Delhi integrate steam rooms as standard wellness amenities, pulling modular generator demand with faster installation cycles. CEA energy efficiency disclosure requirements above specified load thresholds accelerate inverter-based system preference in this segment.
- Spa & Wellness Centers:Ayurvedic therapy centers in Karnataka and Maharashtra are integrating steam protocols for respiratory treatment, opening institutional procurement channels with distinct clinical specifications.
- Fitness Clubs:Boutique chains in Bengaluru specify swap-compatible modular generators to minimize downtime, fragmenting vendor service revenue toward component replacement schedules.
- Hospitality Industry:Five-star hotel chains double spa infrastructure investment, requiring vapor-tight wall assemblies with extended moisture warranties and BIS-certified electrical contractors.
Margin capture concentrates in Spa & Wellness Centers; volume expansion concentrates in Fitness Clubs.
Installation Type:
Project timeline complexity and certified technician availability constrain deployment patterns, with permanent indoor installations dominating current revenue while mobile configurations test regulatory boundaries.
- Indoor Installation:Climate-controlled building envelopes with dedicated HVAC integration dominate Maharashtra and Karnataka commercial developments. BIS-licensed electrical contractors with vapor-sealing expertise concentrate in Mumbai and Delhi, limiting secondary market penetration.
- Outdoor Installation:Weather-resistant generator housings with enhanced insulation address resort and poolside hospitality specifications in coastal Maharashtra.
- Mobile Installation:Trailer-mounted steam units serve event wellness and temporary construction site amenities, facing municipal electrical permitting variability.
- Permanent Installation:Structural integration with 10-year moisture intrusion warranties anchors luxury hospitality procurement, requiring pre-installation structural assessment in aging properties.
Revenue stability favors Permanent Installation; flexibility demand favors Mobile Installation.
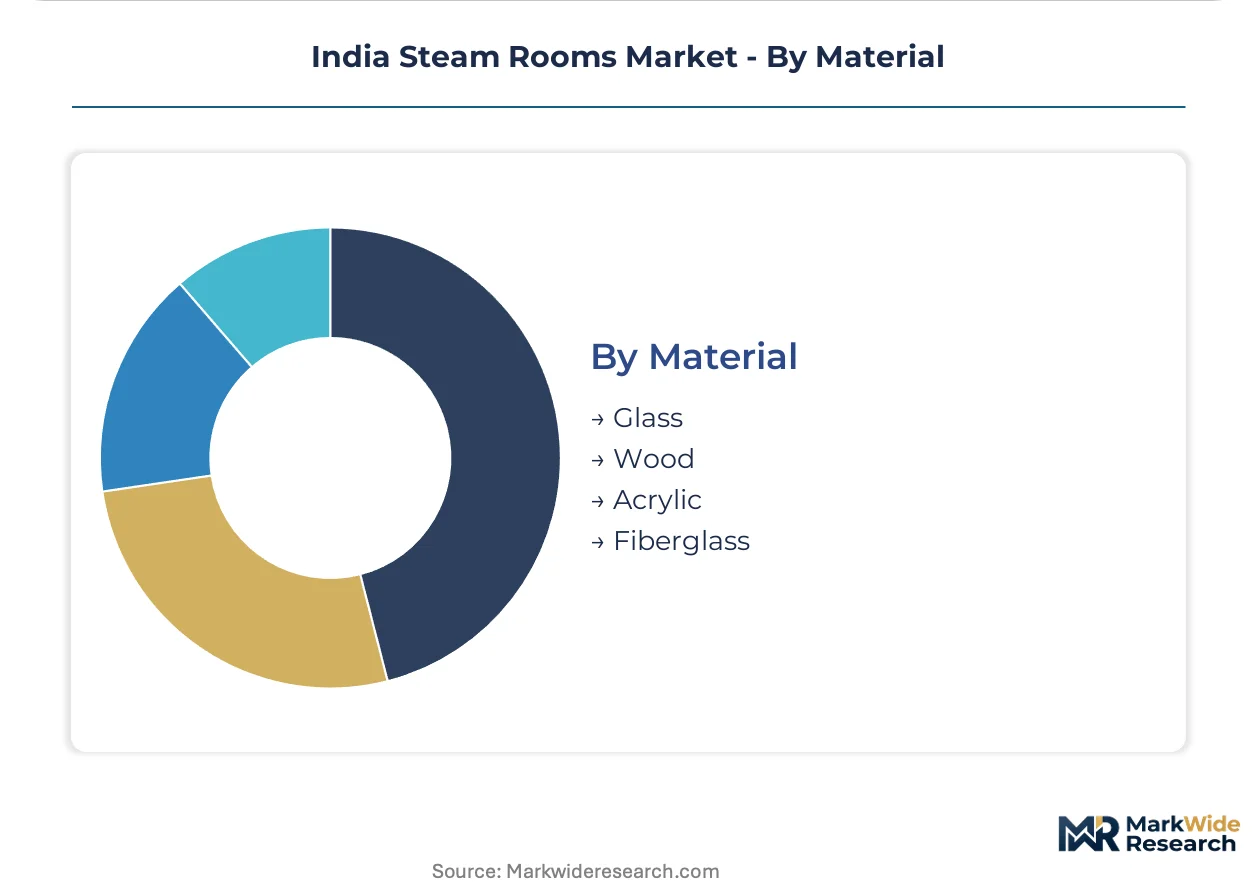
Material:
Supply chain localization incentives and import dependency patterns shape material selection, with domestic acrylic sourcing anchoring South Indian projects while glass specifications dominate premium Mumbai developments.
- Glass:Tempered vapor-tight panels with silicone-sealed joints dominate Mumbai and Delhi luxury residential towers for aesthetic transparency and moisture containment.
- Wood:Thermally treated cedar and hemlock assemblies serve traditional spa aesthetics in Ayurvedic wellness centers, requiring enhanced vapor barriers to prevent degradation.
- Acrylic:Woven Gold India anchors South Indian commercial projects with localized acrylic sourcing and faster turnaround cycles, reducing lead times against imported alternatives.
- Fiberglass:Reinforced polymer panels offer corrosion resistance for coastal Maharashtra outdoor installations and high-humidity fitness club environments.
Supply security favors Acrylic; premium positioning favors Glass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's steam room equipment trade runs a modest deficit, with generator vessels and electronic control modules dominating import flows while acrylic panel fabricators and installation service providers anchor limited export capacity. Domestic production concentrates in Maharashtra and Karnataka, where BIS certification infrastructure and hospitality demand clusters create self-reinforcing supply zones. State-level electrical inspectorates enforce divergent compliance timelines, fragmenting procurement patterns across sub-markets.
Maharashtra
Mumbai's luxury hotel construction pipeline and Pune's green building certification momentum drive generator demand across premium and commercial tiers. The state's electrical inspectorate mandates BIS-marked heating elements for all commercial installations, compressing vendor qualification windows. Thane and Navi Mumbai industrial corridors host captive metal fabrication facilities serving integrated steam room manufacturers.
Karnataka
Bengaluru's boutique fitness chain expansion and Ayurvedic wellness center proliferation create dual demand channels for modular and clinical-grade systems. CEA energy efficiency disclosure requirements apply to commercial heating equipment above specified load thresholds, accelerating inverter-based generator specifications. Mysuru and Mangaluru hospitality projects pull South Indian acrylic sourcing through localized supply relationships.
Delhi-NCR
High-rise residential developers in Gurugram and Noida specify steam rooms as standard wellness amenities, favoring faster-installation modular systems over custom assemblies. Municipal electrical permitting variability across Delhi, Haryana, and Uttar Pradesh jurisdictions extends project timelines for cross-border installations. Independent HVAC technicians with BIS licensing concentrate in the capital, fragmenting OEM service revenue.
Telangana
Hyderabad's commercial real estate pursuit of IGBC certification creates specification pull for low-energy steam generator systems in Grade-A office developments. The state's building code adoption lags Maharashtra and Karnataka, creating regulatory arbitrage for pre-certified equipment vendors. Secunderabad hospitality renovation activity requires structural moisture remediation in aging properties before generator installation.
Tamil Nadu
Chennai's coastal humidity conditions favor corrosion-resistant fiberglass panel specifications for outdoor poolside installations. The state's electrical safety enforcement follows BIS standards with limited state-level augmentation, reducing compliance friction relative to western markets. Coimbatore industrial fabrication capacity supports generator vessel production for regional supply.
India Steam Rooms Market Competitive Landscape
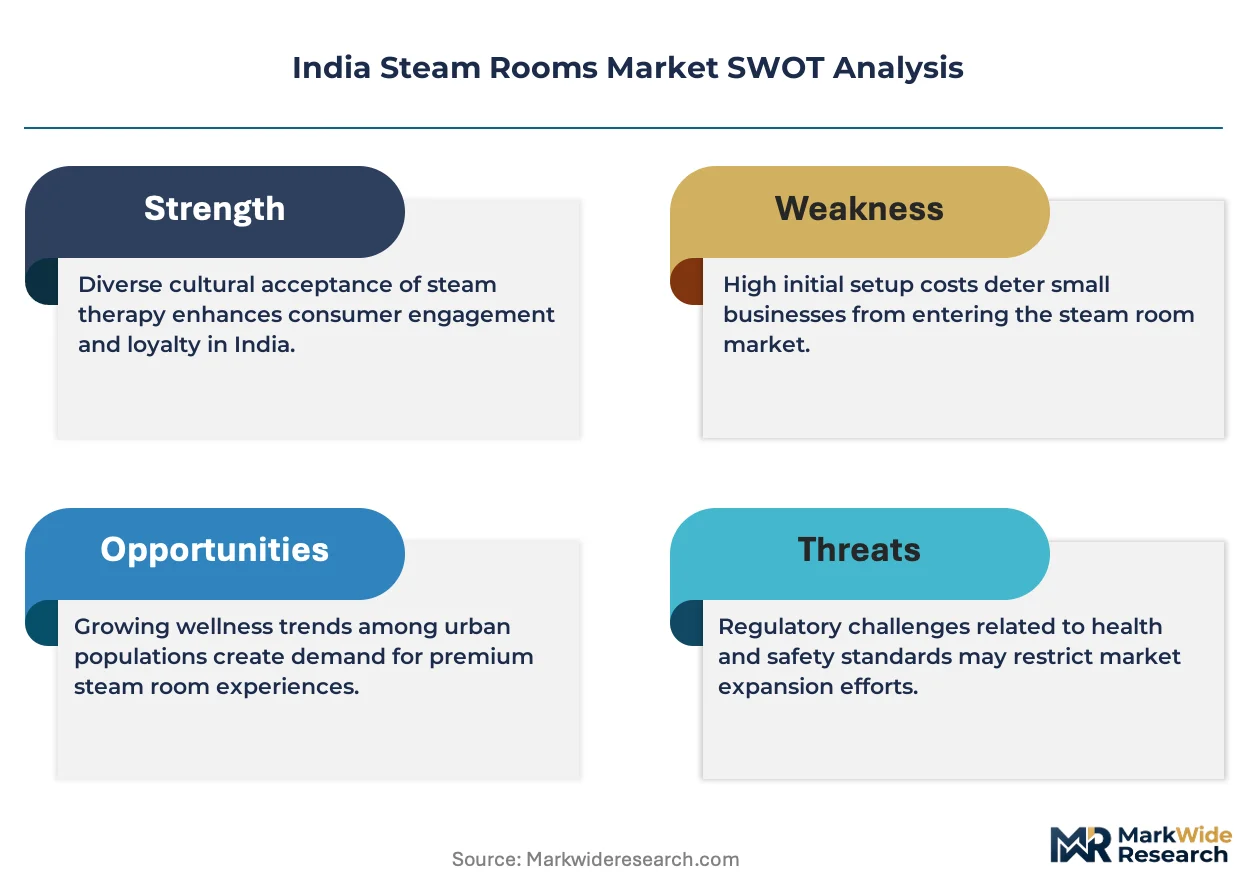
Concentration sits with integrated manufacturers possessing captive metal fabrication and established BIS certification pathways, while assembly-dependent competitors face margin compression from stainless steel price volatility and imported control system lead times. The vendor base stratifies across three archetypes: foundry-integrated domestic specialists, premium-positioned multinationals with hospitality relationships, and regional fabricators leveraging localized acrylic sourcing. Competitive dynamics center on certification speed and installation network density rather than pure price competition, with BIS-licensed electrical contractor relationships serving as the primary defensive moat.
Among domestic integrated manufacturers, Steam Smith Systems exemplifies the foundry-integrated archetype through captive metal fabrication controlling input costs across installation networks. Kohler occupies the premium-tier multinational position, sustaining hospitality sector relationships through imported control systems and extended warranty offerings. Woven Gold India anchors the regional fabricator segment, leveraging South Indian acrylic sourcing relationships and faster turnaround cycles to capture commercial project share outside Mumbai-Delhi corridors.
| Leading Market Players |
|---|
| Steam Smith Systems |
| Kohler |
| Woven Gold India |
| Orion Bathing Concepts |
| Omega Bath Solutions |
| Quantum Solutions India |
| Hi Tech Bath Solutions |
| Bath Systems India |
| Steamers India |
| Others |
Supply & Pricing Matrix
Captive metal fabrication capacity in Maharashtra and Karnataka anchors cost control for integrated manufacturers, compressing price floors for assembly-dependent competitors while elevating entry barriers through BIS certification timelines. This scale concentration rewards foundry-integrated specialists with margin defensibility against stainless steel price volatility.
Pricing Analysis
Luxury hospitality buyers anchor three-tier pricing structure across premium, standard, and economy levels, with BIS certification grade and after-sales service bundling as primary differentiation drivers. Price erosion runs through the standard tier as modular generator adoption accelerates in fitness club procurement. Residential developers in Mumbai and Delhi exhibit highest price sensitivity due to CEA energy efficiency disclosure requirements, while five-star hotel chains absorb premium pricing for extended moisture intrusion warranties.
Supply Chain Analysis
India and China anchor generator vessel fabrication and electronic control module supply respectively, with domestic captive foundries in Thane and Navi Mumbai feeding integrated manufacturers. The supply chain draws from nickel alloy inputs for stainless steel vessels, acrylic panels from South Indian fabricators, and EU-sourced electronic modules. Single-source vulnerability in imported control systems concentrates risk, while distribution runs through BIS-licensed electrical contractors with vapor-sealing expertise concentrated in Mumbai and Delhi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as luxury hospitality capital expenditure rebounds from pandemic deferrals, with spa infrastructure investment accelerating across five-star hotel chains.
For Market Incumbents: Compound defensive positioning through captive metal fabrication expansion in Maharashtra industrial corridors and accelerated BIS certification investment for inverter-based generator architectures. Acrylic panel substitution from infrared sauna cabins and technician scarcity in secondary markets threaten volume retention, making channel control through certified contractor networks the priority lever. For New Entrants and Emerging Players: Lead with Ayurvedic wellness center specifications in Karnataka and Hyderabad's IGBC-certified commercial developments as the most penetrable white-space targets. Tier-2 city green building adoption offers faster qualification pathways than saturated Mumbai-Delhi corridors, with direct maintenance contract propositions to facility managers as the viable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors foundry-integrated domestic specialists with established BIS pathways over assembly-dependent competitors facing margin compression. Long-term viability hinges on PLI scheme component localization momentum and medical wellness convergence traction, with certified installation technician training pipeline development as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Fabrication | Captive foundry capacity insulates Steam Smith Systems from nickel alloy price volatility. |
| BIS Certification Acceleration | Compressed 14-week laboratory timelines favor pre-certified component sourcing strategies. |
| Modular Generator Architecture Launch | Swap-compatible systems fragment vendor revenue toward component replacement schedules. |
| Direct Maintenance Contract Expansion | Independent HVAC technicians capture recurring revenue from Delhi NCR luxury hotels. |
| IGBC Certification Partnership Program | Low-energy specifications in Pune and Hyderabad commercial developments create specification pull. |
Research Methodology
Operator-level perspectives from spa engineering heads, BIS-licensed electrical contractors, fitness club procurement managers, and luxury hotel facility directors anchored the qualitative base. Primary interview insights combined with secondary validation from CEA energy efficiency disclosures, Maharashtra state electrical inspectorate records, customs import data for generator vessels, and hospitality construction pipeline databases. Bottom-up installation volume estimates triangulated against top-down wellness infrastructure spending projections.
Sensitivity analysis across stainless steel price volatility scenarios and BIS certification timeline extensions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include generator architecture type, end-user vertical, installation environment, and regional regulatory cluster. CAGRs derived from trend extrapolation of hospitality capital expenditure cycles and residential wellness amenity penetration rates, with inverter-based system adoption curves and green building certification momentum as industry-specific forecast inputs.
Forecasts assume regulatory continuity in BIS electrical safety standards and Maharashtra state building codes; material policy shifts would require re-modeling. Stainless steel price volatility, imported control system lead time extensions, and certified technician training pipeline development represent specific risk factors that could revise projections. Recalibration cycles align with material shifts in luxury hospitality construction permits and PLI scheme component localization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market