
 Malaysia Sanitaryware Market | 2026-2036
Malaysia Sanitaryware Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Sanitaryware Market Foresight
The capital-intensity divergence between kiln-fired ceramic specialists and plastic-mold assemblers is bifurcating competitive returns in Malaysia sanitaryware. Kohler leverages its captive glaze-chemistry R&D to command premium positioning in luxury residential towers across Kuala Lumpur. Claytan anchors its position through deep backward integration into local kaolin sourcing and controlled-temperature firing tunnels. Jaquar competes aggressively on designer basin collections distributed through architect-specified channels.
Sanitaryware encompasses vitreous ceramic fixtures, polymer-based alternatives, and metal-alloy components engineered for water conveyance, waste disposal, and personal hygiene in built environments. Ceramic variants undergo bisque firing at 1,200°C before vitreous enamel application, yielding non-porous surfaces mandated for health-code compliance in institutional settings. Toilets and basins dominate volume throughput, while bidets capture expanding margin pools as Malaysian households upgrade from basic spray attachments to integrated electronic units. The residential application segment leads absolute consumption, though commercial installations in hospitality and healthcare command higher per-project values due to SIRIM-certified durability specifications.
SIRIM QAS International administers product certification and MS standard compliance for sanitaryware sold in Malaysia, with particular stringency around water-efficiency ratings under MS 147. The Ministry of Housing and Local Government enforces Uniform Building By-Law provisions that mandate accessible fixture specifications in public buildings, directly shaping manufacturer design priorities. CIDB Malaysia's contractor registration requirements influence which brands achieve specification in government-backed affordable housing schemes. Stakeholders must monitor whether proposed amendments to MS water-efficiency thresholds will force ceramic retooling or accelerate plastic-alternative substitution before the next regulatory consultation cycle concludes.
Market Dynamics
Malaysia's sanitaryware sector contends with SIRIM QAS International certification mandates that force manufacturers into dual-track production: water-efficient MS 147-rated lines for government-backed housing, and premium-grade ceramic for private luxury towers. This bifurcation splits capital allocation and technical staffing across incompatible firing protocols.
Growth Catalysts
- Greater Kuala Lumpur residential construction:High-rise developments in KL Sentral and Mont Kiara specify vitreous ceramic fixtures at scale, pulling volume through architect-specified channels.
- SIRIM water-efficiency thresholds:MS 147 ratings mandate dual-flush mechanisms and reduced flow rates, creating replacement demand as older stock phases out.
- Penang high-rise pipeline:Gurney Drive and Tanjung Tokong luxury towers specify imported-design basins and integrated bidet systems, elevating per-project values.
Market Restraints
- Kaolin supply concentration:Local ceramic producers depend on Perak and Johor clay deposits controlled by limited mining concessions, exposing margin pressure during monsoon disruptions.
- Natural gas firing costs:Kiln operations require sustained 1,200°C temperatures, making ceramic production vulnerable to PETRONAS tariff adjustments.
- Polymer substitution threat:Acrylonitrile butadiene styrene and fiberglass-reinforced plastic basins compete on weight and installation speed in budget housing segments.
Strategic Opportunities
- Iskandar Malaysia affordable housing:CIDB-registered contractors in Johor face fixture procurement mandates that favor SIRIM-certified domestic suppliers over imports.
- Electronic bidet convergence:Integration of instant-heating modules and sensor-activated seats creates margin expansion beyond commodity ceramics.
- E-commerce specification platforms:Digital channels enable direct architect-to-manufacturer engagement, bypassing traditional distributor markups in secondary cities.
Industry Challenges
- Glaze-chemistry talent scarcity:Formulation expertise for vitreous enamel application concentrates among aging technicians, constraining quality consistency across production shifts.
- SIRIM certification timelines:MS standard testing cycles extend 4-6 months, delaying product launches and freezing design iterations mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Sanitaryware Market |
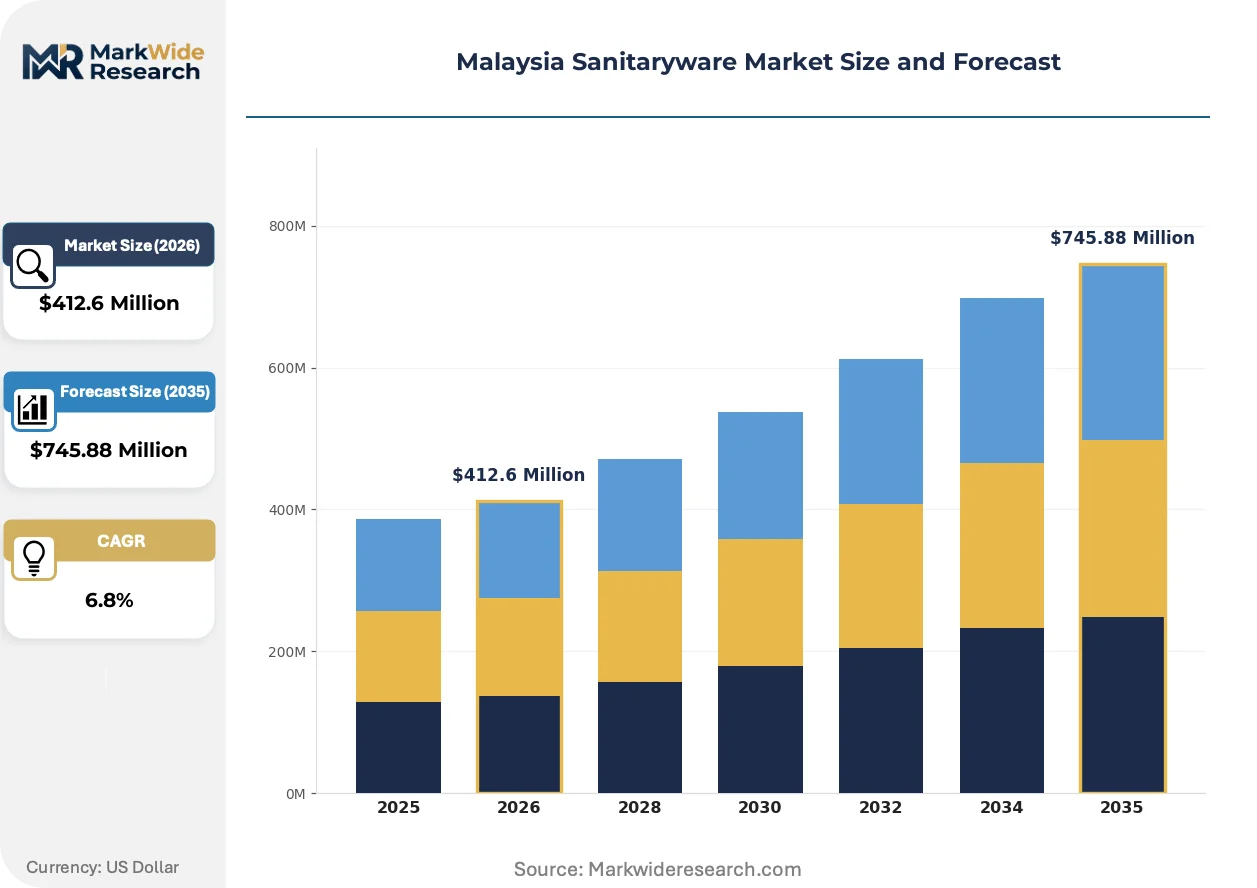
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Basins, Bidets, Urinals Material: Ceramic, Plastic, Acrylic, Stainless Steel Application: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Retail Stores, Online Sales, Wholesalers |
| Companies Covered | Kohler, Claytan, Johnson Suisse, INNO Ceramitec, Jaquar, Roca Malaysia, American Standard, Asher, TOTO Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Sanitaryware Market Shifts & Advancements
Digital specification tools and modular fixture systems are compressing traditional procurement cycles in Malaysian sanitaryware. Manufacturers now face pressure to deliver configurable product families rather than static catalog lines.
Rimless toilet designs employing tornado-flush hydraulics are fragmenting the traditional washdown segment. High-end residential developers in Damansara Heights and Bangsar specify these units for hygiene visibility and reduced cleaning burden. The technology is fragmenting competitive positioning by forcing incumbents to retool mold investments or cede premium specification to specialized importers.
SIRIM QAS International proposes tightened MS 147 water-efficiency thresholds in pending consultation rounds. Ceramic manufacturers must recalibrate firing tunnel outputs to accommodate redesigned trapways and reduced cistern volumes. Penang and Selangor housing authorities signal early adoption of stricter ratings, pressuring stock clearance of legacy inventory ahead of enforcement.
Architect-led specification is displacing contractor-driven procurement in luxury segments. Design firms in Kuala Lumpur now mandate basin and bidet selections before main contractor appointment, compressing traditional distributor influence. This pattern concentrates in Mont Kiara and Desa ParkCity developments where foreign design houses dominate project conception.
Malaysia Sanitaryware Market Segmentation
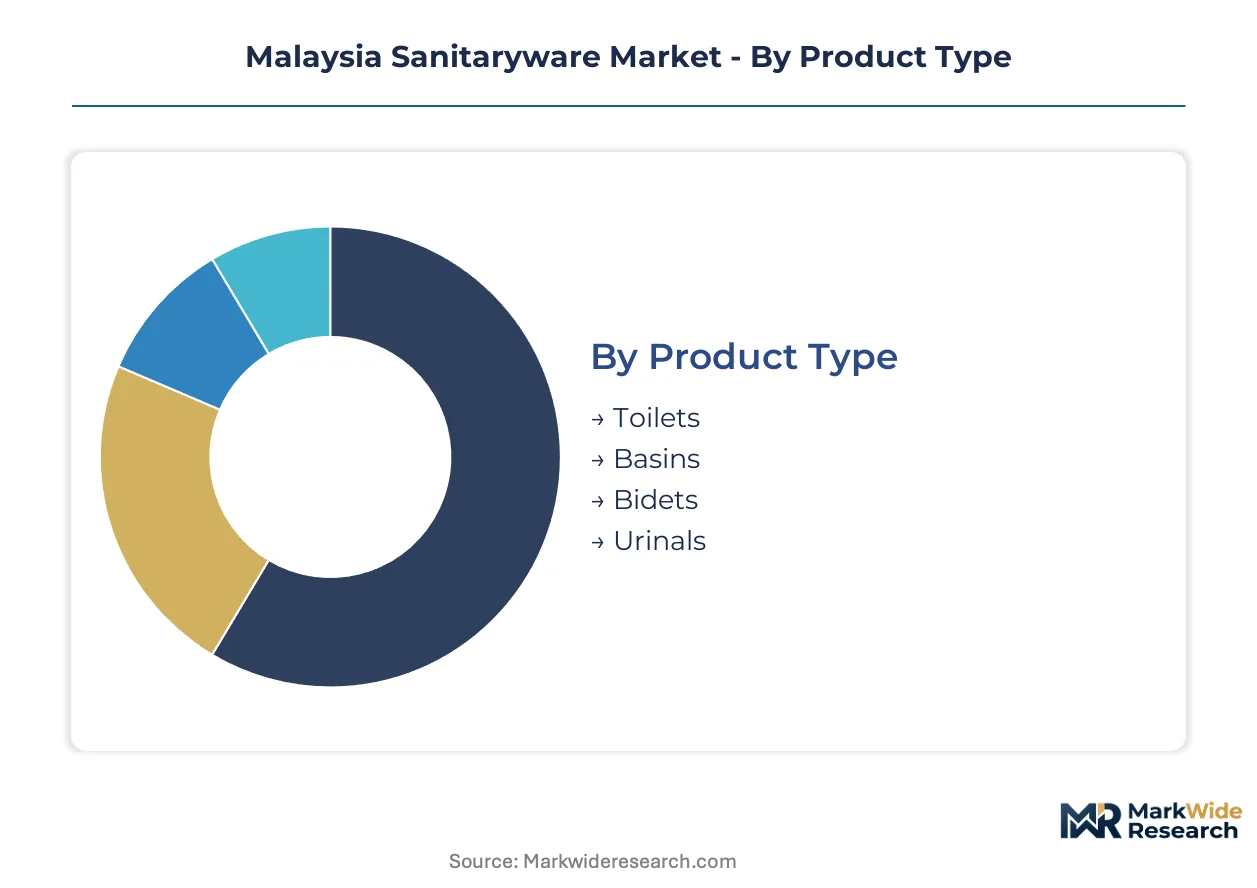
Malaysia's sanitaryware segmentation reveals how SIRIM certification tiers, material cost structures, and channel economics fragment procurement patterns across Greater Kuala Lumpur's high-rise pipeline and Penang's luxury developments. Understanding these divides exposes where specification power concentrates and which segments absorb regulatory-driven replacement cycles.
Product Type:
Margins pool heaviest in integrated electronic bidets and rimless toilet designs where glaze-chemistry R&D creates defendable differentiation against commodity imports.
- Toilets:Vitreous ceramic units dominate volume throughput across Malaysian residential towers, with SIRIM MS 147 water-efficiency ratings now mandatory for government-backed housing schemes in Selangor and Johor. Dual-flush mechanisms and reduced cistern volumes force ceramic retooling as pending regulatory consultations threaten tighter thresholds.
- Basins:Architect-specified collections in Mont Kiara and Damansara Heights luxury towers command premium positioning through designer form factors and captive glaze formulations. Kohler and Claytan compete here through specification relationships with foreign design houses that now mandate basin selections before main contractor appointment.
- Bidets:Integrated electronic units with instant-heating modules and sensor-activated seats are expanding margin pools fastest as Malaysian households upgrade from basic spray attachments.
- Urinals:Waterless and low-flush variants concentrate in commercial and institutional installations governed by Uniform Building By-Law accessibility mandates.
The dominant share belongs to Toilets, while Bidets is closing the gap fastest.
Material:
Cost tiering splits procurement between kiln-fired ceramic for specification-driven projects and polymer alternatives for speed-sensitive budget housing.
- Ceramic:Bisque firing at 1,200°C yields non-porous vitreous enamel surfaces mandated for health-code compliance in Malaysian institutional settings. Local producers depend on Perak and Johor kaolin deposits, exposing margin pressure during monsoon disruptions to mining concessions.
- Plastic:Acrylonitrile butadiene styrene basins compete on weight and installation speed in CIDB-registered affordable housing schemes across Iskandar Malaysia, though SIRIM durability concerns limit penetration in commercial specifications.
- Acrylic:Lightweight alternatives find traction in renovation markets where structural load constraints prohibit ceramic installation.
- Stainless Steel:Industrial and heavy-traffic applications favor corrosion-resistant alloy fixtures in healthcare and transportation infrastructure.
Ceramic holds the specification high ground, though Plastic is expanding most quickly in volume-driven affordable segments.
Application:
Customer type determines compliance burden and per-project value, with institutional buyers enforcing the strictest SIRIM certification requirements.
- Residential:High-rise developments in KL Sentral, Mont Kiara, and Penang's Gurney Drive pull volume through architect-specified channels, with luxury towers importing design-forward basins and integrated bidet systems.
- Commercial:Hospitality and retail installations command elevated per-project values due to SIRIM-certified durability specifications and accelerated replacement cycles in high-traffic environments.
- Institutional:Healthcare and education facilities face Uniform Building By-Law mandates for accessible fixture specifications, directly shaping manufacturer design priorities.
- Industrial:Heavy-duty applications favor stainless steel and reinforced polymer systems in manufacturing and logistics facilities.
Residential absorbs absolute consumption volume, yet Commercial commands the steepest expansion trajectory in value terms.
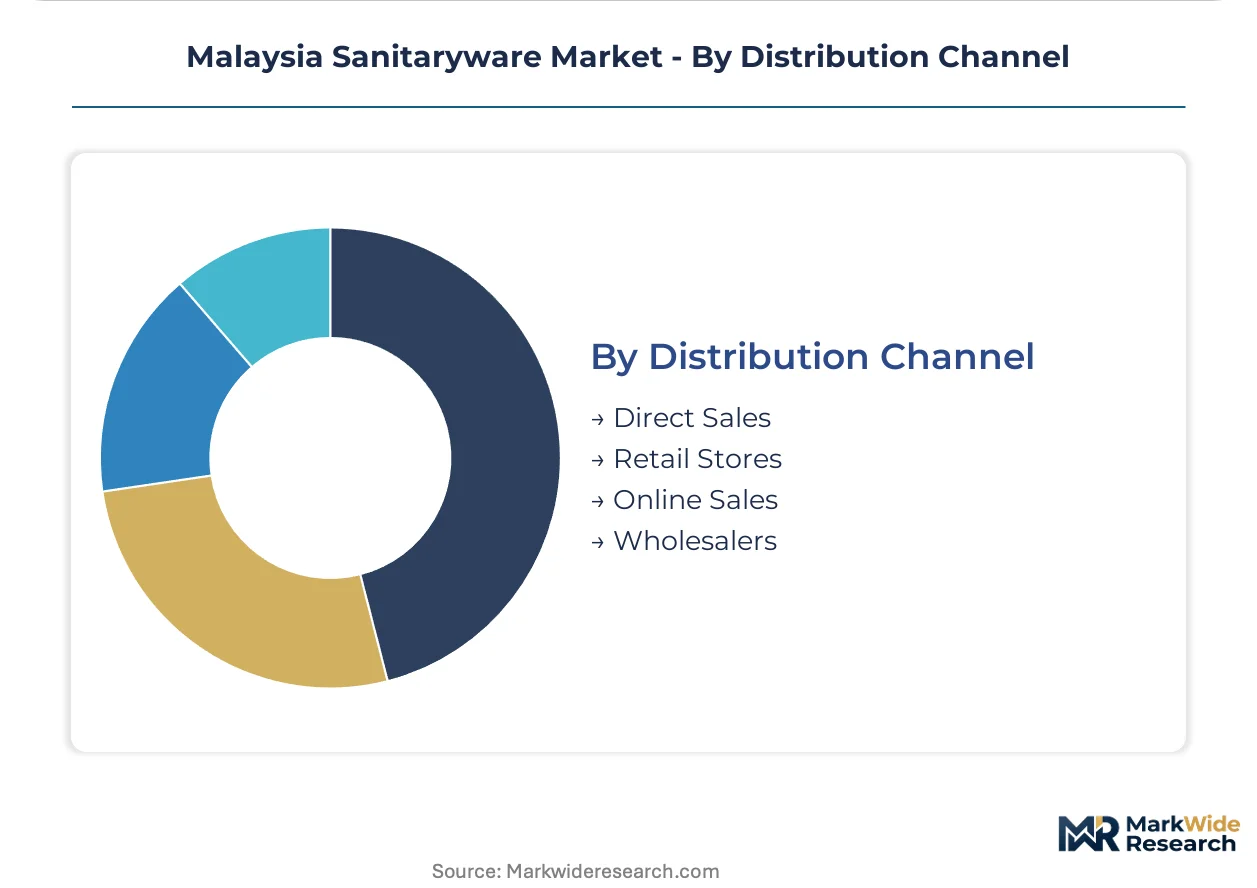
Distribution Channel:
Channel economics are compressing as digital specification platforms enable direct architect-to-manufacturer engagement, bypassing traditional distributor markups.
- Direct Sales:Large-scale developers in Greater Kuala Lumpur negotiate directly with manufacturers for bulk procurement of SIRIM-certified lines, securing volume discounts unavailable through intermediaries.
- Retail Stores:Showroom-based selection persists in renovation and replacement markets where tactile evaluation of glaze quality and flush performance influences purchase decisions.
- Online Sales:E-commerce specification platforms are gaining traction in secondary cities outside the Klang Valley, though physical verification requirements slow adoption for premium ceramic.
- Wholesalers:Traditional distributor networks retain influence in contractor-driven procurement for government-backed housing, where CIDB registration requirements favor established supply relationships.
Direct Sales captures the largest project values, while Online Sales is gaining share fastest among digitally native specification workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Penang's luxury corridor while Selangor absorbs volume-driven procurement at compressed margins. This asymmetry shapes manufacturer portfolio allocation across Malaysian sub-markets.
Selangor
High-rise residential towers in KL Sentral and Mont Kiara pull vitreous ceramic volume through architect-specified channels. CIDB Malaysia contractor registration requirements govern fixture procurement in government-backed affordable housing schemes. Shah Alam industrial zones host backward-integrated producers with captive kaolin processing and controlled-temperature firing tunnels.
Penang
Gurney Drive and Tanjung Tokong luxury developments specify imported-design basins and integrated electronic bidet systems at elevated per-project values. SIRIM QAS International water-efficiency consultations signal early adoption of tightened MS 147 thresholds by Penang housing authorities. Bayan Lepas manufacturing corridors concentrate glaze-chemistry R&D facilities serving premium residential specifications.
Johor
Iskandar Malaysia affordable housing pipelines drive demand for SIRIM-certified domestic suppliers over imports. The Ministry of Housing and Local Government enforces Uniform Building By-Law provisions mandating accessible fixture specifications in public buildings. Pasir Gudang industrial clusters host polymer-mold assemblers competing on weight and installation speed for budget housing segments.
Perak
Local kaolin deposits controlled by limited mining concessions supply ceramic producers with raw material inputs. Monsoon disruptions to extraction operations expose margin pressure across downstream firing operations. Ipoh manufacturing bases anchor supply relationships with Selangor-based sanitaryware fabricators requiring consistent clay quality.
Malaysia Sanitaryware Market Competitive Landscape
Concentration sits with kiln-fired ceramic specialists possessing captive glaze-chemistry capabilities and deep backward integration into local mineral sourcing. The vendor base splits between premium-grade vitreous enamel producers and polymer-mold assemblers serving speed-sensitive budget segments. Two strategic archetypes dominate: vertically integrated ceramic specialists controlling kaolin-to-firing value chains, and design-forward specification players leveraging architect relationships. Competitive moves center on firing tunnel capacity expansion and direct e-commerce specification platforms bypassing traditional distributor networks.
Within the vertically integrated tier, Claytan exemplifies backward integration into Perak kaolin deposits and controlled-temperature firing infrastructure. Kohler occupies a position representing premium glaze-chemistry R&D investment for luxury residential tower specifications. Jaquar sits within the design-forward archetype, anchoring competitive presence through architect-specified basin collections in Greater Kuala Lumpur developments.
| Leading Market Players |
|---|
| Kohler |
| Claytan |
| Johnson Suisse |
| INNO Ceramitec |
| Jaquar |
| Roca Malaysia |
| American Standard |
| Asher |
| TOTO Malaysia |
| Others |
Supply & Pricing Matrix
Polymer substitution in budget housing segments simultaneously relocates production geography toward Pasir Gudang industrial clusters and compresses pricing economics for ceramic incumbents forced into dual-track firing investments. This displacement dynamic fragments procurement power across incompatible material tiers.
Pricing Analysis
The customization-premium spread between architect-specified basin collections and standard catalog lines widens as foreign design houses in Mont Kiara mandate pre-appointment selections. Three-tier pricing structure across premium, standard, and economy levels reflects SIRIM certification grade and glaze-chemistry R&D investment. Cost compression in economy tiers intensifies because polymer-mold assemblers compete on installation speed. Government-backed housing contractors exhibit highest price sensitivity; luxury developers show lowest.
Supply Chain Analysis
Malaysia and China anchor ceramic raw material processing and finished fixture manufacturing respectively. Local production draws from Perak and Johor kaolin deposits, Chinese vitreous enamel additives, and Japanese instant-heating module components. Single-source vulnerability concentrates in monsoon-disrupted mining concessions controlling clay extraction. Distribution runs through CIDB-registered contractor networks for affordable housing and direct architect-manufacturer channels for luxury specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among architect-led specification workflows in Greater Kuala Lumpur luxury developments, fragmenting traditional distributor influence and compressing procurement cycle timelines.
For Market Incumbents: Secure captive glaze-chemistry talent pipelines against aging technician scarcity and expand firing tunnel capacity in Shah Alam to capture KL Sentral high-rise volume. Polymer substitution in Iskandar Malaysia affordable housing threatens ceramic volume absorption; backward integration into Perak kaolin deposits defends margin position against raw material disruption. For New Entrants and Emerging Players: SIRIM MS 147 fast-track certification unlocks specification in Johor government-backed housing pipelines where CIDB registration requirements favor domestic suppliers. White-space targets include electronic bidet integration for Penang luxury towers and e-commerce specification platforms for secondary cities outside Klang Valley. Go-to-market through direct architect engagement bypasses entrenched wholesaler relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated ceramic specialists possessing controlled-temperature firing infrastructure and captive mineral sourcing. Long-term viability hinges on defendable specification relationships with foreign design houses and R&D capabilities for tornado-flush hydraulics. Recalibrate positions upon SIRIM water-efficiency threshold amendments forcing ceramic retooling cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Firing Tunnel Capacity Expansion | Shah Alam producers capture KL Sentral and Mont Kiara high-rise volume at scale. |
| SIRIM Certification Fast-Track Investment | Accelerated MS 147 approval cycles unlock Iskandar Malaysia affordable housing specification. |
| Electronic Bidet Module Integration | Instant-heating and sensor-activation capabilities expand margin pools beyond commodity ceramics. |
| Direct E-Commerce Specification Platform | Digital channels bypass traditional distributor markups in secondary cities outside Klang Valley. |
| Kaolin Deposit Backward Integration | Perak mining concession control insulates margin pressure from monsoon extraction disruptions. |
Research Methodology
The analysis maps vitreous ceramic, polymer alternative, and electronic bidet sub-sectors, each validated through procurement managers at CIDB-registered contractors, specification directors at foreign design houses, and glaze-chemistry technicians at Perak mining operations. Secondary sources include SIRIM QAS International certification databases, Ministry of Housing Uniform Building By-Law amendments, and CIDB contractor registration records. Bottom-up project pipeline enumeration triangulates against top-down construction sector forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application sector, and distribution channel complexity. CAGRs were derived from regression analysis of historical construction completion data and regulatory-driven replacement cycle assumptions. Industry-specific forecast inputs incorporate PETRONAS natural gas tariff trajectories and monsoon disruption patterns affecting kaolin extraction.
Underlying assumptions cover SIRIM certification timeline stability and ceramic-polymer substitution elasticity, with deviation risk concentrated in pending MS 147 water-efficiency threshold amendments and architect-specification workflow permanence. Recalibration cycles align with material shifts in regulatory consultation outcomes and Greater Kuala Lumpur high-rise pipeline announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market