
 Europe Bath and Shower Products Market | 2026-2036
Europe Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bath and Shower Products Market Foresight
Sodium laureth sulfate is decoupling from premium European formulations as brands reformulate around gentler, plant-derived surfactants. Beiersdorf AG leverages its NIVEA research infrastructure to anchor dermatological credibility across German-speaking markets. Unilever PLC sustains volume leadership through concentrated refill systems that reduce plastic intensity. Henkel AG & Co. KGaA specializes in enzyme-based cleansing technologies that differentiate its Schwarzkopf and Dial-aligned portfolios.
Europe bath and shower products encompass liquid, solid, cream, and powder formulations designed for skin cleansing, hydration, and sensory enhancement through controlled pH balance and surfactant chemistry. These products serve personal care, spa wellness, retail distribution, and professional use channels where efficacy claims must align with Cosmetic Regulation (EC) No 1223/2009 safety dossiers. Shower gels and bar soaps occupy the mature volume core, yet bath bombs and body scrubs capture expanding margin pools as experiential gifting and self-care rituals deepen. Liquid formats still dominate household penetration, though solid bars are gaining fastest in urban sustainability-focused segments.
EMA cosmetic ingredient assessments, REACH chemical registration requirements, and the EU Green Deal circular economy framework collectively elevate compliance costs while accelerating biodegradable and refillable innovation cycles. ECHA substance restrictions on microplastics directly impact exfoliating body scrub formulations, forcing reformulation toward cellulose or mineral alternatives. Stakeholders must monitor how the CSRD disclosure regime reshapes supply chain transparency expectations and whether national eco-label schemes in France and Germany fragment market access rules.
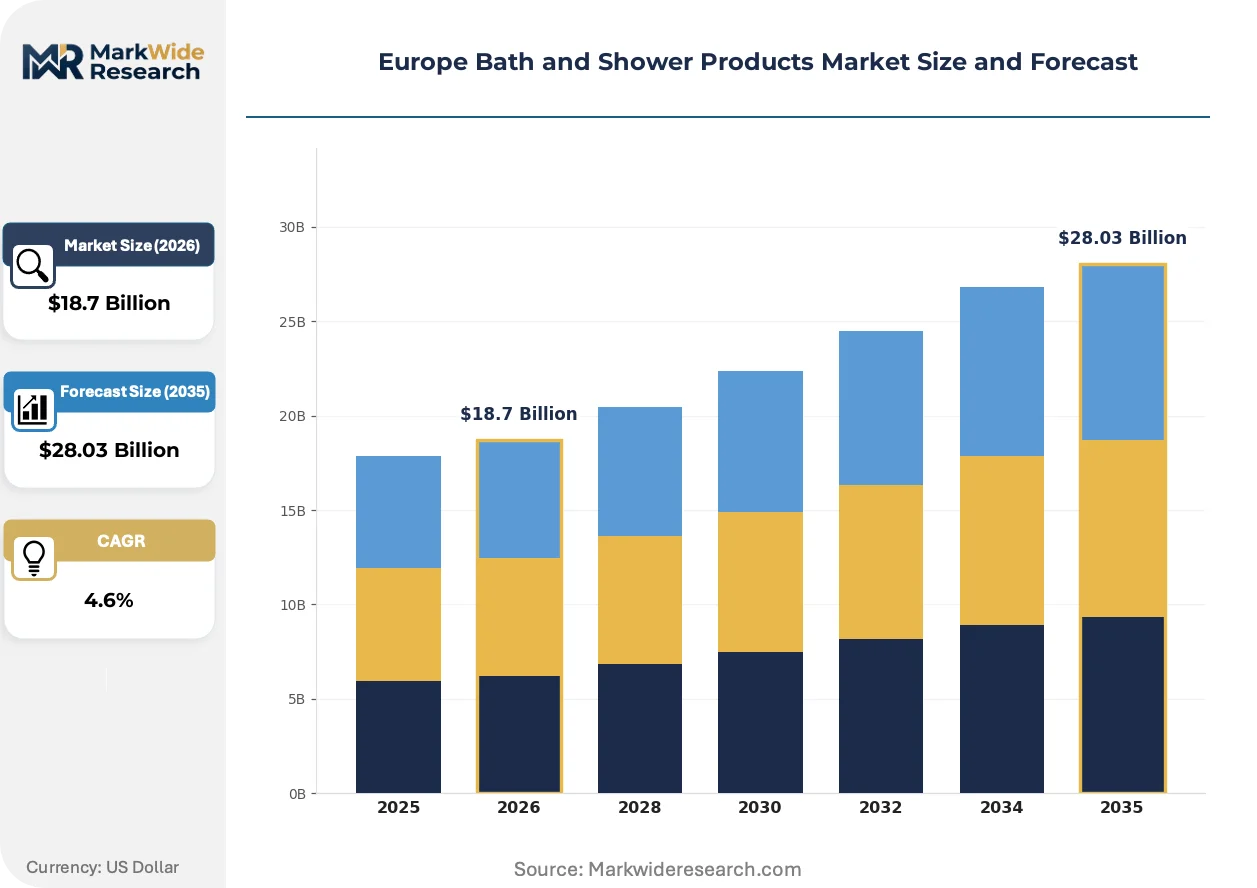
Market Dynamics
REACH chemical registration and the EU Green Deal are forcing wholesale surfactant replacement across European formulation houses, compressing reformulation timelines while elevating biodegradable ingredient premiums. Solid-format bars and refillable concentrates now anchor portfolio strategy for brands seeking pharmacy and urban specialty channel placement.
Growth Catalysts
- EU Green Deal circular economy framework:Mandatory packaging reduction targets accelerate refill station deployment in French and German retail networks, creating captive demand for concentrated formats.
- Biodegradable surfactant chemistry:Plant-derived alkyl polyglucosides replace petrochemical foaming agents in premium dermatological lines, satisfying ECHA substance disclosure requirements.
- Urban sustainability clusters:Berlin, Paris, and Amsterdam concentrate early-adopter households driving solid bar adoption through zero-waste retail partnerships.
Market Restraints
- Palm kernel oil price volatility:Primary feedstock for plant-derived surfactants exposes margin structures to Southeast Asian commodity swings and sustainability certification gaps.
- ECHA microplastic restrictions:Exfoliating body scrub segments face forced reformulation toward cellulose or mineral abrasives, raising unit costs and compressing mass-market viability.
- Specialty chemical supplier concentration:Three German and Swiss firms control majority supply of COSMOS-certified emulsifiers, creating bottleneck risk for mid-tier brands.
Strategic Opportunities
- Portuguese and Spanish pharmacy channel:Underdeveloped relative to French benchmark, these markets show rising dermatological brand awareness among aging demographics.
- CSRD supply chain disclosure mandates:Early compliance positions brands for preferred supplier status with EU institutional procurement frameworks.
- Enzyme-cleansing hybrid formats:Convergence of protease biochemistry with solid bar manufacturing opens professional spa and wellness channel expansion.
Industry Challenges
- Cosmetic safety assessor shortage:Qualified toxicologists for (EC) No 1223/2009 dossier preparation command premium salaries, extending new product registration timelines.
- Legacy liquid filling line stranded assets:Concentrate and solid-format pivots require capital redeployment away from established bottle production infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bath and Shower Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gels, Bath Bombs, Bar Soaps, Body Scrubs End User: Households, Hotels, Spas, Gyms Application: Personal Care, Spa Wellness, Retail Distribution, Professional Use Form: Liquid, Solid, Cream, Powder |
| Companies Covered | Beiersdorf AG, Reckitt Benckiser Group plc, Unilever PLC, Johnson & Johnson, Colgate-Palmolive Company, L'Oréal S.A., Henkel AG & Co. KGaA, PZ Cussons, The Procter & Gamble Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bath and Shower Products Market Shifts & Advancements
Formulation chemistry, regulatory disclosure architecture, and retail format experimentation are simultaneously reshaping competitive advantage in European bath and shower. Brands now compete on ingredient provenance transparency and packaging elimination rather than fragrance differentiation alone.
Solid surfactant bars incorporating syndet (synthetic detergent) bases are converging with cold-process manufacturing to deliver pH-balanced cleansing without preservative loads. German pharmacy chains and Scandinavian specialty retailers stock these formats fastest, compressing conventional liquid gel shelf space. The technology is converging with refill infrastructure investments to lock in urban household switching.
REACH Article 33 communication obligations now require full supply chain substance disclosure for SVHC content above threshold levels. Formulators must map raw material origins through multiple tiers, raising compliance overhead but creating differentiation for brands with captive ingredient sourcing. Exfoliating and antimicrobial claim categories face heaviest documentation burdens, pushing some mass-market SKUs toward delisting.
Zero-waste retail partnerships are replacing conventional supermarket listings for emerging brands. French cooperative grocery networks and British independent health stores now operate bulk refill stations for shower gel and shampoo concentrates, disintermediating packaged goods distributors. This pattern concentrates in metropolitan cores with established package-free retail infrastructure, particularly Copenhagen, Vienna, and Barcelona districts.
Europe Bath and Shower Products Market Segmentation
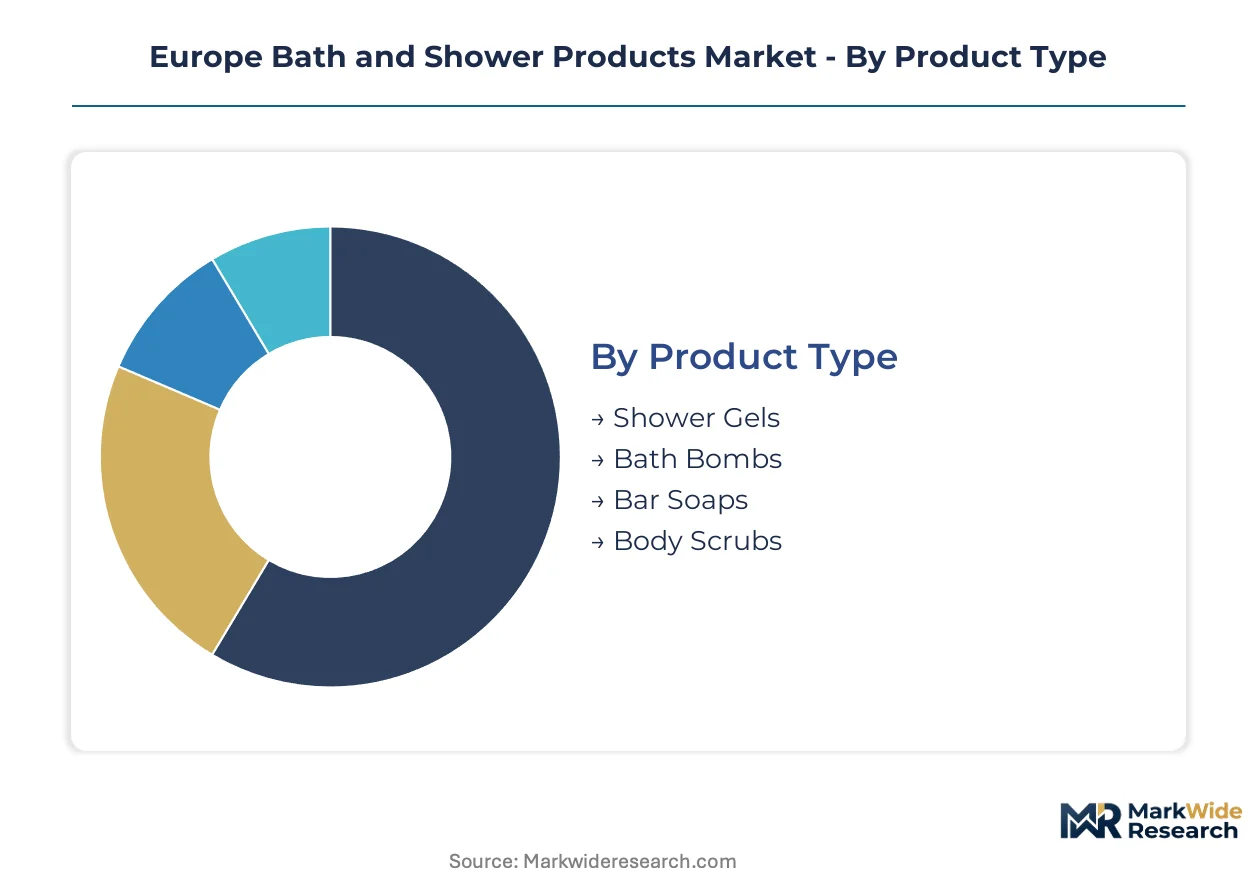
European bath and shower manufacturers configure production lines around format-specific equipment and surfactant chemistry requirements. Segmentation reveals where capital concentrates and which demand pools justify dedicated formulation investments.
Product Type:
Supply concentration in liquid filling infrastructure still dominates, though solid-format investments are accelerating fastest in German and French manufacturing clusters.
- Shower Gels:Surfactant-rich aqueous formulations with controlled pH and viscosity modifiers. Demand concentrates in German urban households and French hypermarket retail, driven by refill station compatibility and concentrated format economics. Shower gels absorb the bulk of installed capacity; Bar Soaps are expanding most quickly.
- Bar Soaps:Syndet-based and cold-process solid formulations incorporating plant-derived alkyl polyglucosides. German pharmacy chains and Scandinavian specialty retailers stock these formats fastest, compressing conventional liquid gel shelf space.
- Bath Bombs:Effervescent solid blends of sodium bicarbonate, citric acid, and essential oils for sensory immersion experiences.
- Body Scrubs:Exfoliating formulations reformulating around cellulose or mineral abrasives to satisfy ECHA microplastic restrictions.
End User:
Cost tier differentiation separates mass-volume household demand from premium hospitality procurement with divergent specification requirements.
- Households:Individual consumers purchasing through retail, pharmacy, and direct-to-commerce channels. French cooperative grocery networks and British independent health stores operate bulk refill stations for concentrates.
- Hotels:Institutional procurement of amenity-sized formats with branded co-packing requirements. Demand concentrates in Mediterranean resort corridors and Alpine wellness destinations.
- Spas:Professional-grade formulations with elevated active ingredient loads for treatment protocols.
- Gyms:High-frequency cleansing products emphasizing antimicrobial claims and rapid-rinse surfactant systems.
Households absorb the bulk of installed capacity; Spas are gaining share fastest.
Application:
Volume maturity varies sharply across channels, with retail distribution commanding scale economics while professional use extracts premium pricing.
- Personal Care:Daily cleansing and hygiene maintenance for individual consumers. German-speaking markets anchor dermatological credibility requirements.
- Spa Wellness:Ritual-oriented consumption emphasizing aromatherapy and hydrotherapy integration. Demand concentrates in Alpine thermal destinations and Portuguese wellness developments.
- Retail Distribution:Packaged goods moving through supermarket, pharmacy, and specialty channels. French pharmacy retail sets the benchmark for dermocosmetic placement standards.
- Professional Use:Salon, clinic, and hospitality procurement with bulk concentrate and private-label specifications.
Retail Distribution absorbs the bulk of installed capacity; Spa Wellness is climbing the fastest.
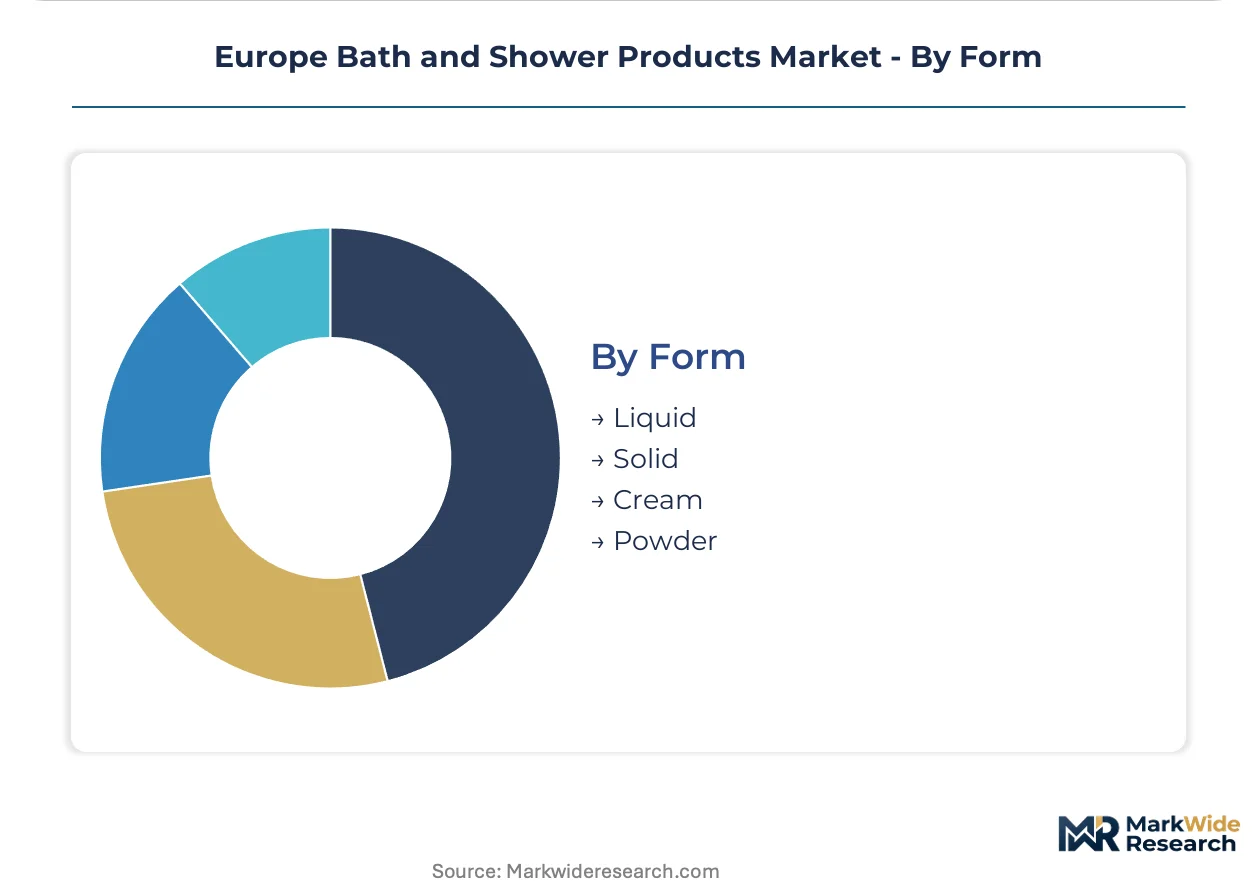
Form:
Customer type fragmentation separates convenience-oriented liquid buyers from sustainability-motivated solid format adopters.
- Liquid:Aqueous surfactant solutions with preservative systems and controlled rheology. Berlin, Paris, and Amsterdam concentrate early-adopter households for refill concentrate adoption.
- Solid:Bar and tablet formats eliminating packaging and water content. German pharmacy chains and Scandinavian specialty retailers stock these formats fastest.
- Cream:Emulsion-based cleansers with elevated lipid content for dry skin conditions.
- Powder:Anhydrous concentrates requiring consumer reconstitution, gaining traction in zero-waste retail partnerships.
Liquid absorbs the bulk of installed capacity; Solid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban sustainability clusters in Germany, France, and the United Kingdom concentrate premium-format demand, while Mediterranean markets expand pharmacy-channel dermatological placement.
Germany
REACH compliance costs and the EU Green Deal packaging mandates drive concentrated refill station deployment in Berlin and Hamburg retail networks. ECHA substance disclosure requirements compress reformulation timelines for surfactant chemistry. The Rhine-Ruhr manufacturing corridor anchors solid-format bar production capacity expansion.
France
Pharmacy retail channel dominance in Paris and Lyon elevates dermatological credibility requirements for brand placement. ANSM cosmetic safety assessments tighten dossier preparation standards beyond baseline EU requirements. The Provence-Alpes-Côte d'Azur wellness corridor concentrates spa-format procurement for Mediterranean resort destinations.
United Kingdom
Zero-waste retail partnerships in London and Manchester accelerate solid bar adoption through independent health store networks. CSRD supply chain disclosure mandates reshape transparency expectations for ingredient provenance. The Southeast England distribution hub handles cross-channel logistics for refill concentrate formats.
Italy
Alpine thermal destination demand in Lombardy and Trentino-Alto Adige supports professional spa-format volumes. CE marking alignment with EU cosmetic regulation maintains market access continuity. The Emilia-Romagna manufacturing cluster specializes in effervescent bath bomb production for experiential gifting segments.
Spain
Underdeveloped pharmacy-channel dermatological awareness in Madrid and Barcelona creates expansion whitespace for premium positioning. National eco-label scheme fragmentation relative to French and German benchmarks complicates multi-market portfolio planning. The Catalan chemical processing corridor supplies biodegradable surfactant feedstocks to formulation houses.
Europe Bath and Shower Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational portfolios dominating mass retail while regional formulators capture pharmacy-channel placement. The vendor base organizes around three strategic archetypes: dermatological credibility builders, sustainability-format innovators, and scale-driven refill system operators. Competitive moves concentrate on portfolio diversification into solid formats and strategic partnerships with zero-waste retail networks.
Among Germany-based personal care conglomerates, Beiersdorf AG and Henkel AG & Co. KGaA occupy positions within the dermatological-specialist tier, while Unilever PLC exemplifies the scale-driven refill system archetype. These anchors represent divergent strategic vectors: captive research infrastructure versus concentrated format economics versus enzyme-based technology differentiation.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Reckitt Benckiser Group plc |
| Unilever PLC |
| Johnson & Johnson |
| Colgate-Palmolive Company |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| PZ Cussons |
| The Procter & Gamble Company |
| Others |
Supply & Pricing Matrix
Captive surfactant sourcing through backward integration into German and Swiss specialty chemical houses anchors both supply security and pricing power for leading European formulation brands. This integration choice insulates premium portfolios from palm kernel oil volatility while compressing margin structures for mid-tier competitors dependent on spot-market alkyl polyglucoside purchases.
Pricing Analysis
Volume-mass liquid shower gels trade on thin margins through French hypermarkets and German drugstore chains, while solid-format bars and concentrated refills capture expanding margin pools in pharmacy and zero-waste specialty channels. Three-tier pricing structure across premium dermocosmetic, standard mass-market, and economy private-label levels stratifies according to dermatological certification tier and refill-system compatibility. Pricing pressure stems from ECHA-driven reformulation costs for microplastic-free body scrubs, which compress mass-market viability. Households in urban sustainability clusters show lowest price sensitivity, while economy-tier buyers in Mediterranean markets resist premium migration.
Supply Chain Analysis
Skilled cosmetic safety assessor scarcity in the Rhine-Ruhr and Basel manufacturing corridors extends new product registration timelines and elevates qualified toxicologist salaries. Supply concentration clusters in Germany, Switzerland, and France, with the Catalan chemical processing corridor feeding biodegradable surfactant feedstocks to formulation houses. Raw material dependencies center on Southeast Asian palm kernel oil, COSMOS-certified emulsifiers, and cold-process syndet bases. Single-source vulnerability pervades the three-firm control of certified emulsifier supply. Distribution runs through pharmacy wholesale networks in France, cooperative grocery refill stations in Germany, and British independent health store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European bath and shower formulation chemistry is transitioning from petrochemical surfactants to plant-derived alkyl polyglucosides, with enzyme-cleansing hybrid formats displacing legacy preservative-loaded liquid gels. This technology shift rewards brands with captive research infrastructure and penalizes those with stranded liquid-filling assets.
For Market Incumbents: Deploy captive NIVEA-equivalent research infrastructure to accelerate dermatological dossier preparation and compress registration timelines against the cosmetic safety assessor shortage. Consolidate position through exclusive supply agreements with the three German and Swiss COSMOS-certified emulsifier suppliers, locking out mid-tier competitors. Channel control through pharmacy retail partnerships in underdeveloped Spanish and Portuguese markets defends margin pools against refill-system commoditization. For New Entrants and Emerging Players: Launch via zero-waste retail partnerships in Copenhagen, Vienna, and Barcelona districts, bypassing conventional packaged-goods distributor gatekeeping. Target the Portuguese and Spanish pharmacy channel whitespace where dermatological brand awareness lags French benchmarks. Position around effervescent bath bomb and enzyme-cleansing hybrid formats for professional spa channel expansion, exploiting Alpine thermal destination procurement concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to German personal care conglomerates seeking solid-format manufacturing capacity and dermatological credibility assets. Five-to-ten-year viability hinges on CSRD supply chain disclosure compliance positioning for EU institutional procurement frameworks. Watch for ECHA substance restriction expansions beyond microplastics as the inflection signal for forced portfolio delisting and acquisition opportunity creation.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Station Network Expansion | EU Green Deal packaging mandates in France and Germany accelerate captive demand for concentrated formats. |
| Biodegradable Surfactant Backward Integration | Rhine-Ruhr manufacturing corridor investments insulate margins from Southeast Asian palm kernel oil volatility. |
| Enzyme-Cleansing Hybrid Format Development | Convergence of protease biochemistry with solid bar manufacturing opens professional spa channel placement. |
| Pharmacy Channel Dermatological Certification | ANSM cosmetic safety assessments in Paris and Lyon elevate dossier preparation standards beyond baseline EU requirements. |
| Zero-Waste Retail Partnership Formation | British independent health store networks and French cooperative grocery bulk stations disintermediate packaged goods distributors. |
Research Methodology
Independent corroboration across primary interviews with brand managers, category buyers at French pharmacy chains, German supply planners, and British health store proprietors underwrites the qualitative findings. Secondary validation draws from REACH substance registration databases, ECHA restriction proposals, EU Green Deal policy documents, and Nielsen retail audit data for bath and shower categories. Bottom-up segment sizing triangulates against top-down macroeconomic anchors across the European personal care sector.
Comparable-period anchoring to historical volume and value trajectories structures the projection framework across the analysis window. Segmentation dimensions span product format, end-user tier, application channel, and surfactant chemistry type, with regional regulatory cluster effects modeled separately. CAGRs derive from trend-line extrapolation adjusted for technology substitution rates, ECHA compliance cost pass-through assumptions, and refill station deployment curves in named urban sustainability clusters.
The model assumes a particular technology adoption path; alternative pathways for solid-format syndet bar manufacturing would alter the outlook if cold-process scalability constraints prove binding. Forecasts reflect assumptions about ECHA enforcement intensity, palm kernel oil certification penetration, and pharmacy channel expansion rates in Mediterranean markets. Material deviation in REACH substance restriction timing or EU Green Deal packaging mandate implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market