
 Bathtub Market | 2026-2036
Bathtub Market Size, Share, and Industry Trends Forecast 2026-2036
Bathtub Market Intelligence
The bathtub category is consolidating around a sharp split between artisanal stone-cast vessels priced above five thousand dollars and mass-produced acrylic units sold through big-box retail. Kohler Co. leverages its captive foundry network to control cast-iron supply from raw pig iron through enamel finishing. TOTO Ltd. anchors its position with sensor-integrated hydrotherapy systems that command specification in luxury hotel contracts. Jacuzzi Inc. differentiates through proprietary jet configurations protected by decades of fluid-dynamics patents.
A bathtub is a fixed sanitary fixture designed for human immersion bathing, typically manufactured from acrylic sheet vacuum-formed over fiberglass reinforcement, cast iron with vitreous enamel coating, or engineered stone resin composites, and engineered to hold between 40 and 80 gallons while draining through a 1.5-inch to 2-inch waste outlet. Freestanding sculptural forms now capture the highest margin pools in residential renovation as consumers prioritize bathroom aesthetics over utilitarian function. Acrylic dominates volume production due to its thermoformability and repairability, though cast iron sustains preference in heritage restoration and acoustic-dampening applications. The hotel end-user segment leads commercial specification as wellness tourism operators install oversized soaking tubs and hydrotherapy systems to differentiate guest experiences.
The EPA WaterSense program and EU Ecodesign Directive impose maximum flow-rate thresholds that manufacturers must satisfy for market access in North America and Europe. China's GB standards for sanitary ceramics and Japan's JIS benchmarks for material safety create additional compliance layers for exporters targeting Asia-Pacific demand. ASTM E84 surface-burning ratings and ADA accessibility guidelines in the United States further constrain design freedom for walk-in and wheelchair-accessible configurations. Stakeholders must monitor how tightening water-efficiency thresholds in California and the European Union interact with consumer preference for deeper fill volumes and larger tub footprints.
Market Dynamics
Water-efficiency mandates from the EPA and EU Ecodesign Directive are compressing fill volumes while consumers demand deeper soaking experiences, creating a specification tension that manufacturers resolve through dual-drain systems and smart-fill sensors.
Growth Catalysts
- Wellness tourism infrastructure:Luxury hospitality operators in Germany and the United States are specifying hydrotherapy suites as competitive differentiators, driving premium vessel procurement.
- REACH material compliance:EU chemical safety standards for resin composites are accelerating substitution of traditional gel-coat formulations with low-VOC alternatives.
- Heritage restoration cycles:Municipal preservation incentives in Boston and Charleston sustain demand for cast-iron enamel reproductions matching early-20th-century specifications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic sheet production depends on MMA monomer supply concentrated in Gulf Coast refineries, exposing margins to energy price swings.
- Freight density economics:Bulky bathtub dimensions limit container utilization rates below 60%, inflating landed costs for imported stone-resin vessels.
- Skilled enamel application scarcity:Vitreous coating expertise concentrates in aging workforces across Ohio and Pennsylvania foundries, constraining cast-iron output expansion.
Strategic Opportunities
- ADA-compliant walk-in segments:Aging-in-place renovation demand in Florida and Arizona outpaces current accessible product availability, creating specification gaps for grab-integrated designs.
- Carbon-neutral material certification:EU Green Deal procurement preferences for construction products with Environmental Product Declarations favor recycled-content stone composites.
- Direct-to-installer platforms:Specialized logistics networks bypassing distributor markups are capturing renovation contractor volume in California metropolitan corridors.
Industry Challenges
- Cross-jurisdiction certification backlog:Simultaneous EPA WaterSense, CSA B45, and IAPMO listings require 14-18 month validation timelines, delaying new product launches.
- Legacy plumbing rough-in incompatibility:Freestanding sculptural forms often conflict with slab-on-grade drain locations common in 1970s-1990s US residential stock, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathtub Market |
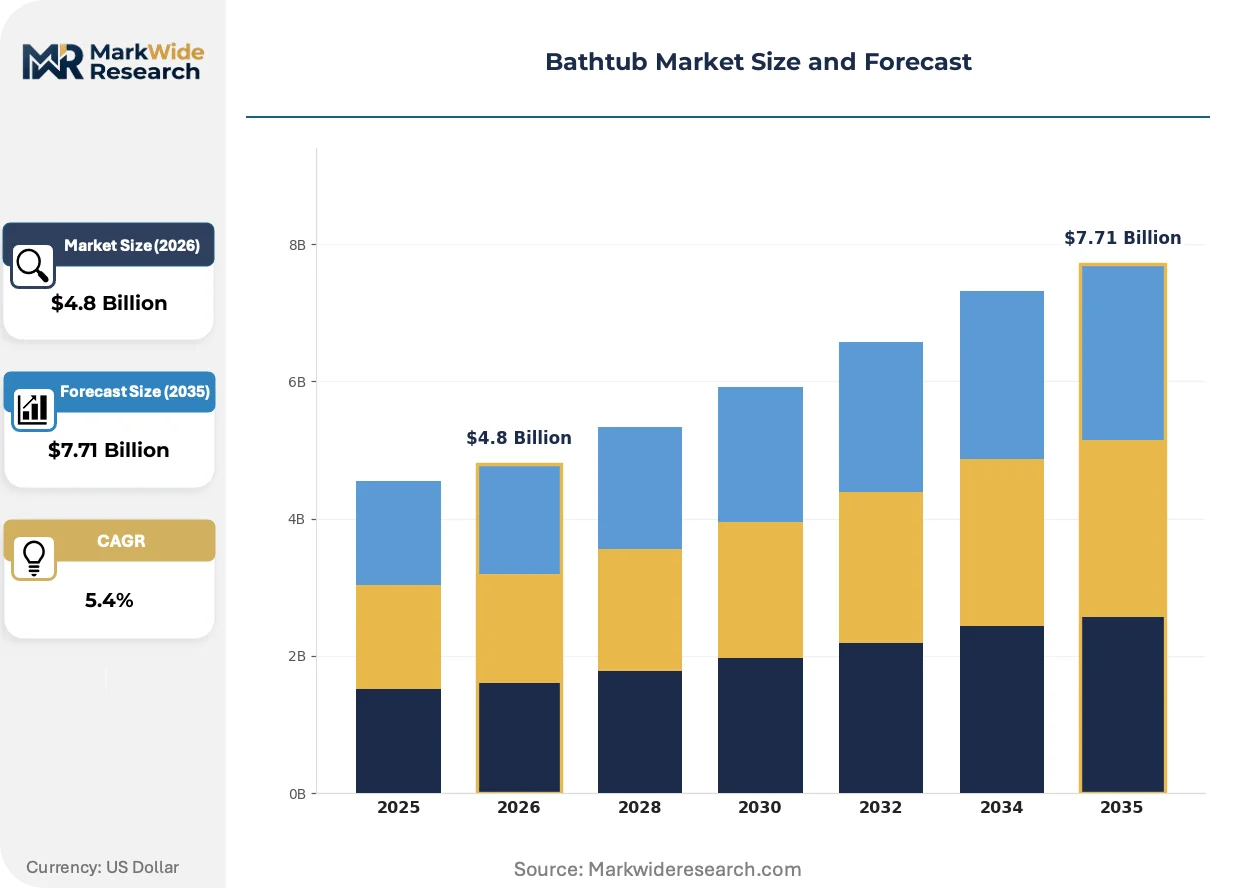
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Alcove, Corner, Drop-in Material: Acrylic, Fiberglass, Cast Iron, Stone End User: Residential, Hotels, Spas, Fitness Centers Installation Type: Walk-in, Standard, Wheelchair Accessible, Shower-Tub Combo |
| Companies Covered | Kohler Co., TOTO Ltd., Jacuzzi Inc., Duravit AG, Roca Group, American Standard, Villeroy & Boch AG, LIXIL Corporation, Kangjian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathtub Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are converging to redefine bathtub performance standards, with manufacturers racing to reconcile sustainability mandates against durability expectations.
Engineered stone resin composites incorporating recycled mineral filler are expanding into mid-market residential renovation as fabricators achieve price parity with premium acrylic. Multi-family developers in Texas and Georgia are specifying these vessels for scratch resistance and thermal retention. The technology is expanding into hospitality specification previously reserved for solid-surface or cast-iron alternatives.
California's Title 20 appliance efficiency regulations now mandate maximum 55-gallon fill volumes for standard bathtubs, with compliance verification through third-party HVI certification. Manufacturers respond with tapered wall designs maintaining perceived depth while reducing water volume. The hotel segment faces acute pressure as wellness operators balance guest experience expectations against municipal water restrictions.
Design-build firms are consolidating material procurement through exclusive supplier arrangements, displacing traditional distributor relationships in major metropolitan renovation markets. These partnerships bundle fixture specification with installation warranty coverage. The pattern is most visible in Chicago and Seattle where bathroom remodel cycles compress below 48-month intervals.
Bathtub Market Segmentation
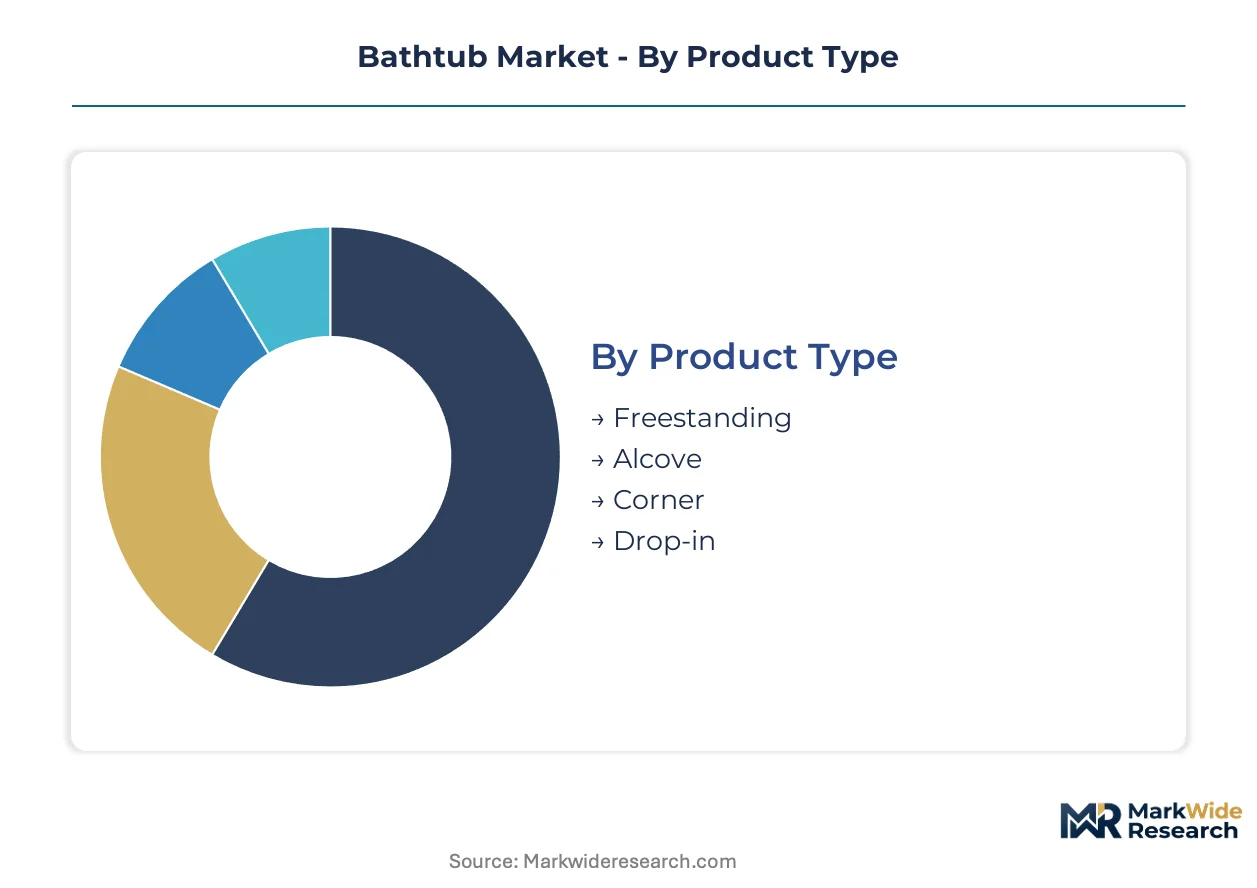
Segmentation in the bathtub market reveals how capital deployment, regulatory compliance, and end-use specifications fragment procurement patterns across vessel categories. Manufacturers align production assets to specific segment requirements rather than pursuing horizontal coverage.
Product Type:
Capital intensity escalates sharply with sculptural complexity and structural independence from wall anchoring.
- Freestanding:These sculptural vessels require reinforced floor structures and precise plumbing rough-in coordination. Demand concentrates in United States residential renovation markets where bathroom square footage expansion permits center-of-room placement. The segment commands premium pricing through aesthetic differentiation and installation complexity barriers.
- Alcove:Three-wall recessed installations dominate new construction volume through standardized rough-in dimensions and efficient material utilization. United States multi-family developers in Texas and Georgia specify these units for cost predictability and rapid installation cycles.
- Corner:Angular configurations maximize floor plan efficiency in compact European bathrooms and Japanese urban apartments. The geometry demands specialized acrylic thermoforming or stone casting molds.
- Drop-in:Rim-mounted vessels integrate with custom surround construction, sustaining specification in hospitality renovation where deck-mounted fixtures coordinate with stone or tile finishes.
Alcove units absorb the bulk of installed capacity; freestanding designs are expanding most quickly.
Material:
Raw material sourcing geography and processing energy intensity create divergent supply chain risk profiles across substrate categories.
- Acrylic:Vacuum-formed polymethyl methacrylate sheet over fiberglass reinforcement enables complex geometries and surface repairability. United States big-box retail channels move volume through price-accessible SKUs, though Gulf Coast petrochemical concentration exposes margin volatility.
- Cast Iron:Vitreous enamel coating over pig iron castings delivers acoustic dampening and thermal retention prized in heritage restoration. Foundry capacity concentrates in Ohio and Pennsylvania where aging skilled workforces constrain output expansion.
- Fiberglass:Gel-coat surface layers over chopped-strand mat construction serve entry-level residential replacement cycles with minimal capital equipment requirements.
- Stone:Engineered resin composites with mineral filler achieve price parity with premium acrylic while offering scratch resistance and thermal mass. German hospitality specifiers favor these vessels for wellness suite durability.
Acrylic commands the greatest production volume; stone composites are climbing the fastest as fabricators scale recycled-content formulations.
End User:
Procurement authority and specification complexity vary dramatically across customer types, from individual homeowners to institutional purchasing departments.
- Residential:Individual renovation decisions prioritize aesthetic coordination with vanity and tile selections. United States homeowners in Florida and Arizona drive accessible product demand through aging-in-place modifications.
- Hotels:Luxury hospitality operators in Germany and the United States specify hydrotherapy installations as competitive differentiators, with procurement centralized through design-build firm relationships.
- Spas:Wellness facility operators require specialized jet configurations and water sanitation systems, creating specification partnerships with hydrotherapy equipment specialists.
- Fitness Centers:Athletic facility procurement emphasizes durability and rapid turnover cleaning protocols, favoring non-porous surfaces and integrated grab features.
Residential channels absorb the bulk of unit volume; hotel specification is gaining share fastest through wellness tourism infrastructure investment.
Installation Type:
Regulatory compliance burden and installation labor specialization create distinct margin structures across mounting configurations.
- Standard:Conventional threshold entry with apron front or deck rim dominates replacement cycles and new construction. Installation skill requirements are commoditized across plumbing trades.
- Walk-in:Threshold-free entry with integrated door seals addresses mobility limitations without full wheelchair clearance. United States ADA-adjacent demand in Arizona and Florida outpaces current product availability.
- Wheelchair Accessible:Transfer seat heights, grab bar reinforcement, and clearance dimensions must satisfy ADA guidelines in United States commercial applications and comparable accessibility standards elsewhere.
- Shower-Tub Combo:Dual-function units maximize spatial efficiency in multi-family construction and compact European bathrooms, with curtain or door enclosure integration affecting specification.
Standard configurations absorb the bulk of current installation; walk-in designs are expanding most quickly through demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's industrial corridor anchors North American bathtub manufacturing, with Ohio and Pennsylvania foundries supplying cast-iron capacity and Texas petrochemical complexes feeding acrylic sheet production.
United States
Florida and Arizona homeowners drive aging-in-place renovation demand for walk-in and ADA-accessible configurations. The EPA WaterSense program mandates maximum flow-rate thresholds for market access. Chicago and Seattle design-build firms are consolidating procurement through exclusive supplier arrangements that bundle fixture specification with installation warranty coverage.
Germany
Luxury hospitality operators specify hydrotherapy suites as competitive differentiators, driving premium vessel procurement. The EU Ecodesign Directive and REACH chemical safety standards for resin composites accelerate substitution of traditional gel-coat formulations. Bavarian wellness tourism infrastructure investment sustains specification partnerships with hydrotherapy equipment specialists.
China
GB standards for sanitary ceramics and JIS benchmarks for material safety create compliance layers for exporters targeting Asia-Pacific demand. Yangtze River Delta fabricators scale engineered stone resin composites with recycled mineral filler to achieve price parity with premium acrylic. Pearl River Delta manufacturers supply multi-family developers in Texas and Georgia with cost-predictable alcove units.
Japan
Urban apartment density maximizes demand for corner configurations that optimize compact bathroom footprints. METI efficiency guidelines and JIS material safety benchmarks constrain design freedom for imported products. Osaka-based hospitality specifiers favor sensor-integrated hydrotherapy systems for luxury hotel contracts.
United Kingdom
Heritage restoration cycles in conservation areas sustain demand for cast-iron enamel reproductions matching early-20th-century specifications. The EU Green Deal procurement preferences favor construction products with Environmental Product Declarations. London design-build relationships are displacing traditional distributor channels in bathroom renovation markets.
Bathtub Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the bathtub category, with foundry-dependent cast-iron specialists facing different margin pressures than acrylic thermoformers. The vendor base clusters around three strategic tiers: integrated foundry operators controlling raw material through finishing, hydrotherapy technology licensors monetizing fluid-dynamics IP, and regional fabricators serving contractor-direct channels. Competitive moves center on captive supply chain control and exclusive design-build partnerships that bypass distributor markups.
Among North American integrated producers, Kohler Co. exemplifies the foundry-control archetype through captive pig iron-to-enamel operations, while Jacuzzi Inc. occupies the hydrotherapy technology tier with proprietary jet configuration expertise. TOTO Ltd. represents the sensor-integrated systems specialist position in luxury hospitality specification. These three anchors illustrate how competitive positioning stratifies across material control, technology licensing, and system integration vectors.
| Leading Market Players |
|---|
| Kohler Co. |
| TOTO Ltd. |
| Jacuzzi Inc. |
| Duravit AG |
| Roca Group |
| American Standard |
| Villeroy & Boch AG |
| LIXIL Corporation |
| Kangjian |
| Others |
Cost & Logistics Intelligence
Captive foundry-to-finish integration anchors Kohler's supply position across Ohio and Pennsylvania while simultaneously supporting premium pricing power in cast-iron enamel segments. This backward control over pig iron sourcing through vitreous coating application insulates margin structures from commodity volatility that pressures acrylic-dependent competitors.
Pricing Analysis
Value-based pricing anchored to wellness outcomes and guest experience metrics commands specification in luxury hospitality procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by material grade, with stone resin composites achieving price parity against premium acrylic through recycled-content certification. Pricing pressure stems from Gulf Coast petrochemical volatility squeezing acrylic sheet margins. Multi-family developers in Texas and Georgia exhibit highest price sensitivity, while German wellness tourism operators prioritize performance over unit cost.
Supply Chain Analysis
Refurbishment flows for cast-iron vessels sustain secondary market activity in heritage restoration corridors, with Boston and Charleston municipal programs incentivizing enamel reproduction matching early-20th-century specifications. Raw material sourcing concentrates in China for engineered stone resin composites, the United States for acrylic sheet production, and Germany for precision hydrotherapy system components. MMA monomer supply draws from Gulf Coast refineries, exposing acrylic fabricators to energy price swings. Single-source vulnerability concentrates in vitreous enamel expertise aging across Ohio and Pennsylvania workforces. Distribution runs through design-build firm partnerships displacing traditional distributor channels in Chicago and Seattle metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA WaterSense and EU Ecodesign Directive certification requirements erect barrier-to-entry moats favoring incumbents with established validation timelines and testing infrastructure.
For Market Incumbents: Hedge against acrylic margin compression by accelerating stone resin composite capacity expansion in Yangtze River Delta partnerships. Secure captive enamel application talent through apprenticeship pipelines in Ohio and Pennsylvania foundries before workforce attrition accelerates. Defensive consolidation around ADA-compliant walk-in product development addresses aging-in-place demand outpacing current availability in Florida and Arizona. For New Entrants and Emerging Players: Design-build firms represent the most accessible channel partner type for bypassing entrenched distributor relationships in California metropolitan renovation markets. White-space targets concentrate in ADA-adjacent walk-in configurations where specification gaps exceed current incumbent capacity. Direct-to-installer platforms bundle fixture procurement with installation warranty coverage, capturing contractor volume through logistics specialization rather than brand recognition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated foundry operators seeking hydrotherapy technology augmentation. Long-term viability favors targets with dual EPA WaterSense and EU Ecodesign certification completion, positioning for regulatory tightening across the analysis window. Acquisition target archetype: regional fabricators with established design-build partnerships and recycled-content stone composite formulations. Monitor California Title 20 enforcement patterns and EU Green Deal procurement preference implementation as inflection indicators for premium vessel demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Material Certification | EU Green Deal procurement preferences favor Environmental Product Declaration holders in German hospitality specification. |
| ADA-Compliant Product Line Expansion | Aging-in-place renovation demand in Florida and Arizona outpaces current accessible product availability. |
| Direct-to-Installer Platform Launch | Chicago and Seattle design-build relationships displace traditional distributor markups in metropolitan corridors. |
| Captive Foundry Capacity Expansion | Ohio and Pennsylvania enamel application expertise constrains cast-iron output growth without workforce investment. |
| Sensor-Integrated Hydrotherapy Development | Osaka-based hospitality specifiers prioritize TOTO-style system integration for luxury hotel contracts. |
Research Approach
Multi-period observation of EPA WaterSense certification timelines, EU Ecodesign compliance patterns, and hospitality procurement cycles anchored the trend analysis, supplemented by interviews with bathtub manufacturing executives, design-build firm procurement directors, foundry operations managers, hospitality FF&E specifiers, and plumbing contractor principals. Secondary validation drew from EPA regulatory filings, EU ECHA substance restriction updates, ASTM standard revision records, and customs trade data for acrylic sheet and engineered stone resin composite flows. Bottom-up unit shipment modeling triangulated against top-down construction spending and renovation cycle indicators.
Segment-weighting applied product type, material substrate, end-user category, and installation configuration dimensions across the modeling period. CAGRs derived from regression analysis of historical shipment volumes against construction permit data and hospitality development pipeline tracking. Industry-specific forecast inputs incorporated water-efficiency mandate phase-in schedules and wellness tourism infrastructure investment announcements.
Caveats apply where California Title 20 enforcement intensity, EU REACH substance restriction expansion, or Gulf Coast petrochemical supply disruption could materially shift the outlook. Practitioners should monitor skilled enamel workforce attrition rates and design-build firm consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market