
 North America Toilet Seat Market | 2026-2036
North America Toilet Seat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Toilet Seat Market Analytics
The capital-intensity gap between automated manufacturing and manual assembly is collapsing across the North America toilet seat supply base. TOTO USA leverages ceramic-to-seat integration to sustain premium positioning in the smart toilet segment. Bemis Manufacturing Company anchors mid-market volume through captive plastic molding operations in Wisconsin. Kohler Co. differentiates via design-forward elongated models that command higher retail placement.
A toilet seat is a hinged sanitary fixture, typically molded from polypropylene, urea-formaldehyde, or engineered wood composites, designed to cover and provide seating access to a toilet bowl while enabling hygienic closure. The product serves residential, commercial, and institutional bathrooms by supporting user ergonomics, water efficiency, and infection control. Plastic material dominates unit volume due to cost scalability and moisture resistance, though smart product types represent the fastest-expanding margin pool as electronic bidet integration advances. Residential end users account for the largest share of replacement cycles, while hospitality applications drive specification-grade demand for elongated designs with antimicrobial coatings.
EPA WaterSense standards and ADA accessibility guidelines shape product dimension and flush-compatibility requirements across the United States, while Health Canada and CSA Group standards govern northern market entry. State-level plumbing codes in California and Texas increasingly mandate reduced water consumption, forcing manufacturers to recalibrate hinge mechanisms and bowl-seal geometry. Stakeholders must monitor evolving smart-product electrical safety certifications and the pace of municipal retrofit incentives to time capacity investments.
Market Dynamics
Residential bathroom renovation cycles across the United States and Canada are compressing replacement timelines, while EPA WaterSense mandates force simultaneous redesign of hinge geometry and bowl-seal interfaces to maintain flush efficiency.
Growth Catalysts
- Sun Belt Housing Construction:New residential development in Texas, Florida, and Arizona generates specification-grade demand for elongated designs with antimicrobial coatings.
- EPA WaterSense Certification:Federal low-flow compatibility requirements drive replacement of legacy seats in municipal retrofit programs and commercial hospitality renovations.
- Smart Toilet Integration:Electronic bidet functionality and heated surfaces expand addressable margin pools in premium residential and healthcare facility segments.
Market Restraints
- Polypropylene Feedstock Volatility:Petrochemical input cost swings compress margin stability for injection-molded product lines.
- Canadian Import Friction:Health Canada and CSA Group certification timelines create lag between US product launches and northern market entry.
- Manual Assembly Cost Floor:Hinge mechanism and soft-close damper installation resist full automation, anchoring labor costs in Wisconsin and Tennessee production bases.
Strategic Opportunities
- ADA-Compliant Elongated Designs:Accessibility guideline expansion in California and New York opens specification channels in institutional and senior housing verticals.
- Municipal Retrofit Incentives:State-level water conservation rebates in Texas and Colorado accelerate replacement velocity in existing housing stock.
- Antimicrobial Coating Convergence:Silver-ion and copper-infused surface technologies meet healthcare infection control standards while penetrating residential premium tiers.
Industry Challenges
- Electrical Safety Certification Timelines:UL and ETL testing protocols for heated and electronic bidet seats extend product development cycles by 4-6 months.
- Legacy Plumbing Compatibility:Non-standard bowl geometries in pre-1990 US housing stock complicate universal fit claims and drive return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Toilet Seat Market |
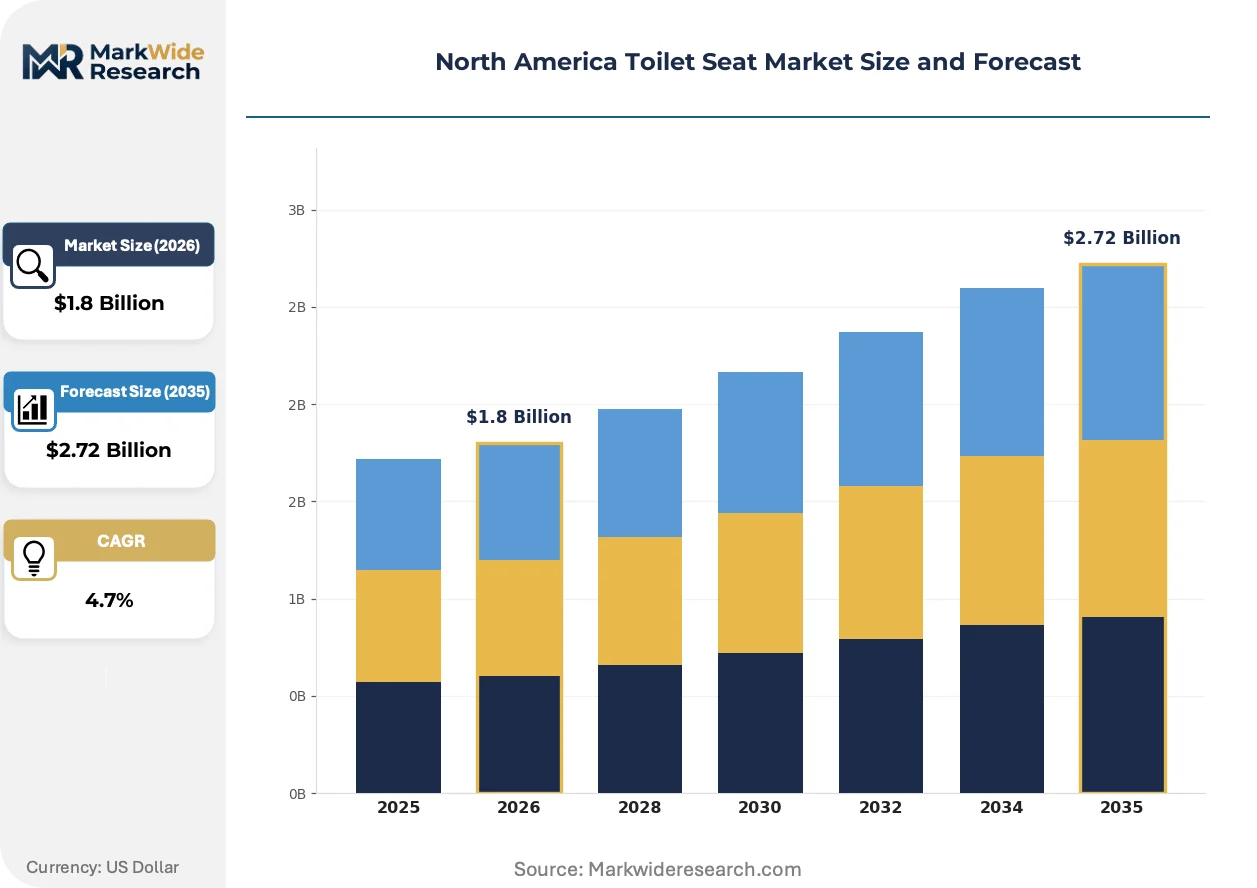
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Bidet, Portable, Smart Material: Plastic, Wood, Ceramic, Metal Design: Round, Elongated, Square, Custom End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | TOTO USA, Centoco, Kohler Co., Ferguson (PROFLO), Ginsey Home Solutions, Bemis Manufacturing Company, Delta Faucet Company, American Standard Brands, LIXIL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Toilet Seat Market Evolving Landscape
Smart functionality integration and surface material science are redefining product tier boundaries, while regulatory water efficiency mandates force concurrent mechanical redesign across the North American supply base.
Urea-formaldehyde thermoset compounds are supplanting basic polypropylene in mid-market residential channels. Home improvement retailers report accelerating shelf-space allocation to denser, warmer-to-the-touch surfaces. This material migration is compressing price gaps between economy and standard tiers while elevating baseline consumer expectations.
EPA WaterSense standards are tightening flush-volume compatibility requirements for replacement seats. Manufacturers must recalibrate hinge placement and seal geometry to maintain bowl performance at 1.28 gallons per flush. California and Texas plumbing code amendments are forcing the fastest product line adjustments, with national rollouts trailing state-specific SKUs by 8-12 months.
Direct-to-installer procurement via building supply cooperatives is fragmenting traditional wholesale distribution in commercial segments. Multi-family developers in Florida and Arizona now source elongated antimicrobial seats through pooled purchasing agreements rather than regional distributors. This channel compression squeezes intermediary margins while rewarding manufacturers with captive logistics capabilities.
North America Toilet Seat Market Segmentation
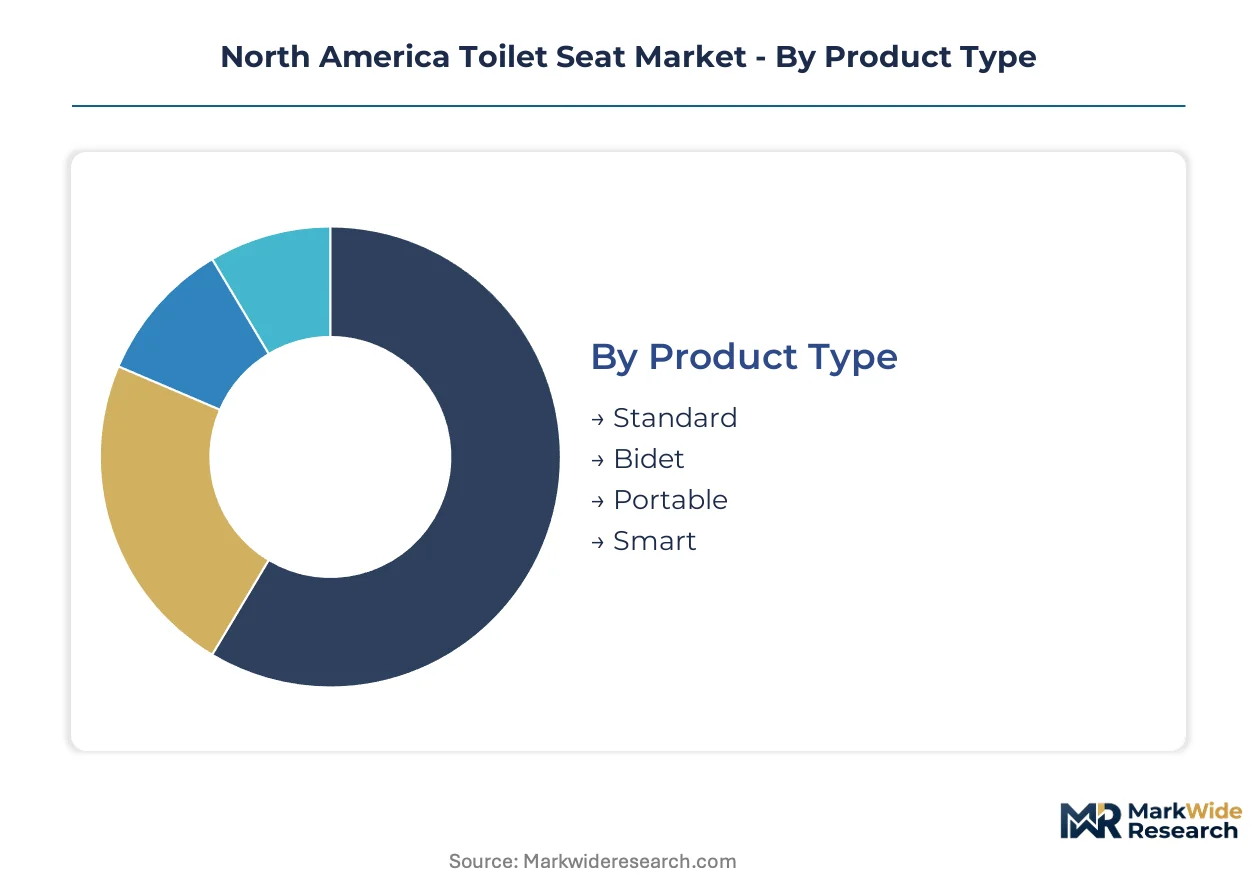
Channel dynamics in the North America toilet seat market vary sharply by segment complexity. Smart and bidet products flow through specialized plumbing distributors and direct-to-contractor platforms, while standard plastic seats dominate mass retail and home improvement channels.
Product Type:
Channel concentration shifts dramatically across complexity tiers, with electronic features forcing migration toward professional installer networks and away from self-service retail.
- Standard:Injection-molded polypropylene or urea-formaldehyde construction with basic hinge mechanisms. Home Depot and Lowe's capture the majority of volume in the US Sun Belt states where replacement cycles compress amid renovation activity. Big-box shelf space allocation favors antimicrobial coatings as a baseline feature.
- Smart:Electronic bidet integration with heated surfaces, remote controls, and sensor-activated functions. Healthcare facilities in California and senior housing developments in Florida drive specification-grade procurement through cooperative purchasing agreements. UL and ETL certification timelines extend product development cycles significantly.
- Bidet:Non-electronic water spray attachments requiring plumbing integration. Independent plumbing distributors in Texas and Arizona handle contractor-specified installations for municipal retrofit programs.
- Portable:Lightweight folding designs for recreational vehicles and temporary sanitation. Camping supply retailers and RV dealerships in Colorado and Utah concentrate seasonal demand.
Standard seats dominate installed base. Smart products are where expansion concentrates.
Material:
Cost tier alignment determines manufacturing location and margin structure, with premium materials anchoring captive production while commodity grades source from distributed molding networks.
- Plastic:Polypropylene homopolymer dominates unit economics through moisture resistance and color stability. Wisconsin-based captive molding operations supply mid-market volume to national retailers. Feedstock volatility from petrochemical inputs compresses margin predictability.
- Wood:Engineered composites and solid hardwoods serve design-forward residential renovations. Custom millwork channels in New York and California specify matching vanity aesthetics.
- Ceramic:Integrated bowl-and-seat systems for smart toilet platforms. TOTO USA's vertically integrated production in Georgia anchors premium positioning.
- Metal:Stainless steel hinges and structural reinforcements for high-traffic commercial installations. Institutional specifications in Texas and Illinois mandate vandal-resistant hardware.
Plastic anchors volume scale. Ceramic commands the steepest expansion trajectory.
Design:
Application requirements dictate geometry selection, with accessibility mandates and water efficiency standards forcing dimensional recalibration across replacement cycles.
- Elongated:Front-to-rear dimension exceeds round bowls by approximately two inches. ADA compliance requirements in California and New York accelerate specification in institutional and senior housing verticals. EPA WaterSense hinge placement standards demand concurrent redesign.
- Round:Compact footprint for pre-1990 housing stock with non-standard bowl geometries. Legacy compatibility challenges drive return rate elevation in Northeastern markets.
- Square:Contemporary aesthetic alignment for European-influenced bathroom design. Boutique hospitality specifications in Miami and Los Angeles concentrate niche demand.
- Custom:Bespoke dimensions for historic restoration and luxury residential. Artisan fabricators in Vermont and North Carolina serve preservation commission requirements.
Elongated designs dominate new construction specifications. Round configurations retain replacement base.
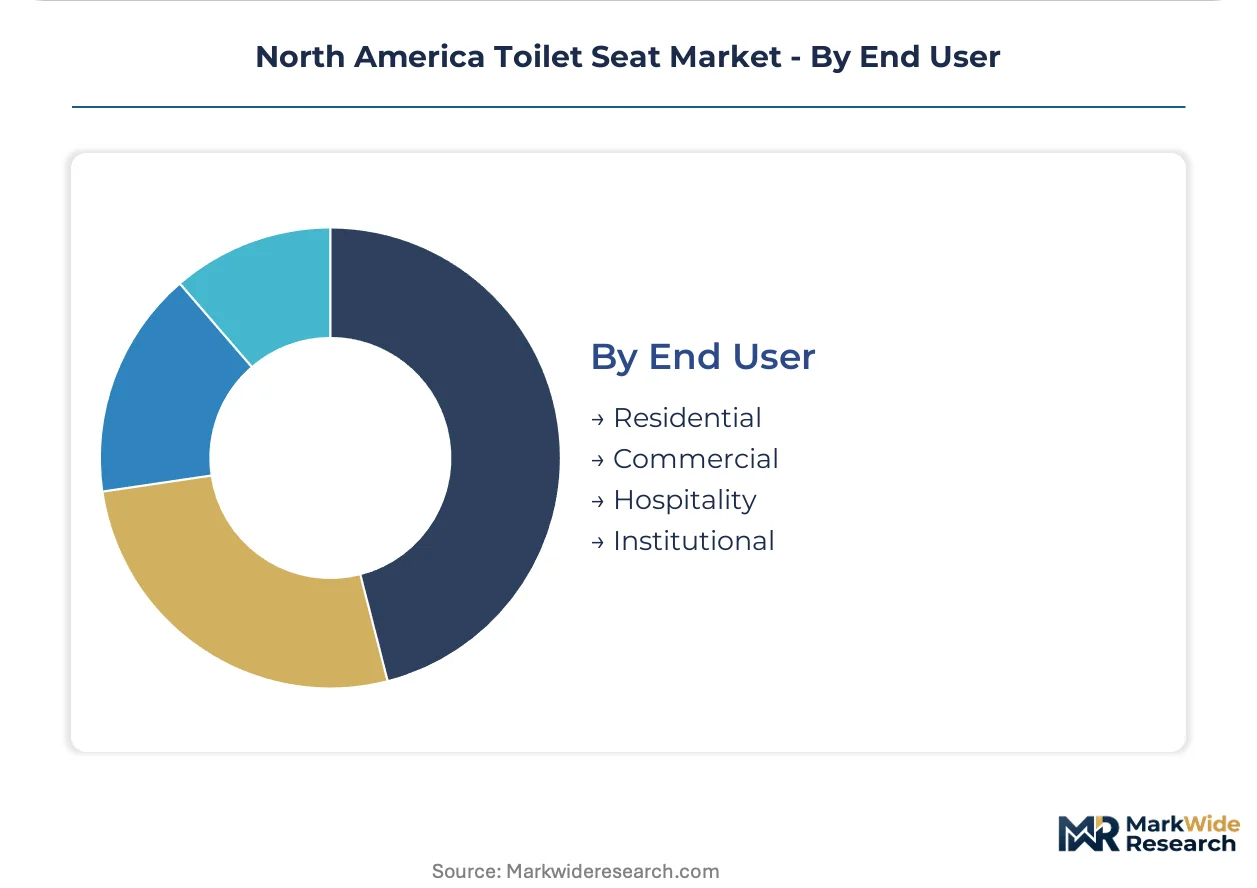
End User:
Customer type segments separate by procurement sophistication, with commercial and institutional buyers leveraging cooperative purchasing while residential remains fragmented.
- Residential:Replacement cycles compress to 7-10 years amid bathroom renovation frequency elevation. Home improvement retailers in Florida and Arizona capture renovation-driven demand.
- Commercial:Multi-family developers in Texas source through pooled purchasing agreements rather than regional distributors. Channel compression rewards manufacturers with captive logistics.
- Hospitality:Specification-grade elongated designs with antimicrobial coatings dominate new construction. Hotel renovation timelines in Las Vegas and Orlando align with seasonal demand patterns.
- Institutional:Healthcare facilities and educational buildings mandate infection control surfaces. Silver-ion coating specifications in California exceed national baseline requirements.
Residential segments anchor volume. Institutional channels are where specification value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where EPA WaterSense mandates and Sun Belt construction activity sustain premium placement, while Canadian certification friction compresses margin capture in cross-border distribution.
United States
Residential bathroom renovation cycles in Florida, Texas, and Arizona compress replacement timelines to seven-to-ten-year intervals. EPA WaterSense certification requirements force hinge geometry and bowl-seal redesigns to maintain flush efficiency at 1.28 gallons. Wisconsin-based captive plastic molding operations supply mid-market volume to national home improvement retailers.
Canada
Health Canada and CSA Group certification timelines create six-to-twelve-month lag between US product launches and northern market entry. Provincial water conservation rebates in British Columbia and Ontario accelerate municipal retrofit program participation. Quebec's institutional procurement channels specify ADA-compliant elongated designs for senior housing developments.
Mexico
Manufacturing cost advantages in Nuevo León and Jalisco attract injection-molding capacity for export-oriented production. Mexican plumbing code harmonization with US standards facilitates cross-border component sourcing. Bajío Region assembly operations serve price-sensitive segments in Central American export markets.
North America Toilet Seat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America toilet seat supply base. The market structure tiers into premium integrated-system providers, mid-market volume manufacturers with captive molding operations, and commodity assemblers sourcing distributed components. Three strategic archetypes dominate: vertically integrated smart-toilet specialists, Wisconsin-based plastic molding scale players, and design-forward brands commanding retail placement premiums. Competitive moves concentrate on ceramic-to-seat integration investments and direct-to-installer procurement channel compression.
Among US-based manufacturers, TOTO USA, Bemis Manufacturing Company, and Kohler Co. occupy distinct tier positions. TOTO USA exemplifies the vertically integrated archetype through Georgia-based ceramic production. Bemis Manufacturing Company anchors mid-market volume scale through Wisconsin captive molding. Kohler Co. represents design-forward positioning that commands elongated model retail premiums.
| Leading Market Players |
|---|
| TOTO USA |
| Centoco |
| Kohler Co. |
| Ferguson (PROFLO) |
| Ginsey Home Solutions |
| Bemis Manufacturing Company |
| Delta Faucet Company |
| American Standard Brands |
| LIXIL Corporation |
| Others |
Value Network & Pricing Analysis
Captive plastic molding capacity in Wisconsin and Tennessee generates scale economies that compress per-unit fixed costs while anchoring price floors for mid-market polypropylene seats. This concentration of injection-molding infrastructure simultaneously limits new entrant cost parity and sustains margin pools for manufacturers with backward-integrated resin handling.
Pricing Analysis
Configured-to-order pricing for ADA-compliant elongated designs with antimicrobial coatings commands spreads of 40-60% above standard round-seat SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material density, with EPA WaterSense-labeled products capturing placement premiums at home improvement retailers. Pricing pressure stems from polypropylene feedstock volatility tied to Gulf Coast petrochemical output fluctuations. Multi-family developers in Texas and Florida exhibit lowest price sensitivity due to specification-grade procurement protocols, while Northeastern replacement buyers facing legacy bowl compatibility issues drive highest discount sensitivity.
Supply Chain Analysis
Inbound logistics costs from Asian hinge-component suppliers through Los Angeles and Long Beach port complexes introduce 3-5 week variability in production scheduling. Wisconsin, Tennessee, and Georgia anchor North American supply concentration through captive molding, ceramic integration, and final assembly operations respectively. Raw material dependencies center on polypropylene homopolymer resin, urea-formaldehyde thermoset compounds, and electronic bidet components sourced from South Korean and Japanese manufacturers. Single-source vulnerability in soft-close damper mechanisms creates bottleneck exposure. Distribution runs through home improvement retail chains, cooperative purchasing agreements for multi-family developers, and specialized plumbing distributors for smart-product categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America toilet seat market functions as a defensive-moat industry where EPA WaterSense certification requirements create regulatory entrenchment that elevates switching costs for institutional buyers.
For Market Incumbents: Consolidate hinge mechanism and soft-close damper supply through captive production or exclusive supplier agreements to neutralize single-source vulnerability. Expand antimicrobial coating certification investment to exceed California healthcare facility specifications and lock out specification-grade competitors. Threat exposure concentrates in electronic bidet component sourcing from South Korean suppliers facing geopolitical friction.
For New Entrants and Emerging Players: Aftermarket installation service gaps in legacy housing stock with non-standard bowl geometries present white-space opportunities underserved by incumbent universal-fit claims. Target Northeastern and Midwestern replacement markets where return-rate elevation from compatibility failures creates demand for measurement and custom-fit services. Go-to-market angle: direct-to-installer partnerships with regional plumbing contractors bypassing big-box retail margin compression.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with ceramic-to-seat integration capabilities and captive molding infrastructure over pure-play assemblers. Long-term viability hinges on WaterSense certification entrenchment and smart-product electrical safety certification timelines. Acquisition target archetype: Wisconsin-based mid-market volume players with unexploited elongated design capacity. Signal to watch: municipal retrofit incentive program expansion in water-stressed states as inflection indicator for replacement velocity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Handling | Captive polypropylene processing in Wisconsin insulates margin pools from Gulf Coast petrochemical volatility. |
| ADA-Compliant Elongated Design Expansion | California and New York accessibility mandates open specification channels in senior housing verticals. |
| Antimicrobial Coating Certification Investment | Silver-ion surface technology exceeds California healthcare standards and penetrates residential premium tiers. |
| Direct-to-Installer Channel Development | Cooperative purchasing agreements with Texas multi-family developers compress intermediary margin capture. |
| Electronic Bidet UL/ETL Certification Acceleration | Reduced 4-6 month safety testing cycles enable faster product launches against smart-toilet specialists. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA WaterSense certification databases, Health Canada product registry filings, and North American customs trade data. Primary interviews engaged product development directors at captive molding operations, procurement managers at multi-family development firms, specification writers for hospitality renovation projects, and category buyers at national home improvement retailers. Secondary validation drew from CSA Group standard documentation, state plumbing code amendments in California and Texas, and petrochemical feedstock pricing indices. Bottom-up unit shipment modeling triangulated against top-down construction spending allocation estimates.
Segmentation dimensions modeled include product type complexity tier, material composition grade, design geometry compliance category, and end-user procurement sophistication across the projection horizon. CAGRs were derived from replacement cycle compression rates, new housing construction permits, and municipal retrofit program participation trajectories. Industry-specific forecast inputs incorporated WaterSense certification adoption curves and smart-product electrical safety certification backlog estimates.
Forecasts assume regulatory continuity in EPA WaterSense standards and ADA accessibility guidelines; material policy shifts in federal water efficiency mandates or state plumbing code harmonization would require re-modeling. Practitioners should keep alternative scenarios live as polypropylene feedstock volatility and cross-border certification friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Shower Curtain Market