
 Bathroom Pods Market | 2026-2036
Bathroom Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Pods Market Insights
Glass-reinforced polymer composites are repositioning steel-framed bathroom pods across mid-rise hospitality and healthcare construction. Walker Modular leverages captive GRP molding capacity to sustain margin control across British social housing tenders. Bathsystem S.p.A. anchors Mediterranean supply through dedicated acrylic-forming lines in northern Italy. Offsite Solutions dominates London's high-rise residential pipeline with volumetric pod-to-core installation protocols.
A bathroom pod constitutes a factory-assembled, self-contained wet room integrating sanitary ware, waterproofed enclosure panels, MEP rough-ins, and finished surfaces, delivered as a single lift-in module for crane or corridor insertion. Units typically ship with pre-tested drainage gradients and sealed junctions to eliminate site-based wet trades. Composite material pods command widening specification share due to superior strength-to-weight ratios and corrosion immunity in high-turnover hospitality settings. New construction installation type leads volume absorption as developers sequence modular bathroom delivery with structural frame completion, while renovation channels face access constraints in occupied buildings.
CE marking under the EU Construction Products Regulation governs structural integrity and fire reaction performance for pods installed across European member states. Germany's KBA-adjacent building product certification bodies enforce acoustic isolation standards that filter out non-compliant imports in multi-family residential applications. The UK's Building Safety Regulator post-Grenfell mandates enhanced traceability for volumetric bathroom suppliers serving structures above 18 meters. Stakeholders must monitor evolving embodied-carbon disclosure requirements that threaten to disqualify steel-intensive pod configurations from public procurement frameworks.
Market Dynamics
Prefabricated wet-room manufacturers face a structural squeeze between France's RE2020 embodied-carbon thresholds and Germany's KBA-adjacent acoustic isolation mandates, forcing material substitution decisions that ripple through composite supply chains and steel-framed pod economics.
Growth Catalysts
- France's RE2020 environmental regulations:Thermally efficient composite pod structures gain specification share as developers document lifecycle carbon performance for public procurement eligibility.
- Hospital construction pipelines:Healthcare facilities in the United Kingdom absorb volumetric bathroom units to compress infection-control commissioning timelines and eliminate site-based wet trades.
- Glass-reinforced polymer molding capacity:Captive GRP fabrication lines enable margin control against volatile steel input costs and accelerate delivery schedules for social housing tenders.
Market Restraints
- Resin and fiberglass input cost volatility:Composite pod manufacturers face margin compression when petrochemical feedstock prices spike, limiting price pass-through in fixed-price construction contracts.
- UK Building Safety Regulator traceability mandates:Post-Grenfell documentation requirements for structures above 18 meters extend sales cycles and disqualify smaller fabricators lacking certified quality systems.
- Site access constraints in occupied buildings:Renovation channel penetration stalls where corridor dimensions and existing MEP infrastructure prevent crane or corridor insertion of factory-assembled modules.
Strategic Opportunities
- Netherlands modular residential acceleration:Dutch government housing production targets create absorption capacity for pod-to-core installation protocols in mid-rise timber-frame construction.
- CE marking convergence with CSRD disclosure:EU Construction Products Regulation structural integrity certification aligns with emerging embodied-carbon reporting, rewarding early-compliant composite suppliers.
- Digital twin integration with BIM workflows:Factory-level MEP pre-testing data feeds directly into building information models, compressing commissioning timelines for hospitality chains.
Industry Challenges
- Multi-craft technician scarcity:Pod assembly requires workers certified across waterproofing, MEP rough-in, and finish carpentry, creating recruitment bottlenecks in Northern England manufacturing clusters.
- Fire reaction performance certification timelines:Extended testing protocols for composite enclosure panels delay product launches and lock capital in work-in-progress inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Pods Market |
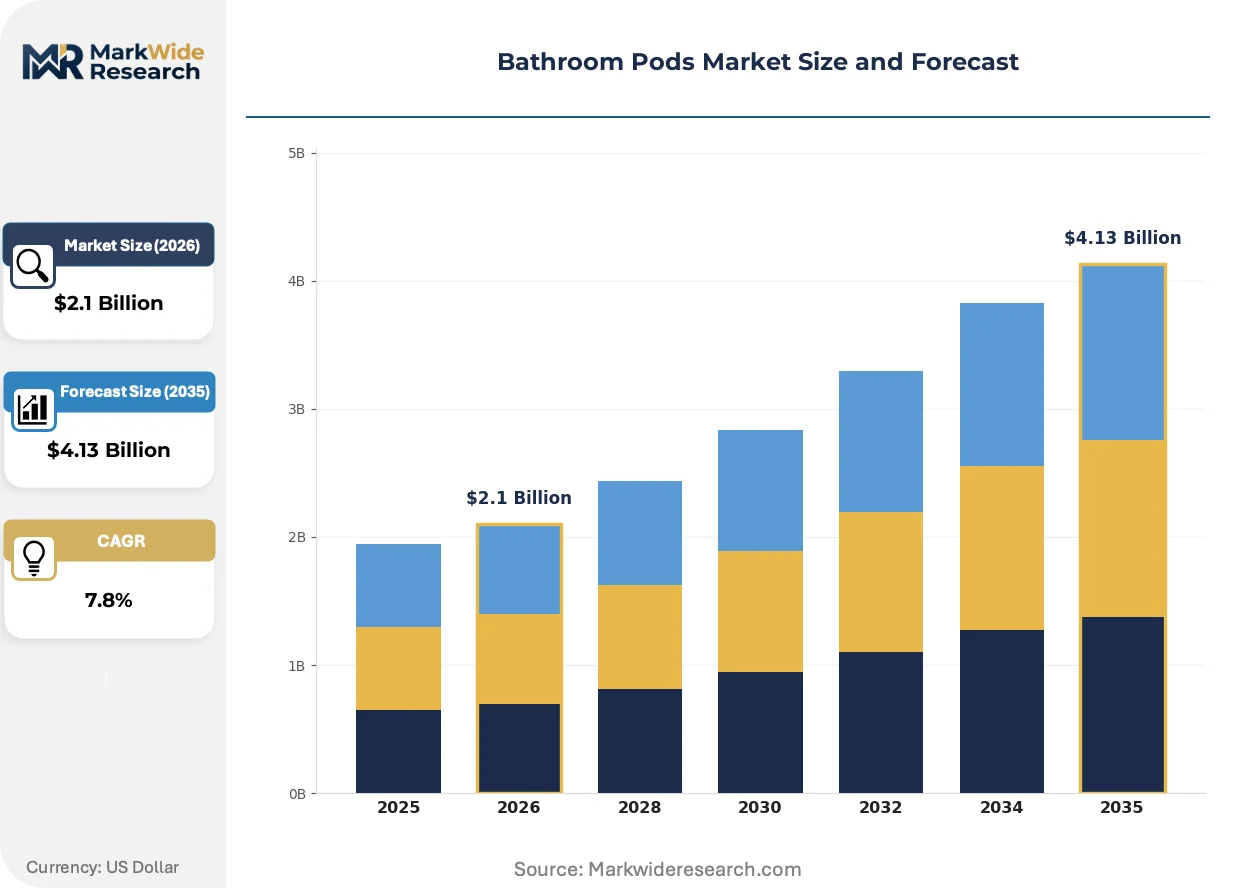
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefab Units, Modular Bathrooms, Shower Pods, Integrated Solutions End User: Residential Projects, Commercial Buildings, Hospitality, Healthcare Facilities Installation Type: New Construction, Renovation, Temporary Setup, Permanent Installation Material: Fiberglass, Acrylic, Steel, Composite |
| Companies Covered | Walker Modular, Bathsystem S.p.A, Offsite Solutions, Sanika, StoneBathwear, Roca Sanitario, S.A., Altor Industries, Triton Showers Limited, CIMC Modular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Pods Market Trends and Innovations
Digital fabrication and regulatory carbon accounting are compressing traditional boundaries between factory production and site assembly, redefining competitive advantage around data continuity rather than manufacturing scale alone.
Glass-reinforced polymer composite enclosures are unifying structural, waterproofing, and finish functions into monolithic molded shells. Hospitality developers in Manchester and London specify these units for high-turnover hotel rooms where corrosion immunity and rapid replacement cycles matter. This material convergence is unifying supply chains previously fragmented across steel framers, membrane applicators, and tile subcontractors.
REACH substance restrictions and the EU Green Deal carbon border adjustments are elevating documentation burdens for imported steel-framed pods. Manufacturers with EU-based composite molding operations capture specification share as procurement teams screen suppliers for embodied-carbon compliance. German multi-family residential tenders now filter out non-compliant imports through KBA-adjacent certification bodies enforcing acoustic isolation standards.
Design-build contracts are displacing traditional general contractor-led procurement for modular hotel projects. Hospitality chains in the United Kingdom now source bathroom pods directly from fabricators, inserting units during structural frame completion rather than through tiered subcontractor networks. This channel compression is most visible in London's high-rise residential pipeline, where volumetric suppliers coordinate directly with structural engineers for pod-to-core integration.
Bathroom Pods Market Segmentation
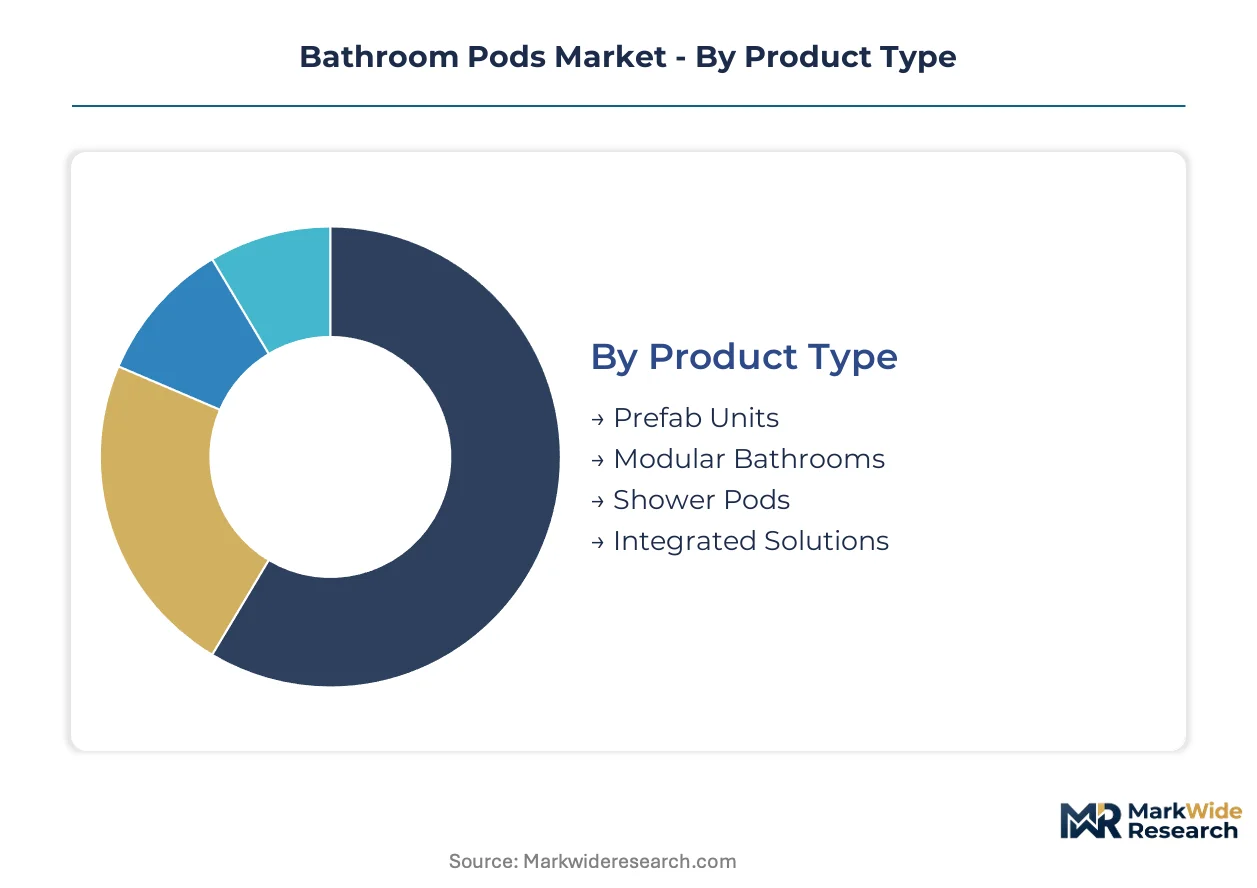
Bathroom pod procurement decisions hinge on lifecycle cost calculations that vary sharply across building types and installation contexts. Segmentation reveals where prefabrication economics outperform traditional wet construction.
Product Type:
Upgrade cycles for hospitality and healthcare assets drive specification divergence between standardized commodity units and performance-engineered systems.
- Prefab Units:Factory-assembled enclosures with pre-fitted sanitary ware and sealed waterproofing membranes. Demand concentrates in United Kingdom social housing tenders where capital budgets prioritize first-cost minimization over customization flexibility.
- Modular Bathrooms:Volumetric steel or composite-framed pods with integrated MEP rough-ins and finished surfaces. Manchester and London hotel developers specify these for mid-rise projects where crane insertion during structural frame completion compresses construction schedules.
- Shower Pods:Compact wet-room modules optimized for footprint efficiency in space-constrained renovations.
- Integrated Solutions:Custom-engineered units with embedded smart fixtures and digital control systems for premium hospitality segments.
Prefab Units sit at the top of the volume ranking, with Modular Bathrooms climbing the fastest.
End User:
Cost tier stratification separates public procurement frameworks from private developer specifications.
- Residential Projects:Multi-family developers in Germany absorb thermally efficient composite pods to meet tightened building energy codes. France's RE2020 embodied-carbon thresholds filter specification toward EU-manufactured units with documented lifecycle performance.
- Commercial Buildings:Office-to-residential conversions in London's high-rise pipeline deploy volumetric pods to eliminate wet-trade coordination in tight urban sites.
- Hospitality:High-turnover hotel chains specify corrosion-immune GRP enclosures for rapid replacement cycles.
- Healthcare Facilities:United Kingdom NHS trusts procure infection-control-optimized pods with seamless antimicrobial surfaces and pre-tested drainage gradients.
Residential Projects capture the largest installed base, while Healthcare Facilities gain share fastest as infection-control commissioning timelines tighten.
Installation Type:
Application context determines whether crane insertion logistics or occupied-building access constraints govern procurement.
- New Construction:Structural frame sequencing allows direct pod-to-core integration with MEP pre-testing. Offsite Solutions coordinates volumetric delivery with structural engineers for London high-rise residential towers.
- Renovation:Corridor dimension limits and existing infrastructure block crane insertion in occupied buildings, stalling penetration despite lifecycle cost advantages.
- Temporary Setup:Rapid-deployment units for disaster relief and interim healthcare capacity.
- Permanent Installation:Standard procurement for ground-up development with full building lifecycle integration.
New Construction dominates volume absorption, though Renovation channels face structural access barriers that limit expansion.
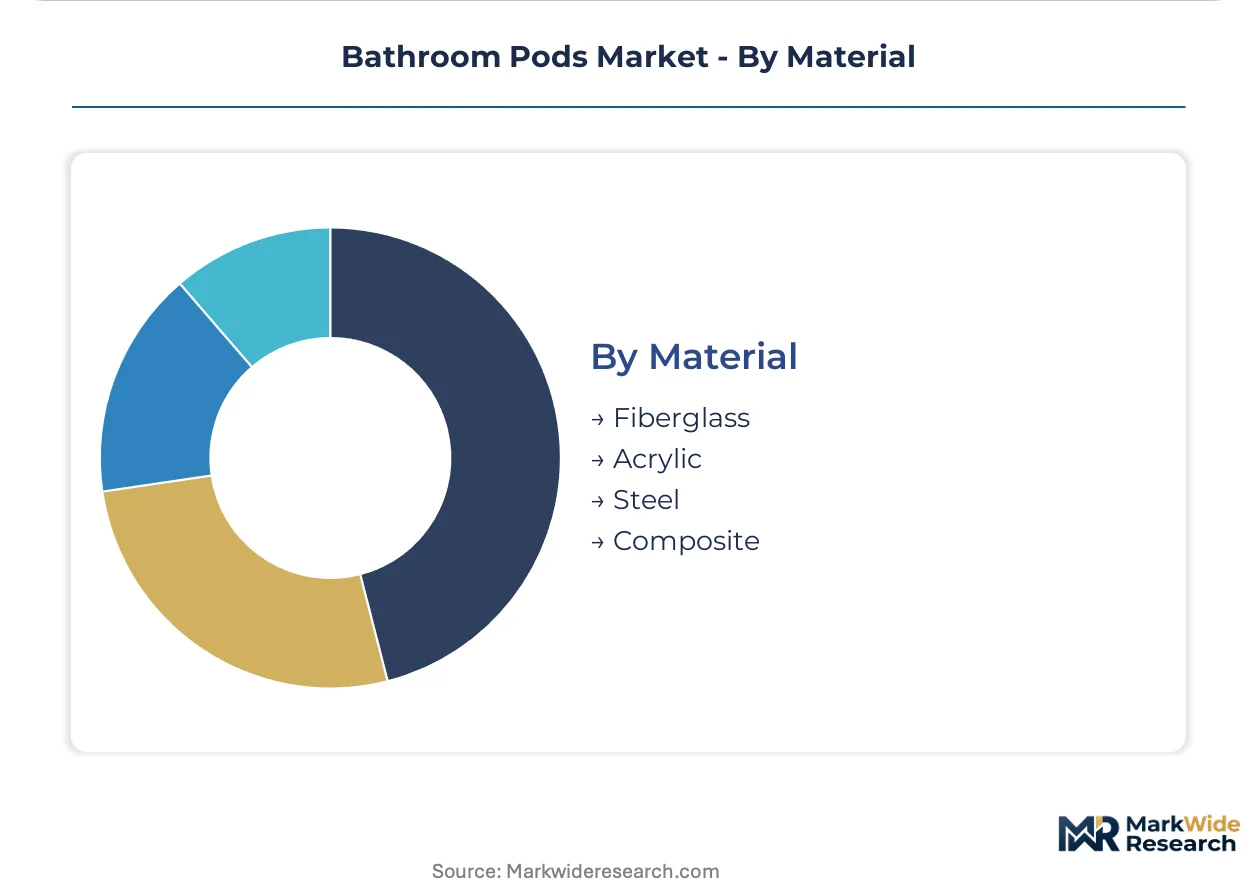
Material:
Margin structure varies with input cost volatility and certification burden across substrate categories.
- Fiberglass:Glass-reinforced polymer composites unify structural, waterproofing, and finish functions in monolithic molded shells. Walker Modular leverages captive GRP molding capacity to sustain margin control against volatile steel input costs.
- Acrylic:Thermoformed surfaces with high gloss finish retention for premium hospitality specifications. Bathsystem S.p.A. anchors Mediterranean supply through dedicated forming lines in northern Italy.
- Steel:Traditional framed construction facing margin compression from REACH substance restrictions and EU Green Deal carbon border adjustments.
- Composite:Hybrid material systems combining fiber reinforcement with polymer matrices for strength-to-weight optimization.
Fiberglass leads specification share in volume terms, with Acrylic expanding most quickly in Mediterranean hospitality markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom construction clusters absorb the dominant share of European bathroom pod procurement, with Manchester and London hotel pipelines sequencing modular wet-room delivery alongside structural frame completion. Developers compress commissioning timelines by eliminating site-based wet trades through factory-pre-tested drainage systems.
United Kingdom
NHS trusts procure infection-control-optimized pods with seamless antimicrobial surfaces to accelerate hospital commissioning timelines. The Building Safety Regulator mandates enhanced traceability documentation for volumetric suppliers serving structures above 18 meters. London's high-rise residential pipeline coordinates pod-to-core integration directly between fabricators and structural engineers.
Germany
Multi-family residential developers specify thermally efficient composite pods to comply with tightened national building energy codes. KBA-adjacent certification bodies enforce acoustic isolation standards that filter non-compliant imports from specification lists. North Rhine-Westphalia manufacturing clusters concentrate captive GRP molding capacity for margin control against volatile input costs.
France
Public procurement frameworks prioritize thermally efficient composite structures eligible under RE2020 embodied-carbon thresholds. Developers document lifecycle carbon performance to maintain tender eligibility for state-funded housing projects. Île-de-France hospitality developers accelerate procurement of prefabricated wet-room units to compress construction schedules for urban hotel assets.
Italy
Mediterranean hospitality chains specify acrylic-forming line output for premium bathroom pod configurations in resort developments. Northern Italian manufacturing anchors regional supply through dedicated thermoforming capacity serving French and Spanish export markets. Emilia-Romagna fabricators coordinate composite enclosure delivery with timber-frame construction timelines for Dutch modular residential projects.
Netherlands
Government housing production targets create absorption capacity for pod-to-core installation protocols in mid-rise timber-frame construction. National building codes favor factory-assembled modules with pre-tested MEP systems over site-built wet rooms. Randstad urban developers sequence bathroom pod delivery with structural frame completion to compress overall project timelines.
Bathroom Pods Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators invest in captive GRP molding lines to insulate margins from petrochemical feedstock volatility. The vendor base stratifies across three tiers: multinational plumbing fixture conglomerates with modular divisions, mid-scale regional specialists with certified quality systems, and project-specific fabricators lacking traceability documentation. Two strategic archetypes occupy distinct positions: composite-focused molders leveraging strength-to-weight advantages in high-rise applications, and steel-framed traditionalists facing margin compression from REACH substance restrictions. Geographic expansion and portfolio diversification represent the dominant competitive vectors as suppliers chase Dutch modular residential acceleration and UK healthcare facility pipelines.
Among British fabricators, Walker Modular occupies a position exemplifying the composite-focused archetype through its captive molding infrastructure, while Offsite Solutions anchors the scale-driven tier serving London's volumetric residential demand. Bathsystem S.p.A. represents the Mediterranean specialist model with dedicated acrylic-forming capacity. These three entities collectively illustrate how material specialization and geographic clustering determine competitive positioning across distinct national procurement frameworks.
| Leading Market Players |
|---|
| Walker Modular |
| Bathsystem S.p.A |
| Offsite Solutions |
| Sanika |
| StoneBathwear |
| Roca Sanitario, S.A. |
| Altor Industries |
| Triton Showers Limited |
| CIMC Modular |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock indices cascade through bathroom pod manufacturing into three distinct pricing tiers that separate GRP composite units from steel-framed alternatives and premium acrylic configurations. Input cost volatility at resin and fiberglass suppliers compresses margins for composite fabricators serving fixed-price social housing contracts in the United Kingdom.
Pricing Analysis
Input-cost pass-through operates through project-based long-term offtake contracts for hospitality chains, with price differentiation hinging on CE marking tier and volume scale. Premium-mid-economy pricing differentiation separates infection-control-optimized NHS-specified pods from standard social housing units. Cost compression in steel-framed segments is intensifying because REACH substance restrictions and EU Green Deal carbon border adjustments erode competitiveness against composite alternatives. Social housing developers exhibit highest price sensitivity, while luxury hospitality chains prioritize corrosion immunity and rapid replacement cycles over first-cost minimization.
Supply Chain Analysis
Reverse-logistics flows for bathroom pods remain underdeveloped, though refurbishment networks for hospitality asset upgrade cycles are emerging in Manchester and London. Manufacturing concentrates in the United Kingdom, Germany, and Italy, with raw material dependencies spanning petrochemical-derived resins, fiberglass reinforcement, and thermoformed acrylic sheets. Single-source vulnerability characterizes GRP molding capacity in North Rhine-Westphalia, where captive fabrication lines anchor regional supply. Distribution runs through direct fabricator-to-developer channels for volumetric residential projects, displacing traditional tiered subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
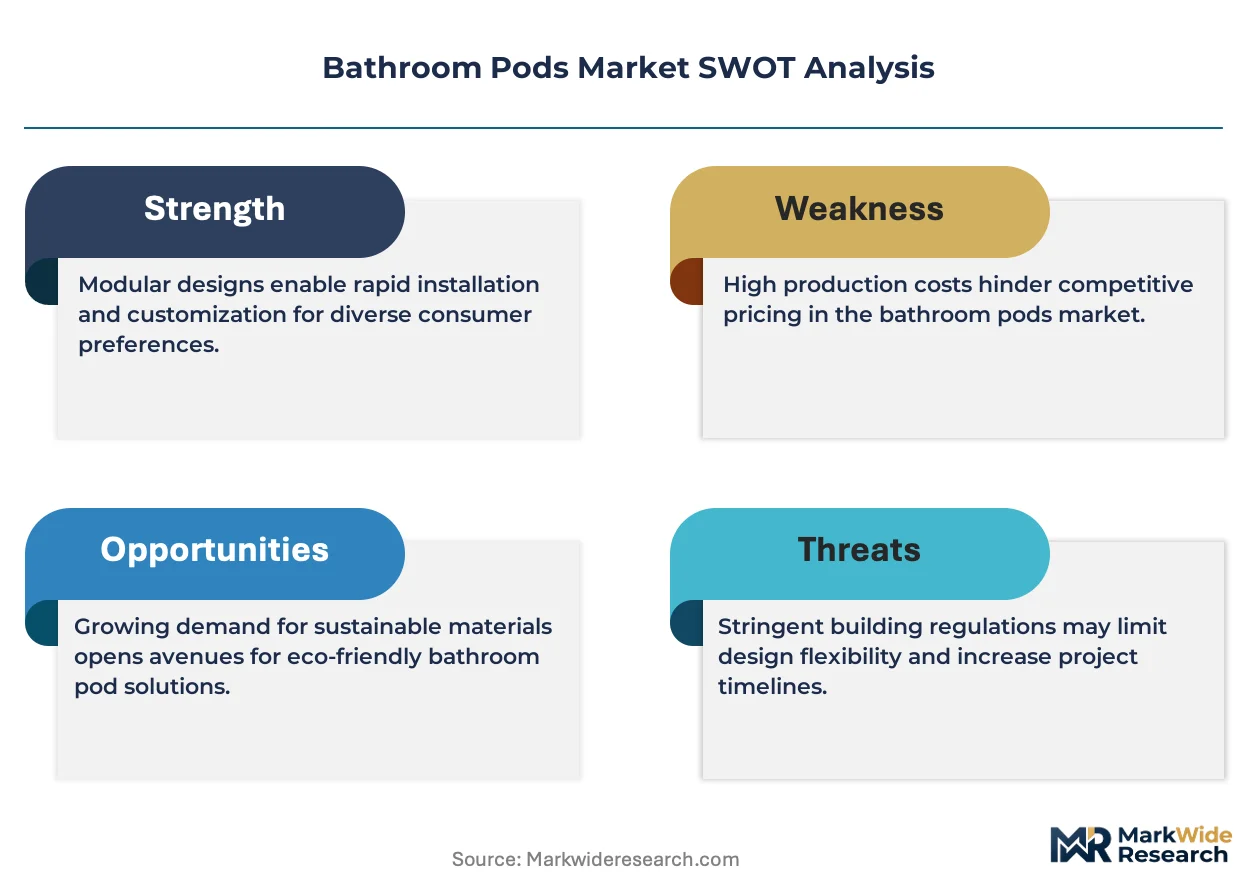
The bathroom pods market functions as a regulatory compounder where France's RE2020 embodied-carbon thresholds and Germany's KBA-adjacent acoustic mandates continuously elevate compliance barriers that filter out marginal suppliers.
For Market Incumbents: To counter margin erosion from petrochemical feedstock volatility, Walker Modular and comparable composite specialists should deepen backward integration into captive resin compounding operations in North Rhine-Westphalia. Certification investment in enhanced fire reaction performance documentation secures eligibility for UK structures above 18 meters under Building Safety Regulator mandates. For New Entrants and Emerging Players: Design-build contractors represent the most accessible channel partner type for penetrating Dutch modular residential acceleration, where government housing production targets outstrip established supply capacity. White-space opportunities concentrate in timber-frame pod-to-core integration protocols and digital twin-enabled BIM workflow partnerships for hospitality chains. For Investors and Strategic Acquirers: Consolidation pressure builds where smaller fabricators lack certified quality systems for post-Grenfell traceability documentation. Long-term viability favors EU-based composite molders with documented embodied-carbon compliance for public procurement frameworks. The signal to watch is KBA-adjacent certification body enforcement patterns that determine import eligibility for multi-family residential tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GRP Molding Capacity Expansion | Insulates margins from petrochemical volatility for UK social housing tenders. |
| CE Marking Convergence with CSRD Disclosure | Aligns structural integrity certification with embodied-carbon reporting for EU eligibility. |
| Digital Twin Integration with BIM Workflows | Compresses commissioning timelines for Manchester and London hotel developers. |
| Direct Fabricator-to-Developer Channel Development | Eliminates tiered subcontractor markups in London high-rise residential pipelines. |
| Acoustic Isolation Certification Investment | Secures access to German multi-family residential tenders through KBA-adjacent bodies. |
Research Methodology
Coverage spans the United Kingdom, Germany, France, Italy, and the Netherlands, with primary inputs from each construction cluster combining interviews with modular construction directors, hospital procurement managers, hospitality development executives, and structural engineering consultants. Secondary validation draws from UK Building Safety Regulator guidance documents, EU Construction Products Regulation technical files, RE2020 compliance databases, and national building energy code submissions. Bottom-up pod shipment tallies triangulate against top-down construction pipeline valuations.
Rate-of-change decomposition separates volume absorption across new construction and renovation channels, with segmentation dimensions spanning product type, end user, installation context, and material substrate. CAGRs derive from structural frame completion timelines correlated with pod delivery schedules, hospitality pipeline data, and healthcare commissioning acceleration patterns. Analysis window projections incorporate regulatory milestone enforcement dates and embodied-carbon disclosure phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility, REACH substance restriction expansions, and EU Green Deal carbon border adjustment implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market