
 Bathroom Cabinets Market | 2026-2036
Bathroom Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Cabinets Market Intelligence
The rising prevalence of asset-light manufacturing models, where brands outsource production to specialized OEMs, is narrowing the competitive field to firms with superior supply chain management and design capabilities. Global giant Kohler leverages its extensive distribution network and brand recognition to command premium pricing. In contrast, Duravit specializes in the high-end, design-forward segment, often collaborating with renowned designers. American Woodmark sustains a strong presence in the North American residential market through large-scale, efficient production for homebuilders and retail channels.
Bathroom cabinets are enclosed storage units specifically engineered for high-humidity environments. They are typically constructed from materials like moisture-resistant medium-density fiberboard (MDF), solid wood, or plywood, often featuring protective finishes to prevent water damage. The primary function is to organize toiletries, medicines, and cleaning supplies while contributing to the overall aesthetic of the bathroom space. While wood and MDF remain the dominant materials by volume, wall-mounted and modular cabinets represent the fastest-growing installation types, favored for their space-saving benefits in urban residential projects.
Product compliance is shaped by a matrix of international and national standards. In the United States, the EPA enforces TSCA Title VI, which limits formaldehyde emissions from composite wood products used in cabinetry. The European Union's REACH regulation governs the use of chemical substances, and CE marking is mandatory for products sold within the European Economic Area, indicating conformity with health and safety standards. Future competitive advantage depends on navigating evolving material sustainability regulations and adapting to consumer preferences for smart, integrated storage solutions.
Market Dynamics
The bathroom cabinets market is shaped by the tension between demand for aesthetic, feature-rich designs from the hospitality and residential sectors and the increasing stringency of material regulations. Compliance with chemical standards like the EPA's TSCA Title VI and EU's REACH is now a baseline competitive requirement.
Growth Catalysts
- Urban Infrastructure Investment:Government-backed initiatives to expand urban housing in countries such as India are generating significant, large-scale demand for standardized bathroom cabinetry, creating volume for manufacturers able to meet project specifications and timelines.
- Hospitality Sector Renovations:Hotels are undergoing frequent and extensive renovation cycles to attract guests, driving demand for modern, durable, and space-efficient cabinets that enhance the guest experience and align with contemporary design trends.
- Modular Design Adoption:Consumer and developer preference for wall-mounted and modular cabinet systems is growing, particularly in dense urban residential projects where optimizing floor space and achieving a minimalist aesthetic are primary design goals.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the cost of core materials like moisture-resistant MDF, plywood, and specialized hardware creates margin pressure for manufacturers, making long-term project quoting and cost control difficult.
- Regulatory Compliance Costs:Adhering to a fragmented landscape of international chemical safety regulations, including the EU's REACH and the US EPA's TSCA Title VI, adds significant testing, certification, and administrative costs.
- Threat of Substitution:The increasing popularity of minimalist bathroom design trends, which favor open shelving or fully integrated vanity sinks with built-in storage, poses a direct substitution threat to traditional enclosed cabinet units.
Strategic Opportunities
- Smart Cabinet Integration:There is a growing opportunity to embed technology such as integrated LED lighting, anti-fog heating elements, and built-in charging ports, transforming the cabinet into a value-added, multifunctional smart bathroom fixture.
- Emerging Market Penetration:Targeting the expanding middle-class consumer base in Southeast Asian nations offers new growth avenues beyond established markets, particularly for mid-range and affordable luxury product lines.
- Direct-to-Consumer E-commerce:Establishing robust online sales channels allows manufacturers to bypass traditional retail intermediaries, build brand equity directly with end-users, and capture higher margins, especially within the DIY renovation segment.
Industry Challenges
- Supply Chain Fragmentation:Managing a complex global supply chain for diverse components, from specialized European hardware to Asian composite boards, exposes manufacturers to risks of shipping delays, quality inconsistencies, and geopolitical disruptions.
- Certification and Traceability:The operational burden of documenting material provenance and ensuring continuous compliance with evolving sustainability and chemical safety standards requires significant investment in supply chain management systems and personnel.
- Skilled Labor Shortages:A deficit of skilled craftspeople proficient in precision woodworking, finishing, and the installation of complex, feature-rich cabinetry hinders the production capacity and quality control of high-end and custom manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Cabinets Market |
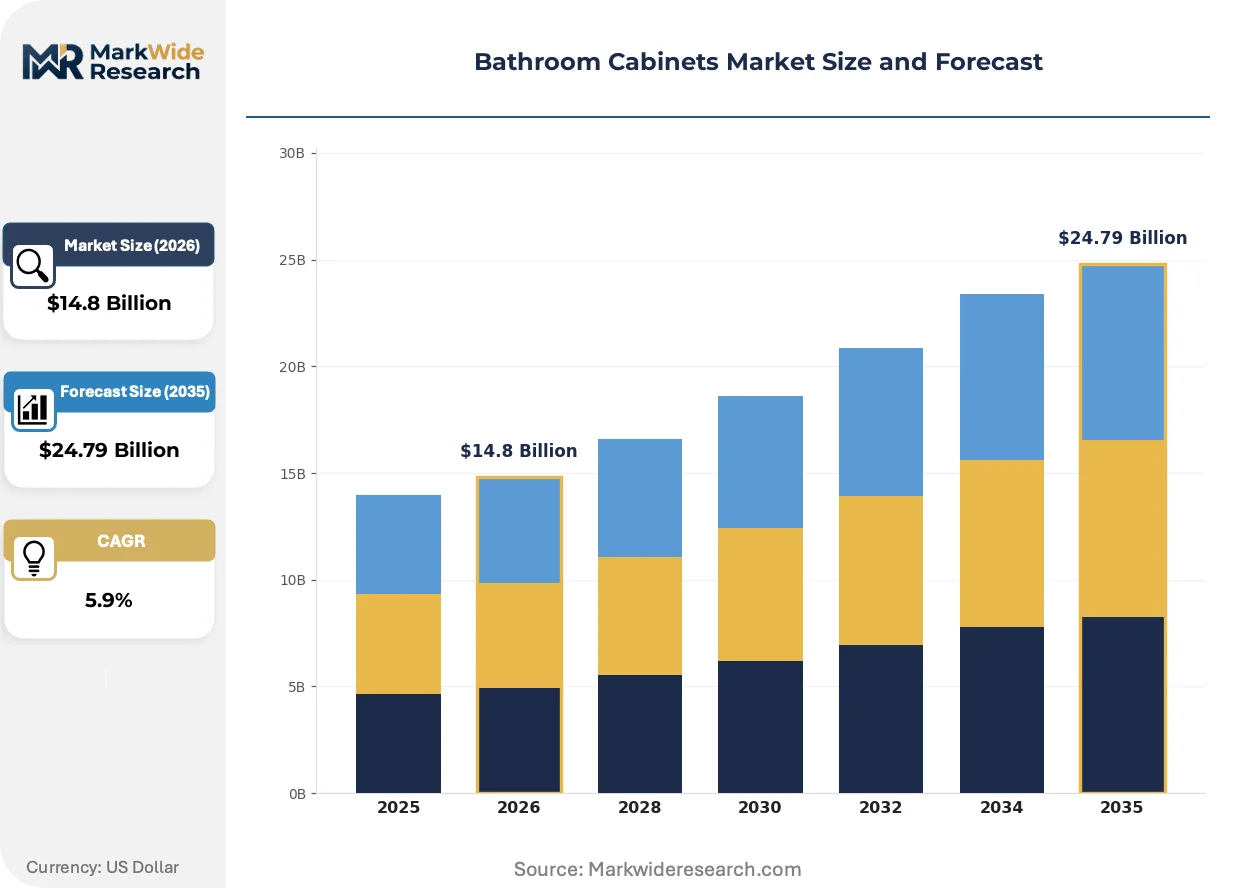
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, MDF, Plywood, Metal Style: Modern, Traditional, Rustic, Contemporary Installation Type: Wall-mounted, Freestanding, Built-in, Modular End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Duravit, James Martin Vanities, Kohler, Villeroy & Boch, Fortune Brands Home & Security, MasterBrand Cabinets, Roca, Cabinetworks Group, American Woodmark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Cabinets Market Strategic Shifts & Innovations
Product evolution is driven by the convergence of material science and smart home technology. Manufacturers are responding to consumer demand for greater personalization and sustainability, moving beyond basic storage to offer integrated, feature-rich solutions that define the bathroom environment.
Integrated smart features are becoming a key differentiator in the premium segment. Technologies such as embedded LED lighting with adjustable color temperature, heated defogging mirrors, and Bluetooth speakers are being incorporated directly into cabinet designs. High-end residential and luxury hospitality sectors are the primary adopters, viewing these additions as essential modern amenities. This integration of electronics and furniture is collapsing the traditional boundaries between product categories, creating a new class of smart bathroom fixture.
Heightened regulatory scrutiny over chemical substances is compelling material innovation. The European Union's REACH regulation, alongside stricter enforcement of formaldehyde limits under standards like TSCA Title VI in the US, is forcing a shift away from traditional binders in composite wood. This primarily affects manufacturers of MDF and particleboard, who must now invest heavily in developing and validating alternative, low-emission resin systems to maintain market access and meet green building criteria.
Project-based procurement is altering B2B sales cycles and channel dynamics. Large-scale customers like hotel developers and homebuilders are increasingly sourcing bathroom components as a complete package rather than purchasing individual items. This model disrupts the traditional role of distributors and favors manufacturers who can offer a full suite of coordinated products, from vanities to medicine cabinets. This shift is most pronounced in major urban development zones in North America and Asia.
Bathroom Cabinets Market Segmentation
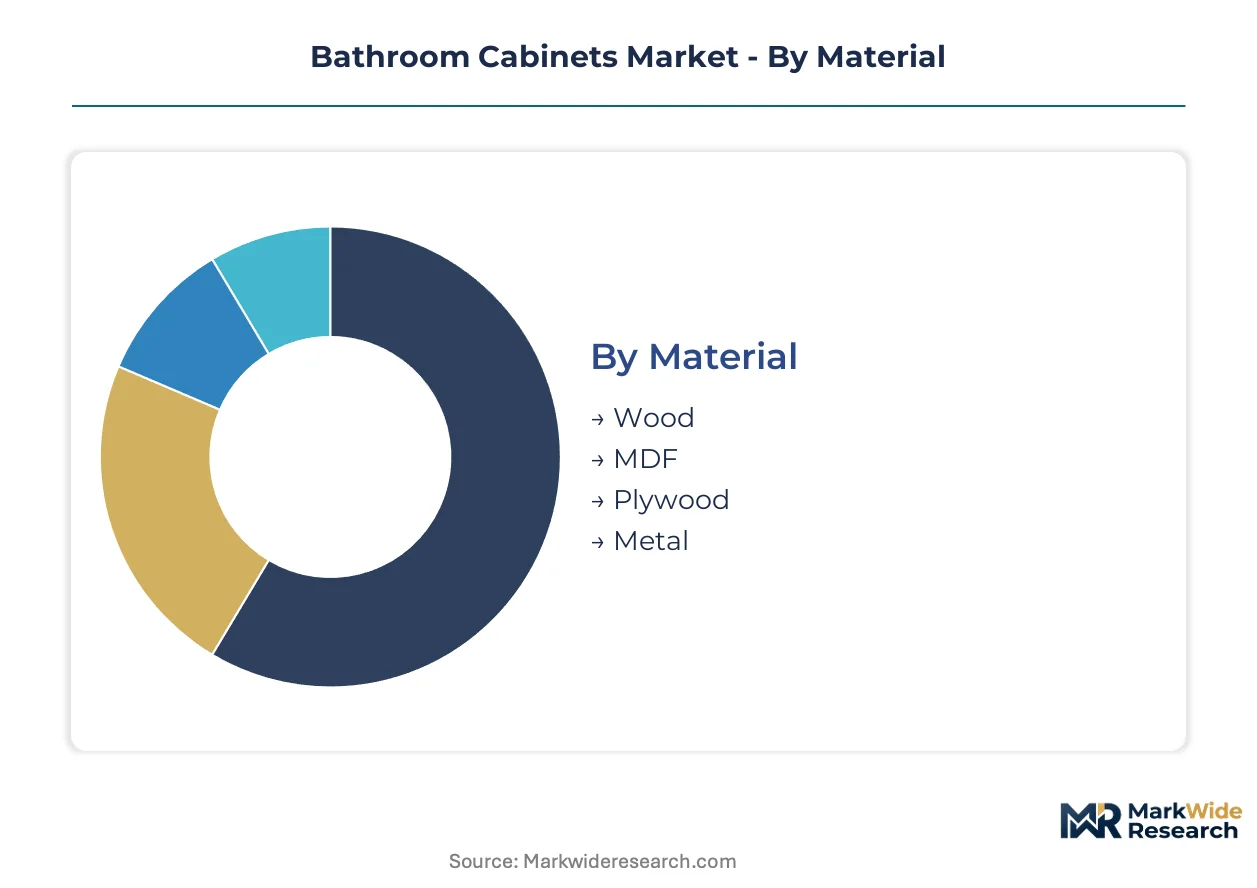
Market segmentation provides a granular view of demand drivers and competitive dynamics within the bathroom cabinets sector. Understanding the distinct needs of various material preferences, design aesthetics, installation methods, and end-user requirements is essential for manufacturers to tailor product development and market entry strategies effectively.
Material:
The durability and maintenance requirements of bathroom cabinets are heavily influenced by their core material composition, directly impacting after-sales service intensity and product longevity expectations.
- MDF:Moisture-resistant medium-density fiberboard, a composite wood product, offers a cost-effective and versatile base for various finishes. Demand concentrates in large-scale urban residential projects and mid-range hospitality renovations due to its balance of price and performance.
- Plywood:Composed of multiple layers of wood veneers bonded together, plywood provides superior strength and resistance to moisture compared to standard MDF. This material sees strong adoption in high-humidity environments and commercial applications where longevity is a primary concern.
- Wood:Solid wood cabinets offer a premium aesthetic and traditional appeal, often featuring intricate details and natural grain patterns for high-end residential spaces.
- Metal:Metal cabinets, typically steel or aluminum, provide exceptional durability and a modern, industrial look, frequently specified for commercial and institutional settings.
By volume, MDF leads due to its cost-effectiveness and widespread use. By growth pace, Plywood is ahead, driven by its enhanced durability and moisture resistance.
Style:
Style often dictates the perceived value and pricing tier of bathroom cabinetry, influencing consumer purchasing decisions across various budget points and design preferences.
- Modern:Characterized by sleek lines, minimalist hardware, and neutral color palettes, modern cabinets prioritize functionality and uncluttered aesthetics. This style is highly sought after in urban residential developments and hospitality renovations aiming for a contemporary, clean look.
- Contemporary:Reflecting current design sensibilities, contemporary cabinets often blend various elements, incorporating integrated technology and unique finishes. Luxury residential and boutique hotel projects frequently adopt this style to create distinctive and personalized bathroom environments.
- Traditional:Traditional designs feature classic architectural elements, ornate details, and often darker wood finishes, appealing to homeowners seeking a timeless and elegant aesthetic.
- Rustic:Rustic cabinets emphasize natural textures, distressed finishes, and often reclaimed wood, aligning with farmhouse or natural-themed interior designs for residential customers.
Modern and Contemporary styles collectively capture a significant share of new installations, reflecting current architectural preferences and technological integration.
Installation Type:
The chosen installation type directly impacts bathroom functionality and space optimization, critical for diverse architectural footprints in residential and commercial settings.
- Wall-mounted:These units are affixed directly to the wall, leaving the floor clear, which enhances perceived space and simplifies cleaning. Wall-mounted cabinets are favored in dense urban residential projects and hospitality settings for their spatial efficiency and sleek appearance.
- Modular:Comprising interchangeable components that can be configured in various ways, modular cabinets offer flexibility in design and layout. Developers utilize modular systems for large-scale projects requiring customization and efficient installation in urban environments.
- Freestanding:Freestanding cabinets are self-contained units that rest on the floor, offering placement flexibility and ease of installation for individual homeowners.
- Built-in:Built-in cabinets are custom-fitted into the bathroom architecture, providing a seamless, integrated aesthetic, typically found in high-end residential and custom commercial projects.
Wall-mounted and Modular systems are experiencing the steepest expansion trajectory, driven by their space-saving benefits and design versatility.
End User:
End-user segments dictate procurement scale and product specifications, influencing manufacturing volumes and distribution channels for bathroom cabinet producers.
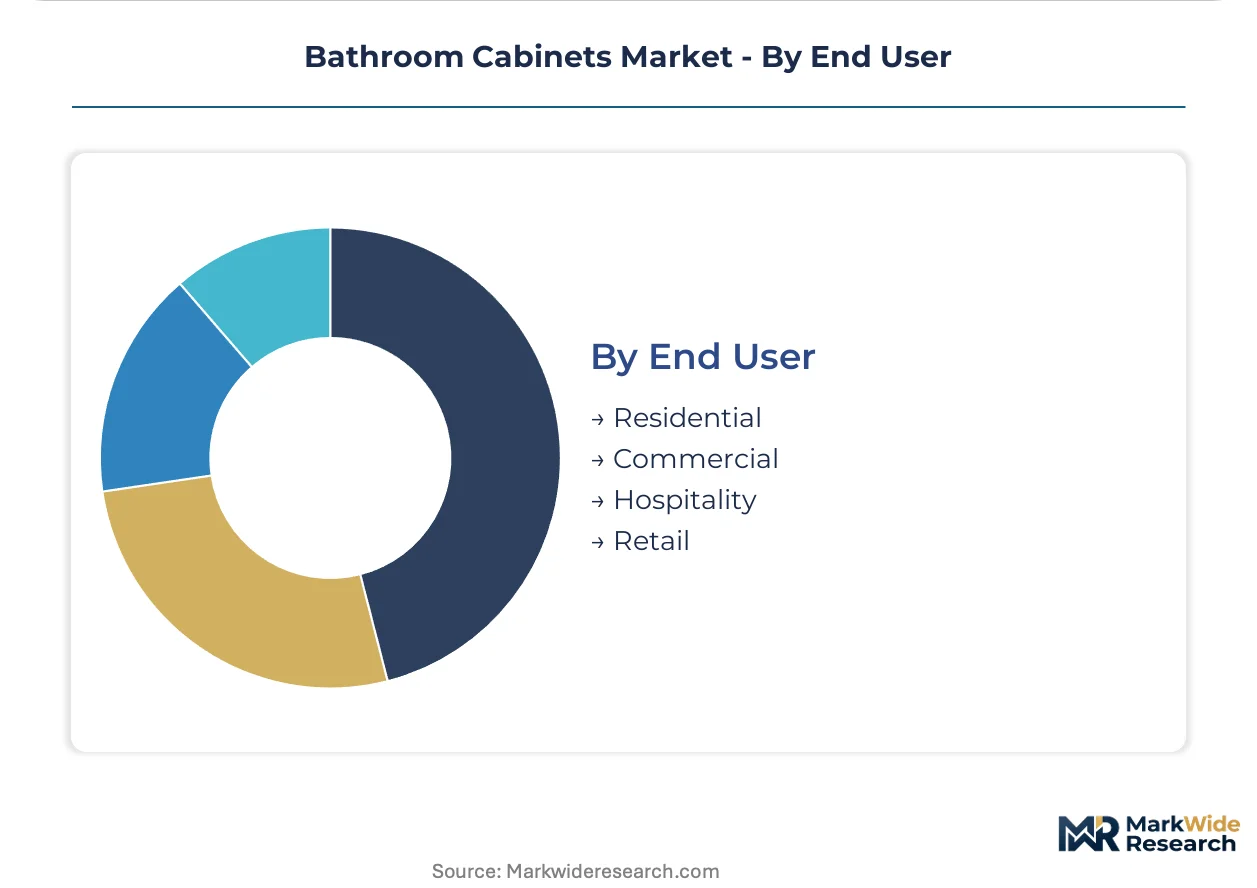
- Residential:Encompassing individual homes, apartments, and multi-family dwellings, the residential segment demands a wide range of styles and price points for new construction and renovation. New housing construction and DIY renovation projects across North America drive substantial volume in this segment.
- Hospitality:This sector includes hotels, resorts, and guest houses, requiring durable, aesthetically pleasing, and often custom-designed cabinets that withstand heavy use. Extensive renovation cycles and modernization of guest amenities globally drive significant demand for high-quality solutions.
- Commercial:Commercial applications, such as offices, public buildings, and healthcare facilities, prioritize robust construction and functional designs for high-traffic environments.
- Retail:The retail segment involves direct sales to consumers through showrooms, big-box stores, and e-commerce platforms, offering diverse product lines for individual purchases.
The Residential segment represents the largest volume consumer, while Hospitality projects drive significant demand for durable and aesthetic solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bathroom cabinets market exhibits varied regional dynamics, with some countries acting as net exporters of finished goods and components, while others drive substantial import demand. Trade flows are influenced by local manufacturing capabilities, raw material access, and specific regulatory environments. This balance between domestic production and international trade shapes competitive strategies across different geographies.
India
India's demand for bathroom cabinets is significantly propelled by extensive government investment in urban housing infrastructure and a burgeoning middle-class consumer base. The Bureau of Indian Standards (BIS) ensures product quality and safety, influencing material selection for domestic manufacturers. Major urban centers like Mumbai and Delhi-NCR are experiencing concentrated construction activity, creating large-scale project demand.
United States
The United States residential construction and renovation sectors drive substantial demand for bathroom cabinetry, particularly within the North American market. The Environmental Protection Agency (EPA) enforces TSCA Title VI, mandating strict limits on formaldehyde emissions from composite wood products. Manufacturing clusters in states like North Carolina and Indiana cater to both large homebuilders and retail channels.
Germany
Germany represents a significant market for high-quality, design-forward bathroom cabinets, with a strong emphasis on engineering and sustainability. The European Union's REACH regulation governs chemical substances, and CE marking is mandatory for products sold within the European Economic Area. The Black Forest region, known for its precision manufacturing, hosts numerous specialized producers.
Vietnam
Vietnam is emerging as a critical manufacturing hub and a growing market for bathroom cabinets, benefiting from foreign direct investment and expanding export capabilities. Government policies aimed at boosting manufacturing and infrastructure development support the industry's expansion. Ho Chi Minh City and Hanoi are experiencing rapid urbanization, fueling demand for modern residential and hospitality projects.
Brazil
Brazil's bathroom cabinet market is driven by a large domestic consumer base and a recovering construction sector, particularly for mid-range and affordable luxury segments. National regulations, including those set by ABNT (Brazilian Association of Technical Standards), guide product specifications and material sourcing. The São Paulo state, with its robust industrial base, is a key production and consumption area.
Bathroom Cabinets Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, ranging from global conglomerates to specialized regional manufacturers. Companies differentiate through superior supply chain management, design capabilities, and adherence to evolving sustainability standards. Dominant competitive moves include strategic partnerships for distribution and continuous portfolio diversification into smart home integration.
Within the premium and design-forward segment, Duravit exemplifies a focus on high-end aesthetics and collaborations with renowned designers. Global brand Kohler leverages its extensive distribution network and strong brand recognition to command premium pricing across diverse product lines. American Woodmark, meanwhile, anchors the North American residential market through large-scale, efficient production tailored for homebuilders and retail channels.
| Leading Market Players |
|---|
| Duravit |
| James Martin Vanities |
| Kohler |
| Villeroy & Boch |
| Fortune Brands Home & Security |
| MasterBrand Cabinets |
| Roca |
| Cabinetworks Group |
| American Woodmark |
| Others |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in Southeast Asia drives competitive pricing from Vietnam-based producers, influencing global supply dynamics and forcing established manufacturers to optimize cost structures. This capacity utilization directly impacts raw material procurement strategies and downstream pricing models.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing, which dominates large-scale procurement. Price differentiation stems from material durability, such as plywood's enhanced moisture resistance, and compliance with certifications like EPA's TSCA Title VI. Pricing pressure intensifies for mid-range products due to raw material price volatility in MDF and hardware components. Homebuilders represent the most price-sensitive segment, while luxury hospitality projects prioritize design and durability over cost.
Supply Chain Analysis
The supply of moisture-resistant MDF and specialized hardware draws from concentrated manufacturing hubs. Geographic supply concentration includes China and Vietnam for composite boards and Germany for high-end hardware components. Raw material dependencies include moisture-resistant MDF, plywood, specialized hardware, and protective finishes. Geopolitical disruptions impacting global shipping lanes present a structural supply chain risk. B2B project-based procurement forms the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, particularly as integrated smart features like connectivity and personalized lighting offer recurring-revenue layers expanding faster than the core cabinet hardware.
For Market Incumbents: Entrench existing relationships with large-scale residential developers and hospitality chains through bundled product offerings. Invest in advanced material science for sustainable, low-emission composite wood products to counter evolving environmental regulations. This strategy mitigates the threat of substitution from minimalist designs and strengthens channel control for premium solutions.
For New Entrants and Emerging Players: Pursue white-space opportunities in mid-range affordable luxury segments within Southeast Asian nations. Target urban residential projects in India, where demand for standardized, space-efficient cabinetry is high. A direct-to-consumer e-commerce strategy provides a penetrable go-to-market angle, bypassing traditional retail intermediaries and building brand equity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart cabinet providers offering embedded technology services and long-term maintenance contracts. The market exhibits long-term viability over a 5-10 year window, sustained by continuous renovation cycles and smart home integration trends. Niche manufacturers specializing in modular, wall-mounted systems with strong design capabilities represent an attractive acquisition archetype. Consumer adoption rates of smart bathroom fixtures serve as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Lower manufacturing costs and proximity to growing Asian markets enhance competitive advantage. |
| R&D in Bio-based Resins | Addresses formaldehyde regulations and consumer demand for green, compliant products. |
| Direct-to-Consumer Platform Launch | Captures higher margins and builds brand loyalty in the burgeoning DIY renovation segment. |
| Strategic Partnership with Smart Home Tech Firm | Accelerates integration of features like anti-fog mirrors and built-in charging ports. |
| Modular Product Line Extension | Catters to space-saving demands in dense urban residential developments effectively. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings within this analysis. Primary research involved discussions with hotel procurement managers, residential developers, material scientists, and retail buyers. Secondary data sources included government housing initiatives, construction project databases, EPA TSCA Title VI compliance records, and EU REACH documentation. This approach facilitated both bottom-up and top-down triangulation of market estimates.
The quantitative model is calibrated using historical growth patterns and projected economic indicators across the analysis window. Segmentation dimensions modeled include material, style, installation type, end-user, and regional construction spending. Compound annual growth rates were derived from a synthesis of historical market performance and anticipated future demand drivers. Urbanization rates and hospitality renovation budgets served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in raw material price volatility and global shipping costs would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and sustained consumer preference for integrated storage solutions. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Bathtub Market