
 North America Plumbing Fixture Market | 2026-2036
North America Plumbing Fixture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plumbing Fixture Market Intelligence
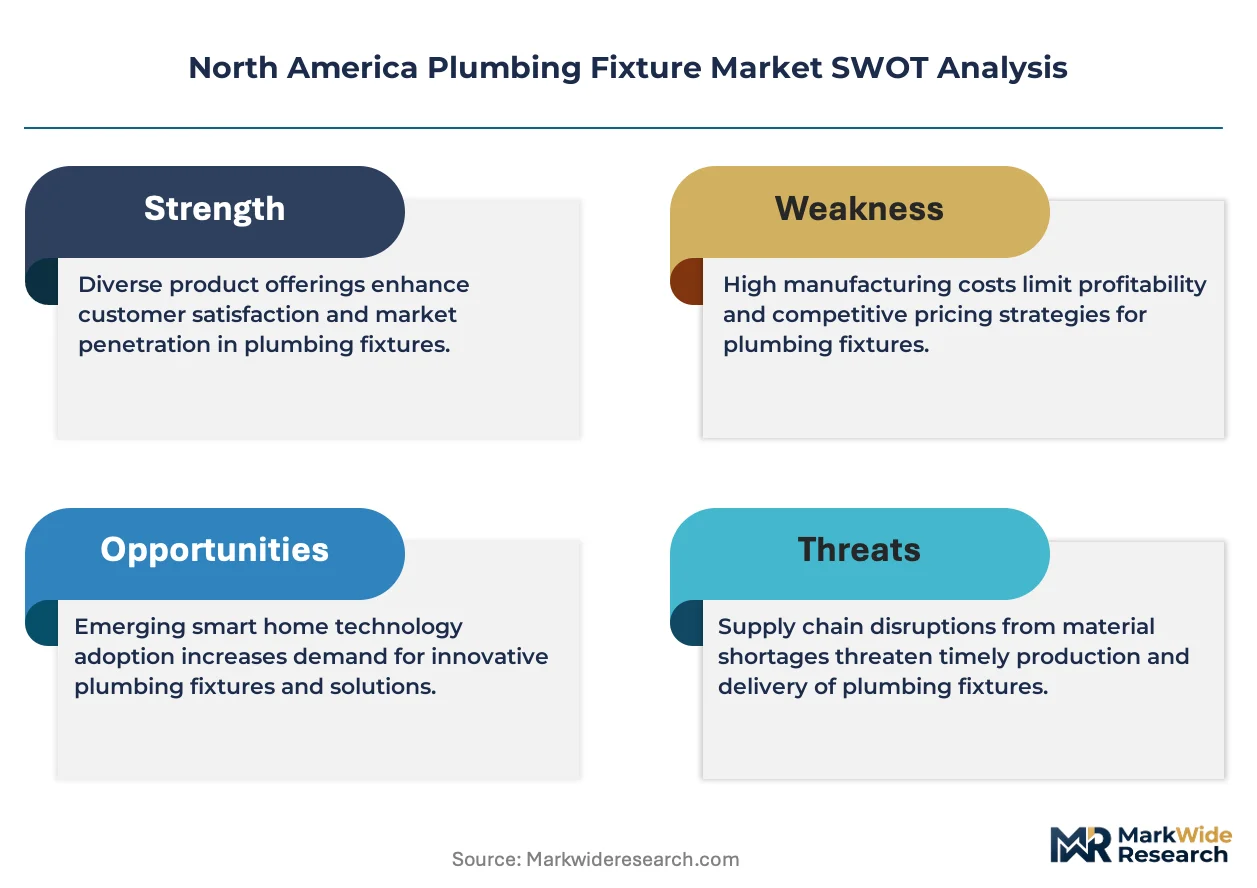
The EPA WaterSense program is shifting demand toward ultra-low-flow fixtures across North American residential and commercial construction. Kohler Co. leverages its vertically integrated brass foundry operations to control material costs and specification cycles. Moen Incorporated anchors its competitive position through Moen Smart Water Network integration, while Delta Faucet Company differentiates via Touch2O and VoiceIQ technology platforms in the connected fixture segment.
North America plumbing fixtures encompass permanently installed water delivery and drainage devices engineered to ANSI/ASME pressure ratings, ceramic disc valve tolerances, and EPA flow-rate thresholds for residential, commercial, and institutional wet spaces. Faucets dominate volume shipments due to universal replacement cycles across all end-user segments, while ceramic and stainless steel materials command premium positioning in hospitality and luxury residential specifications where finish durability and antimicrobial properties justify higher procurement budgets.
EPA WaterSense, ASME A112.18.1, and CSA B125.1 collectively govern fixture performance, safety, and cross-border market access across the United States and Canada. The EPA mandates maximum 1.28 gallons per flush for toilets and 1.5 gallons per minute for faucets, while CSA certification remains mandatory for Canadian commercial and institutional procurement channels. Stakeholders must monitor state-level drought emergency declarations and municipal retrofit ordinances, as these local measures increasingly preempt federal minimums and reshape replacement demand timing.
Market Dynamics
EPA WaterSense mandates are compressing flow-rate tolerances across residential and commercial specifications, forcing manufacturers to redesign valve architectures and ceramic disc geometries to maintain performance at reduced water volumes.
Growth Catalysts
- WaterSense Retrofit Mandates:Municipal ordinances in Arizona, California, and Nevada now require WaterSense-certified fixtures in all building permit applications, accelerating replacement cycles in drought-affected municipalities.
- Brass Foundry Integration:Captive brass casting operations allow fixture manufacturers to buffer against LME copper price volatility and secure alloy specifications for low-lead compliance under EPA Safe Drinking Water Act amendments.
- Commercial Hospitality Upgrades:Hotel chains across Texas and Florida are specifying antimicrobial copper-nickel finishes to meet enhanced hygiene protocols, expanding premium fixture demand in the accommodation sector.
Market Restraints
- Raw Material Concentration:Chilean copper concentrate and Chinese zinc ingot supply disruptions expose North American brass mills to price spikes and alloying delays.
- Low-Flow Performance Skepticism:Consumer complaints about inadequate flush performance in 1.28 gpf toilets create resistance to specification in custom residential projects.
- Cross-Border Certification Friction:Divergent EPA WaterSense and CSA B125.1 testing protocols force manufacturers to maintain dual certification inventories for US-Canada distribution.
Strategic Opportunities
- Smart Water Network Convergence:Integration of flow sensors with home automation platforms creates recurring revenue streams through leak detection subscriptions and usage analytics.
- Midwest Commercial Retrofit:Aging infrastructure in Chicago, Detroit, and Cleveland presents untapped demand for pressure-compensating aerators and thermostatic mixing valves in institutional buildings.
- State-Level Green Building Incentives:California's CALGreen tiered certification system and New York's Local Law 97 carbon penalties reward ultra-low-flow fixture specification with accelerated permitting and tax abatements.
Industry Challenges
- Plumber Training Shortfalls:Installation of cartridge-based smart valves requires electrical troubleshooting skills that aging trade workforces in the US Southwest and Canadian Prairies often lack.
- Lead-Free Alloy Brittleness:Bismuth and silicon substitutions in C87850 brass reduce machinability, increasing tool wear and scrap rates at high-volume production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plumbing Fixture Market |
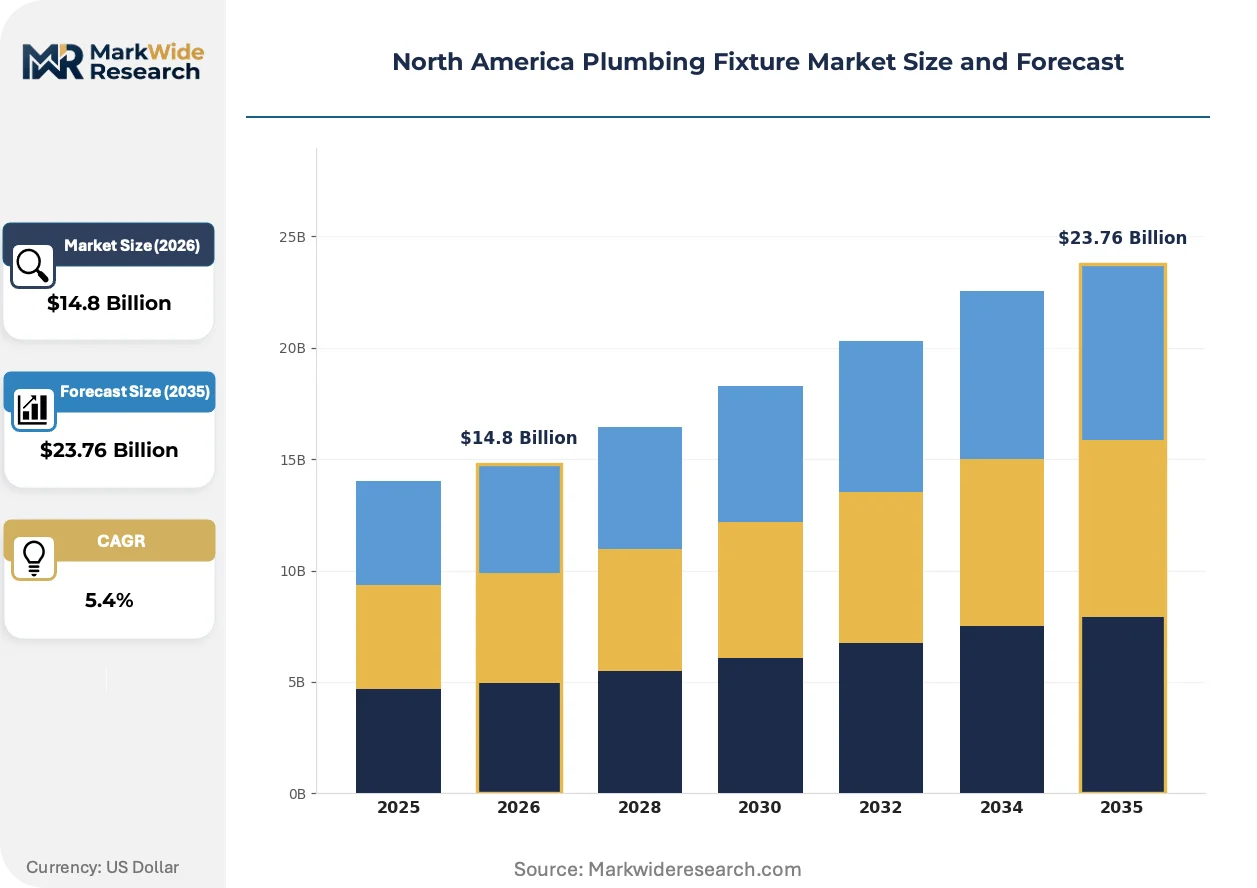
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Shower Heads, Toilets, Sinks, Bathtubs, Urinals Material: Stainless Steel, Brass, Plastic, Ceramic, Copper, Bronze Installation Type: Wall-Mounted, Floor-Mounted, Deck-Mounted, Ceiling-Mounted End User: Residential Buildings, Commercial Complexes, Hospitality Units, Educational Institutions, Government Establishments |
| Companies Covered | Kohler Co., Delta Faucet Company, Moen Incorporated, Masco Corporation, GROHE AG, Hansgrohe SE, House of Rohl, Waterworks Operating Company LLC, Brizo Kitchen & Bath Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plumbing Fixture Market Strategic Shifts & Innovations
Digital sensing and connectivity architectures are penetrating fixture categories previously dominated by mechanical valve systems, creating new specification criteria around data interoperability and predictive maintenance capabilities.
Thermostatic mixing valves with embedded flow sensors are integrating with building management systems to enable real-time Legionella prevention protocols and water balance monitoring. Healthcare facilities and senior living operators in California and Texas are specifying these systems to reduce liability exposure from scalding incidents and bacterial colonization. The technology is compressing traditional preventive maintenance schedules by shifting from calendar-based inspections to condition-based valve replacement.
EPA WaterSense is tightening maximum flow-rate thresholds for kitchen faucets from 2.2 gpm to 1.8 gpm under revised draft specifications released for stakeholder comment. Fixture manufacturers must recertify entire product lines or risk exclusion from federal procurement and rebate programs. The residential replacement segment faces the steepest compliance timeline, with existing inventory grandfathering provisions varying by state environmental agency.
Builder procurement departments are consolidating specification authority at regional distribution centers rather than allowing site-level purchasing, compressing supplier diversity and favoring manufacturers with national logistics networks. Large production homebuilders in Arizona, Nevada, and Texas are centralizing fixture selection through preferred vendor agreements with single-source distributors. This concentration is most visible in entry-level residential construction, where cost engineering teams now dictate SKU rationalization across multi-state development portfolios.
North America Plumbing Fixture Market Segmentation
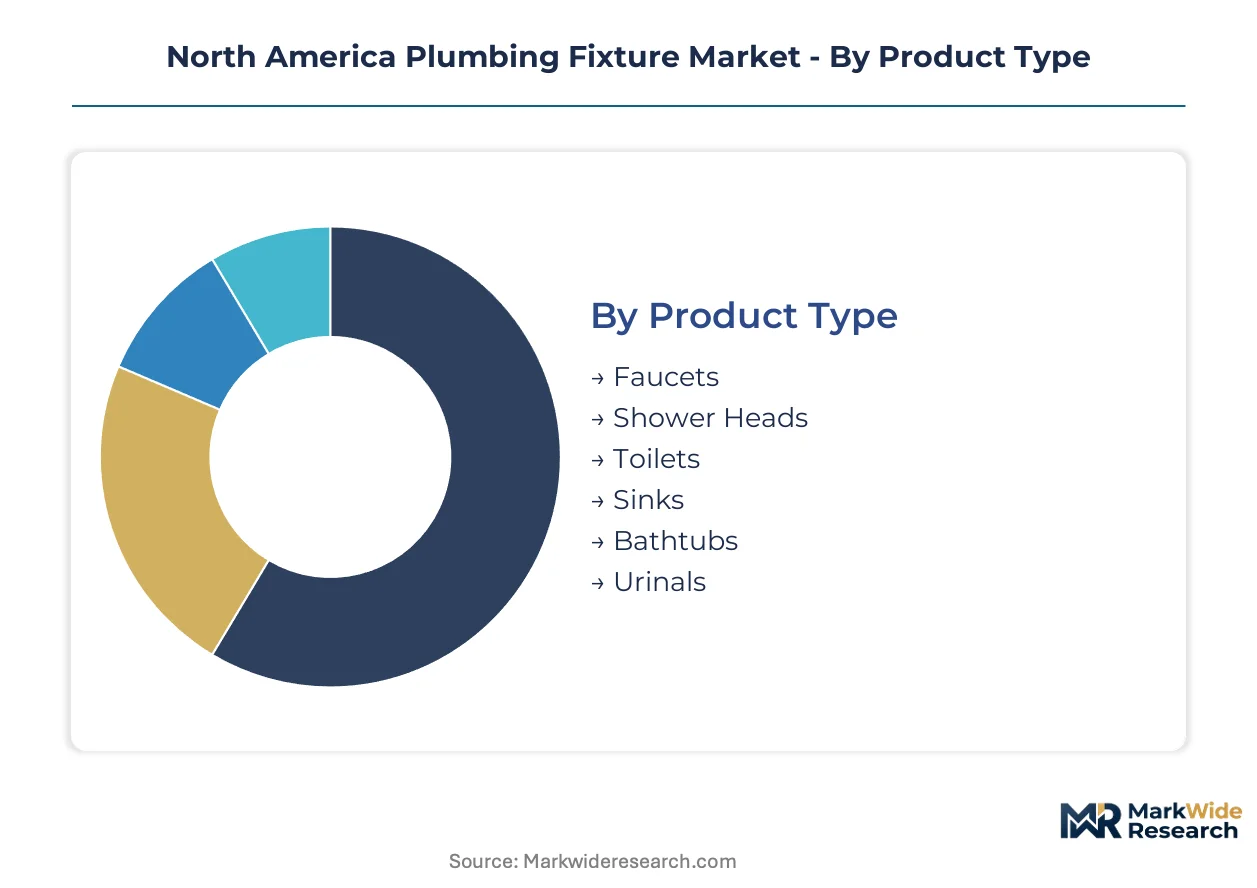
Plumbing fixture segmentation reveals how specification authority concentrates across distinct procurement channels. Material selection and installation geometry directly determine compliance pathways with EPA WaterSense and CSA B125.1 standards.
Product Type:
Supply concentration tilts heavily toward valve-intensive categories where brass foundry integration yields cost control advantages.
- Faucets:Universal replacement cycles across all building types sustain volume leadership. Kitchen and lavatory variants face imminent EPA flow-rate compression from 2.2 gpm to 1.8 gpm, forcing cartridge redesigns in Arizona and California municipal retrofit programs.
- Toilets:Gravity-fed and pressure-assisted flush platforms engineered to 1.28 gpf maximums dominate residential specification. Consumer resistance to low-flow performance in custom homes constrains uptake in the southwestern United States luxury segment.
- Shower Heads:Multi-function spray heads with pressure-compensating flow restrictors address WaterSense thresholds.
- Sinks:Vessel, undermount, and pedestal configurations span ceramic and stainless steel material grades.
- Bathtubs:Alcove and freestanding installations concentrate in hospitality renovation cycles.
- Urinals:Waterless and ultra-low-flush variants target commercial and institutional water conservation mandates.
Faucets absorb the bulk of installed capacity; toilets are expanding most quickly under drought-driven retrofit ordinances.
Material:
Cost tier stratification separates specification-grade alloys from commodity alternatives.
- Brass:Lead-free C87850 and silicon-bismuth alloys dominate valve bodies and fittings. Captive foundry operations at major manufacturers buffer against LME copper volatility and secure low-lead compliance for Safe Drinking Water Act amendments.
- Stainless Steel:304 and 316 grades command premium positioning in healthcare and foodservice applications where corrosion resistance and antimicrobial properties justify higher procurement budgets in Texas and Florida hospitality chains.
- Plastic:ABS and PVC formulations serve drain-waste-vent systems and economy-priced fixture housings.
- Ceramic:Vitreous china formulations dominate toilet bowls and lavatory sinks.
- Copper:Antimicrobial copper-nickel finishes gain traction in enhanced hygiene protocols.
- Bronze:Oil-rubbed and brushed bronze finishes target luxury residential and boutique hospitality specifications.
Brass commands the greatest production volume; stainless steel is climbing the fastest on antimicrobial specification demand.
Installation Type:
Application geometry dictates plumbing rough-in complexity and labor skill requirements.
- Wall-Mounted:Concealed carrier systems for toilets and lavatories maximize floor space in compact commercial restrooms. Chicago and Detroit institutional retrofits drive demand for pressure-compensating flushometers in aging infrastructure.
- Floor-Mounted:Traditional close-coupled toilets and pedestal sinks dominate residential replacement cycles. Standardized rough-in dimensions simplify inventory management for national production homebuilders in Arizona, Nevada, and Texas.
- Deck-Mounted:Kitchen and lavatory faucets integrate with countertop substrates across material grades.
- Ceiling-Mounted:Rainfall shower heads and specialty spouts serve luxury residential and spa hospitality segments.
Floor-mounted fixtures retain the largest installed base; wall-mounted configurations are gaining share fastest in commercial space optimization.
End User:
Customer type determines specification authority, compliance tier, and replacement cycle velocity.
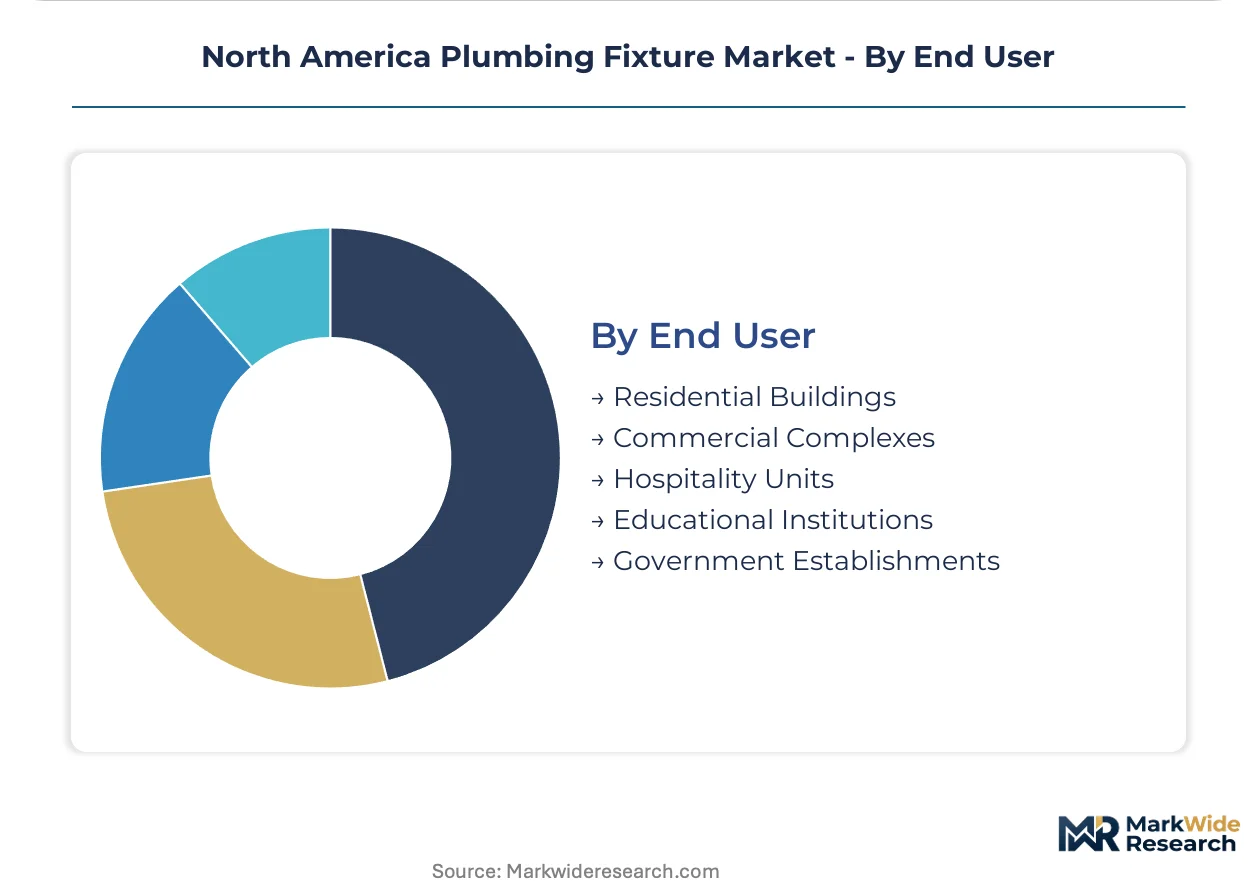
- Residential Buildings:Single-family and multifamily construction drives faucet and toilet volume through production builder procurement consolidation. Centralized specification at regional distribution centers compresses supplier diversity and rewards manufacturers with national logistics networks.
- Commercial Complexes:Office and retail tenant improvements specify pressure-compensating aerators and thermostatic mixing valves. California and New York green building incentives reward ultra-low-flow fixture selection with accelerated permitting.
- Hospitality Units:Hotel chains across Texas and Florida specify antimicrobial finishes and smart water network integration to meet enhanced hygiene protocols and reduce liability exposure.
- Educational Institutions:K-12 and university facilities prioritize vandal-resistant designs and WaterSense compliance for rebate eligibility.
- Government Establishments:Federal procurement mandates WaterSense certification, while state-level drought emergency declarations preempt federal minimums in southwestern municipalities.
Residential buildings consume the greatest fixture volume; hospitality units are expanding most quickly on antimicrobial and connected-technology specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors fixture demand acceleration across the southwestern United States, where drought emergency declarations and municipal retrofit ordinances compress replacement cycles faster than national averages.
United States
Southwestern drought mandates in Arizona, California, and Nevada now require WaterSense-certified fixtures for all building permits, accelerating residential and commercial replacement demand. The EPA's tightening flow-rate standards for kitchen faucets—from 2.2 gpm to 1.8 gpm—force manufacturers to recertify product lines or lose federal procurement eligibility. Chicago and Detroit institutional retrofits drive demand for pressure-compensating thermostatic mixing valves in aging Midwest infrastructure.
Canada
CSA B125.1 certification remains mandatory for commercial and institutional procurement channels, creating cross-border friction with divergent EPA testing protocols. Toronto and Vancouver green building codes reward ultra-low-flow specification with accelerated permitting timelines. Quebec's provincial environmental regulations preempt federal minimums in Montreal municipal retrofit programs, mirroring southwestern US drought-response patterns.
Mexico
Industrial corridor expansion around Monterrey and Tijuana generates specification demand for ANSI-compliant fixtures in manufacturing facility construction. Mexican federal water conservation programs lack enforcement parity with EPA WaterSense, creating a two-tier market split between export-grade certified production and domestic non-compliant consumption. Baja California's proximity to California drought mandates creates spillover specification pressure in Tijuana commercial development.
North America Plumbing Fixture Market Key Industry Players
Premium-margin players sit above commodity-margin players across material-grade and certification-tier positioning. The vendor base stratifies into three tiers: vertically integrated brass foundry operators controlling alloy specifications, smart-technology platform developers monetizing data services, and regional distributors serving fragmented contractor procurement. Consolidation pressure concentrates in entry-level residential construction, where production homebuilders centralize specification authority through preferred vendor agreements. Dominant competitive moves include captive brass casting investments and home automation platform integration.
Within the vertically integrated tier, Kohler Co. and Masco Corporation exemplify foundry-control strategies that buffer against LME copper volatility. Moen Incorporated anchors the connected-technology vector through smart water network positioning. Delta Faucet Company occupies the touchless and voice-activated specification niche. GROHE AG and Hansgrohe SE represent European-origin premium-positioning archetypes competing on finish durability and design authority. House of Rohl and Waterworks Operating Company LLC exemplify boutique luxury-channel specialists serving custom residential and hospitality renovation cycles.
| Leading Market Players |
|---|
| Kohler Co. |
| Delta Faucet Company |
| Moen Incorporated |
| Masco Corporation |
| GROHE AG |
| Hansgrohe SE |
| House of Rohl |
| Waterworks Operating Company LLC |
| Brizo Kitchen & Bath Company |
| Others |
Cost & Logistics Intelligence
Smart valve cartridge miniaturization is compressing per-unit brass consumption while concentrating procurement leverage among manufacturers with captive foundry operations, simultaneously reshaping cost economics and supplier tier consolidation across North American distribution channels.
Pricing Analysis
WaterSense certification tier anchors value-based pricing across residential and commercial specification channels. Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial-finish hospitality fixtures from commodity builder-grade products, with EPA flow-rate compliance as the primary differentiation driver. Cost compression in entry-level residential SKUs is intensifying because production homebuilders centralize procurement through regional distribution centers. Custom residential projects exhibit lowest price sensitivity, while multi-family production builders demonstrate highest sensitivity to per-unit fixture costs.
Supply Chain Analysis
Dual-sourcing requirements for lead-free brass alloys mandate multi-supplier qualification across Chilean copper concentrate, Chinese zinc ingot, and domestic silicon-bismuth feedstock channels. Raw material dependencies center on LME copper pricing, zinc alloying elements, and ceramic disc valve components. Single-source vulnerability concentrates in Chilean mining output disruptions and Chinese smelter capacity constraints. Distribution runs through national distributor networks serving consolidated production builder procurement and fragmented contractor supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America plumbing fixture market sits in a technology-transition phase as cartridge-based smart valves displace legacy mechanical systems, forcing specification criteria toward data interoperability and predictive maintenance capabilities.
For Market Incumbents: Deepen captive brass foundry investments to buffer LME copper volatility and secure low-lead alloy specifications under EPA Safe Drinking Water Act amendments. Expand smart water network platform integration to monetize recurring revenue through leak detection subscriptions, countering emerging IoT-native entrants with software-first positioning.
For New Entrants and Emerging Players: Capture institutional retrofit demand in Chicago, Detroit, and Cleveland aging infrastructure for pressure-compensating thermostatic mixing valves. Target mid-scale hospitality chains in Texas and Florida seeking antimicrobial copper-nickel finishes without incumbent preferred vendor lock-in, deploying direct specification relationships with regional facilities management groups.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by vertically integrated brass foundry operators seeking smart technology capabilities. Long-term viability favors manufacturers with dual EPA WaterSense and CSA B125.1 certification infrastructure spanning US-Canada distribution. Watch California kitchen faucet flow-rate recertification deadlines as inflection indicator for compliance-driven replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Brass Foundry Investment | Buffers LME copper price volatility and secures low-lead alloy compliance for EPA regulations. |
| Smart Water Network Platform Integration | Creates recurring revenue streams through leak detection subscriptions and usage analytics services. |
| Dual Certification Infrastructure | Enables seamless US-Canada distribution by satisfying divergent EPA WaterSense and CSA B125.1 protocols. |
| Antimicrobial Finish Development | Captures premium positioning in Texas and Florida hospitality chains with enhanced hygiene protocols. |
| Regional Distribution Center Consolidation | Aligns logistics networks with production homebuilder procurement centralization in Arizona, Nevada, and Texas. |
Research Approach
Multi-period observation of municipal retrofit ordinance adoption, EPA WaterSense certification timelines, and LME copper price volatility anchored the trend analysis, supplemented by interviews with brass foundry operations managers, production homebuilder procurement directors, commercial plumbing contractors, and regional distributor inventory planners. Secondary validation drew from EPA regulatory filings, CSA certification databases, customs import records for copper concentrate and zinc ingot, and SEC 10-K disclosures from publicly traded fixture manufacturers. Bottom-up volume estimates triangulated against top-down construction spending allocations across residential, commercial, and institutional end-use segments.
Input-output matrix modeling connected raw material cost indices, certification compliance timelines, and specification authority shifts to project segment-level demand across the analysis window. Segmentation dimensions included product type, material grade, installation geometry, and end-user procurement channel. CAGRs derived from fitted growth curves applied to replacement cycle acceleration in drought-mandated municipalities and green building incentive jurisdictions. Industry-specific forecast inputs incorporated state-level drought emergency declaration frequency and municipal ordinance grandfathering provisions.
The model holds under continued EPA WaterSense tightening and stable LME copper pricing; deviation in Chilean supply disruptions or accelerated California flow-rate compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market