
 Global OFF-THE-SHELF Second Hand Furniture Market | 2026-2036
Global OFF-THE-SHELF Second Hand Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global OFF-THE-SHELF Second Hand Furniture Market Outlook
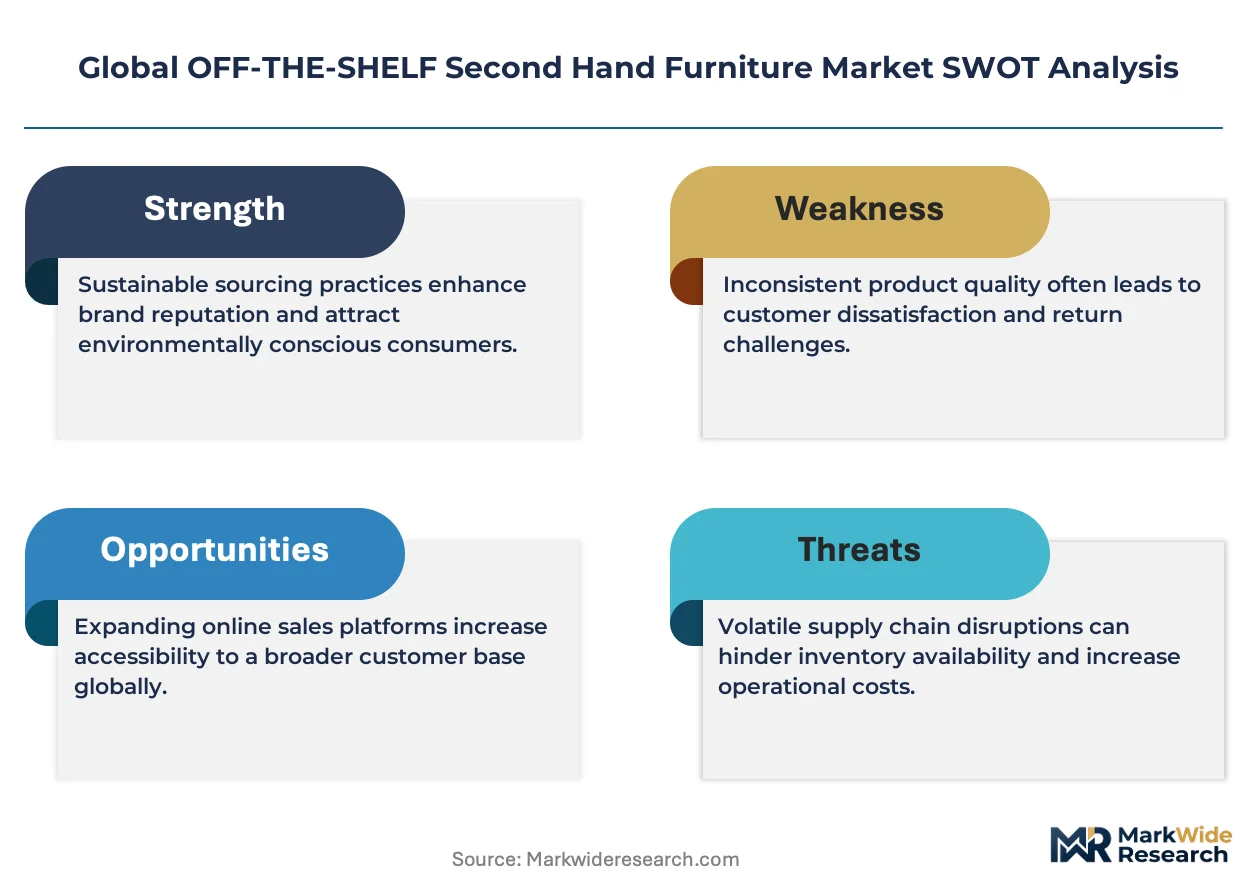
Small office and co-working space outfitting is shifting toward pre-owned desks and seating as operators trim setup costs. Kaiyo leverages its white-glove delivery and condition-grading system to sustain premium pricing on verified used sofas. AptDeco competes in the New York-to-Washington corridor with logistics infrastructure that controls last-mile costs for bulky items. Chairish anchors the designer and vintage segment with curated inventory that differentiates from mass-market peer-to-peer platforms.
Off-the-shelf second hand furniture comprises previously owned, ready-to-use furnishings sold without custom modification, typically inspected for structural integrity, cleaned, and priced below comparable new goods. These items serve commercial and residential buyers seeking immediate deployability with reduced capital outlay and lower embodied carbon. Wood-framed seating and tables occupy the deepest resale liquidity pools due to durability and repairability. Vintage-condition upholstery commands the strongest margin expansion as scarcity and provenance attract design professionals. Refurbished cabinets lead volume growth among office end users prioritizing functional storage with rapid turnaround.
The EPA's waste reduction guidelines and state-level landfill diversion mandates in California and New York shape collection infrastructure and seller incentives across the United States. REACH and the EU Green Deal impose substance-tracking and circularity obligations on furniture reprocessors operating in France, Germany, and the Netherlands. Stakeholders must monitor evolving extended producer responsibility schemes and platform liability rules that will determine which intermediaries bear compliance costs.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are redirecting millions of furniture units from landfill disposal into verified resale channels, compressing supply acquisition costs for platforms while tightening compliance requirements for cross-border reprocessors.
Growth Catalysts
- REACH substance-tracking obligations:France, Germany, and the Netherlands now require documented material provenance for reprocessed furnishings, creating competitive moats for compliant platforms against informal peer-to-peer sellers.
- Rental housing procurement:Co-living operators in Berlin, Hamburg, and Copenhagen are standardizing pre-owned outfitting to reduce per-unit capital expenditure on rapid-turnover units.
- Refurbishment automation:Computer vision grading systems are compressing inspection timelines from days to hours, enabling inventory velocity that manual assessment cannot match.
Market Restraints
- Input cost volatility:Reupholstery foam and textile prices fluctuate with petrochemical indices, squeezing margin on restored seating.
- Supply concentration risk:Dense vintage dealer networks in Berlin and Hamburg control premium mid-century inventory, limiting platform access to authenticated designer pieces.
- Substitution threat:Flat-pack new furniture from Southeast Asian manufacturers competes aggressively on price for first-apartment and student housing segments.
Strategic Opportunities
- Underpenetrated geography:Spain and Italy lack centralized refurbishment infrastructure despite high urban density, creating first-mover advantages for logistics-capable entrants.
- Technology convergence:Blockchain provenance tracking paired with AR visualization tools enables remote authentication and condition assessment, unlocking cross-border trade.
- Regulatory tailwind:California's landfill diversion mandates and New York's extended producer responsibility pilots are subsidizing collection infrastructure for certified resellers.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction compliance with REACH, EPA guidelines, and emerging state-level substance restrictions requires dedicated regulatory staff.
- Skill scarcity in restoration trades:Upholstery and wood refinishing expertise concentrates in aging craft networks with limited apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OFF-THE-SHELF Second Hand Furniture Market |
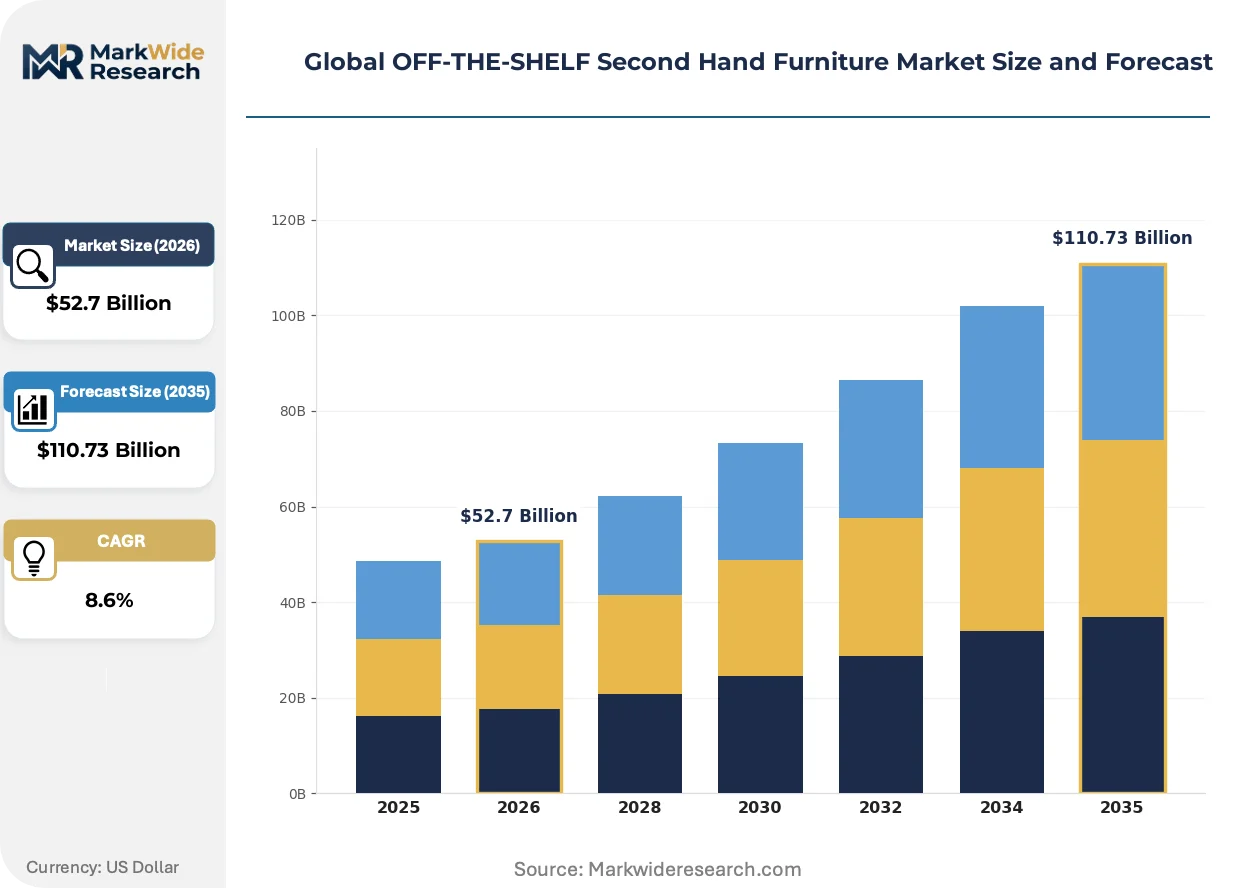
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
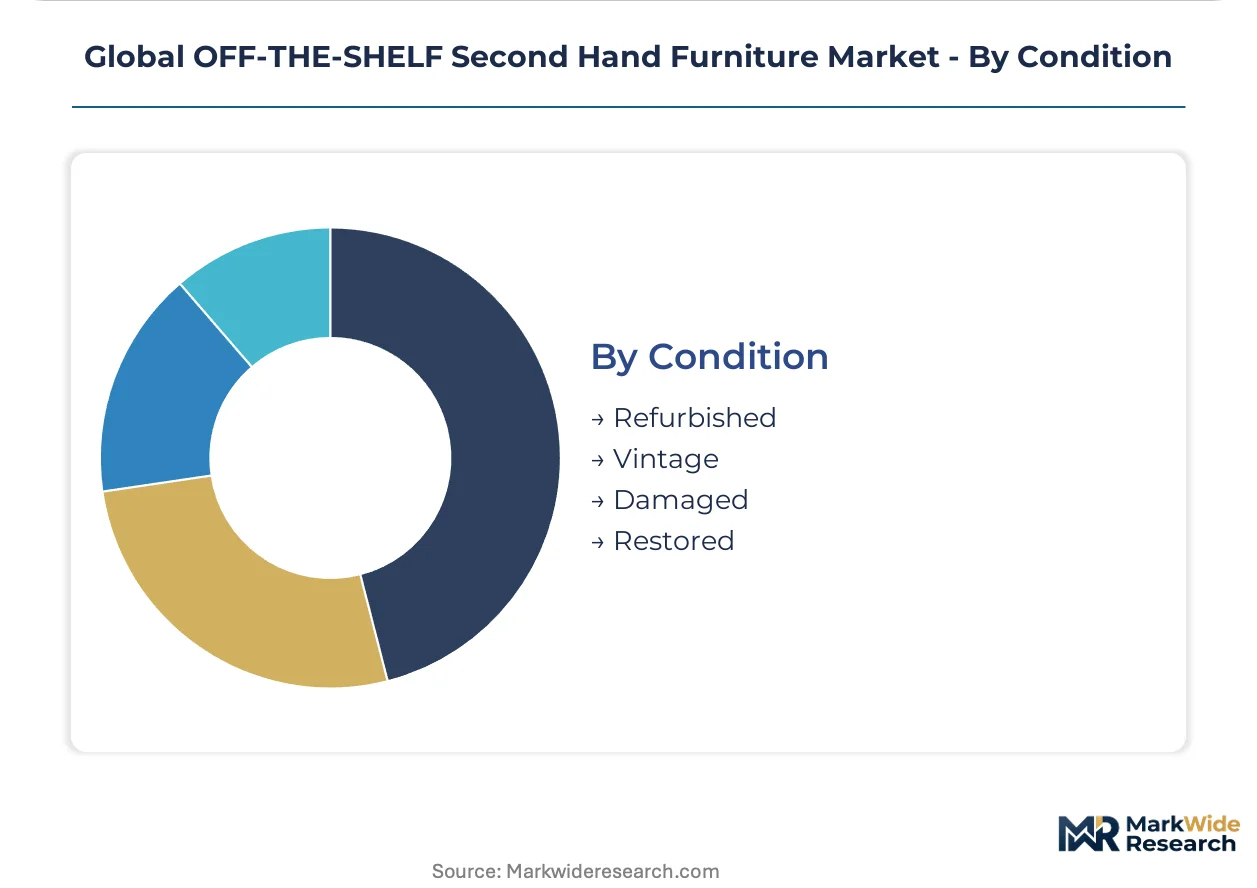
| Segmentation | Product Type: Chairs, Tables, Sofas, Cabinets End User: Households, Offices, Retailers, Designers Material: Wood, Metal, Plastic, Upholstery Condition: Refurbished, Vintage, Damaged, Restored |
| Companies Covered | Kaiyo, AptDeco, Chairish, eBay, Facebook Marketplace, Goodwill Industries, Habitat for Humanity ReStores, Craigslist, IKEA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OFF-THE-SHELF Second Hand Furniture Market Strategic Shifts
Digital condition verification and logistics orchestration are displacing traditional estate-sale and consignment models, while regulatory pressure on embodied carbon accelerates platform investment in refurbishment standardization.
Computer vision grading systems equipped with depth-sensing cameras are absorbing the labor-intensive inspection burden that previously constrained inventory throughput. Large resale platforms in Germany and France are deploying these tools at warehouse scale, reducing per-item assessment time by an order of magnitude. The technology is absorbing quality-control bottlenecks that historically limited geographic expansion for mid-market operators.
REACH substance-tracking amendments and the EU Green Deal's circularity reporting requirements are imposing documentation burdens on cross-border furniture reprocessors. German and Dutch platforms must now maintain chain-of-custody records for flame retardants and surface treatments. Vintage-condition upholstery segments face the steepest compliance costs, driving consolidation toward vertically integrated refurbishers with in-house testing capabilities.
Corporate procurement departments are unbundling furniture acquisition from facility management contracts, creating direct relationships with verified resale platforms. Co-working operators in London, Amsterdam, and New York are bypassing traditional office dealers to source pre-owned desks and storage systems. This disintermediation is most visible in rapid-setup commercial spaces where depreciation schedules favor immediate deployability over brand-new warranties.
Global OFF-THE-SHELF Second Hand Furniture Market Segmentation
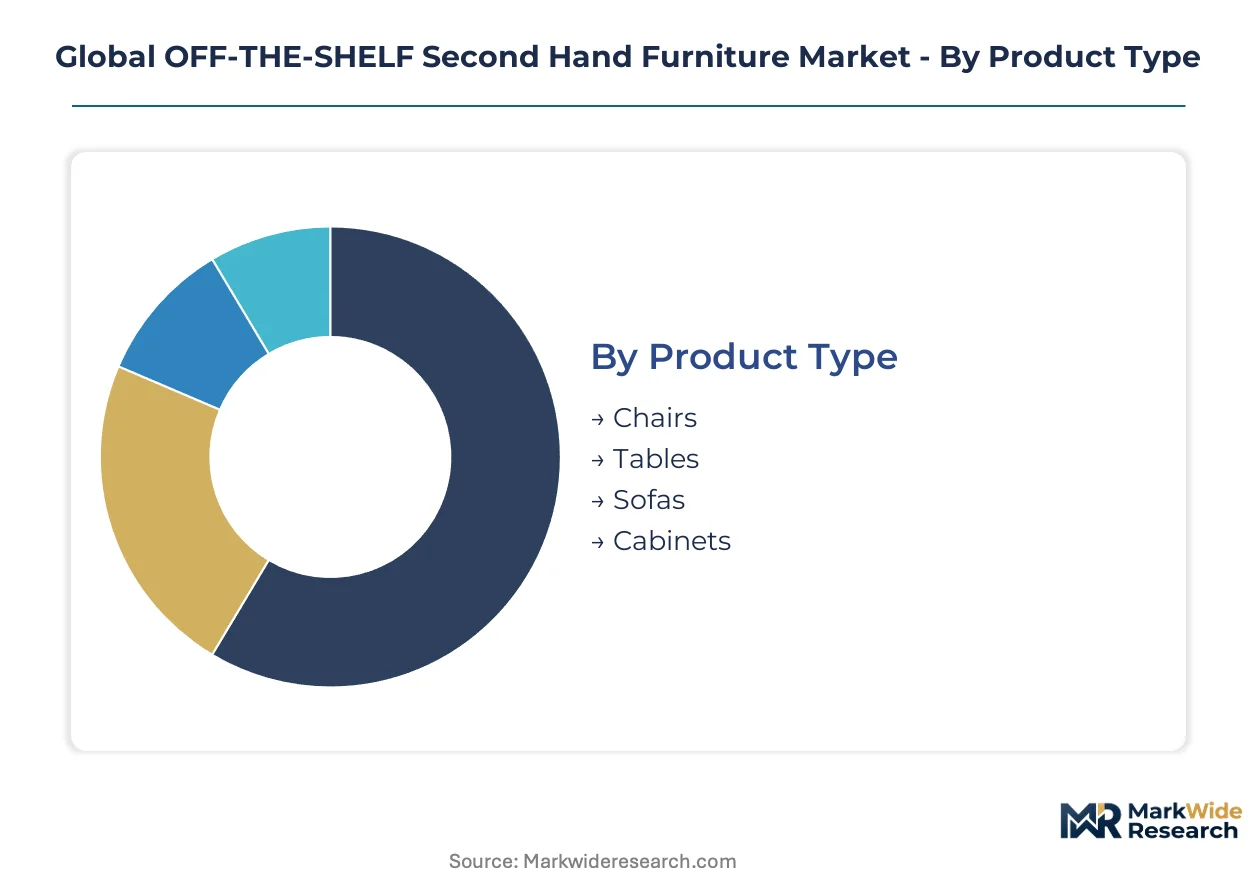
Off-the-shelf second hand furniture markets fragment across four critical dimensions that determine pricing power, logistics complexity, and regulatory exposure. Product type and material composition shape refurbishment economics, while end-user concentration and condition grading define margin architecture.
Product Type:
Volume concentrates in structural seating and surfaces, while premium capture clusters in statement pieces with design provenance.
- Chairs:Wood-framed seating offers the deepest resale liquidity due to repairability and component standardization. Demand concentrates in Berlin and Hamburg refurbishment workshops serving co-living operators who standardize pre-owned seating to trim per-unit capital expenditure.
- Sofas:Bulky upholstered units require white-glove logistics infrastructure that platforms like Kaiyo leverage for premium positioning. Vintage-condition specimens with documented provenance attract design professionals in Copenhagen and Amsterdam seeking scarcity value.
- Tables:Surface units trade on dimensional utility with limited margin expansion. Office end users in London source pre-owned conference and dining tables for rapid-setup commercial spaces.
- Cabinets:Storage systems lead volume growth among commercial buyers prioritizing functional deployability. REACH substance-tracking obligations impose documentation burdens on cross-border reprocessors handling treated wood surfaces.
Today's leader: Sofas. Tomorrow's challenger: Cabinets.
End User:
Procurement patterns diverge sharply between capital-constrained operators and taste-driven individual buyers.
- Households:Individual consumers seek immediate deployability with reduced embodied carbon. Design-conscious buyers in urban Germany drive vintage segment liquidity through dense dealer networks.
- Offices:Co-working operators bypass traditional dealers to source pre-owned desks and storage directly from verified platforms. Corporate procurement departments unbundle furniture acquisition from facility management contracts.
- Retailers:Curated resale platforms like Chairish anchor the designer segment with authenticated inventory that differentiates from peer-to-peer mass market.
- Designers:Specifiers command premium access to authenticated mid-century pieces. Dense vintage dealer networks in Berlin and Hamburg limit platform access to this scarce inventory.
Commercial buyers currently dominate transaction velocity. Designer procurement represents the steepest margin expansion trajectory.
Material:
Repairability and substance-compliance burdens stratify material economics across the value chain.
- Wood:Solid and veneered frames dominate refurbishment throughput due to refinishing viability. EU Green Deal extended producer responsibility mandates redirect millions of wood units from landfill into verified resale channels.
- Metal:Structural frames and hardware components offer durability with limited aesthetic customization. Office outfitters source pre-owned metal seating for high-traffic environments.
- Plastic:Polymer furnishings face steep substitution pressure from flat-pack new goods. Student housing segments prioritize price over material provenance.
- Upholstery:Fabric and leather surfaces command the strongest margin expansion where scarcity and condition verification justify premium positioning. REACH flame-retardant documentation requirements concentrate compliance costs in this segment.
Wood maintains supply dominance. Upholstery offers the highest margin capture potential.
Condition:
Grading precision determines platform credibility and cross-border trade eligibility.
- Refurbished:Structurally restored and cleaned units trade at mid-tier pricing with immediate deployability. Computer vision grading systems compress inspection timelines from days to hours.
- Vintage:Authenticated period pieces with documented provenance attract design professionals. German and Dutch platforms maintain chain-of-custody records for surface treatments to satisfy REACH amendments.
- Damaged:As-is units serve buyers with in-house restoration capability or component harvesting intent. Limited platform infrastructure supports this segment.
- Restored:Professionally renewed specimens bridge refurbished utility and vintage aesthetics. Skill scarcity in upholstery and wood refinishing concentrates expertise in aging craft networks.
Refurbished goods anchor platform volume. Vintage authentication unlocks pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin and Hamburg anchor the densest concentration of vintage dealer networks and refurbishment workshops serving design-conscious consumers across Europe.
United States
Co-living operators in New York and Washington D.C. standardize pre-owned desk and seating procurement to trim per-unit capital expenditure on rapid-turnover units. The EPA's waste reduction guidelines and California's landfill diversion mandates subsidize collection infrastructure for certified resellers. Kaiyo leverages white-glove delivery infrastructure in the Northeast corridor to sustain premium positioning on verified used sofas.
Germany
EU Green Deal extended producer responsibility mandates redirect millions of furniture units from landfill into verified resale channels, compressing supply acquisition costs for platforms. REACH substance-tracking obligations require documented material provenance for reprocessed furnishings, creating competitive moats for compliant operators. Dense vintage dealer networks in Berlin and Hamburg control premium mid-century inventory, limiting platform access to authenticated designer pieces.
France
National waste hierarchy laws mandate extended producer responsibility, redirecting usable furniture from landfills into resale channels with tightening compliance requirements. ANSM and ECHA guidelines impose documentation burdens on cross-border reprocessors handling treated wood surfaces and flame-retardant upholstery. Paris hosts curated resale platforms anchoring the designer segment with authenticated inventory.
Netherlands
Co-working operators in Amsterdam bypass traditional office dealers to source pre-owned desks and storage directly from verified platforms. REACH amendments require Dutch platforms to maintain chain-of-custody records for surface treatments and flame retardants. Rotterdam and The Hague concentrate refurbishment automation deployment, with computer vision grading systems compressing inspection timelines from days to hours.
United Kingdom
Corporate procurement departments in London unbundle furniture acquisition from facility management contracts, creating direct relationships with verified resale platforms. Co-working operators source pre-owned conference and dining tables for rapid-setup commercial spaces. The capital's design professionals command premium access to authenticated period pieces through established dealer networks.
Global OFF-THE-SHELF Second Hand Furniture Market Competitive Environment
Platform specialization dominates the current landscape, with competitive positioning hardening around logistics infrastructure and condition-verification capabilities. The vendor base stratifies into three tiers: vertically integrated refurbishers with in-house testing capabilities, curated marketplace operators with authenticated inventory, and peer-to-peer platforms competing on transaction volume. Strategic archetypes include white-glove logistics specialists, computer vision grading technology deployers, and designer-focused curation platforms. M&A activity concentrates on logistics capability acquisition, while technology licensing partnerships spread condition-verification systems across mid-market operators.
Within the premium curation tier, Chairish anchors designer and vintage segment positioning with authenticated inventory that differentiates from mass-market peer-to-peer alternatives. Kaiyo exemplifies the white-glove logistics archetype, leveraging delivery infrastructure and condition-grading systems for premium positioning on bulky upholstered items. AptDeco occupies a position in the mid-market corridor, with logistics infrastructure controlling last-mile costs for furniture moving between major metropolitan areas. These three platforms collectively represent the strategic vectors—curation depth, logistics sophistication, and regional density—that define competitive differentiation in the resale channel.
| Leading Market Players |
|---|
| Kaiyo |
| AptDeco |
| Chairish |
| eBay |
| Facebook Marketplace |
| Goodwill Industries |
| Habitat for Humanity ReStores |
| Craigslist |
| IKEA |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up refurbishment specialists in Germany and France anchor supply acquisition through estate-sale aggregation networks, compressing input costs while enforcing three-tier pricing discipline across vintage, refurbished, and as-is condition grades.
Pricing Analysis
Platform margin layers capture value through white-glove delivery premiums and authentication fees rather than traditional retail markup. Price differentiation stratifies across certification grade, with REACH-compliant documented provenance commanding premium positioning over informal peer-to-peer alternatives. Cost compression in the refurbished tier is intensifying because petrochemical-linked reupholstery inputs fluctuate with oil indices. Student housing operators in Berlin exhibit the highest price sensitivity, while Copenhagen design professionals absorb scarcity premiums for authenticated mid-century seating.
Supply Chain Analysis
Reupholstery foam and textile supply rests on Belgian and Dutch specialty chemical producers, with flame-retardant formulations subject to ECHA amendment tracking. Wood frame inputs draw from sustainably harvested Baltic and Scandinavian timber certified under EU Green Deal circularity protocols. Single-source vulnerability concentrates in aging craft networks where upholstery expertise lacks apprenticeship pipelines. Distribution runs through platform-controlled last-mile logistics in urban corridors, bypassing traditional furniture dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement departments at co-working operators and rental housing platforms unbundling from facility management contracts to source verified pre-owned furnishings with documented carbon reduction credentials.
For Market Incumbents: Deploy computer vision grading automation to compress inspection timelines from days to hours, absorbing quality-control bottlenecks that constrain inventory velocity. Deepen backward integration into refurbishment workshops in Spain and Italy where centralized infrastructure remains underdeveloped. Flat-pack new furniture from Southeast Asian manufacturers threatens substitution in student housing segments; counter with certified circularity documentation that satisfies EU Green Deal extended producer responsibility mandates.
For New Entrants and Emerging Players: Blockchain provenance tracking paired with AR visualization tools offers a technology-first wedge to unlock cross-border trade in authenticated vintage upholstery. Target the Spanish and Italian refurbishment infrastructure gap where logistics-capable entrants capture first-mover advantages in high-density urban markets. Go-to-market through direct procurement relationships with rapid-setup commercial space operators in Amsterdam and London who bypass traditional office dealers.
For Investors and Strategic Acquirers: Logistics platform operators are the most active acquirer in this space, consolidating last-mile delivery capabilities and condition-verification technology licenses. The five-to-ten-year viability window favors vertically integrated refurbishers with in-house REACH testing capabilities and captive supply from estate-sale aggregation networks. Watch California landfill diversion mandate expansion and New York extended producer responsibility pilot scaling as regulatory inflection signals that would accelerate platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Computer Vision Grading Deployment | German platforms reduce per-item assessment time by an order of magnitude, enabling geographic expansion. |
| Blockchain Provenance Tracking | Cross-border trade in authenticated vintage upholstery unlocks remote authentication for Copenhagen design professionals. |
| White-Glove Logistics Infrastructure | Kaiyo sustains premium positioning on bulky upholstered items through controlled last-mile delivery costs. |
| REACH Compliance Investment | French and Dutch platforms create competitive moats against informal sellers through documented material provenance. |
| Refurbishment Workshop Acquisition | Spain and Italy infrastructure gaps offer first-mover consolidation opportunities for logistics-capable entrants. |
Study Parameters
Coverage spans Germany, France, the Netherlands, the United Kingdom, and the United States, with primary inputs from each combining structured interviews with refurbishment workshop operators, co-living procurement directors, vintage dealer network owners, and logistics platform executives alongside secondary validation from EU Green Deal implementation reports, EPA waste reduction guidelines, ECHA substance-tracking amendments, and trade data on reupholstery material flows. Bottom-up inventory velocity modeling triangulates against top-down circular economy policy impact assessments.
Granularity-level framing models transaction volumes and value flows at the product-condition-material intersection, with separate treatment of vintage authentication premiums and refurbished utility pricing across the projection horizon. CAGRs derive from regression-weighted policy adoption curves and platform capacity expansion timelines. Industry-specific inputs include REACH compliance cost absorption rates and computer vision grading adoption thresholds in warehouse-scale operations.
The model holds under sustained regulatory enforcement of extended producer responsibility and landfill diversion mandates; deviation in petrochemical input volatility or craft skill pipeline collapse would shift refurbishment economics and platform margin architecture. A small set of named triggers—California mandate expansion, EU Green Deal circularity reporting escalation, and Southeast Asian flat-pack price competitiveness—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Multifunctional Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Spain Furniture Market
Furniture
Europe Outdoor Furniture Market
Furniture
North America Slide Rails Market
Furniture
Kids Furniture Market
Furniture
Brazil Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
School Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Wooden Furniture Market