
 Vietnam Sanitary Ware & Bathroom Accessories Market | 2026-2036
Vietnam Sanitary Ware & Bathroom Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Sanitary Ware & Bathroom Accessories Market Insights
Modular bathroom suites is decoupling hardware from installation services, letting buyers mix brands across fixtures. TOTO Ltd. leverages its ceramic technology leadership to anchor premium positioning in urban developments. Viglacera Corporation dominates northern Vietnam through captive manufacturing and distribution control. CAESAR Bathroom differentiates via localized design adapted to Vietnamese plumbing standards.
Vietnam sanitary ware and bathroom accessories encompass vitreous china fixtures, thermoset polymer components, and metal fittings engineered for water delivery and waste removal with flow rates typically below six liters per flush. These products serve residential, commercial, and institutional buildings requiring hygienic water management and durable surface finishes. Ceramic toilets and porcelain sinks occupy the largest volume share due to replacement cycles in aging housing stock, while stainless steel and glass accessories represent the fastest-expanding margin pool as design preferences shift toward minimalist aesthetics. The hospitality end user segment commands premium pricing through custom specifications, whereas residential distribution runs through wholesale channels serving contractor-driven bulk procurement.
Vietnam's Ministry of Construction and the country's national standards body enforce water-efficiency labeling and plumbing compatibility rules that shape product certification requirements for market entry. BIS-equivalent conformity assessment procedures for ceramic durability and lead-free metal content determine which suppliers qualify for public infrastructure tenders. Stakeholders must monitor regulatory tightening on embedded carbon in fired ceramics, as this will reshape supplier qualification criteria and manufacturing investment decisions.
Market Dynamics
Water-efficiency mandates from Vietnam's Ministry of Construction are forcing fixture redesigns across the supply chain, compressing flush volumes below six liters while manufacturers scramble to maintain performance standards.
Growth Catalysts
- Ho Chi Minh City housing stock renewal:Aging apartment complexes in District 2 and Thu Duc City are triggering wholesale bathroom renovations, creating pull-through demand for ceramic fixtures and thermoset polymer accessories.
- Da Nang hospitality pipeline:Beachfront resort construction is specifying custom vitreous china suites with integrated water-recovery systems, elevating average transaction values for qualified suppliers.
- Dual-flush mechanism adoption:Gravity-assisted and pressure-assisted dual-flush technologies are penetrating mid-market residential developments as buyers prioritize utility cost reduction.
Market Restraints
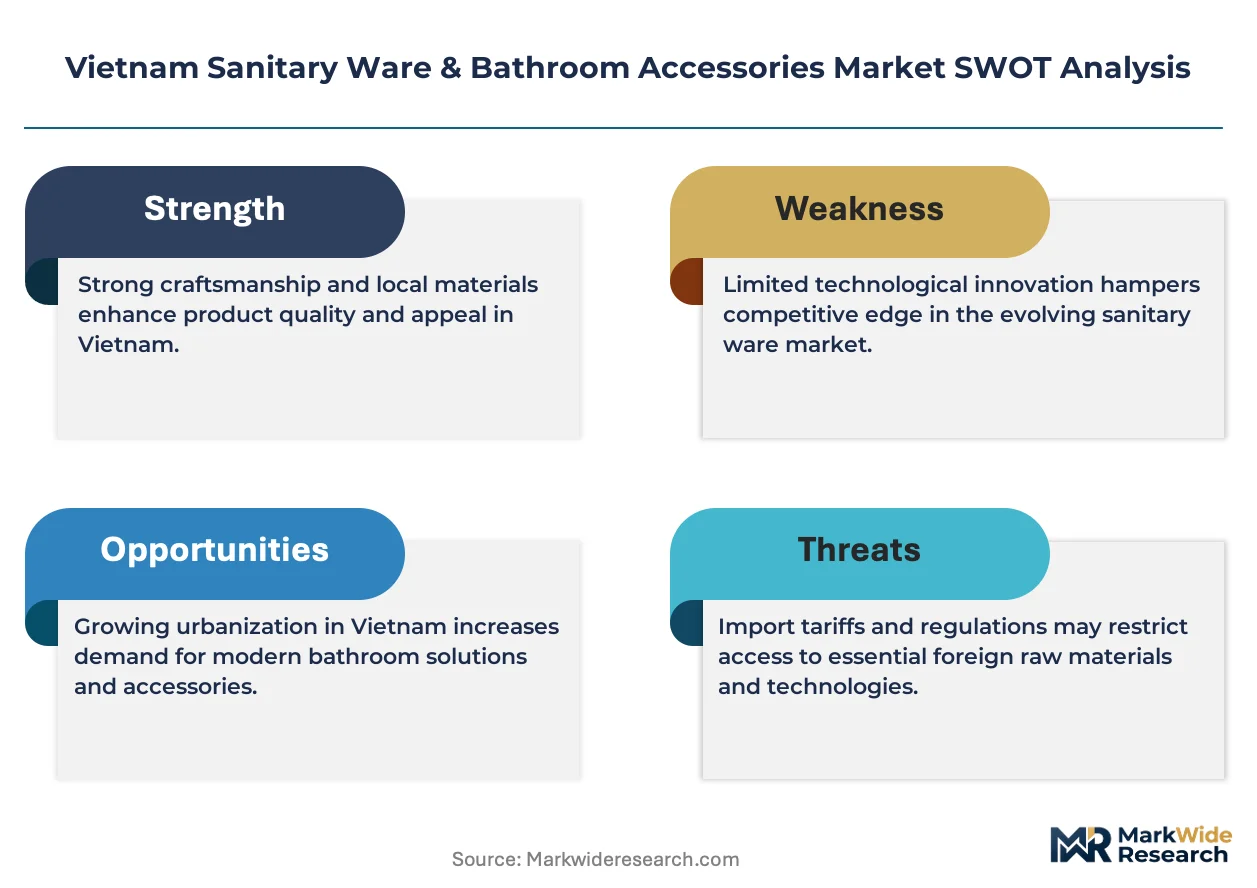
- Kaolin and feldspar import dependency:Vietnamese ceramic manufacturers rely on imported raw materials from China and India, exposing margins to freight volatility and currency fluctuation.
- Northern manufacturing concentration:Viglacera Corporation's captive production in Bac Ninh and Hai Duong provinces creates supply vulnerability to monsoon flooding and power rationing events.
- Lead-free brass sourcing constraints:Biocide-free metal alloy certification for faucets and fittings remains bottlenecked by limited Southeast Asian foundry capacity.
Strategic Opportunities
- Phu Quoc integrated resort zone:The island's special economic status and accelerated hotel construction timeline create demand for imported premium fixtures with extended warranty terms.
- Smart bathroom convergence:Sensor-activated flush valves and IoT-enabled leak detection are opening specification opportunities in Hanoi luxury condominiums targeting tech-forward buyers.
- Rural provincial distribution gaps:Can Tho, Da Lat, and Hue lack dedicated sanitary ware showrooms, presenting whitespace for contractor-direct bulk supply arrangements.
Industry Challenges
- Ceramic firing technician scarcity:Vietnamese technical colleges produce insufficient kiln operators versed in computerized temperature profiling for vitreous china production.
- BIS-equivalent conformity timeline:New entrants face six-to-nine-month certification delays for ceramic durability and metal content testing at Vietnam's national standards body.
- Legacy plumbing compatibility:Retrofit installations in 1990s-era buildings require adapters for non-standard pipe diameters, complicating inventory management for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Sanitary Ware & Bathroom Accessories Market |
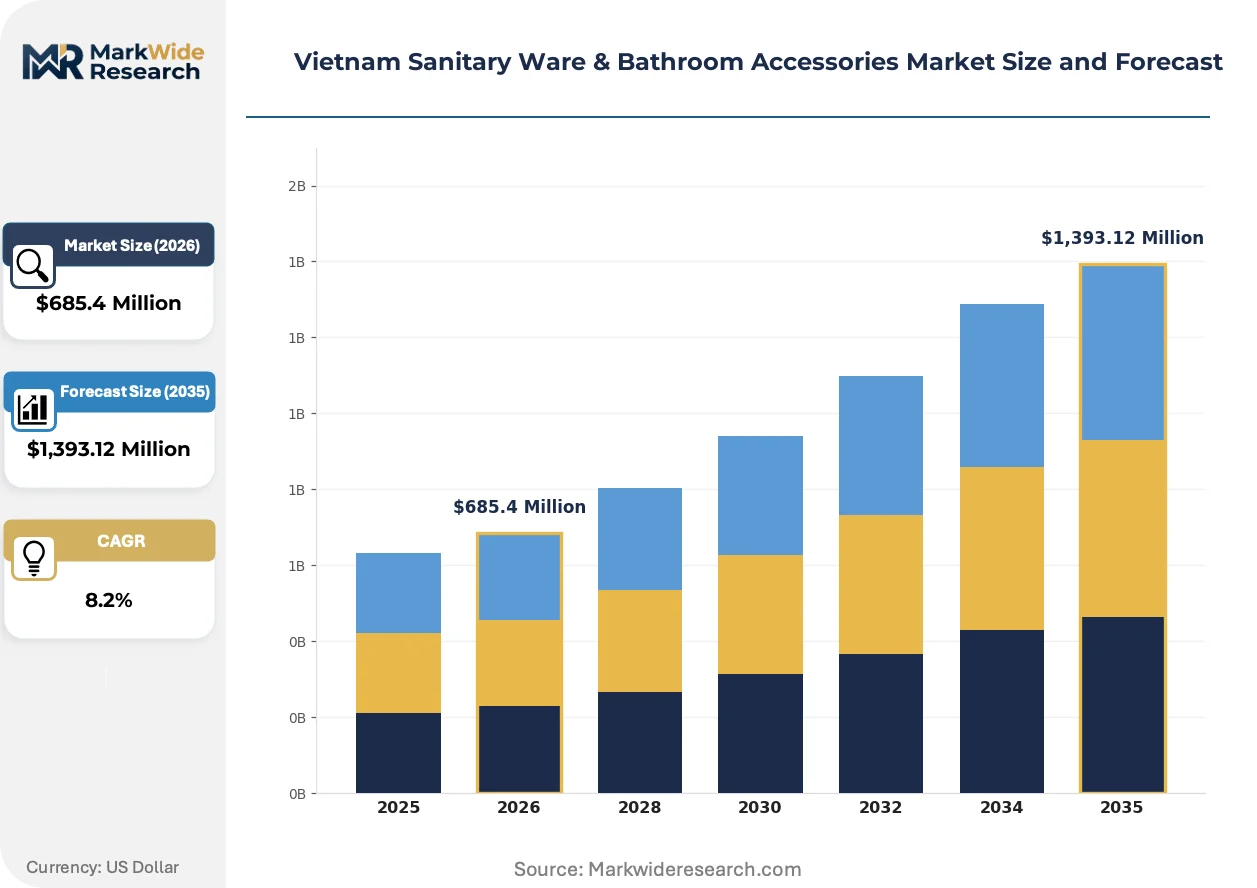
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Sinks, Showers, Bathtubs Material: Ceramic, Porcelain, Glass, Stainless Steel End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Jaquar Group, Roca Sanitario, S.A., CAESAR Bathroom, Viglacera Corporation, TOTO Ltd., Gessi SpA, LIXIL Group, Thien Thanh Sanitaryware Joint Stock Company, Innoci Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Sanitary Ware & Bathroom Accessories Market Trends and Innovations
Rimless toilet bowl designs and concealed cistern systems are compressing traditional fixture footprints while Vietnamese developers pursue higher space-efficiency ratios in compact urban units.
Electrochromic glass and anti-fog mirror technology is electrifying the accessories segment, enabling hospitality operators to eliminate visible wiring and reduce cleaning labor. Five-star properties in Da Nang are specifying these surfaces for 40% of new bathroom installations. The shift is compressing demand for conventional framed mirrors with exposed heating elements.
Vietnam's Ministry of Construction water-efficiency labeling scheme is tightening eligibility thresholds for public infrastructure tenders, compelling manufacturers to submit third-party flow-rate verification. Ceramic fixture suppliers must now document sub-4.8-liter flush performance to qualify for government housing projects. Northern manufacturers are responding by retrofitting glaze formulations to reduce surface friction and improve waste removal at lower volumes.
Developer-direct procurement is displacing traditional wholesale channel dominance in Ho Chi Minh City and Hanoi, with Vinhomes and Novaland negotiating frame agreements for standardized bathroom packages. Contractors are losing specification influence as procurement teams centralize vendor selection at headquarters level. This concentration is most visible in Thu Duc City's master-planned communities, where single-source sanitary ware contracts cover 500-unit phases.
Vietnam Sanitary Ware & Bathroom Accessories Market Segmentation
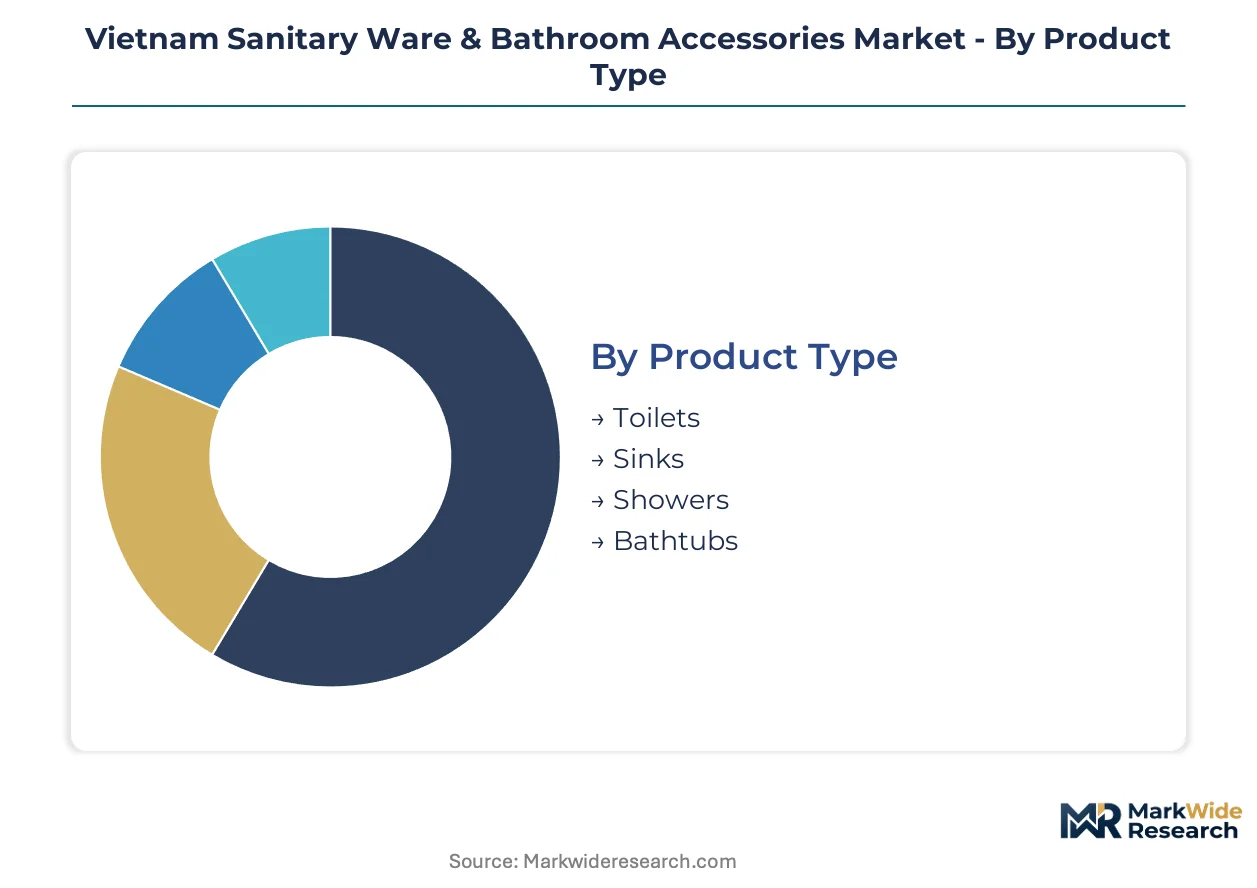
Vietnam's sanitary ware market fragments across four distinct dimensions that govern supplier positioning and margin capture. Product type and material composition determine manufacturing investment requirements, while end-user concentration and channel structure shape pricing power and working capital intensity.
Product Type:
Supply concentration clusters around high-volume ceramic fixtures where kiln capacity constraints favor incumbents with captive production.
- Toilets:Vitreous china fixtures with siphonic or washdown flush mechanisms dominate procurement volumes in Ho Chi Minh City residential developments. Vietnam's Ministry of Construction water-efficiency mandates below six liters per flush are forcing glaze reformulations to maintain waste removal performance at reduced volumes.
- Sinks:Countertop and wall-mounted basins in ceramic and solid surface materials anchor bathroom suite specifications. Da Nang hospitality projects are specifying integrated vanity systems with concealed drainage, compressing demand for standalone pedestal designs.
- Showers:Thermostatic mixer systems and frameless glass enclosures serve mid-market residential retrofits. Stainless steel rain showerheads from Thai and Chinese suppliers are gaining specification share in Hanoi luxury condominiums.
- Bathtubs:Acrylic and enameled steel soaking tubs retain niche demand in premium residential and spa-hospitality segments. Import dependency for acrylic sheet and reinforcement fiberglass limits domestic manufacturing scale.
Today's leader: Toilets. Tomorrow's challenger: Showers.
Material:
Cost tier stratification separates commodity ceramics from premium metals and glass where import content elevates landed costs.
- Ceramic:Fired vitreous china with alumina-enhanced glaze formulations provides the dominant substrate for toilets and sinks. Viglacera Corporation's captive Bac Ninh kilns supply northern Vietnam with standardized whiteware, though kaolin import dependency from China exposes margins to freight volatility.
- Porcelain:Higher-density ceramic with lower water absorption rates commands specification in high-traffic commercial restrooms. TOTO Ltd. leverages Japanese firing technology to anchor premium positioning in urban master-planned developments.
- Glass:Tempered safety glass for shower enclosures and vanity surfaces represents the fastest-expanding margin pool. Electrochromic anti-fog mirror technology is penetrating Da Nang five-star properties at 40% of new bathroom installations.
- Stainless Steel:Grade 304 and 316 alloys for faucets, drains, and accessories face lead-free certification bottlenecks from limited Southeast Asian foundry capacity. Biocide-free metal content verification extends procurement timelines for public infrastructure tenders.
Volume dominance: Ceramic. Margin expansion: Glass.
End User:
Application-driven demand splits between replacement cycles in aging housing stock and new construction in hospitality corridors.
- Residential:District 2 and Thu Duc City apartment renewal drives bulk procurement of water-efficient dual-flush systems. Developer-direct frame agreements with Vinhomes and Novaland are displacing traditional wholesale channel influence.
- Commercial:Office and retail fit-outs specify durable vitreous china with vandal-resistant flush valves. BIS-equivalent conformity assessment for ceramic durability determines qualification for government building tenders.
- Institutional:Schools and hospitals require sensor-activated fixtures to reduce cross-contamination risk. Procurement centralization at provincial education and health departments compresses vendor margins through competitive bidding.
- Hospitality:Phu Quoc integrated resort construction demands imported premium fixtures with extended warranty terms. Custom vitreous china suites with integrated water-recovery systems elevate average transaction values for qualified suppliers.
Procurement concentration: Residential. Premium pricing power: Hospitality.
Distribution Channel:
Customer type and geography dictate channel selection, with urban consolidation favoring direct procurement over fragmented wholesale networks.
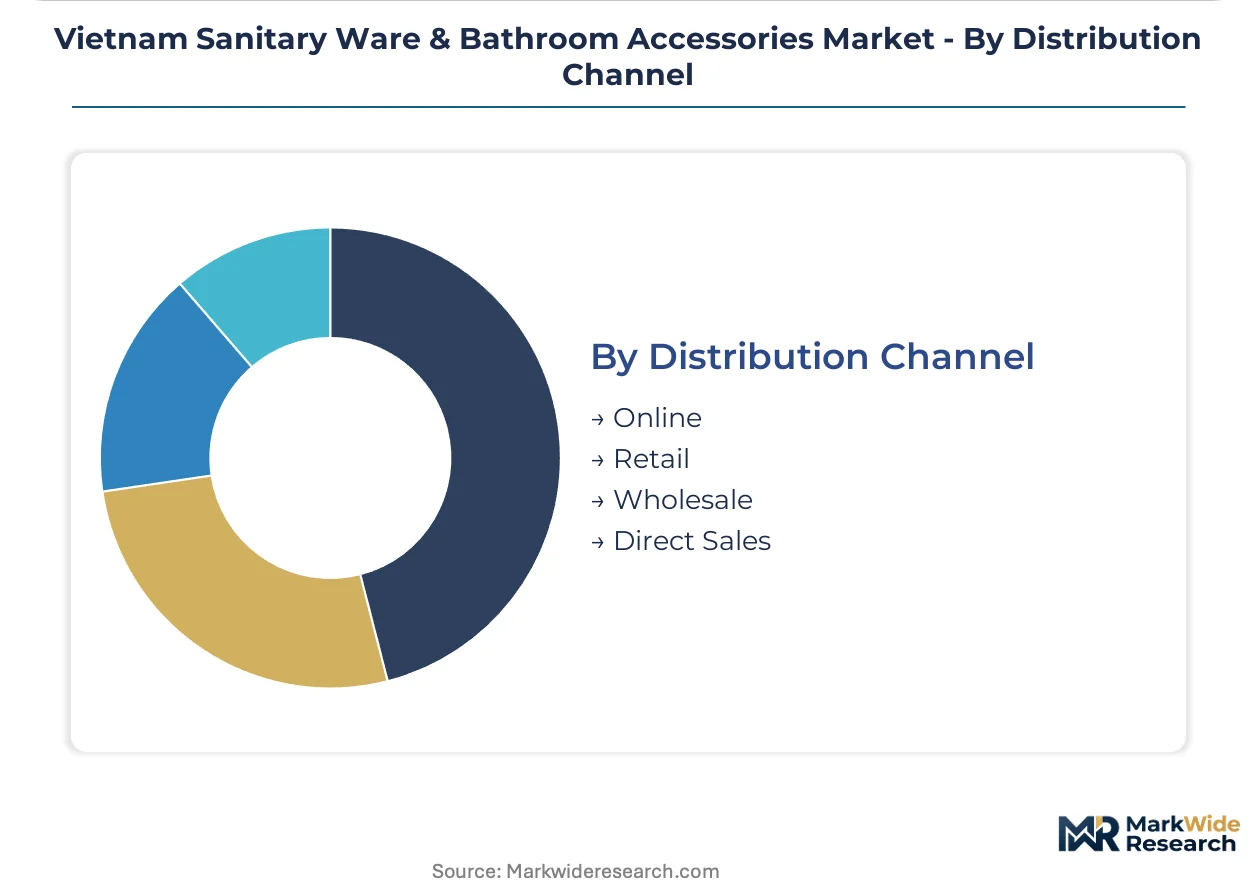
- Online:E-commerce platforms serve replacement part demand and accessory upgrades in secondary cities. Logistics constraints for bulky ceramic fixtures limit penetration beyond glass and metal accessories.
- Retail:Showroom networks in Ho Chi Minh City and Hanoi cater to renovation-driven homeowners seeking tactile evaluation. Can Tho, Da Lat, and Hue lack dedicated sanitary ware showrooms, presenting whitespace for format expansion.
- Wholesale:Contractor-serving distributors retain volume share in provincial construction markets. Legacy plumbing compatibility issues for 1990s-era buildings complicate inventory management with adapter SKU proliferation.
- Direct Sales:Developer and hospitality procurement teams negotiate frame agreements for standardized bathroom packages. Thu Duc City master-planned communities execute single-source contracts covering 500-unit phases.
Volume throughput: Wholesale. Margin capture: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's sanitary ware industry traces its manufacturing lineage to state-owned ceramic enterprises established during the 1960s in northern provinces, which evolved into today's vertically integrated production clusters serving domestic and export markets.
Ho Chi Minh City
District 2 and Thu Duc City apartment renewal drives bulk procurement of water-efficient dual-flush systems. The Ministry of Construction's 2023 building code tightening compels developers to source sub-six-liter flush fixtures. Developer-direct frame agreements with Vinhomes and Novaland are displacing traditional wholesale channel influence across master-planned communities.
Hanoi
Luxury condominium construction in Cau Giay and Tay Ho districts specifies sensor-activated flush valves and IoT-enabled leak detection systems. The national standards body enforces BIS-equivalent conformity assessment for ceramic durability and lead-free metal content. Viglacera Corporation's captive Bac Ninh kilns supply standardized whiteware to northern Vietnam residential developments.
Da Nang
Beachfront resort construction specifies custom vitreous china suites with integrated water-recovery systems. Hospitality procurement teams negotiate extended warranty terms for imported premium fixtures. The city's accelerated hotel construction timeline elevates average transaction values for qualified ceramic suppliers.
Phu Quoc
The island's special economic status attracts integrated resort investment specifying imported fixtures with custom specifications. Water-efficiency labeling scheme compliance determines eligibility for hospitality tenders. Construction activity concentrates in the southern beach zone where five-star properties drive premium accessory demand.
Can Tho and Mekong Delta
Rural provincial distribution gaps in secondary cities create whitespace for contractor-direct bulk supply arrangements. Provincial construction markets rely on wholesale distributors serving renovation-driven homeowners. The absence of dedicated sanitary ware showrooms limits brand penetration beyond glass and metal accessories.
Vietnam Sanitary Ware & Bathroom Accessories Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic incumbents with captive kiln capacity and distribution control. Market concentration clusters around ceramic fixture manufacturing where capital-intensive firing infrastructure favors established players with multi-decade operational history. Two strategic archetypes dominate: Japanese technology licensors anchoring premium urban positioning, and Vietnamese state-legacy manufacturers controlling northern supply corridors. Competitive moves center on developer-direct procurement consolidation and glaze formulation licensing for water-efficiency compliance.
Among Vietnamese state-legacy manufacturers, Viglacera Corporation exemplifies the vertically integrated archetype through northern production concentration and distribution control. CAESAR Bathroom occupies a position within the localization-focused tier, adapting designs to domestic plumbing standards. TOTO Ltd. represents the technology-licensor archetype, leveraging Japanese firing expertise to anchor premium positioning in Hanoi and Ho Chi Minh City master-planned developments.
| Leading Market Players |
|---|
| Jaquar Group |
| Roca Sanitario, S.A. |
| CAESAR Bathroom |
| Viglacera Corporation |
| TOTO Ltd. |
| Gessi SpA |
| LIXIL Group |
| Thien Thanh Sanitaryware Joint Stock Company |
| Innoci Vietnam |
| Others |
Pricing and Supply Chain Analysis
Kiln operator scarcity in northern Vietnamese provinces widens pricing-tier spreads between premium Japanese-licensed ceramics and economy-grade domestic output. Labor-cost differentials between Bac Ninh's captive production clusters and Ho Chi Minh City's assembly-dependent distributors compress margins at the standard tier while elevating premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction values in Vietnam's sanitary ware market. Price differentiation hinges on water-efficiency certification grade and glaze formulation technology. Cost compression in the economy tier intensifies because kaolin import dependency from China exposes margins to freight volatility. Residential developers in Thu Duc City exhibit highest price sensitivity, while Phu Quoc hospitality procurement teams prioritize warranty terms over unit cost.
Supply Chain Analysis
Freight volatility on China-Vietnam routes elevates landed costs for ceramic raw materials and pressure-assisted flush mechanisms. Manufacturing concentrates in Vietnam, China, and Thailand, with Vietnamese kilns drawing from Indian feldspar and Chinese kaolin deposits. Single-source vulnerability to monsoon flooding in Bac Ninh province threatens northern supply continuity. Distribution runs through developer-direct frame agreements in urban centers and wholesale contractor networks in provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's sanitary ware market offers margin-expansion potential as water-efficiency mandates force glaze reformulation investments that premium-tier suppliers can monetize through developer-direct procurement consolidation.
For Market Incumbents: Lock in developer frame agreements before Vinhomes and Novaland finalize 500-unit phase contracts. Secure captive kaolin supply through backward integration into Indian mining partnerships to offset Chinese import dependency. Viglacera Corporation's northern concentration creates flooding exposure that TOTO Ltd. can exploit through southern logistics redundancy. For New Entrants and Emerging Players: The mid-market gap between TOTO's premium positioning and Viglacera's economy dominance offers specification whitespace. Target Can Tho and Hue's showroom-deficient provincial markets through contractor-direct bulk supply arrangements. Lead with IoT-enabled leak detection systems to differentiate in Hanoi's luxury condominium pipeline. For Investors and Strategic Acquirers: Japanese building-material conglomerates are the most active acquirer in this space, seeking ceramic technology licensing platforms. Five-to-ten-year viability favors suppliers with water-efficiency certification ahead of Ministry of Construction threshold tightening. Monitor Phu Quoc resort construction permit issuance as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Glaze Formulation Licensing | Japanese firing technology transfers anchor premium positioning in master-planned developments. |
| Developer-Direct Procurement Consolidation | Vinhomes and Novaland frame agreements displace wholesale channel influence in Thu Duc City. |
| Water-Efficiency Certification Investment | Sub-4.8-liter flush verification qualifies suppliers for government housing project tenders. |
| Provincial Distribution Expansion | Can Tho and Hue showroom gaps present whitespace for contractor-direct bulk arrangements. |
| Smart Bathroom Technology Integration | Sensor-activated flush valves open specification opportunities in Hanoi luxury condominiums. |
Research Methodology
Bottom-up residential and hospitality demand modeling reconciled against top-down ceramic production capacity tracking forms the analytical core. Primary interviews with kiln operations managers, hospitality procurement directors, developer sourcing leads, and wholesale distributor principals combined with secondary validation from Vietnam Ministry of Construction building code filings, national standards body certification registries, and customs import data for kaolin and feldspar shipments.
Historical trendline analysis of fixture replacement cycles and new construction permit issuance established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user application, and distribution channel structure. CAGRs derived from volume-outcome modeling incorporating water-efficiency mandate compliance timelines and hospitality construction pipeline data.
Caveats apply where Ministry of Construction regulatory tightening or Phu Quoc special economic zone investment suspension could materially shift the outlook. Forecasts reflect assumptions about ceramic durability certification timelines and monsoon season production continuity. A model refresh is warranted upon material change in developer-direct procurement concentration or kaolin import tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Toilet Seat Market