
 Camera Accessories Market | 2026-2036
Camera Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Accessories Market Analysis
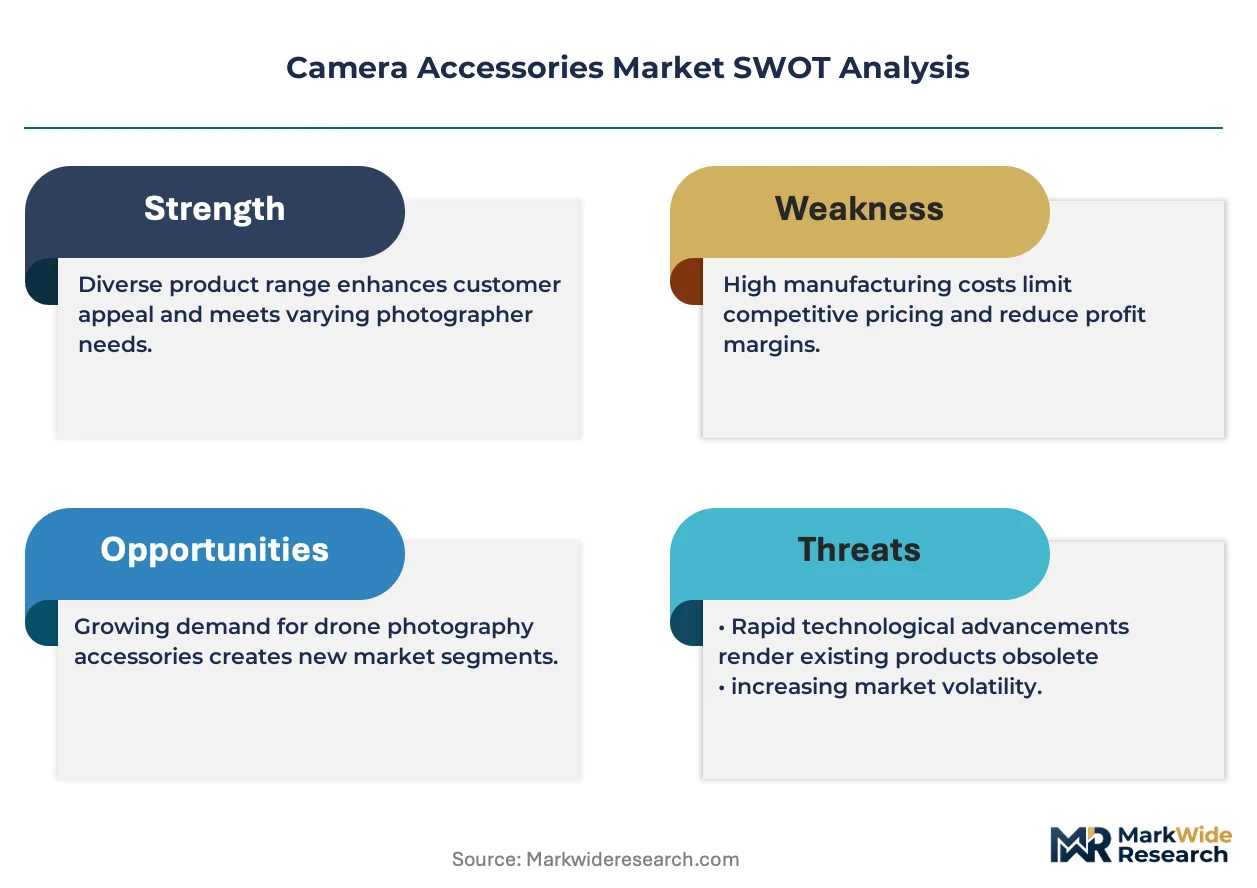
Online retail is reshaping how camera accessories reach end users, with direct-to-consumer platforms bypassing traditional specialty stores. Canon Inc. leverages its established brand ecosystem to bundle accessories with camera bodies. Sony Group Corp. competes through proprietary battery and mount systems that lock users into its product orbit. Peak Design differentiates via modular clip-and-plate architectures that span multiple device categories.
Camera accessories encompass auxiliary equipment that extends optical capture capability, including stabilization platforms, light-modification films, power cells, and illumination units typically engineered to precision tolerances of 0.1 mm for mount compatibility. These products serve commercial imaging workflows where operational uptime and shot consistency carry direct revenue consequences. Carbon fiber tripods command premium positioning among professional photographers who prioritize weight reduction for location work. Aluminum variants dominate hobbyist demand through cost accessibility. Online retail channels capture the fastest volume expansion as videographers research and purchase filters and batteries through platform algorithms.
The EU's RoHS directive and REACH framework restrict cadmium and lead content in batteries and electronic contacts, forcing reformulation of power cell chemistries. The US FCC regulates wireless trigger and remote-control accessories for radio-frequency emissions, adding certification layers to product development cycles. China's GB standards govern charger safety and interoperability, affecting export qualification for Shenzhen-based manufacturers. Stakeholders must monitor how battery-safety regulations in multiple jurisdictions converge or diverge, as compliance fragmentation could reshape supplier qualification costs and sourcing geography.
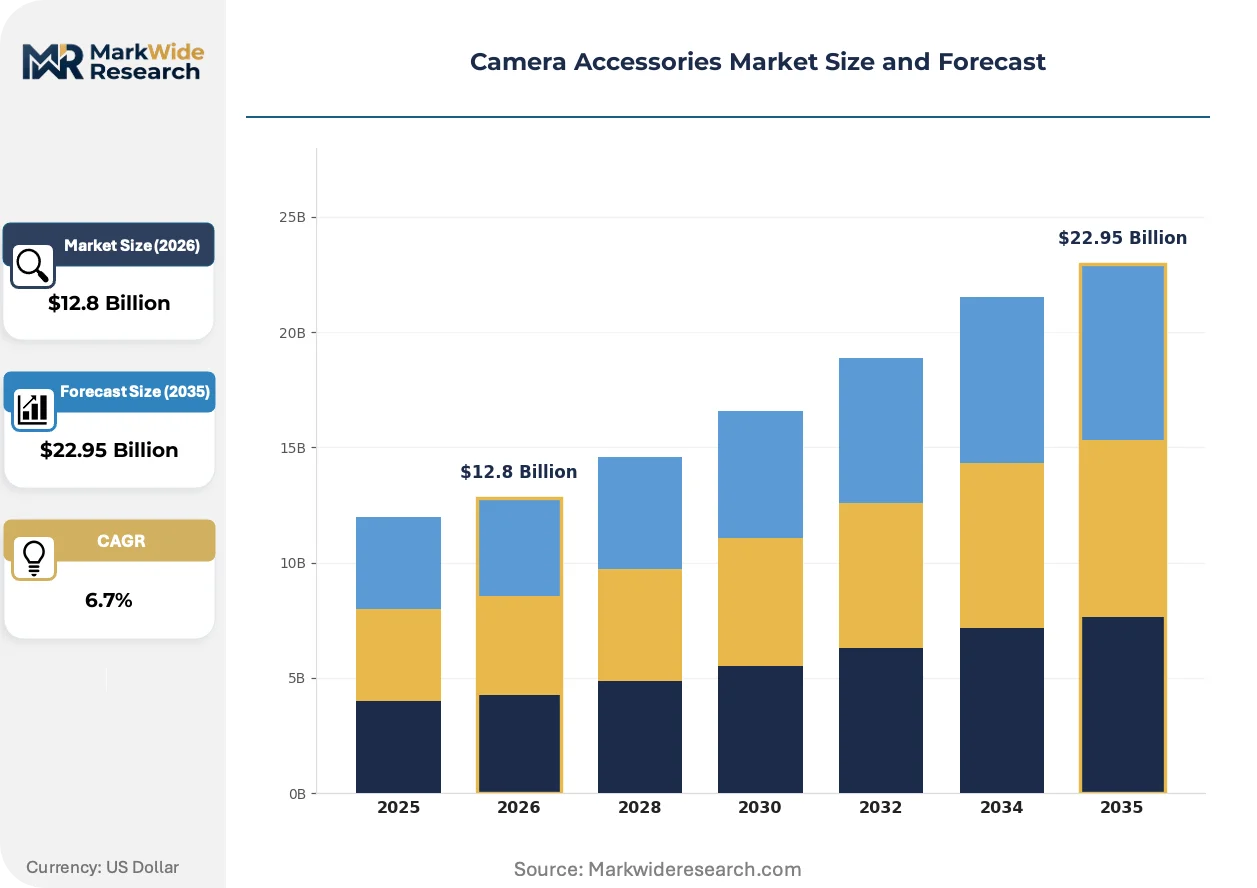
Market Dynamics
Content creators on TikTok and YouTube are compressing product refresh cycles, forcing accessory manufacturers to accelerate modular platform releases while Shenzhen's manufacturing cluster concentrates global tripod and gimbal supply.
Growth Catalysts
- REACH and RoHS frameworks:The EU's tightening hazardous substance restrictions on batteries and electronic contacts are accelerating reformulation investments, opening qualification advantages for compliant chemistry suppliers.
- Carbon fiber stabilization platforms:Location photographers are migrating from aluminum to carbon fiber tripods, pulling demand toward premium-weight reduction architectures.
- Shenzhen manufacturing cluster:Concentrated production of motorized gimbals and quick-release plates is compressing lead times and enabling rapid prototype-to-production cycles for direct-to-consumer brands.
Market Restraints
- Lithium-ion cell cost volatility:Raw material price swings for cobalt and nickel are destabilizing battery pack pricing, squeezing margin predictability for power accessory vendors.
- Single-city supply concentration:Overreliance on Shenzhen for precision-machined mounts and carbon fiber tubing creates vulnerability to localized logistics disruptions or energy rationing.
- Proprietary mount lock-in:Sony's E-mount and Canon's RF-mount ecosystems fragment accessory compatibility, forcing third-party vendors to maintain multiple tooling sets.
Strategic Opportunities
- India content creator economy:Short-form video production in Mumbai and Bangalore is outpacing local accessory supply, creating import substitution potential for gimbal and lighting kit distributors.
- GB standards harmonization:China's charger safety certification convergence with IEC protocols is reducing dual-testing burdens, opening export qualification efficiencies for Shenzhen manufacturers.
- Modular clip architectures:Cross-device mounting systems spanning cameras, drones, and smartphones are hybridizing accessory categories, enabling SKU consolidation for platform-native brands.
Industry Challenges
- FCC Part 15 certification timelines:Wireless trigger and remote-control accessories face extended radio-frequency emission testing cycles, delaying product launches by four to six months.
- Precision machining talent scarcity:CNC operators capable of maintaining 0.1 mm mount tolerances are concentrated in aging workforces across Dongguan and Taichung, constraining quality-scaling capacity.
- Legacy battery form factor fragmentation:Incompatible cell geometries across camera generations complicate inventory management for rental houses and retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Accessories Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tripods, Filters, Batteries, Flash End User: Professional Photographers, Hobbyists, Studios, Videographers Material: Aluminum, Carbon Fiber, Plastic, Glass Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Canon Inc., Sony Group Corp., Nikon Corp., FUJIFILM Holdings Corp., Panasonic Holdings Corp., GoPro Inc., SZ DJI Technology Co. Ltd., Peak Design, Manfrotto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Accessories Market Emerging Trajectories
Stabilization and power technologies are converging with software-defined control systems, while regulatory chemistry mandates and platform-native distribution are compressing traditional hardware release cycles.
Computational gimbal stabilization is hybridizing mechanical and electronic correction methods. Wedding videographers and travel content creators are adopting smartphone-sized three-axis motors with integrated subject-tracking AI. This convergence is collapsing the performance gap between entry-level and professional stabilization rigs, forcing hardware vendors to differentiate through software subscription layers rather than mechanical precision alone.
REACH Annex XVII restrictions on cadmium and lead in battery contacts are forcing cell manufacturers toward nickel-manganese-cobalt alternatives. The reformulation burden falls heaviest on low-cost power pack producers serving hobbyist segments, while premium brands with established chemistry partnerships absorb compliance costs more readily. Shenzhen exporters are consolidating testing laboratory relationships to maintain EU market access.
Direct-to-consumer platform algorithms are displacing specialty retail discovery for filter and battery purchases. Videographers on YouTube and TikTok now research accessories through creator affiliate links rather than brick-and-mortar counter staff, compressing the consideration phase from weeks to hours. This behavioral shift concentrates marketing spend toward platform-native content production rather than trade show presence or dealer training programs.
Camera Accessories Market Segmentation
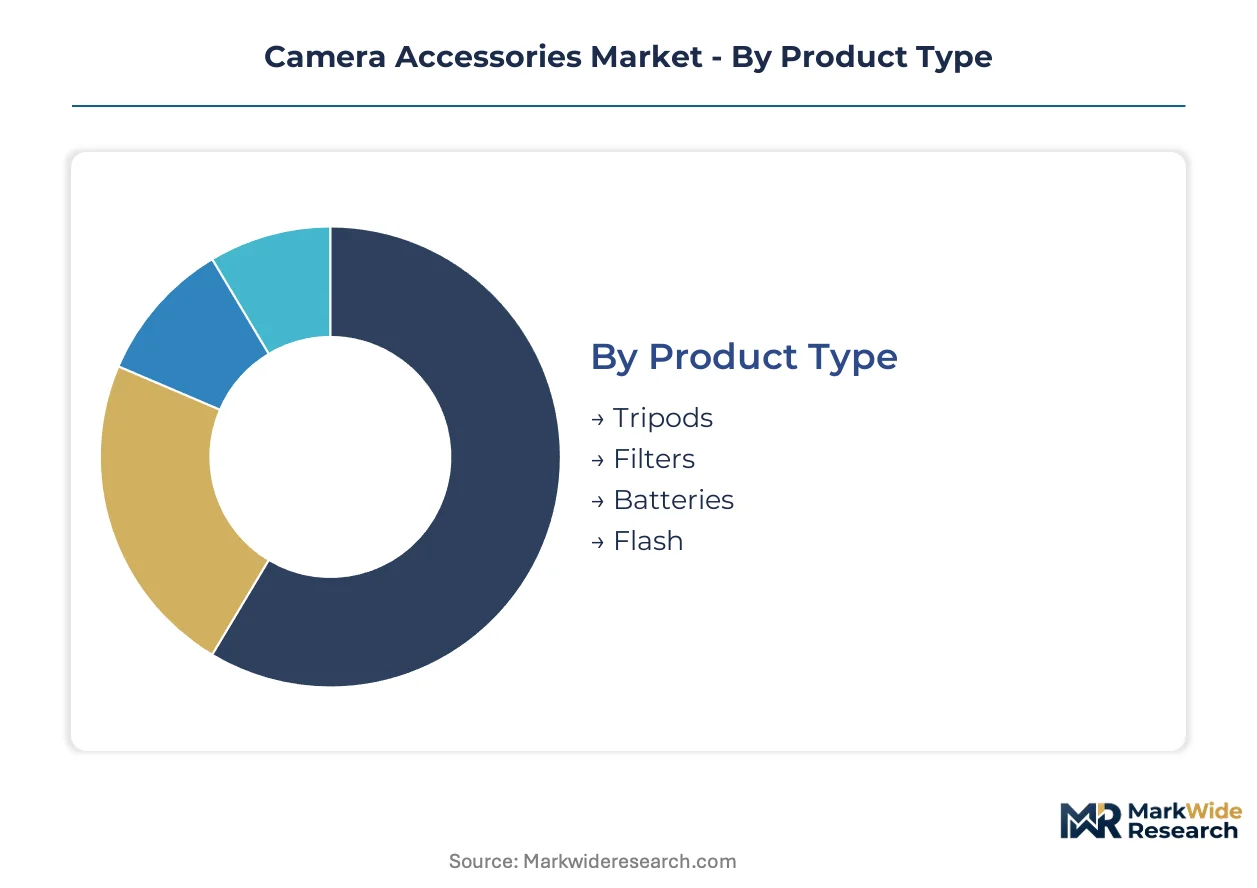
Camera accessories serve divergent workflows from TikTok creators to commercial studios, requiring manufacturers to balance precision engineering against cost accessibility. Segmentation reveals how material choices and channel strategies separate premium stabilization platforms from mass-market power cells.
Product Type:
Professional workflows demand stabilization and light-modification equipment, while content creators prioritize power redundancy and compact mounting solutions.
- Tripods:Carbon fiber variants achieve sub-kilogram weights for location photographers trekking to remote shoot sites. Demand clusters among wedding videographers in India and travel creators in Southeast Asia who trade absolute stability for portability. The dominant share belongs to tripods, while filters are closing the gap fastest.
- Filters:Polarizing and neutral-density films require optical-grade glass polished to wavelength-specific tolerances. Cinematographers in Germany and France drive replacement cycles as sensor dynamic range improves, forcing filter stack recalibration.
- Batteries:Lithium-ion packs with nickel-manganese-cobalt chemistries comply with REACH Annex XVII restrictions on cadmium contacts.
- Flash:Studio monolights and speedlights serve controlled lighting environments where recycle time and color temperature consistency determine purchasing decisions.
Stabilization platforms absorb the largest equipment budgets, though power accessories generate recurring revenue through cell degradation cycles.
End User:
Customer sophistication spans from algorithm-dependent content creators to technicians calibrating shot-to-shot consistency for commercial clients.
- Professional Photographers:These users specify 0.1 mm mount tolerances and demand carbon fiber weight reduction for multi-day location assignments. Procurement concentrates in Germany, Japan, and the United States where commercial imaging rates justify premium equipment spend.
- Hobbyists:Cost sensitivity dominates aluminum tripod selection and third-party battery adoption.
- Studios:Fixed installations prioritize durability over portability, favoring steel-reinforced light stands and cabled power solutions.
- Videographers:Three-axis gimbal demand is expanding most quickly among YouTube and TikTok creators in Mumbai and Bangalore.
Professional photographers command the highest per-capita spend, yet videographers are gaining share fastest through platform-native content monetization.
Material:
Weight-to-stiffness ratios and electromagnetic shielding properties separate aerospace-grade composites from commodity polymers.
- Aluminum:Extruded 6061-T6 alloy dominates entry-level tripod legs and mounting brackets through machining cost efficiency.
- Carbon Fiber:Woven prepreg tubes achieve specific stiffness metrics impossible with metallic alternatives. Location specialists in the United States and Germany absorb 70-80% price premiums for kilogram-level weight savings on international flights.
- Plastic:Glass-reinforced polymers serve battery housings and quick-release levers where impact resistance outweighs thermal conductivity requirements.
- Glass:Schott and Hoya optical substrates provide the refractive index stability required for color-accurate filter production.
Carbon fiber claims the margin-rich premium tier, while aluminum maintains volume leadership through hobbyist accessibility.
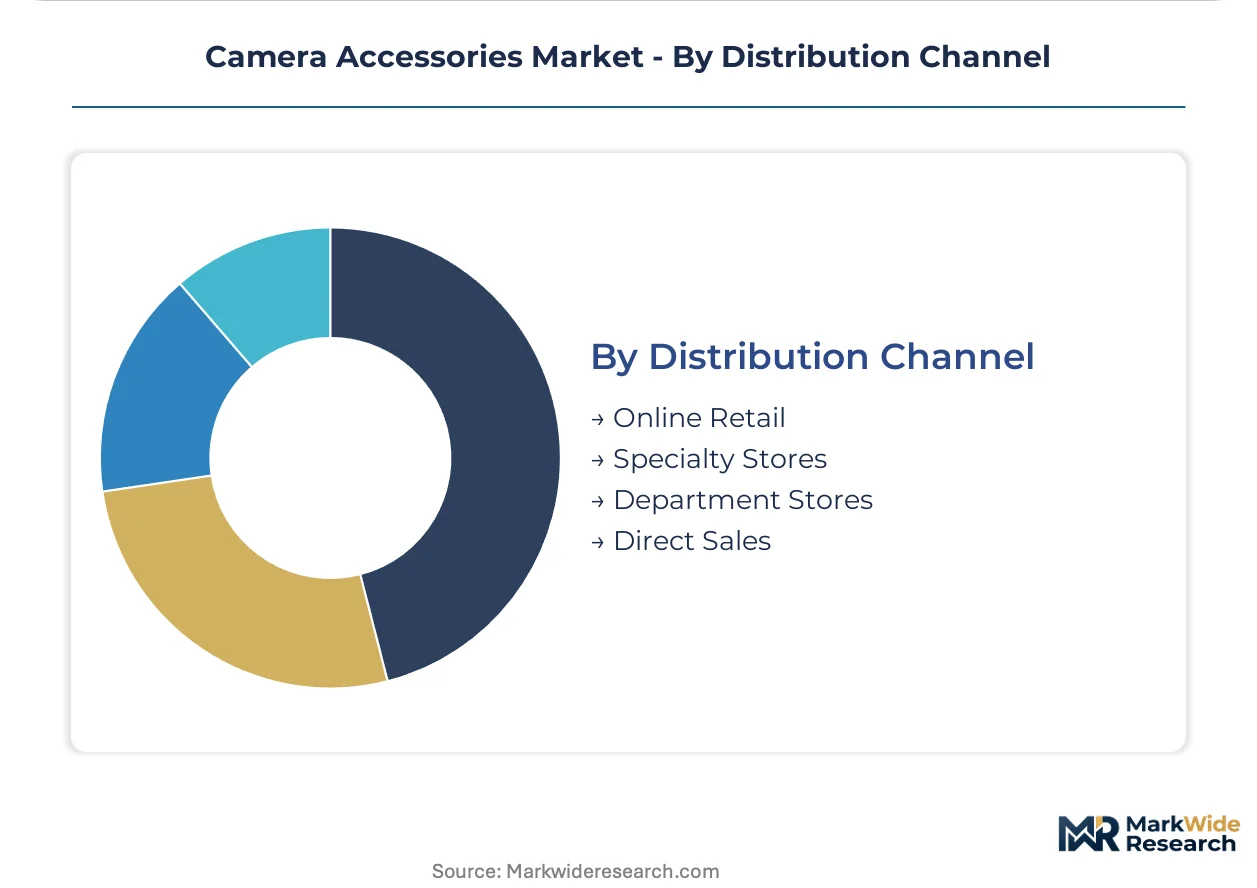
Distribution Channel:
Discovery behavior has shifted from counter staff consultation to algorithm-driven platform recommendations, reshaping inventory and marketing investments.
- Online Retail:Platform algorithms now surface filters and batteries to videographers within hours of camera body purchase. Amazon and direct-to-consumer sites capture creator segment growth through affiliate link ecosystems.
- Specialty Stores:Remaining brick-and-mortar presence concentrates in Tokyo's Shinjuku and New York's midtown districts where hands-on stabilization testing justifies rent premiums.
- Department Stores:Mass-market electronics sections stock entry-level tripods and universal battery chargers for casual photographers.
- Direct Sales:Manufacturer-owned channels bypass retailer margin extraction for professional lighting and motion control systems.
Online retail commands the dominant transaction volume, though specialty stores defend relevance through high-consideration stabilization purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional photographers in Germany absorb 70-80% price premiums for carbon fiber tripods, while hobbyists in India prioritize aluminum variants at entry-level price points. This pricing-power asymmetry reflects divergent commercial imaging rates and platform-native content monetization maturity across markets.
United States
Wedding videographers and travel content creators drive carbon fiber stabilization demand, prioritizing sub-kilogram weights for location work. The FCC regulates wireless trigger accessories under Part 15 for radio-frequency emissions, extending certification timelines by four to six months. Los Angeles and New York anchor specialty retail presence where hands-on gimbal testing justifies rent premiums.
China
Shenzhen's manufacturing cluster supplies the majority of global tripod and gimbal production, compressing lead times for direct-to-consumer brands. GB standards govern charger safety and interoperability, affecting export qualification for Pearl River Delta manufacturers. Dongguan faces precision machining talent scarcity as CNC operators capable of 0.1 mm mount tolerances concentrate in aging workforces.
Germany
Cinematographers in Berlin and Munich drive filter replacement cycles as sensor dynamic range improves, forcing filter stack recalibration. REACH Annex XVII and RoHS directives restrict cadmium and lead content in battery contacts, accelerating reformulation toward nickel-manganese-cobalt chemistries. Bavaria hosts optical-grade glass polishing operations for Schott substrate production.
India
Short-form video production in Mumbai and Bangalore outpaces local accessory supply, creating import substitution potential for gimbal and lighting kit distributors. BIS certification requirements for electronic imports add compliance layers to product entry. Content creators on YouTube and TikTok compress product refresh cycles through algorithm-driven discovery.
Japan
Commercial imaging workflows in Tokyo and Osaka command premium equipment spend, justifying carbon fiber weight reduction investments. METI oversees industrial standards coordination while JIS specifications govern mount compatibility tolerances. Kanto region specialty stores in Shinjuku maintain hands-on stabilization testing infrastructure.
Camera Accessories Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three strata: camera body manufacturers bundling proprietary accessories, Shenzhen-based precision fabricators serving direct-to-consumer channels, and modular platform specialists spanning multiple device categories. Strategic moves concentrate on M&A for mount ecosystem control and vertical integration into carbon fiber prepreg sourcing.
Within the platform integrator tier, Canon Inc. and Sony Group Corp. anchor proprietary ecosystem strategies through battery and mount system lock-in. SZ DJI Technology Co. Ltd. exemplifies the Shenzhen fabrication archetype with concentrated production of motorized stabilization platforms. Peak Design occupies a position in the modular specialist tier, representing cross-device mounting architectures that hybridize accessory categories.
| Leading Market Players |
|---|
| Canon Inc. |
| Sony Group Corp. |
| Nikon Corp. |
| FUJIFILM Holdings Corp. |
| Panasonic Holdings Corp. |
| GoPro Inc. |
| SZ DJI Technology Co. Ltd. |
| Peak Design |
| Manfrotto |
| Others |
Supply Flow & Price Mechanics
The Shenzhen-Dongguan freight corridor compresses logistics costs for carbon fiber tubing and precision-machined mounts, enabling Shenzhen manufacturers to sustain aggressive pricing on gimbals while European REACH compliance costs widen the premium spread for battery suppliers serving German cinematographers.
Pricing Analysis
The customization-premium spread separates configured-to-order carbon fiber tripods from standard aluminum SKUs, with pricing stratifying across premium, standard, and economy tiers based on weight reduction performance and mount tolerance certification. Brand premiums for proprietary E-mount and RF-mount ecosystems sustain 40-60% markups over third-party alternatives. Cost compression in entry-level batteries intensifies because nickel-manganese-cobalt chemistry reformulations absorb REACH compliance overhead. Hobbyists exhibit highest price sensitivity, while location photographers in Germany and the United States absorb premiums for sub-kilogram stabilization platforms.
Supply Chain Analysis
Supplier-financing facilities from Pearl River Delta manufacturers extend 90-120 day payment terms to direct-to-consumer brands, anchoring working capital efficiency in Shenzhen's manufacturing cluster. Raw material dependencies rest on Japanese Toray carbon fiber prepreg, South Korean lithium-ion cell chemistries, and German Schott optical glass substrates. Single-city concentration in Shenzhen creates vulnerability to localized energy rationing or logistics disruptions. Distribution runs through platform-native algorithms for filters and batteries, while specialty retail persists for high-consideration stabilization purchases in Tokyo and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The camera accessories market is recovering from content creator demand compression, with TikTok and YouTube algorithm monetization cycles now driving replacement demand for compact gimbals and lighting kits.
For Market Incumbents: Harden proprietary mount ecosystem control through backward integration into precision machining capacity in Dongguan, defending against modular platform specialists eroding compatibility lock-in. Accelerate nickel-manganese-cobalt battery chemistry partnerships to absorb REACH Annex XVII reformulation costs that threaten low-cost competitors. Channel control through direct-to-consumer platform algorithms now supersedes dealer network investments.
For New Entrants and Emerging Players: Establish a beachhead in India's short-form video production segment, where Mumbai and Bangalore content creators outpace local gimbal and lighting supply. Target aluminum tripod white space with cost-accessible SKUs for hobbyist price sensitivity, bypassing carbon fiber premium tiers dominated by incumbents. Deploy creator affiliate link ecosystems as the primary go-to-market angle, displacing traditional trade show presence.
For Investors and Strategic Acquirers: Modular platform specialists with cross-device mounting architectures spanning cameras, drones, and smartphones represent the most defensible acquisition target archetype against ecosystem fragmentation. Long-term viability hinges on software subscription layering over hardware margins as computational stabilization collapses mechanical differentiation. Watch FCC Part 15 certification timeline compression as the inflection signal for wireless trigger accessory market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Toray supply agreements secure weight-reduction performance for premium tripod tiers. |
| REACH-Compliant Battery Chemistry Partnership | Nickel-manganese-cobalt reformulations maintain EU market access against cadmium restrictions. |
| Platform-Native Algorithm Distribution | YouTube and TikTok affiliate ecosystems compress consideration phases for filter and battery purchases. |
| Modular Mount Architecture Development | Cross-device compatibility spans camera, drone, and smartphone categories for SKU consolidation. |
| Precision Machining Talent Acquisition | Dongguan and Taichung CNC operator pipelines address 0.1 mm tolerance quality scaling constraints. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, and platform algorithm disclosure documents, combining interviews with product managers at direct-to-consumer accessory brands, procurement leads at Shenzhen manufacturing clusters, and cinematography rental house operators. Bottom-up demand modeling from content creator segment sizing and top-down triangulation against camera body shipment data validate volume estimates.
Forecast inputs include product type segmentation across stabilization, power, and light-modification categories; end-user stratification by professional, hobbyist, and videographer archetypes; and material tier differentiation between carbon fiber and aluminum. CAGRs were derived from algorithm-driven purchase velocity indicators and replacement cycle compression patterns across the projection horizon. Industry-specific inputs capture REACH chemistry reformulation timelines and FCC Part 15 certification duration variability.
Stress conditions across lithium raw material price volatility, Shenzhen logistics disruption scenarios, and platform algorithm monetization shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding content creator economy maturation and regulatory chemistry convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
TDI Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
Photoacoustic Tomography Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Photoconductor Drums Market
Imaging
LCD Digital Microscope Market
Imaging
Camera Stabilizer Market
Imaging
Video Capture Card Market
Imaging
Camera Technology Market
Imaging
China Electron Microscopy Market
Imaging
Short-Wave Infrared Imaging Market
Imaging
Facial Recognition Machine Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
SWIR Camera Market
Imaging
X-Ray Systems Market
Imaging
Hyper Spectral Imaging System Market