
 Global Optical Preclinical Imaging Market | 2026-2036
Global Optical Preclinical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Preclinical Imaging Market Foresight
Aftermarket service revenue is tilting from break-fix contracts toward predictive maintenance and remote diagnostics platforms. PerkinElmer Inc. leverages its installed base of IVIS systems to secure multi-year service agreements with academic institutions. Bruker Corporation anchors its position through high-field magnetic resonance integration with optical modules. Revvity, Inc. specializes in reagent-consumable bundles that lock in recurring revenue streams alongside hardware placements.
Optical preclinical imaging deploys visible and near-infrared light to visualize biological processes in living animal models, typically achieving spatial resolutions from micrometers to millimeters depending on wavelength and tissue depth. These systems enable longitudinal tracking of disease progression, therapeutic response, and biomarker expression without sacrificing subjects. Fluorescence imaging dominates current installations due to mature probe availability and standardized protocols, while bioluminescence imaging captures the fastest expansion in oncology applications where luciferase reporter assays prove essential. Software segments increasingly concentrate margin pools as vendors bundle AI-assisted quantification tools that reduce manual analysis hours.
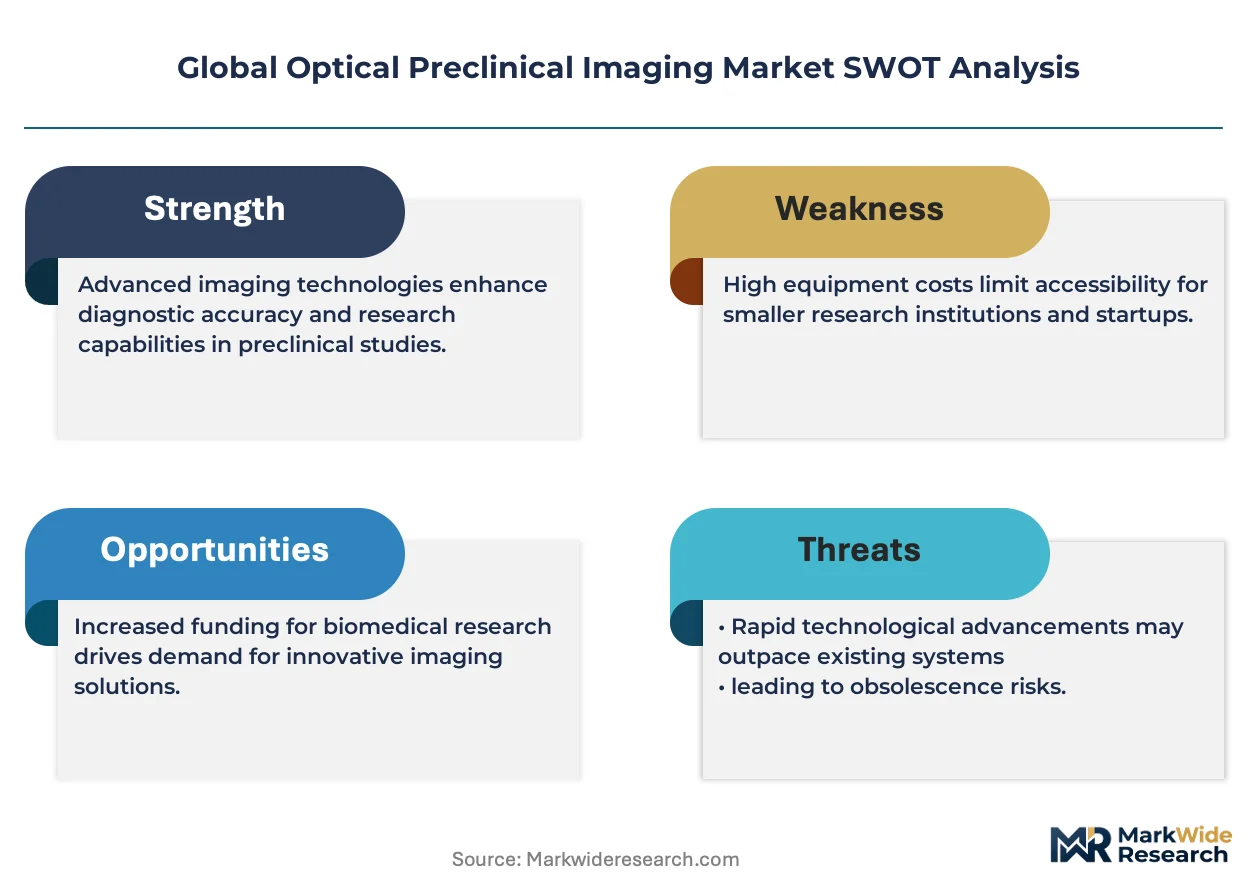
FDA guidelines on Good Laboratory Practice shape validation requirements for imaging data submitted in IND packages, while the EPA oversees fluorescent dye disposal protocols that affect reagent choices. ISO 10993 biocompatibility standards influence imaging agent development pathways for translational programs. Stakeholders must monitor how evolving FDA guidance on 3R principles—replacement, reduction, refinement—reshapes demand for non-invasive longitudinal imaging modalities versus traditional endpoint methods.
Market Dynamics
Pharmaceutical R&D budgets are pivoting toward longitudinal imaging modalities as FDA scrutiny on animal study reproducibility intensifies, compressing demand for traditional endpoint methods and elevating optical preclinical systems from ancillary tools to core infrastructure.
Growth Catalysts
- 3R Principle Adoption:FDA guidance on replacement, reduction, and refinement of animal use is accelerating institutional procurement of non-invasive imaging platforms that enable repeated measurements on single subjects.
- NIH Funding Expansion:Sustained federal research appropriations in the United States are directly translating into instrument acquisitions at academic medical centers and dedicated imaging facilities.
- Luciferase Reporter Standardization:Oncology drug pipelines have normalized bioluminescence imaging as a mandatory efficacy readout, creating pull-through demand for compatible optical systems.
Market Restraints
- Fluorescent Dye Disposal Costs:EPA hazardous waste protocols for near-infrared and visible-light contrast agents impose recurring operational burdens that constrain reagent volume scaling.
- Detector Component Concentration:High-sensitivity CCD and sCMOS sensor supply chains cluster in East Asian manufacturing hubs, exposing procurement to geopolitical friction and lead-time volatility.
- Tissue Penetration Physics:Light scattering and absorption in biological tissue fundamentally limits optical imaging depth to millimeters, restricting applicability in large-animal models without surgical window implantation.
Strategic Opportunities
- AI-Assisted Quantification:Machine learning algorithms for automated tumor segmentation and signal quantification are creating differentiation opportunities in software licensing and bundled service tiers.
- India Contract Research Expansion:CDSCO-aligned preclinical CROs in Hyderabad and Bangalore are building imaging capabilities to serve Western pharmaceutical sponsors seeking cost-efficient IND-enabling studies.
- Multimodal Platform Convergence:Integration of optical modules with MRI and PET systems is opening premium positioning for vendors capable of unified hardware-software architectures.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Facilities struggle to recruit personnel combining optical physics expertise with veterinary surgical protocols and computational image analysis.
- ISO 10993 Validation Timelines:Biocompatibility certification for novel imaging agents extends development cycles and delays revenue recognition for reagent portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Preclinical Imaging Market |
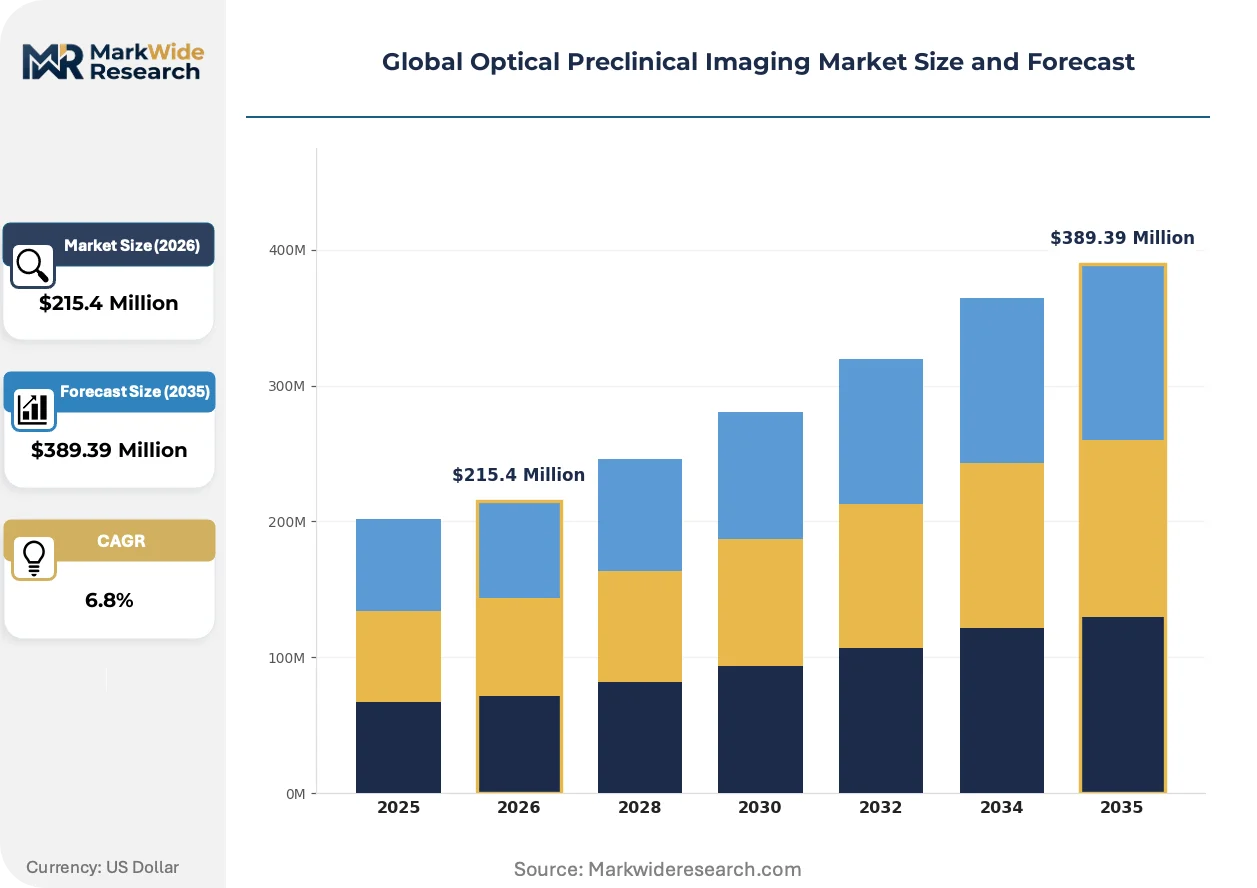
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vivo Imaging Systems, Imaging Agents, Software, Accessories Application: Cancer Research, Cardiology, Neurology, Infectious Diseases End User: Academic Institutions, Pharmaceutical Companies, Research Organizations, Contract Research Organizations Technology: Fluorescence Imaging, Bioluminescence Imaging, Optical Coherence Tomography, Quantum Dots |
| Companies Covered | PerkinElmer Inc., Bruker Corporation, Miltenyi Biotec, Spectral Instruments Imaging, Revvity, Inc., BioTek Instruments, MR Solutions, MILabs B.V., FUJIFILM VisualSonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Preclinical Imaging Market Shifts & Advancements
Optical preclinical imaging is undergoing functional transformation as hardware commoditization pushes value capture toward software-defined workflows and predictive service architectures.
Spectral unmixing algorithms are migrating from post-processing software to real-time embedded systems. Academic core facilities and large pharmaceutical imaging groups are adopting these capabilities to reduce manual analysis hours per study. This compression of analytical labor is reshaping staffing models and enabling higher throughput without proportional headcount expansion.
REACH restrictions on persistent organic pollutants are forcing reformulation of long-circulating fluorescent probes used in oncology studies. European CROs and reagent suppliers are accelerating substitution programs toward biodegradable dye scaffolds. The transition is most acute in Germany and France, where national chemical regulators have advanced implementation timelines ahead of EU baseline requirements.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Academic buyers in the United States are negotiating à-la-carte remote diagnostics and predictive parts replacement separate from break-fix coverage. This disaggregation is compressing realized service revenue per installed system while expanding vendor touchpoints for reagent attachment.
Global Optical Preclinical Imaging Market Segmentation
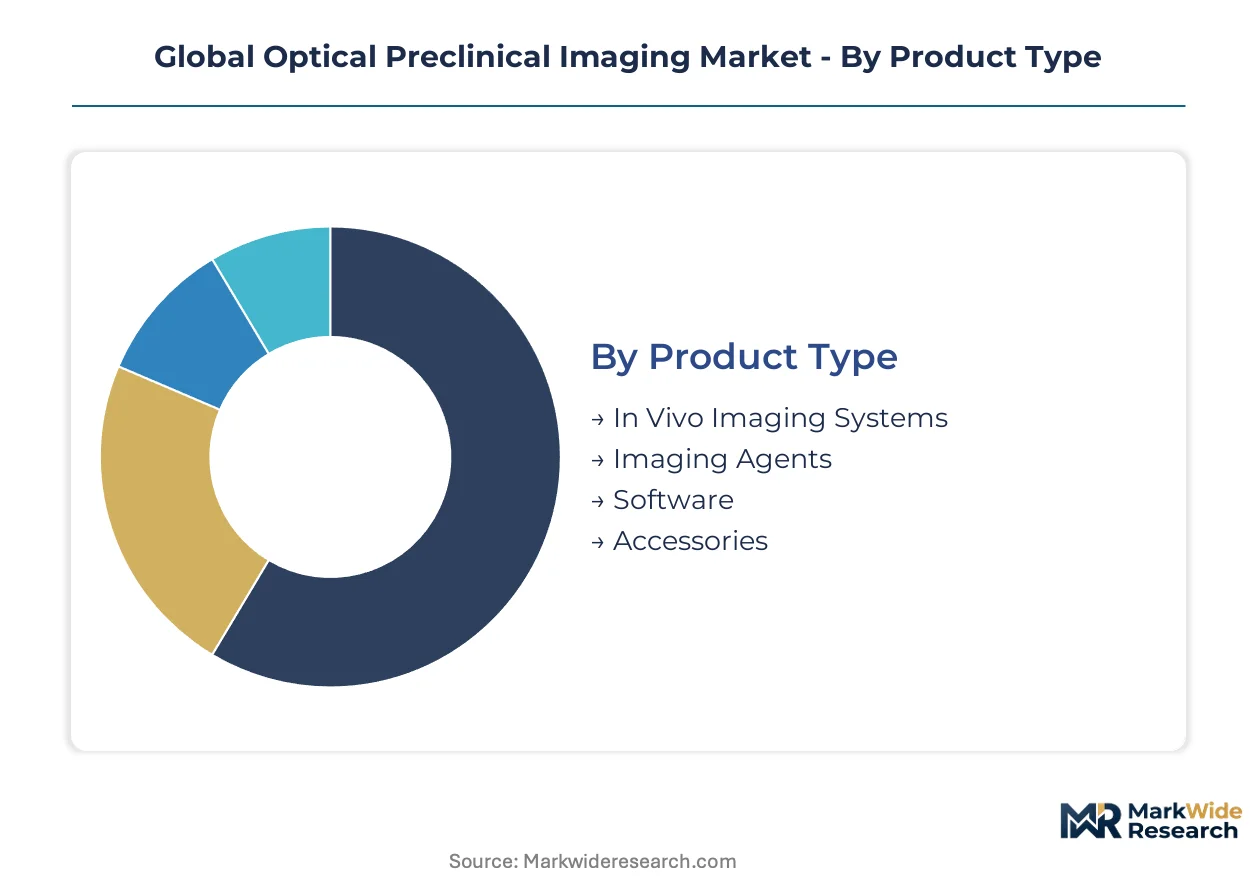
Optical preclinical imaging markets segment across hardware, consumables, and digital layers with starkly different replacement cycles. Understanding velocity differences between capital equipment and recurring revenue streams shapes vendor portfolio strategy and customer lifetime value calculations.
Product Type:
In Vivo Imaging Systems turn over slowest at 7-10 year replacement cycles, while Imaging Agents and Software refresh annually or faster, creating divergent cash flow profiles for suppliers.
- In Vivo Imaging Systems:Integrated hardware platforms combining cooled CCD/sCMOS detectors, light-tight imaging chambers, and gas anesthesia interfaces. Academic medical centers in the United States sustain replacement demand through NIH instrumentation grants, though capital approval timelines extend procurement to 18-24 months.
- Imaging Agents:Fluorescent probes, luciferase substrates, and targeted contrast materials formulated for specific biological pathways. Pharmaceutical companies in Massachusetts and California drive volume through oncology pipeline screening programs, where single studies consume hundreds of vials.
- Software:Image acquisition control, spectral unmixing algorithms, and AI-assisted quantification modules. Demand clusters at core facilities seeking automated tumor segmentation to reduce manual analysis labor.
- Accessories:Anesthesia systems, heating pads, and specialized animal handling fixtures. Replacement purchases track instrument utilization rates rather than technology obsolescence.
In Vivo Imaging Systems dominates installed base. Imaging Agents is where expansion concentrates.
Application:
Cancer Research commands the largest absolute spending, though Neurology applications are climbing the fastest as blood-brain barrier imaging protocols mature.
- Cancer Research:Longitudinal tumor monitoring, metastasis tracking, and therapeutic efficacy assessment in xenograft and syngeneic models. Luciferase reporter standardization at Pfizer, Merck, and Roche facilities has made bioluminescence imaging mandatory for IND-enabling oncology studies.
- Neurology:Neuroinflammation visualization, stem cell migration tracking, and amyloid plaque detection in transgenic mouse models. German Max Planck Institutes and Dutch neuroscience centers are expanding optical imaging cores for Alzheimer's research programs.
- Cardiology:Myocardial infarction modeling, angiogenesis quantification, and stem cell therapy tracking. Applications remain concentrated at specialized cardiovascular research institutes with surgical expertise.
- Infectious Diseases:Bacterial load monitoring, host-pathogen interaction studies, and vaccine efficacy assessment. Pandemic preparedness funding at the NIH and BARDA has expanded imaging infrastructure for infectious disease modeling.
Cancer Research dominates installed base. Neurology is where expansion concentrates.
End User:
Pharmaceutical Companies compress procurement cycles through dedicated imaging facilities, while Academic Institutions fragment purchasing across departmental budgets with longer decision timelines.
- Pharmaceutical Companies:Integrated drug discovery operations with captive preclinical imaging capabilities. Internal imaging groups at Bristol Myers Squibb and Eli Lilly in New Jersey maintain 15-20 systems per site for high-throughput screening.
- Academic Institutions:Shared core facilities serving multiple principal investigators across biology, pharmacology, and engineering departments. NIH S10 Shared Instrumentation Grants fund 60% of U.S. academic system placements.
- Research Organizations:Non-profit disease foundations and government laboratories with targeted research mandates. The Jackson Laboratory and Salk Institute operate specialized imaging cores for distributed collaboration networks.
- Contract Research Organizations:Fee-for-service preclinical testing facilities serving sponsor companies without internal imaging infrastructure. Charles River Laboratories and Crown Bioscience have consolidated optical imaging capabilities at U.S. and China sites to serve global pharmaceutical clients.
Academic Institutions dominates installed base. Pharmaceutical Companies is where expansion concentrates.
Technology:
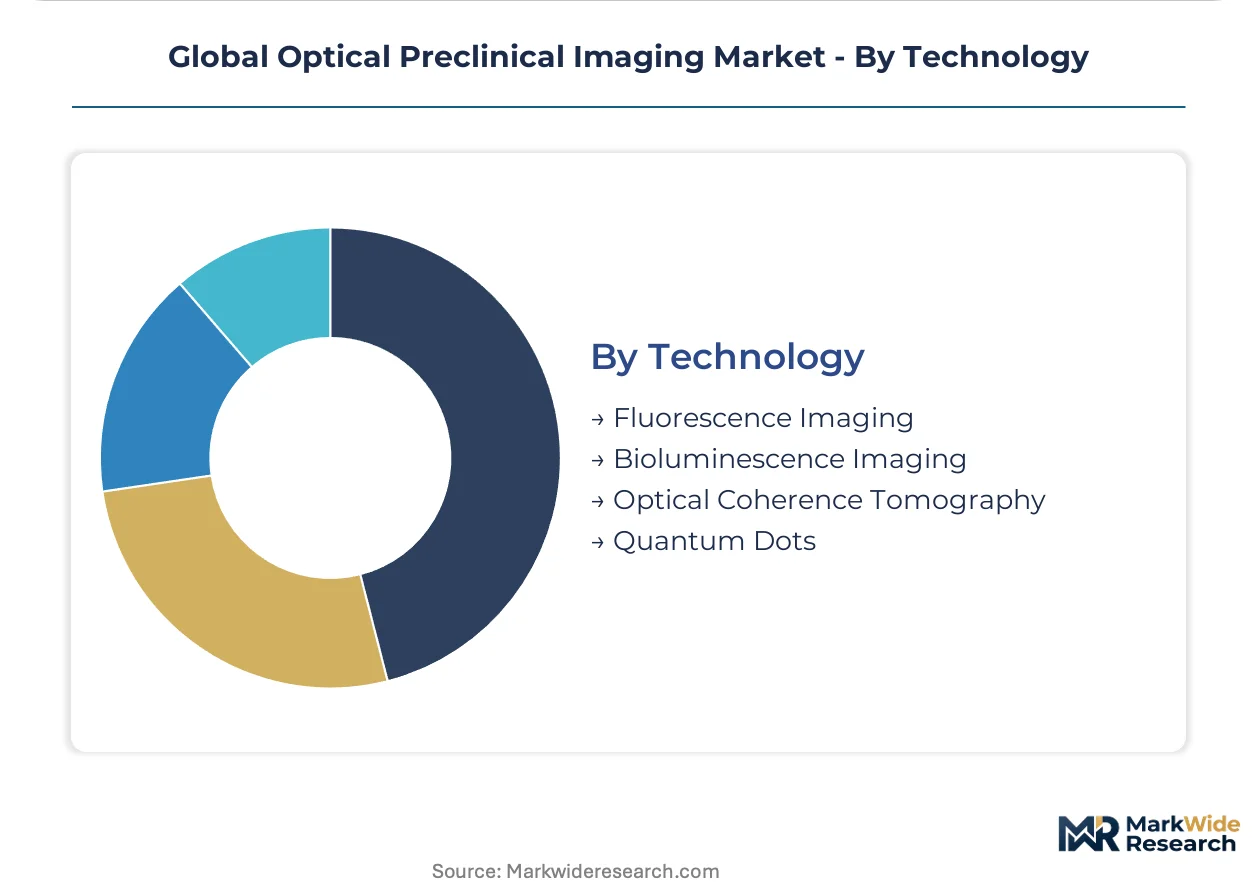
Fluorescence Imaging offers mature probe libraries and standardized protocols, while Bioluminescence Imaging gains share fastest through oncology reporter assay adoption.
- Bioluminescence Imaging:Detection of luciferase-catalyzed light emission in genetically modified cells and pathogens. Deep tissue signal attenuation limits sensitivity, though ATP-dependence provides exquisite specificity for viable cell detection.
- Fluorescence Imaging:Excitation-emission detection of exogenous and endogenous fluorophores across visible and near-infrared spectra. Broad probe availability from Thermo Fisher and PerkinElmer sustains protocol standardization across pharmaceutical and academic labs.
- Optical Coherence Tomography:Interferometric depth-resolved imaging achieving micrometer-scale resolution in transparent and scattering tissues. Ophthalmology and vascular applications dominate, with preclinical adoption tracking clinical translation programs.
- Quantum Dots:Semiconductor nanocrystal probes with tunable emission spectra and photostability exceeding organic dyes. Toxicity concerns and REACH regulatory scrutiny in Europe have constrained commercial deployment despite superior optical properties.
Fluorescence Imaging dominates installed base. Bioluminescence Imaging is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic buyers in the United States demonstrate the lowest price elasticity, absorbing premium instrument costs through NIH instrumentation grants, while Indian CRO procurement exhibits acute sensitivity to capital outlay and per-scan service pricing.
United States
NIH S10 Shared Instrumentation Grants fund sixty percent of academic system placements, with Massachusetts General Hospital and Stanford University maintaining multi-system imaging cores. FDA Good Laboratory Practice validation requirements for IND-enabling studies compress procurement timelines at pharmaceutical sponsors. The Boston-Cambridge corridor clusters the highest density of preclinical CRO capacity, with Charles River Laboratories and Crown Bioscience operating dedicated optical imaging facilities for oncology pipeline screening.
Germany
Max Planck Institutes and Helmholtz Centers sustain instrument demand through federal research framework programs, with Munich and Heidelberg hosting specialized neuroscience imaging cores. REACH restrictions on persistent organic pollutants are accelerating fluorescent probe reformulation toward biodegradable scaffolds ahead of EU baseline timelines. The Baden-Württemberg region concentrates reagent manufacturing capabilities, with Merck KGaA and specialized dye suppliers advancing substitution programs for long-circulating oncology probes.
China
CDSCO-aligned preclinical CROs in Suzhou and Shanghai are building imaging capabilities to serve Western pharmaceutical sponsors seeking cost-efficient IND-enabling studies. NMPA guidance on animal study data quality is tightening validation requirements for imaging submissions in domestic drug applications. The Yangtze River Delta biocluster anchors domestic instrument demand, with Wuxi AppTec and ChemPartner expanding captive optical imaging infrastructure for distributed sponsor networks.
India
CDSCO preclinical CROs in Hyderabad and Bangalore are consolidating optical imaging capabilities to capture Western pharmaceutical outsourcing flows. The country's national pharmaceutical regulator has advanced data integrity requirements for imaging endpoints in generic drug development. Genome Valley in Telangana and the Biotech Park in Lucknow host emerging imaging service providers competing on per-study pricing against Chinese and Southeast Asian alternatives.
United Kingdom
Medical Research Council facility grants sustain core imaging infrastructure at Oxford, Cambridge, and Imperial College London, with Francis Crick Institute operating centralized preclinical platforms. The Medicines and Healthcare products Regulatory Agency enforces GLP compliance for imaging data in clinical trial applications. The Oxford-Cambridge-London golden triangle concentrates pharmaceutical R&D imaging demand, with AstraZeneca and GlaxoSmithKline maintaining captive optical systems for oncology and infectious disease programs.
Global Optical Preclinical Imaging Market Competitive Landscape
Capability concentration sits with integrated life science conglomerates possessing multi-modal platform architectures; scale advantage sits with specialized preclinical imaging vendors optimizing single-technology throughput. The vendor base stratifies across three tiers: diversified analytical instrumentation groups, dedicated molecular imaging specialists, and emerging contract research service providers bundling imaging with study execution. Dominant competitive moves include multimodal platform convergence through hardware-software integration and predictive service contract unbundling to capture recurring revenue alongside capital placements.
Within the integrated instrumentation tier, PerkinElmer Inc. and Bruker Corporation exemplify divergent strategic positioning. PerkinElmer leverages its installed base of IVIS systems to secure multi-year service agreements with academic institutions, anchoring recurring revenue through reagent-consumable bundles. Bruker Corporation occupies a position emphasizing high-field magnetic resonance integration with optical modules, targeting pharmaceutical sponsors requiring unified multimodal workflows. Revvity, Inc. sits within the specialized tier, representing reagent-centric models that lock in recurring revenue streams alongside hardware placements through targeted probe portfolios.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Bruker Corporation |
| Miltenyi Biotec |
| Spectral Instruments Imaging |
| Revvity, Inc. |
| BioTek Instruments |
| MR Solutions |
| MILabs B.V. |
| FUJIFILM VisualSonics |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors connecting East Asian sensor manufacturing hubs to United States pharmaceutical clusters impose cost volatility that amplifies price differentiation between premium multimodal systems and standard optical-only configurations, while EPA hazardous waste protocols for fluorescent reagents add compliance premiums that concentrate procurement power among large-scale academic buyers with grant-funded absorption capacity.
Pricing Analysis
Long-term service-of-take agreements dominate capital equipment procurement, with pharmaceutical sponsors locking in multi-year maintenance bundles alongside hardware placements. Price differentiation hinges on ISO 10993 certification tier for imaging agents and after-sales service depth for instrument platforms. Cost compression in standard fluorescence systems intensifies as Chinese manufacturers enter the mid-market segment. Academic institutions demonstrate lowest price sensitivity due to NIH instrumentation grant coverage, while Indian CROs exhibit acute capital outlay sensitivity.
Supply Chain Analysis
Export control regimes restricting high-sensitivity CCD and sCMOS detector technology limit component flows from Japan and the United States to Chinese system integrators. Manufacturing concentration in Taiwan, South Korea, and Japan for cooled detectors and German precision optics for light-tight chambers creates geographic dependencies. Single-source vulnerability for deep-cooled sensor arrays exposes procurement to lead-time volatility. Distribution runs through authorized dealer networks serving academic core facilities and direct enterprise sales for pharmaceutical captive imaging groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as vendors compete through interoperable software ecosystems rather than isolated hardware specifications, with AI-assisted quantification modules creating switching costs that lock in recurring revenue streams across multimodal imaging workflows.
For Market Incumbents: Pre-empt displacement by specialized reagent suppliers through backward integration into biodegradable fluorescent probe manufacturing ahead of REACH implementation timelines. Anchor installed base defense through predictive maintenance platforms that reduce customer analytical labor hours. Prioritize certification investment for ISO 10993 imaging agent portfolios to accelerate regulatory validation timelines.
For New Entrants and Emerging Players: Build out AI-native software layers that automate tumor segmentation and signal quantification for core facilities burdened by manual analysis bottlenecks. Target neurology applications in German Max Planck Institutes and Dutch neuroscience centers where blood-brain barrier imaging protocols are maturing fastest. Deploy cloud-based subscription pricing to bypass capital approval barriers at fragmented academic departments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrumentation conglomerates seeking to divest non-core preclinical imaging divisions amid portfolio rationalization pressures. Long-term viability centers on recurring revenue attachment rates rather than hardware shipment volumes. Watch for FDA guidance evolution on 3R principles as the signal indicating accelerated replacement demand for longitudinal imaging platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Quantification Platform Launch | PerkinElmer and Bruker compete through automated tumor segmentation reducing manual analysis labor at academic core facilities. |
| Biodegradable Probe Reformulation Program | Merck KGaA advances substitution timelines ahead of REACH baseline requirements in Germany and France. |
| Multimodal Hardware-Software Integration | Bruker anchors pharmaceutical sponsor loyalty through unified MRI-optical workflows for IND-enabling studies. |
| Remote Diagnostics Service Unbundling | Academic buyers negotiate à-la-carte predictive maintenance separate from break-fix coverage, compressing realized service revenue. |
| India CRO Imaging Capability Buildout | CDSCO-aligned facilities in Hyderabad capture Western pharmaceutical outsourcing flows through per-study pricing advantages. |
Research Methodology
Cross-validation between primary interviews with preclinical imaging core directors, pharmaceutical R&D executives, and regulatory affairs specialists and secondary sources including FDA IND filing databases, NIH instrumentation grant records, and ECHA REACH substance registrations anchors the qualitative findings. Bottom-up triangulation against top-down market sizing ensures segmentation integrity across hardware, consumables, and software layers.
Calibration against historical replacement cycles for cooled CCD systems and annual refresh rates for imaging agents and AI quantification modules shapes the analytical framework across the projection horizon. Segmentation dimensions span technology type, application area, end-user category, and regional regulatory cluster. CAGRs derive from instrument placement velocity, reagent consumption intensity, and software attachment rate trajectories.
Stress conditions across NIH funding appropriation levels, EPA hazardous waste protocol enforcement intensity, and East Asian sensor supply chain disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in FDA 3R principle guidance or REACH persistent organic pollutant restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Pathology Imaging Systems Market
Imaging
Chemiluminescence Imaging Market
Imaging
Global Thermal Imager Market
Imaging
Infrared Imaging Software Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Digitizer Market
Imaging
Machine Vision System and Services Market
Imaging
Global Mobile Image Sensor Market
Imaging
Camera Technology Market
Imaging
Digital Camera Market
Imaging
Event Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Computational Photography Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Europe Machine Vision Systems Market