
 Ship/Boat Keel Market | 2026-2036
Ship/Boat Keel Market Size, Share, and Industry Trends Forecast 2026-2036
Ship/Boat Keel Market Analytics
Asian shipyard consolidation is realigning global keel fabrication capacity toward integrated marine complexes. Hyundai Heavy Industries leverages captive steel-forging facilities to control bilge keel production for very large crude carriers. Samsung Heavy Industries anchors its keel operations within the Geoje yard, sustaining throughput for LNG carrier newbuilds. Mitsubishi Heavy Industries competes through precision casting of complex bulb keel profiles for naval contracts.
A ship or boat keel constitutes the primary longitudinal structural member at the hull's lowest point, typically fabricated from high-tensile steel plate exceeding 50 millimeters thickness through segmented welding and post-weld heat treatment to achieve specified Charpy impact values. The keel distributes hydrodynamic loads, provides ballast integration points, and establishes the vessel's directional stability backbone. Steel dominates material selection for commercial and naval keels due to fatigue resistance under cyclic loading, while fiberglass occupies sailing yacht segments where weight reduction governs performance. Application demand concentrates in cargo ships and naval vessels where classification society scantling rules mandate substantial keel sectional modulus, whereas yacht and sailboat builders prioritize hydrodynamic efficiency through bulb and wing keel geometries.
Lloyd's Register, DNV, and the International Maritime Organization shape keel design through structural rules, fatigue assessment protocols, and hull integrity standards that govern newbuild certification. Lloyd's Register's Rules for Ships specifies minimum keel section modulus calculations tied to vessel length and service notation, while DNV's ship classification directives mandate non-destructive testing of keel weld seams. Stakeholders must monitor evolving emission-linked hull efficiency regulations that will recalibrate keel optimization priorities toward drag reduction and auxiliary fuel savings.
Market Dynamics
Naval defense procurement cycles and classification society welding mandates are compressing keel fabrication timelines while concentrating supply among integrated steel-forging shipyards with captive heat-treatment capacity.
Growth Catalysts
- IMO Hull Integrity Standards:The International Maritime Organization's revised hull girder strength requirements are mandating thicker keel scantlings for tankers and bulk carriers, expanding material demand per vessel.
- South Korean Naval Expansion:The Republic of Korea Navy's KSS-III submarine program and FFX-III frigate procurement are generating sustained orders for specialized bulb keel castings at Ulsan and Geoje yards.
- High-Tensile Steel Advances:EH40 and FH40 grade plate adoption is reducing keel sectional area requirements while maintaining fatigue resistance under cyclic loading.
Market Restraints
- Scrap Steel Volatility:Electric arc furnace feedstock costs for ship-grade plate production fluctuate with Turkish and Vietnamese scrap import demand, compressing mill margins.
- Ulsan Cluster Concentration:Over 60 percent of commercial keel welding capacity sits within 50 kilometers of Hyundai Heavy Industries' integrated complex, creating single-point vulnerability.
- Fiberglass Substitution:Advanced epoxy-infused carbon fiber keel structures are displacing steel in performance sailing yacht segments above 30 meters length.
Strategic Opportunities
- Indian Navy Indigenization:The Ministry of Defence's Strategic Partnership model for P-75I submarines and Next Generation Missile Vessels mandates domestic keel fabrication at Mazagon Dock and Garden Reach.
- EU Green Deal Hull Efficiency:The European Union's FuelEU Maritime regulations are incentivizing bulb keel optimization for drag reduction and auxiliary fuel savings on intra-EU routes.
- Hybrid Propulsion Integration:Convergence of battery-electric propulsion and computational fluid dynamics is enabling active keel-fin stabilization systems for cruise and ferry operators.
Industry Challenges
- Certified Welder Scarcity:Lloyd's Register and DNV qualification requirements for thick-plate submerged arc welding exceed training pipeline output at Korean and Japanese maritime institutes.
- Post-Weld Heat Treatment Bottlenecks:Furnace capacity constraints at integrated forging facilities are extending delivery timelines for complex bulb keel profiles beyond 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship/Boat Keel Market |
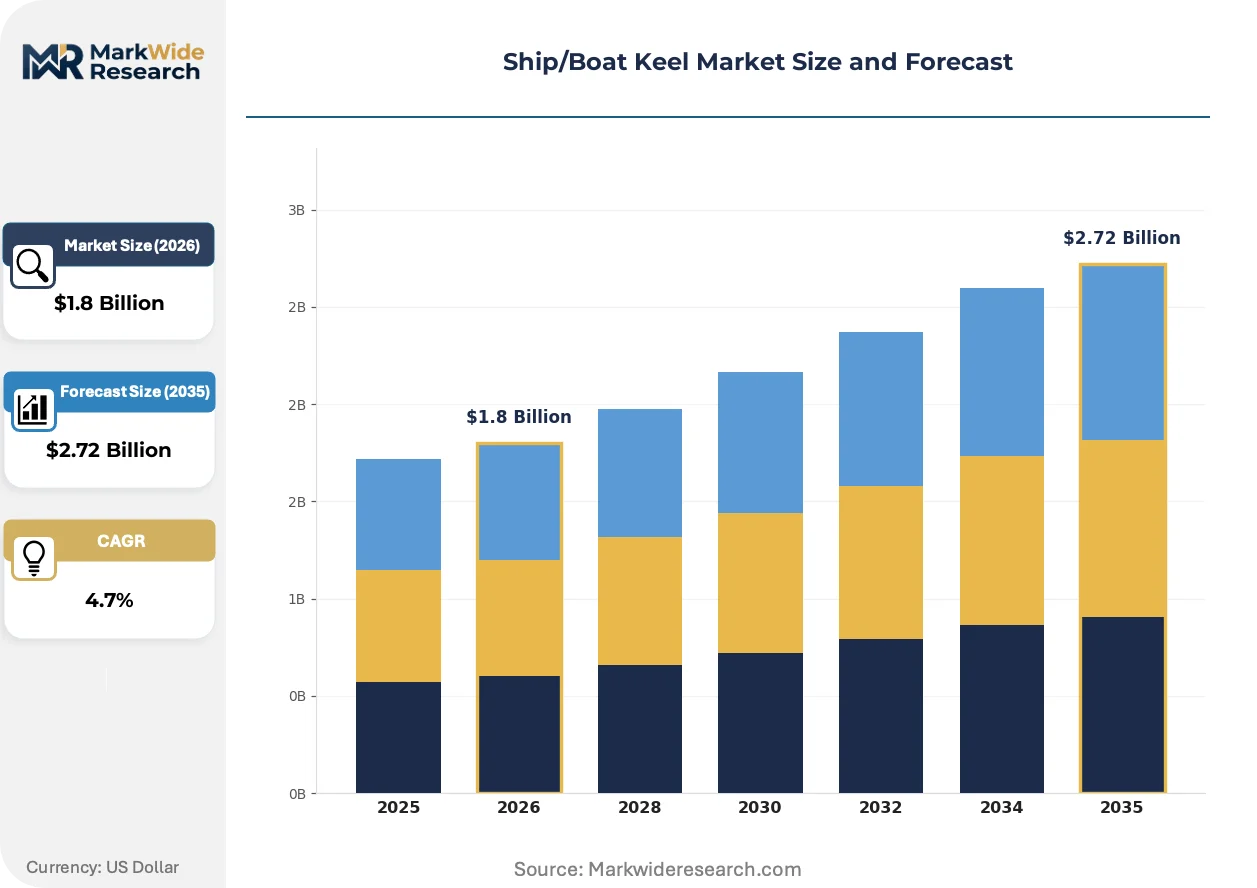
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Full Keel, Fin Keel, Bulb Keel, Wing Keel Material: Fiberglass, Aluminum, Steel, Wood Application: Yachts, Sailboats, Fishing Vessels, Cargo Ships Size: Large, Medium, Small, Mini |
| Companies Covered | Hyundai Heavy Industries, Samsung Heavy Industries, Mitsubishi Heavy Industries, Fincantieri, Damen Shipyards Group, Huntington Ingalls Industries, BAE Systems, Kawasaki Heavy Industries, Naval Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship/Boat Keel Market Evolving Landscape
Computational hull optimization and additive manufacturing are converging to reshape keel design workflows, while regulatory pressure on lifecycle emissions is recalibrating material selection criteria toward energy efficiency.
Additive manufacturing of nickel-aluminum-bronze keel bushings and bearing housings is absorbing prototyping lead times for custom naval geometries. Classification societies are granting equivalence certificates for wire-arc directed energy deposition at Lloyd's Register-approved facilities in Norway and Singapore. This technology is absorbing the market for one-off casting patterns in submarine and research vessel applications.
The European Union's FuelEU Maritime regulation imposes lifecycle greenhouse gas intensity limits on vessels calling at EU ports. Shipowners are responding by optimizing bulb keel profiles for reduced drag coefficients on container and cruise segments. DNV's new class notation for hull and propeller efficiency is accelerating adoption of computational fluid dynamics-validated keel designs among German and Italian yards.
Buyer consolidation among container line alliances is compressing newbuild specification cycles and unbundling keel fabrication from full-hull construction contracts. Independent keel specialists in Poland and Croatia are securing direct orders from MSC and CMA CGM procurement teams, bypassing traditional yard intermediaries. This disintermediation is most visible in the Mediterranean feeder vessel segment where specification standardization enables modular sourcing.
Ship/Boat Keel Market Segmentation
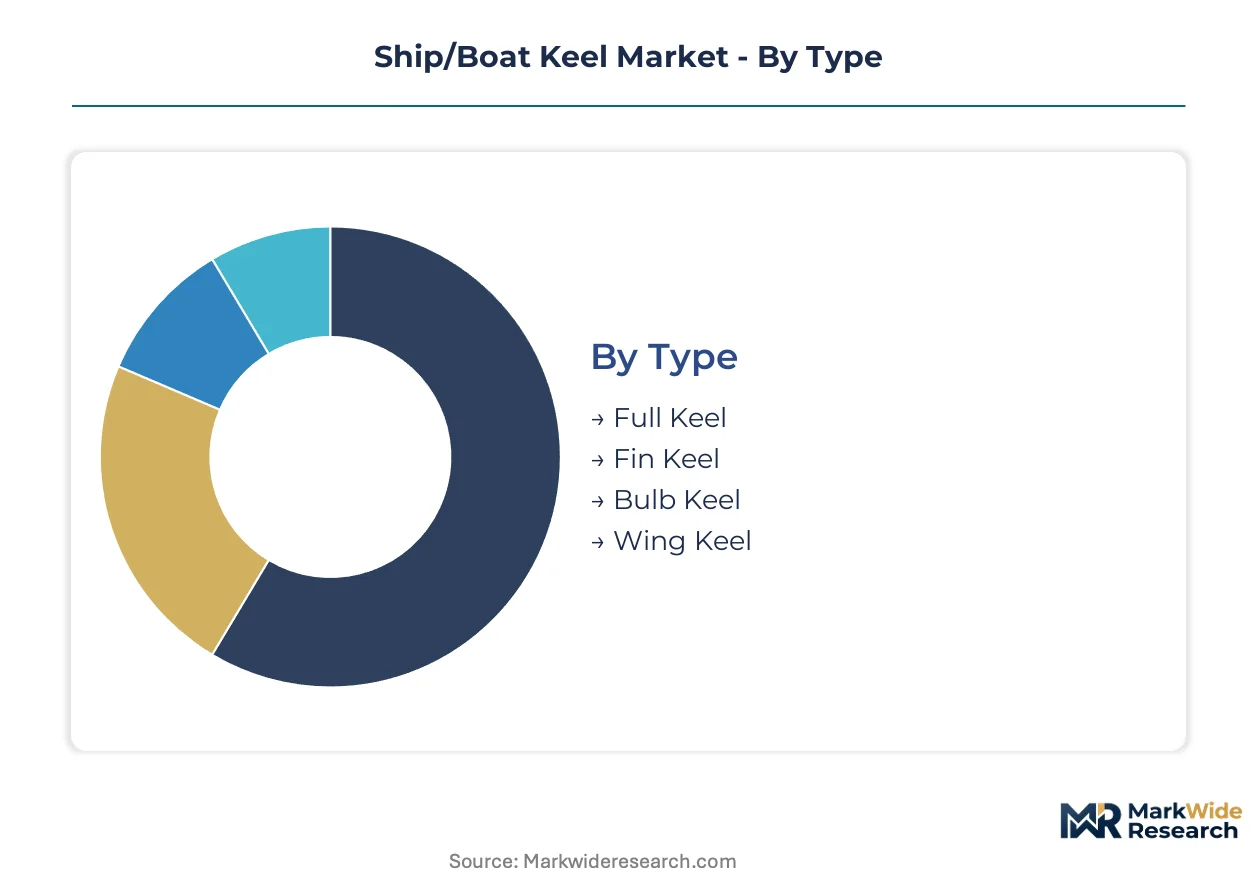
Keel segmentation reflects divergent certification burdens across naval, commercial, and recreational maritime sectors. Classification society rules from Lloyd's Register and DNV impose distinct structural requirements that reshape material selection and fabrication complexity for each segment.
Type:
Lloyd's Register and DNV apply differentiated scantling calculations and weld inspection protocols across keel geometries, with bulb and full keels facing the most intensive certification regimes for naval and commercial contracts.
- Full Keel:Continuous longitudinal structure running the hull's full length, fabricated from thick steel plate segments with post-weld heat treatment. Demand concentrates in naval frigate and submarine programs at South Korea's Ulsan cluster, where Hyundai Heavy Industries maintains captive forging capacity for integrated hull-keel construction.
- Bulb Keel:Streamlined cast-steel or fabricated bulb profile optimized for hydrodynamic efficiency and ballast concentration. Mitsubishi Heavy Industries dominates precision casting for Japanese naval contracts, while Samsung Heavy Industries anchors bulb production for LNG carriers at Geoje.
- Fin Keel:Separated high-aspect foil structure bolted to hull bottom, common in performance sailing yachts. Advanced epoxy-infused carbon fiber variants are displacing steel above 30 meters length.
- Wing Keel:Shallow-draft twin-foil geometry enabling reduced depth without stability sacrifice. Popular in Mediterranean and Caribbean charter fleets where marina access constraints govern design.
Leading the category by volume: Full Keel. Growing fastest: Bulb Keel.
Material:
Material selection pivots on the fatigue-cycle requirements of classification society notations, with high-tensile steel grades commanding premium certification scrutiny.
- Steel:EH40 and FH40 grade plate dominates commercial and naval applications, with Charpy impact testing mandated by DNV for Arctic service notations. Hyundai Heavy Industries controls bilge keel production through captive steel-forging facilities.
- Fiberglass:E-glass and carbon fiber epoxy laminates serve sailing yacht segments where weight reduction governs performance. Vacuum-infused construction at Italian and French yards achieves complex foil geometries.
- Aluminum:5083-H321 marine alloy deployed in high-speed ferries and patrol craft where magnetic signature reduction or corrosion resistance priorities override steel economics.
- Wood:Traditional timber construction persists in classic yacht restoration and heritage replica builds, with Lloyd's Register maintaining specific scantling rules for wooden hull-keel integration.
Steel commands the greatest absolute tonnage. Fiberglass gains share fastest in recreational segments above 24 meters.
Application:
End-use segmentation determines whether IMO hull integrity standards or recreational craft directives govern design priorities.
- Cargo Ships:Tankers and bulk carriers face IMO-mandated thicker keel scantlings under revised hull girder strength requirements. South Korean yards concentrate newbuild contracts for very large crude carriers.
- Yachts:Superyacht builders above 60 meters prioritize computational fluid dynamics-validated bulb profiles for drag reduction, with German and Italian yards leading DNV efficiency notation adoption.
- Sailboats:Performance cruising and racing segments drive carbon fiber keel-fin development, with epoxy-infused structures displacing steel in 30-meter-plus performance cruisers.
- Fishing Vessels:Steel full keels with ice-class reinforcement predominate in North Atlantic and North Pacific trawler fleets, with classification society ice notations driving material specification.
Cargo ships generate the largest material offtake. Yachts show the steepest expansion trajectory in value terms.
Size:
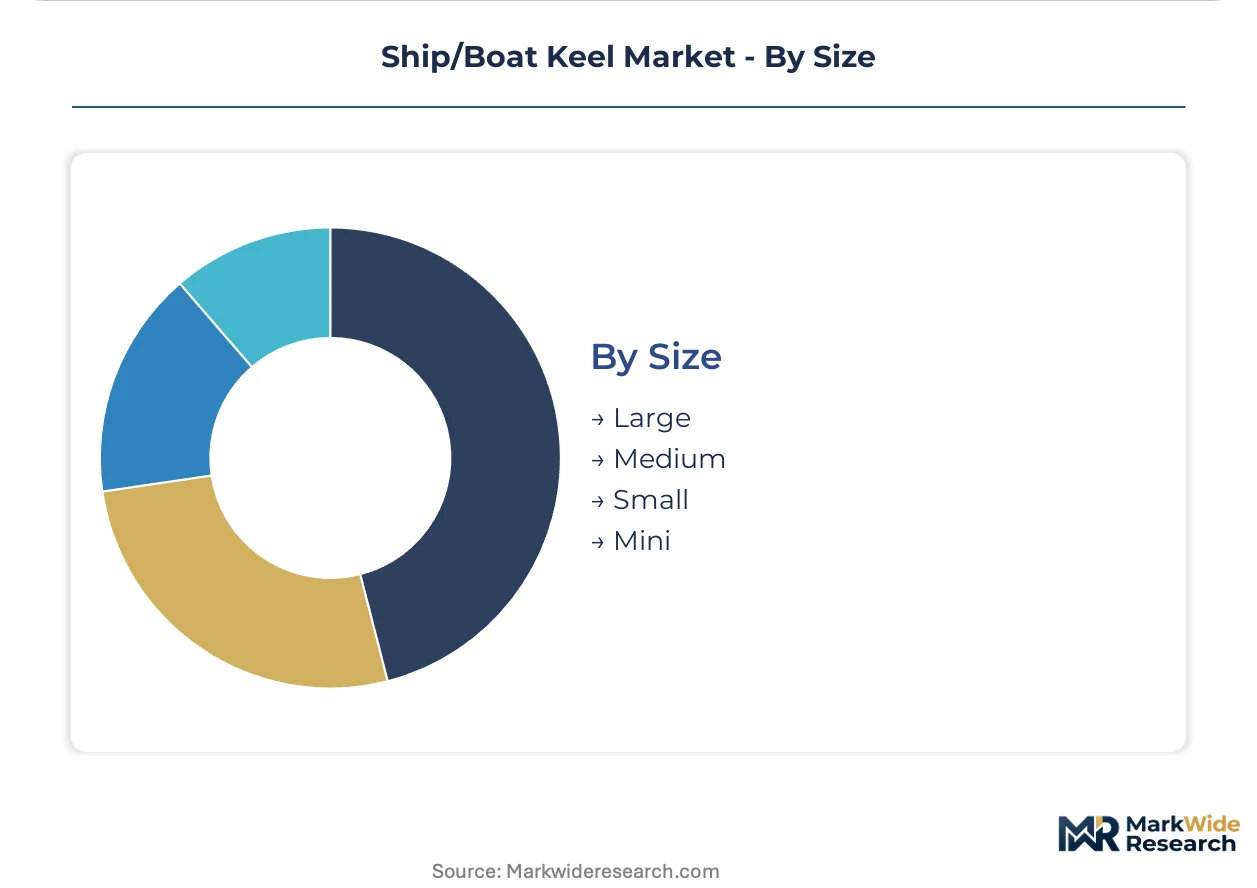
Size tiering correlates with fabrication method and supply chain access, with large keels requiring integrated forging facilities unavailable to smaller specialists.
- Large:Exceeding 50 meters in length for ultra-large crude carriers and naval vessels. Production concentrates at Hyundai Heavy Industries' Ulsan complex and Samsung Heavy Industries' Geoje yard with captive heat-treatment furnaces.
- Medium:20-50 meter range covering feeder container vessels and offshore support craft. Polish and Croatian independent specialists are securing direct orders from MSC and CMA CGM procurement teams.
- Small:10-20 meter segment for coastal cargo and fishing vessels. Modular sourcing enables Mediterranean and Southeast Asian yard competition.
- Mini:Below 10 meters for recreational sailing craft and small commercial boats. Fiberglass and aluminum dominate with standardized mold-based production.
Large keels absorb the majority of high-tensile steel tonnage. Medium keels are climbing the fastest as independent specialists disintermediate traditional yard channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-tensile steel plate from South Korean blast furnaces and Japanese integrated mills anchors keel fabrication capacity across East Asian maritime clusters, with specialized forging facilities concentrating near major shipbuilding complexes.
South Korea
The Republic of Korea Navy's KSS-III submarine program and FFX-III frigate procurement drive specialized bulb keel demand. Lloyd's Register and DNV classification rules govern thick-plate welding certification for naval contracts. Hyundai Heavy Industries controls bilge keel production through captive steel-forging facilities at its Ulsan complex, while Samsung Heavy Industries anchors bulb operations at Geoje for LNG carrier newbuilds.
Japan
Precision casting capabilities for complex naval geometries distinguish Japanese keel fabrication. METI industrial policy supports maritime defense supply chain resilience through designated critical component programs. Mitsubishi Heavy Industries competes through advanced bulb keel profiles at its Nagoya-area facilities, serving Japan Maritime Self-Defense Force contracts under strict JIS standards.
China
State-owned shipyard consolidation under CSSC and CSIC is redirecting keel capacity toward naval and commercial dual-use production. MIIT shipbuilding industry guidelines emphasize domestic steel grade qualification for hull structural components. Shanghai and Dalian maritime clusters are expanding heat-treatment furnace capacity to reduce dependency on imported EH40 and FH40 plate certification.
United States
Navy Virginia-class and Columbia-class submarine programs sustain demand for specialized keel castings at Ingalls and Electric Boat facilities. Jones Act requirements preserve domestic hull construction for commercial vessels, with keel fabrication governed by American Bureau of Shipping rules. Newport News and Groton shipyard clusters maintain captive forging partnerships for critical naval components.
India
The Ministry of Defence's Strategic Partnership model for P-75I submarines and Next Generation Missile Vessels mandates domestic keel fabrication. BIS steel grade certification and Indian Register of Shipping hull rules apply to indigenous construction. Mazagon Dock and Garden Reach Shipbuilders in Mumbai and Kolkata are developing thick-plate welding capacity under technology transfer arrangements.
Ship/Boat Keel Market Competitive Landscape
Global majors compete with regional champions across integrated fabrication capacity and classification society certification reach. The market structure concentrates among tier-one shipbuilders with captive steel-forging and heat-treatment infrastructure, while tier-two specialists in Mediterranean and Baltic states compete on modular sourcing flexibility. Three archetypes dominate: integrated Korean-Japanese conglomerates with full vertical control; European naval specialists with state-backed defense pipelines; and emerging Indian state-owned yards building indigenous capability. Competitive moves center on M&A consolidation of forging assets and strategic partnerships for classification society equivalence certification.
Among integrated Korean conglomerates, Hyundai Heavy Industries and Samsung Heavy Industries exemplify the scale-driven archetype through Ulsan and Geoje complex dominance. Mitsubishi Heavy Industries occupies a parallel position in Japanese precision casting for naval bulb profiles. European naval specialists include Fincantieri and Naval Group, representing state-backed defense pipeline models with concentrated Mediterranean and Atlantic facility networks.
| Leading Market Players |
|---|
| Hyundai Heavy Industries |
| Samsung Heavy Industries |
| Mitsubishi Heavy Industries |
| Fincantieri |
| Damen Shipyards Group |
| Huntington Ingalls Industries |
| BAE Systems |
| Kawasaki Heavy Industries |
| Naval Group |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between Lloyd's Register-approved naval keels and commercial classification tiers manifests in both pricing premiums and supply chain concentration around captive heat-treatment facilities. EH40-grade plate procurement for Arctic service notations commands substantial weld-inspection add-ons, while standard commercial keels flow through modular Polish and Croatian specialists with unbundled service terms.
Pricing Analysis
Warranty bundling separates premium naval contracts from commercial segments, with Lloyd's Register and DNV weld-certification packages included in Korean yard pricing but unbundled at Mediterranean independents. Project-based contracting dominates large keel fabrication, with price differentiation driven by Charpy impact testing tiers and geographic delivery costs. Pricing pressure stems from scrap steel volatility compressing mill margins, while cargo ship operators show greatest price sensitivity versus naval procurement teams prioritizing certification reliability.
Supply Chain Analysis
Reverse-logistics flows for keel refurbishment remain minimal given structural weld replacement economics, though nickel-aluminum-bronze bearing housings see additive remanufacturing at Norwegian and Singaporean facilities. Supply concentrates in South Korea, Japan, and China, with EH40-grade plate and high-tensile forging feedstock anchoring raw material dependencies. Single-source vulnerability runs through the Ulsan cluster's heat-treatment furnace capacity. Distribution runs through integrated shipyard complexes for large keels and direct procurement channels for medium-segment modular sourcing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics-validated bulb profiles are displacing legacy rule-based scantling designs, recalibrating competitive advantage toward simulation-capable yards.
For Market Incumbents: Deepen captive forging capacity at Ulsan and Geoje complexes to offset certified welder scarcity threatening delivery timelines. Secure Lloyd's Register equivalence certification for wire-arc directed energy deposition before additive specialists capture naval prototyping markets. Lock in long-term EH40 plate offtake agreements with POSCO and Nippon Steel to insulate against scrap volatility. For New Entrants and Emerging Players: Additive manufacturing of custom naval bearing housings offers technology-first entry into submarine and research vessel niches bypassing heavy forging investments. Target Indian Navy indigenization contracts at Mazagon Dock and Garden Reach where technology transfer arrangements lower incumbent barriers. Lead with DNV efficiency notation consulting for European superyacht builders seeking FuelEU Maritime compliance. For Investors and Strategic Acquirers: Re-rating potential sits with European naval specialists possessing state-backed defense pipelines and Mediterranean facility networks given EU Green Deal hull efficiency mandates. Long-term viability favors yards with integrated heat-treatment capacity and classification society equivalence certification spanning Lloyd's Register and DNV rules. Monitor Indian Register of Shipping domestic certification milestones as inflection signals for indigenous fabrication scale-up.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | Reduces delivery timelines for complex bulb keel profiles at integrated Korean complexes. |
| Additive Manufacturing Certification | Enables Lloyd's Register equivalence for wire-arc deposition at Norwegian and Singaporean facilities. |
| Indian Defense Partnership Model | Opens domestic fabrication mandates for P-75I submarines at Mazagon Dock under technology transfer. |
| Computational Fluid Dynamics Validation | Secures DNV hull efficiency notation adoption among German and Italian superyacht builders. |
| Long-Term Steel Plate Offtake Agreement | Insulates mill margins against Turkish and Vietnamese scrap import demand volatility. |
Research Methodology
Document review covered Lloyd's Register Rules for Ships, DNV classification directives, and IMO hull integrity standards, complemented by interviews with shipyard procurement directors, naval program managers at Republic of Korea Navy and Japan Maritime Self-Defense Force, classification society surveyors, and EH40-grade plate metallurgists at POSCO and Nippon Steel. Secondary validation drew from customs trade data, Korean Shipbuilders' Association production statistics, and Ministry of Defence tender disclosures. Bottom-up vessel-order aggregation and top-down steel consumption estimates were triangulated across analysis approaches.
Historical keel installation rates were cross-referenced against panel input from shipyard planning officers and naval architect consultants to anchor projection assumptions across the analysis window. Segmentation modeling covered keel type, material grade, application sector, and vessel size tier, with CAGRs derived from regression against naval procurement cycles and commercial orderbook pipelines. Forecast inputs incorporated classification society rule revision timelines and FuelEU Maritime implementation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Korean naval budget reallocation or Lloyd's Register weld-certification requirement changes. Forecasts reflect documented assumptions regarding South Korean cluster capacity utilization and Indian indigenization timeline adherence. Practitioners should monitor Indian Register of Shipping domestic certification progress and EU Green Deal hull efficiency enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fender Market
Marine
Offshore AUV and ROV Market
Marine
Ballast Water Management Market
Marine
Pneumatic Marine Fender Market
Marine
Electric Ship Market
Marine
Buoys and Beacon Market
Marine
GCC ROV Market
Marine
Boat Hook Market
Marine
Marine VFD Market
Marine
Mooring Ropes Market
Marine
Marine Pipes Market
Marine
Jack-Up Vessels Market
Marine
Marine Communication Market
Marine
Marine Asset Integrity Services Market
Marine
Digital Nautical Charts Market
Marine
Marine Gas Oil Market