
 Mooring Ropes Market | 2026-2036
Mooring Ropes Market Size, Share, and Industry Trends Forecast 2026-2036
Mooring Ropes Market Analysis
High-modulus polyethylene (HMPE) is broadening its addressable scope in heavy-lift offshore applications as vessel operators replace wire rope assemblies to cut deck weight and handling crew requirements. Samson Rope Technologies leverages proprietary braid architecture to secure long-term supply contracts with North Sea offshore energy contractors. Teufelberger Holding AG anchors its position through backward integration into synthetic fiber extrusion, capturing margin pools that competitors forfeit to third-party suppliers. Katradis Marine Ropes Industry S.A. specializes in polyester-nylon hybrid constructions purpose-built for Mediterranean port authorities with high UV-exposure profiles.
Mooring ropes are load-bearing tensile members, typically braided or twisted from synthetic fibers such as polypropylene, polyester, or HMPE, engineered to secure vessels or floating structures against drift from wind, current, and tide forces; break strengths routinely exceed 2,000 kN for offshore platform applications. Polyester dominates permanent mooring installations due to its creep resistance and seawater durability, while polypropylene commands fishing fleet refit cycles where cost sensitivity outweighs service life. Marine construction applications represent the fastest-expanding demand pool, driven by floating offshore wind platform deployments that require station-keeping systems with 25-year design lives. The above 16mm diameter category carries disproportionate margin contribution, as custom splicing, proof-loading, and classification society certification add value beyond raw fiber cost.
ISO 2307 and Bureau Veritas NR493 establish minimum breaking strength and fatigue testing protocols that exclude uncertified manufacturers from European offshore energy tenders. The US Coast Guard and OSHA mooring safety directives shape product specifications for commercial shipping fleets operating in US waters, particularly regarding snap-back hazard mitigation. Stakeholders must monitor classification society evolution toward bio-based fiber acceptance, as DNV and Lloyd's Register pilot qualification pathways that could restructure raw material sourcing requirements within the decade.
Market Dynamics
Floating offshore wind platform deployments are compressing design cycles and forcing rope manufacturers to certify 25-year service life products before project financing closes. This structural pressure elevates classification society approval from a quality signal to a hard gate for contract eligibility.
Growth Catalysts
- EU Marine Equipment Directive:Tightened certification requirements for permanent offshore installations are filtering out uncertified competitors and consolidating procurement among qualified suppliers.
- Floating offshore wind:Deep-water wind farms in the North Sea and Norwegian continental shelf require specialized high-performance synthetic mooring lines with extended fatigue resistance.
- HMPE fiber substitution:Heavy-lift vessel operators are replacing wire rope assemblies with high-modulus polyethylene to reduce deck weight and crew handling requirements.
Market Restraints
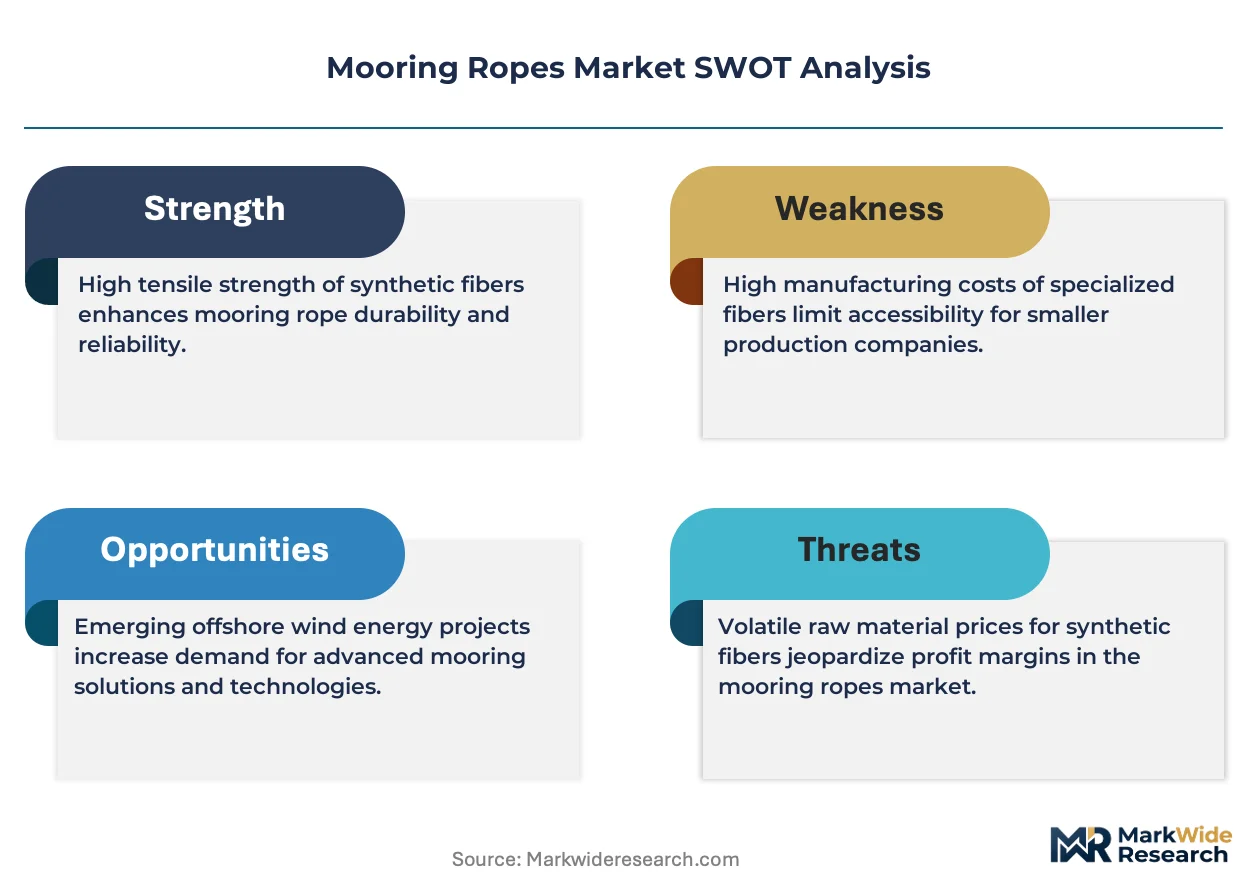
- Petrochemical feedstock volatility:Synthetic fiber prices track naphtha and propylene markets, compressing margins when oil prices spike without corresponding contract escalation clauses.
- Norwegian supply concentration:Floating wind and aquaculture demand clusters in a single geography, creating regional overcapacity risk if project timelines slip.
- Wire rope residual preference:Conservative marine construction contractors in Mediterranean ports retain steel assemblies for visible-load applications despite synthetic performance advantages.
Strategic Opportunities
- Mediterranean port authority upgrades:UV-resistant polyester-nylon hybrid constructions address southern European harbor infrastructure renewal cycles with 15-20 year replacement horizons.
- Bio-based fiber qualification:DNV and Lloyd's Register pilot pathways for renewable feedstock ropes could restructure raw material sourcing and unlock premium positioning.
- Direct contractor integration:Rope manufacturers are embedding splicing and proof-loading services at offshore construction yards, capturing margin from third-party rigging shops.
Industry Challenges
- Classification society backlog:ISO 2307 and Bureau Veritas NR493 fatigue testing queues extend certification timelines, delaying contract execution for novel fiber constructions.
- Synthetic splicing technician scarcity:HMPE and aramid rope termination requires specialized heat-setting and tapering skills that maritime academies have not scaled to match demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mooring Ropes Market |
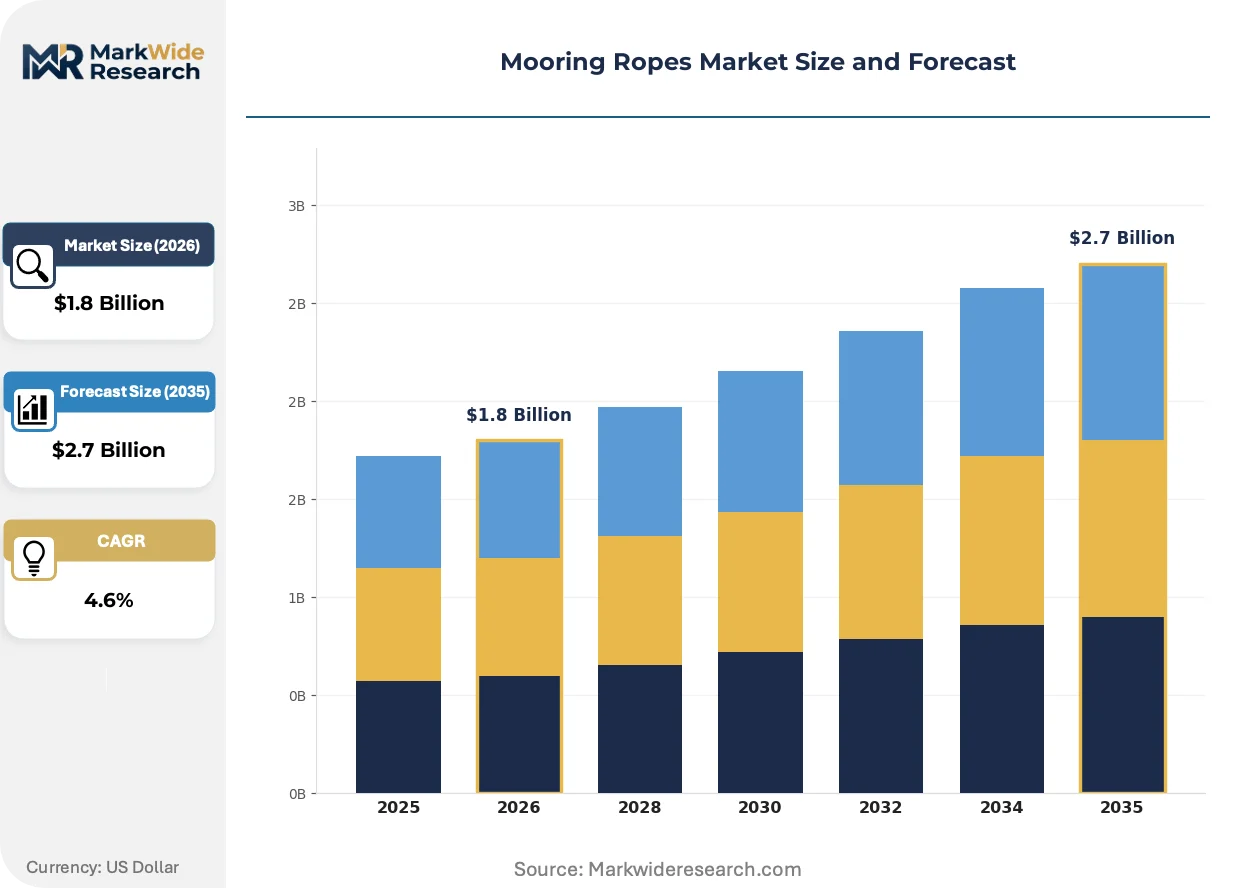
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Nylon, Polyester, Manilla Diameter: Up to 8mm, 8-12mm, 12-16mm, Above 16mm Application: Commercial Shipping, Fishing, Recreational Boating, Marine Construction End User: Shipping Companies, Fishing Charters, Yacht Owners, Port Authorities |
| Companies Covered | Teufelberger Holding AG, Marlow Ropes Ltd, Samson Rope Technologies, Katradis Marine Ropes Industry S.A., Cortland Limited, WireCo WorldGroup, Lankhorst Ropes, Yale Cordage, Bridon-Bekaert Ropes Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mooring Ropes Market Emerging Trajectories
Material science advances and regulatory qualification pathways are restructuring how mooring systems are specified, procured, and maintained across offshore energy and commercial marine segments.
High-modulus polyethylene is absorbing load-bearing functions previously reserved for wire rope in heavy-lift offshore applications. North Sea offshore energy contractors are specifying HMPE assemblies for floating wind platform station-keeping systems. The technology is absorbing engineering talent and certification resources that steel rope suppliers previously commanded.
REACH substance restrictions and the EU Green Deal are accelerating scrutiny of petrochemical-based synthetic fibers in European offshore tenders. Manufacturers must now document full lifecycle environmental profiles to maintain eligibility for public-sector floating wind contracts. Baltic Sea projects are responding fastest, with Danish and German developers inserting bio-based fiber readiness clauses into supply agreements.
Buyers are unbundling rope supply from integrated rigging packages and negotiating direct long-term agreements with fiber manufacturers. Offshore construction contractors are disintermediating traditional marine distributors to secure volume commitments and technical support. Norway's floating wind developers pioneered this model, and the practice is propagating to Scottish and Portuguese project consortia.
Mooring Ropes Market Segmentation
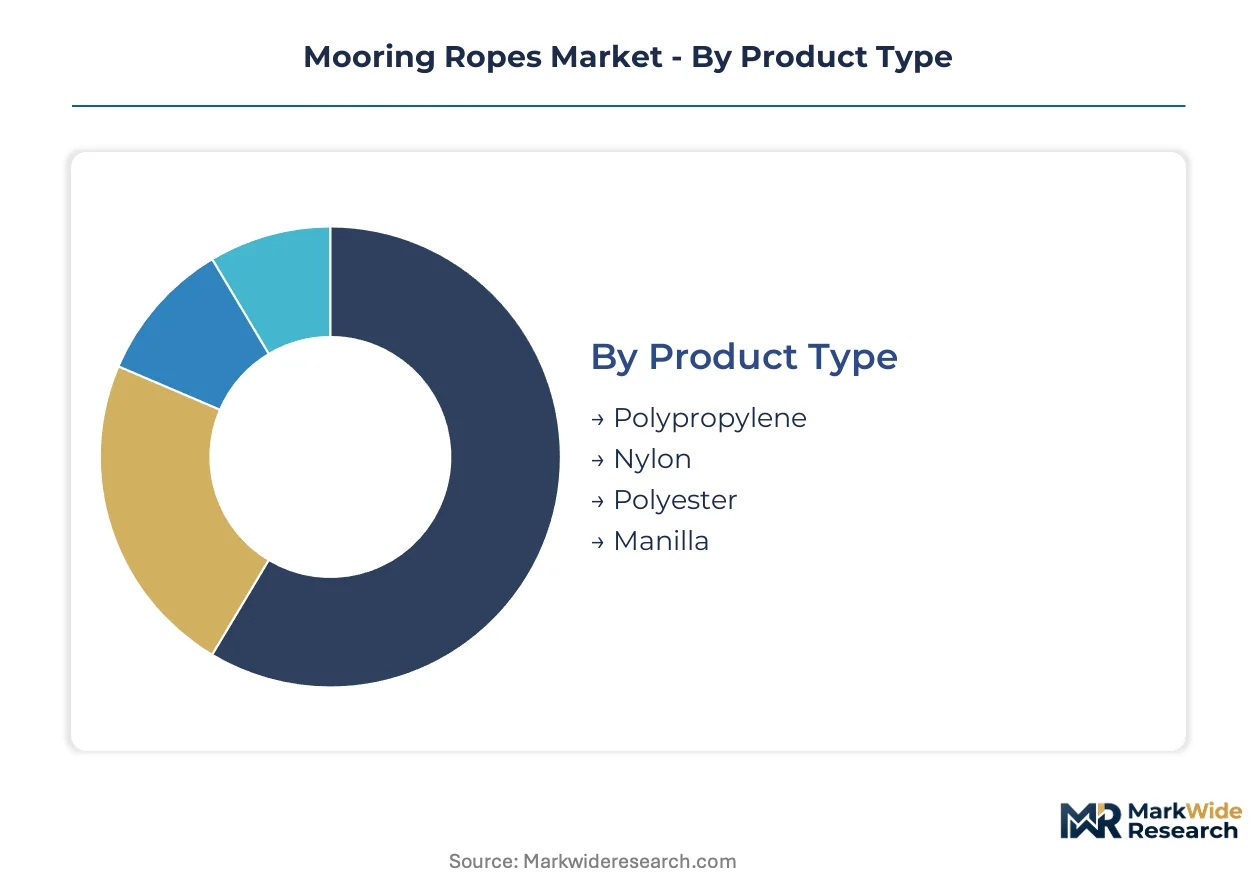
Mooring rope specifications diverge sharply across end-use environments, with certification requirements and service life expectations dictating fiber selection and diameter thresholds. Segmentation reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
ISO 2307 and Bureau Veritas NR493 impose tiered certification burdens: polyester and HMPE constructions face extended fatigue testing protocols, while polypropylene and manilla qualify under lighter inspection regimes for non-permanent installations.
- Polyester:Braided or twisted polyethylene terephthalate fiber engineered for creep resistance and hydrolytic stability in permanent mooring installations. North Sea floating offshore wind developers specify polyester for 25-year design life station-keeping systems, though REACH substance documentation requirements now extend procurement timelines.
- High-modulus polyethylene (HMPE):Ultra-high molecular weight polyethylene delivering strength-to-weight ratios that enable wire rope substitution in heavy-lift offshore applications. Norwegian continental shelf contractors are absorbing HMPE assemblies for floating wind platforms, compressing deck weight and reducing crew handling requirements.
- Polypropylene:Lightweight olefin fiber with positive buoyancy characteristics suited to fishing fleet trawl and temporary mooring applications. Mediterranean fishing cooperatives favor polypropylene for cost-sensitive refit cycles where service life expectations remain below five years.
- Nylon:Polyamide construction offering superior shock absorption and abrasion resistance in dynamic loading environments. US commercial shipping fleets specify nylon for barge fleeting and harbor assist operations where elasticity mitigates snap-back hazards.
- Manilla:Natural abacá fiber retaining niche demand from traditional sailing vessel operators and heritage port authorities. Italian and Greek island ferry terminals maintain manilla inventories for aesthetic and regulatory compliance in protected maritime zones.
Leading the category by volume: polyester. Growing fastest: HMPE.
Diameter:
Margin structures invert across diameter thresholds, with certification and splicing labor comprising disproportionate value share in larger specifications.
- Above 16mm:Custom-engineered tensile members requiring proof-loading, classification society certification, and specialized splicing protocols. Offshore platform mooring legs and floating wind station-keeping systems concentrate demand in this category, with Bureau Veritas and DNV approval gates filtering supplier participation.
- 12-16mm:Mid-range diameter serving commercial shipping permanent mooring and deep-water aquaculture grid installations. Norwegian salmon farming operators specify 12-16mm polyester hybrids for exposed-site pen anchoring.
- 8-12mm:Standard commercial fishing and coastal shipping specification where volume throughput offsets per-unit margin compression. Portuguese and Spanish Atlantic fleet operators cycle through 8-12mm polypropylene on 3-5 year replacement horizons.
- Up to 8mm:Recreational boating and small-craft auxiliary mooring applications with minimal certification overhead. Mediterranean marina operators stock up to 8mm nylon for transient yacht berthing.
Price differentiation concentrates above 16mm. Volume throughput dominates below 12mm.
Application:
End-use environments dictate fiber selection through load cyclicity, UV exposure, and regulatory visibility.
- Marine Construction:Floating offshore wind platform deployment and subsea infrastructure installation requiring 25-year service life certification. North Sea and Norwegian continental shelf projects are absorbing specialized synthetic mooring assemblies at rates outpacing other applications.
- Commercial Shipping:Container vessel, tanker, and bulk carrier permanent mooring systems subject to port state control inspection regimes. US Coast Guard and OSHA directives shape snap-back hazard mitigation specifications for fleets operating in US waters.
- Fishing:Trawl, seine, and longline vessel operations with high fiber consumption and compressed replacement cycles. North Atlantic and Mediterranean fishing fleets drive polypropylene and nylon volume through seasonal refit patterns.
- Recreational Boating:Yacht and pleasure craft mooring with aesthetic and handling priorities superseding technical performance. Coastal Mediterranean and Caribbean marinas represent seasonal demand concentration.
Marine construction claims steepest expansion trajectory. Commercial shipping retains largest installed base.
End User:
Procurement sophistication varies sharply across buyer categories, with technical specification authority residing in distinct organizational functions.
- Port Authorities:Municipal and regional harbor operators managing permanent mooring infrastructure with 15-20 year replacement horizons. Southern European port authorities in Spain, Italy, and Greece specify UV-resistant polyester-nylon hybrids for high-exposure Mediterranean conditions.
- Shipping Companies:Fleet operators with centralized procurement functions negotiating volume contracts against classification society approval lists. Danish and German container lines have pioneered direct fiber manufacturer agreements, disintermediating traditional marine distributors.
- Fishing Charters:Small-scale operators and cooperative fleets with decentralized purchasing and price-sensitive specification. Atlantic and Mediterranean fishing charters cycle lower-diameter polypropylene on annual or biennial replacement schedules.
- Yacht Owners:Individual and club-operated recreational vessels with preference-driven fiber selection and minimal regulatory oversight. Premium synthetic and natural fiber demand clusters in Mediterranean and Caribbean charter hubs.
Port authorities anchor public-sector specification authority. Shipping companies drive contract scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Floating offshore wind procurement concentrates demand in North Sea littoral states, with certification requirements and project financing timelines filtering supplier participation toward qualified domestic and regional manufacturers.
Norway
Floating wind platforms and deep-water aquaculture operations drive specialized rope consumption along the Norwegian continental shelf. The Norwegian Maritime Authority enforces station-keeping system certification aligned with DNV standards for 25-year design life installations. Bergen and Stavanger host engineering clusters where contractors coordinate synthetic mooring assembly procurement for North Sea energy projects.
United Kingdom
Scottish floating wind consortia and North Sea decommissioning activity absorb high-diameter synthetic assemblies. The Maritime and Coastguard Agency implements mooring safety directives that shape commercial fleet specifications for vessels operating in UK waters. Aberdeen and Dundee serve as procurement hubs where offshore construction contractors negotiate direct fiber manufacturer agreements.
Germany
Baltic Sea offshore wind developers insert bio-based fiber readiness clauses into supply agreements under EU Green Deal procurement guidelines. The Federal Maritime and Hydrographic Agency oversees classification society alignment for permanent offshore installations. Rostock and Hamburg anchor industrial clusters where port infrastructure renewal cycles drive UV-resistant polyester-nylon hybrid demand.
United States
Heavy-lift vessel operators replace wire rope assemblies with HMPE to reduce deck weight and crew handling requirements. The US Coast Guard and OSHA mooring safety directives shape snap-back hazard mitigation specifications for commercial shipping fleets. Gulf Coast offshore construction yards in Texas and Louisiana embed splicing and proof-loading services to capture rigging margin.
China
Deep-water aquaculture grid expansion and port infrastructure development absorb volume throughput in mid-diameter specifications. The Maritime Safety Administration implements national standards for mooring equipment certification that parallel ISO protocols. Qingdao and Shanghai host manufacturing clusters where synthetic fiber extrusion capacity serves domestic and export demand.
Mooring Ropes Market Vendor Landscape
Backward integration into synthetic fiber extrusion dominates the current landscape, with manufacturers capturing margin pools that competitors forfeit to third-party suppliers. The vendor base organizes around three strategic archetypes: integrated fiber-to-rope producers, specialized marine construction suppliers, and diversified industrial cordage manufacturers. M&A activity and capacity expansion constitute the primary competitive vectors, as classification society approval requirements elevate barriers for uncertified entrants.
Among European integrated producers, Teufelberger Holding AG anchors the fiber-extrusion archetype through captive supply of synthetic raw materials. Samson Rope Technologies occupies a position within the specialized marine construction tier, securing long-term supply relationships with North Sea offshore energy contractors. Katradis Marine Ropes Industry S.A. represents the regional specialist archetype, serving Mediterranean port authorities with hybrid constructions purpose-built for high UV-exposure profiles.
| Leading Market Players |
|---|
| Teufelberger Holding AG |
| Marlow Ropes Ltd |
| Samson Rope Technologies |
| Katradis Marine Ropes Industry S.A. |
| Cortland Limited |
| WireCo WorldGroup |
| Lankhorst Ropes |
| Yale Cordage |
| Bridon-Bekaert Ropes Group |
| Others |
Supply Flow & Price Mechanics
Floating offshore wind developers' compressed 25-year certification timelines are forcing rope manufacturers to pre-qualify products before project financing closes, elevating classification society approval costs and filtering supply toward qualified producers with captive testing capacity.
Pricing Analysis
Volume throughput dominates below 12mm diameters where polypropylene fishing fleet specifications compete on raw fiber cost, while margin pools concentrate above 16mm where Bureau Veritas and DNV certification, custom splicing, and proof-loading services add value beyond commodity fiber inputs. Price differentiation separates premium HMPE heavy-lift assemblies from standard polyester permanent moorings and economy polypropylene temporary lines. Cost compression in mid-diameter commercial shipping specifications is intensifying as fleet operators consolidate procurement through direct fiber manufacturer agreements. Fishing charters exhibit highest price sensitivity due to seasonal cash flow patterns, while Norwegian floating wind consortia accept premium positioning for 25-year design life certification.
Supply Chain Analysis
Synthetic splicing technician scarcity in Norway, Germany, and the United States is constraining termination capacity for HMPE and aramid rope assemblies, forcing manufacturers to embed heat-setting and tapering skills at offshore construction yards. Raw material supply draws from petrochemical feedstocks tracking naphtha and propylene markets, specialized synthetic fiber extrusion equipment, and classification society testing protocols. Single-source vulnerability concentrates in high-modulus polyethylene fiber production where limited extrusion capacity serves heavy-lift offshore demand. Distribution runs through direct contractor integration at North Sea and Gulf Coast construction yards, disintermediating traditional marine distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ISO 2307 and Bureau Veritas NR493 certification requirements erect barrier-to-entry moats that consolidate procurement among qualified suppliers with approved testing capacity.
For Market Incumbents: Hedge petrochemical feedstock exposure through long-term polymer supply agreements or backward integration into synthetic fiber extrusion, while defending DNV and Lloyd's Register approval positions against emerging bio-based fiber qualification pathways that could restructure raw material sourcing requirements. For New Entrants and Emerging Players: Enter via Mediterranean port authority infrastructure renewal cycles where UV-resistant polyester-nylon hybrid specifications face lighter certification burdens than North Sea floating wind applications, targeting Spanish and Greek harbor operators with 15-20 year replacement horizons through specialized splicing and proof-loading service bundling. For Investors and Strategic Acquirers: The window for entry favors integrated fiber-to-rope producers with captive extrusion capacity and established classification society relationships, as approval backlogs and technician scarcity extend competitive moats; monitor DNV and Lloyd's Register bio-based fiber qualification pathway advancement as inflection signal for raw material sourcing restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Extrusion | Captures margin pools forfeited to third-party polymer suppliers and secures supply continuity. |
| Classification Society Certification Investment | DNV and Bureau Veritas approval gates filter contract eligibility for permanent offshore installations. |
| Direct Contractor Integration | Embedding splicing and proof-loading at Norwegian and Gulf Coast yards disintermediates rigging shops. |
| Bio-based Fiber Qualification Pathway | EU Green Deal procurement guidelines accelerate scrutiny of petrochemical-based synthetic fibers. |
| Synthetic Splicing Technician Training Scale-Up | HMPE and aramid termination skills scarcity constrains capacity expansion across qualified manufacturers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with offshore construction procurement officers, classification society surveyors, synthetic fiber extrusion plant managers, and port authority engineering directors with bottom-up and top-down triangulation against Bureau Veritas certification databases, EU Marine Equipment Directive implementation reports, and Norwegian Maritime Authority station-keeping system filings.
Reconciling vessel deployment schedules with fiber manufacturer capacity announcements and certification timeline data established the analytical framework across the projection horizon, modeling diameter thresholds, fiber type specifications, application segments, and regional regulatory clusters to derive growth trajectories; floating offshore wind project financing closures and aquaculture grid expansion permits served as demand-side validation inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock volatility, Norwegian floating wind project timeline slippage, or accelerated bio-based fiber qualification pathway adoption. Material deviation in classification society backlog duration or synthetic splicing technician training scale warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fender Market
Marine
Marine Stabilizers Market
Marine
Unmanned Marine Vehicles Market
Marine
Marine Gas Oil Market
Marine
Azimuth Thrusters Market
Marine
Marine Pipes Market
Marine
Global Marine Gearbox Market
Marine
Marine Salvage Services Market
Marine
Offshore AUV and ROV Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Marine Strip Market
Marine
Military Marine Engine Market
Marine
Europe Recreational Boating Market
Marine
LNG Bunkering Vessel Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Boat Console Market