
 Boat Hook Market | 2026-2036
Boat Hook Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Hook Market Outlook
The capital-intensity divergence between mass-market distributors and precision manufacturers is unwinding competitive stability in the boat hook supply base. West Marine leverages its coast-to-coast retail footprint to control shelf access for recreational skippers. Lewmar anchors its position through specialized marine hardware engineering that sustains premium positioning in the sailing segment. Garelick Manufacturing competes on domestic production scale, occupying the commercial-vessel replacement channel with standardized fixed-length models.
A boat hook is a pole-mounted retrieval and mooring tool, typically extending six to twelve feet, with a curved or blunted tip designed to catch lines, fend off obstacles, or guide vessels without direct contact. Aluminum telescopic variants dominate the consumer segment due to their strength-to-weight ratio and saltwater corrosion resistance, while fiberglass fixed models lead professional applications requiring rigidity under load. The material dimension shows margin pools concentrating in marine-grade aluminum extrusions, whereas the application dimension reveals recreational boating as the volume anchor and professional use as the specification driver for extended-reach designs. The end-user split shows marine enthusiasts as the price-sensitive mass base and commercial vessels as the contract-stable institutional buyer.
US Coast Guard equipment carriage requirements and ABYC (American Boat and Yacht Council) safety standards shape minimum performance thresholds for onboard retrieval tools, while EPA anti-fouling coating rules indirectly influence material selection for hardware stored in wet environments. The Consumer Product Safety Commission monitors recreational marine product recalls, creating compliance overhead for imported telescopic mechanisms. Stakeholders must monitor how state-level marina safety audits and insurance underwriter equipment mandates reshape procurement specifications ahead of the next replacement cycle.
Market Dynamics
The corrosion-resistant aluminum extrusion wave is compressing traditional wood and steel supply tiers while redistributing margin pools toward precision extruders serving Florida's charter fleet expansion.
Growth Catalysts
- Coastal Marina Safety Mandates:Florida and Gulf Coast jurisdictions are tightening equipment carriage requirements for commercial charter operators, forcing systematic replacement cycles across aging fleets.
- Fiberglass Composite Maturation:Pultrusion advances have reduced unit costs for rigid fixed-length models, opening professional-specification products to serious recreational buyers.
- REACH Compliance Spillover:European anti-corrosion coating standards are pressuring Asian exporters to upgrade surface treatments, indirectly elevating quality baselines for US-imported hardware.
Market Restraints
- Primary Aluminum Volatility:LME price swings for marine-grade 6061-T6 extrusions compress fabricator margins and deter long-term contract pricing.
- Guangdong Supply Concentration:Telescopic mechanism subassembly production clusters in China's Pearl River Delta, exposing distributors to single-point logistics risk.
- Wood Substitute Limitations:Traditional hardwoods retain price-insulated demand among heritage sailing vessel restorers who reject synthetic aesthetics.
Strategic Opportunities
- Great Lakes Underpenetration:Freshwater charter operators in Michigan and Wisconsin currently underspend on saltwater-grade hardware, creating upgrade conversion potential.
- Insurance-Driven Specification:Marine underwriters are tightening equipment audit protocols, converting discretionary safety spending into mandated procurement.
- Direct-to-Slip E-Commerce:Harbor-based fulfillment models bypass traditional chandlery markups and capture emergency replacement demand from moored vessels.
Industry Challenges
- ABYC Certification Bottlenecks:Third-party testing backlogs for telescopic locking mechanisms delay product launches by 4-8 months.
- Weld Technician Scarcity:TIG certification requirements for marine-grade aluminum assembly outpace vocational training pipeline output in coastal manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Hook Market |
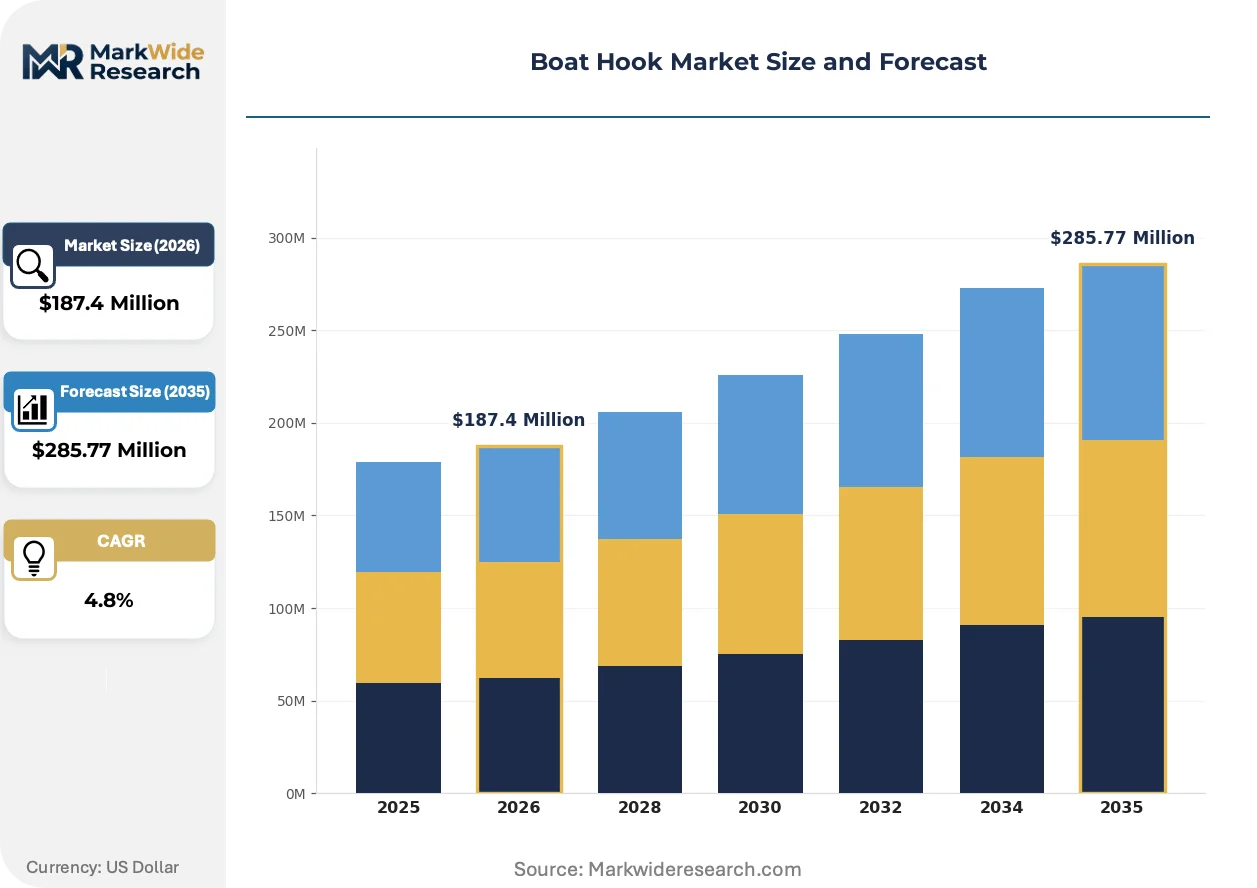
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic, Fixed, Folding, Inflatable Material: Aluminum, Fiberglass, Wood, Plastic Application: Sailing, Fishing, Recreational Boating, Professional Use End User: Marine Enthusiasts, Commercial Vessels, Charters, Boat Rentals |
| Companies Covered | West Marine, Lewmar, Davis Instruments, Sea-Dog Line, Perko, Attwood, Dock Edge, Garelick Manufacturing, Taylor Made Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Hook Market Strategic Shifts
Material substitution and procurement digitization are converging to compress traditional distribution hierarchies while elevating performance specifications across both consumer and professional tiers.
Carbon fiber reinforced polymer (CFRP) hybrid shafts are supplanting pure aluminum telescopic designs in high-load sailing applications. Offshore racing teams and performance catamaran operators are adopting these models despite 40-60% price premiums. The technology is supplanting incumbent aluminum suppliers in the specification-driven segment where gram-counting dictates equipment selection.
EPA anti-fouling coating restrictions are indirectly reshaping hardware storage protocols for wet-environment equipment. Marina operators must now segregate coated and uncoated metal inventory, increasing handling complexity. Coastal Florida facilities are responding by consolidating procurement through distributors with compliant warehousing certifications.
Charter fleet managers are consolidating vendor relationships around integrated safety equipment packages rather than discrete tool purchasing. This behavior concentrates buying power with full-line marine hardware distributors and marginalizes single-product specialists. The pattern is most pronounced in the Gulf of Mexico hub where multi-vessel operators dominate fleet renewal cycles.
Boat Hook Market Segmentation
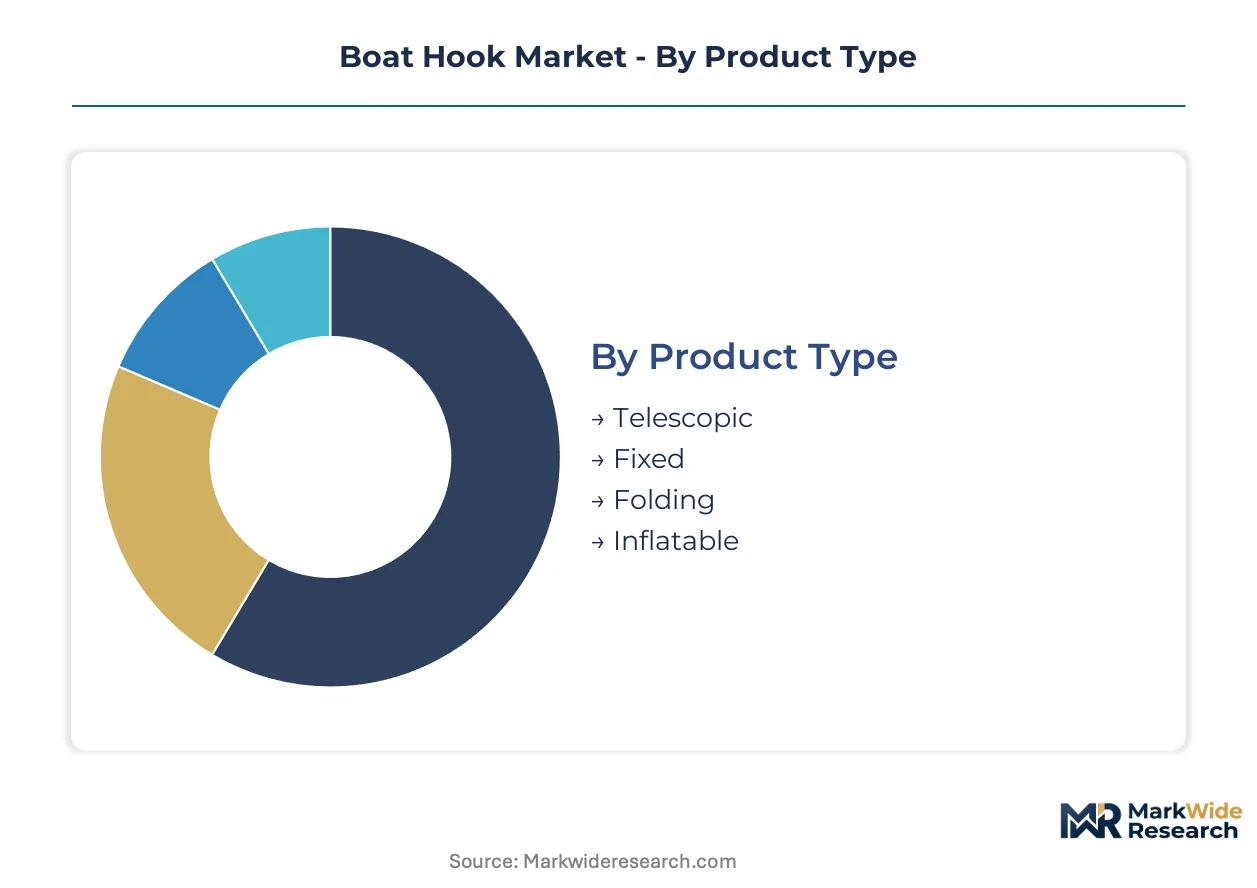
Boat hook procurement patterns diverge sharply between recreational skippers prioritizing portability and commercial operators demanding load-rated rigidity. Material selection and mechanism type determine margin capture, while application context dictates specification intensity and replacement frequency.
Product Type:
Margin pools concentrate in precision-engineered locking mechanisms and corrosion-resistant surface treatments rather than raw pole fabrication.
- Telescopic:Aluminum shaft segments with twist-lock or cam-lock extensions collapse to three feet and extend to twelve feet. Saltwater charter fleets in Florida and the Gulf of Mexico drive specification upgrades as marina safety audits mandate reachable retrieval capability across vessel freeboard heights.
- Fixed:Single-piece aluminum or fiberglass shafts deliver maximum rigidity for heavy-load mooring operations. Commercial fishing vessels and tug operators in Pacific Northwest ports specify fixed models where deflection tolerance approaches zero under bollard load.
- Folding:Hinged mid-shaft designs reduce stowage footprint for cabin cruisers with limited locker space. Coastal liveaboard communities in the Chesapeake Bay show concentration here.
- Inflatable:Rigid-hull inflatable boat operators use buoyant foam-cored variants that float if dropped overboard. Marina-based rental fleets in San Diego specify these for liability reduction.
Fixed models hold installed capacity across commercial replacement channels. Telescopic variants are rotating up the share rankings as charter fleet consolidation drives standardized equipment packages.
Material:
Cost tiers separate marine-grade extrusions from commodity substitutes, with surface treatment certification becoming the decisive price discriminator.
- Aluminum:6061-T6 marine-grade extrusions with anodized or powder-coated finishes dominate volume production. REACH-compliant coating upgrades from Asian suppliers are elevating baseline quality for US-imported hardware.
- Fiberglass:Pultruded E-glass or S-glass composites offer electrical isolation and radar transparency for sailing yachts. Performance racing programs in Newport and Annapolis specify carbon-fiber hybrids despite substantial price premiums.
- Wood:Traditional hardwoods including ash and hickory persist among heritage vessel restorers rejecting synthetic aesthetics. Great Lakes wooden boat societies sustain niche demand.
- Plastic:Glass-reinforced nylon and polypropylene serve freshwater recreational markets where salt corrosion is absent. Inland lake operators in Minnesota and Wisconsin prioritize weight reduction over marine-grade durability.
Aluminum commands the replacement volume base. Fiberglass is climbing the fastest as pultrusion cost reductions open professional specifications to serious recreational buyers.
Application:
Customer type determines whether procurement is discretionary safety spending or mandated equipment carriage.
- Sailing:Lightweight retrieval tools for man-overboard recovery and sail-handling from deck level. Offshore racing teams specify gram-counted carbon fiber variants where every pound alters handicap ratings.
- Fishing:Heavy-duty gaff and tag-line applications requiring load-rated shafts. Commercial longline operators in Alaska and Pacific Northwest ports drive demand for fixed-length aluminum models.
- Recreational Boating:General-purpose mooring and fending for powerboat operators. West Marine's coast-to-coast retail footprint captures this price-sensitive mass market through private-label telescopic offerings.
- Professional Use:Charter captains and marine pilots requiring ABYC-certified equipment for insurance compliance. Gulf of Mexico multi-vessel operators consolidate procurement through integrated safety equipment packages.
Recreational boating anchors volume throughput. Professional use is expanding most quickly as underwriter audit protocols convert discretionary spending into mandated procurement.
End User:
Procurement authority separates individual purchasing decisions from fleet-scale contract negotiations with multi-year replacement schedules.
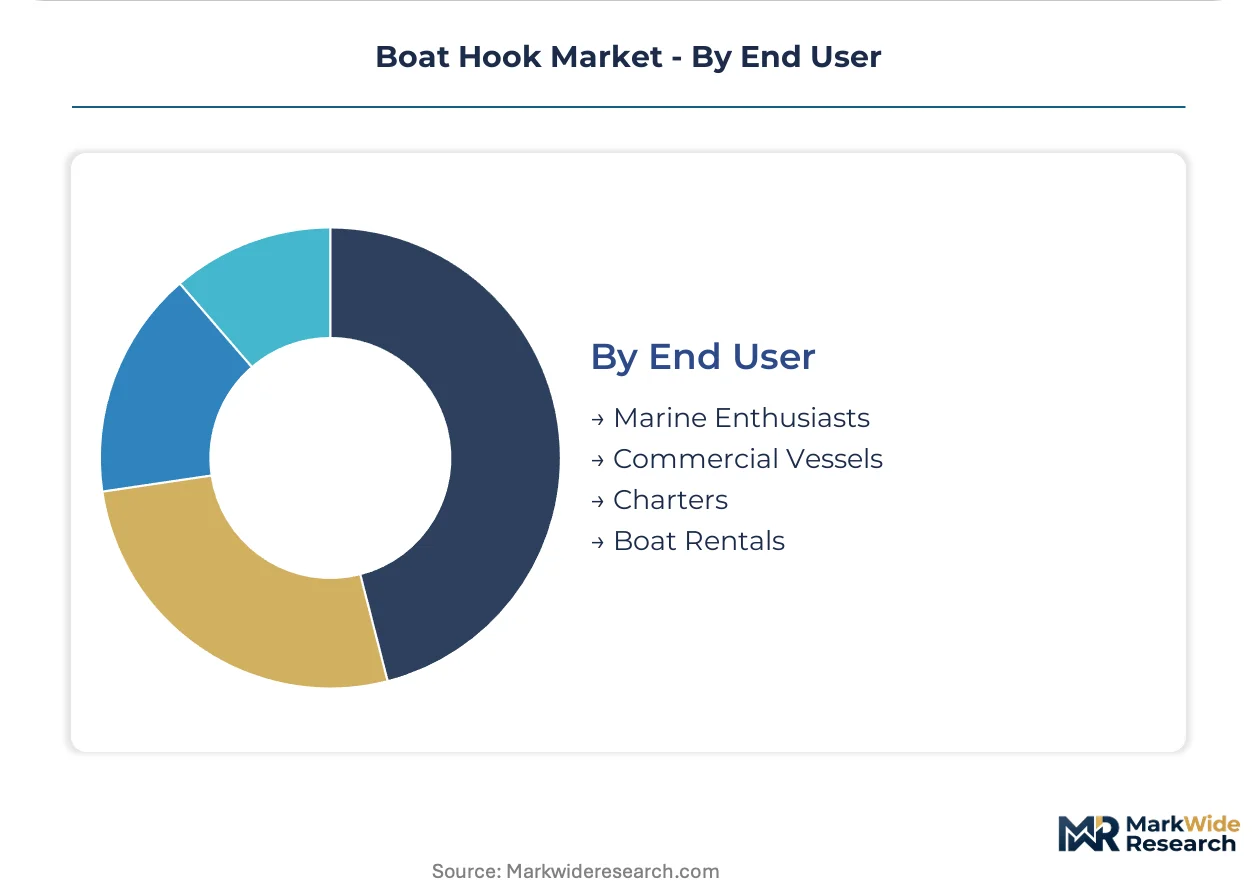
- Marine Enthusiasts:Individual boat owners making discretionary safety equipment purchases through chandleries and e-commerce. Harbor-based direct-to-slip fulfillment models are capturing emergency replacement demand.
- Commercial Vessels:Shipping companies and workboat operators with documented maintenance protocols. Garelick Manufacturing occupies this channel with standardized fixed-length models and domestic production scale.
- Charters:Multi-vessel operators in Florida and Gulf Coast jurisdictions facing tightened equipment carriage requirements. Fleet managers consolidate vendor relationships around full-line marine hardware distributors.
- Boat Rentals:Marina-based day-rental and bareboat operations with high tool attrition rates. Inflatable and plastic variants dominate for loss tolerance and cost recovery.
Marine enthusiasts sustain the broadest SKU variety. Charters are gaining share fastest as fleet consolidation concentrates buying power among specification-driven institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States charter operators deploy telescopic aluminum models for marina compliance, while European sailing programs prioritize carbon fiber hybrids for racing handicaps. Asian manufacturing clusters supply mechanism subassemblies to both markets under divergent coating standards.
United States
Florida and Gulf Coast charter fleets drive specification upgrades as marina safety audits mandate extended-reach retrieval capability. US Coast Guard equipment carriage requirements and ABYC safety standards enforce minimum performance thresholds for onboard tools. Miami and Tampa Bay serve as consolidation hubs where multi-vessel operators standardize procurement through integrated safety equipment packages.
Germany
Precision marine hardware engineering sustains premium positioning in the sailing segment, particularly for Baltic and North Sea racing programs. REACH compliance spillover from ECHA anti-corrosion coating standards elevates quality baselines for hardware imports. Hamburg and Bremen harbor districts concentrate specialist fabricators serving northern European yacht builders.
China
Pearl River Delta manufacturing clusters dominate telescopic mechanism subassembly production for export markets. GB standards and SAMR oversight shape domestic product certification while dual carbon goals pressure energy-intensive extrusion operations. Guangdong province facilities face logistics concentration risk as primary supply nodes for US and European distributors.
United Kingdom
Heritage sailing vessel restorers in Solent and Clyde estuary regions sustain niche demand for traditional hardwood construction. Maritime and Coastguard Agency equipment guidelines influence commercial operator procurement alongside ISO marine standards. Southampton and Portsmouth marine clusters retain specialist chandleries serving classic yacht preservation societies.
Australia
Queensland and New South Wales charter operators adopt saltwater-grade aluminum hardware for Great Barrier Reef tourism fleets. TGA-equivalent marine safety protocols and state-level workplace equipment mandates shape procurement specifications. Sydney and Gold Coast marinas consolidate vendor relationships around full-line distributors with compliant warehousing certifications.
Boat Hook Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with coast-to-coast retail footprints controlling shelf access while precision engineering shops capture specification-driven sailing demand. The vendor base stratifies across mass-market distributors, marine hardware specialists, and domestic production scale players. Three archetypes dominate: retail-network operators leveraging private-label sourcing, engineering-centric brands sustaining premium positioning through technical differentiation, and contract-stable manufacturers serving institutional replacement channels. Competitive moves concentrate on vendor consolidation for charter fleet accounts and direct-to-slip e-commerce fulfillment bypassing traditional chandleries.
Among US-based marine retailers, West Marine exemplifies the coast-to-coast network archetype with extensive shelf presence for recreational skippers. Lewmar occupies a position within the precision-engineered tier, anchoring premium positioning through specialized marine hardware design. Garelick Manufacturing represents the domestic production scale archetype, serving commercial-vessel replacement channels with standardized fixed-length models.
| Leading Market Players |
|---|
| West Marine |
| Lewmar |
| Davis Instruments |
| Sea-Dog Line |
| Perko |
| Attwood |
| Dock Edge |
| Garelick Manufacturing |
| Taylor Made Products |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for marine-grade 6061-T6 aluminum extrusions lock in supply access for Florida charter fleet operators while anchoring price visibility against LME volatility. This contract structure concentrates procurement power among multi-vessel operators who can commit to volume minimums, squeezing spot-market buyers into premium pricing tiers.
Pricing Analysis
After-sales service contracts for telescopic mechanism refurbishment drive lifetime value capture among commercial fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates ABYC-certified carbon fiber hybrids from anodized aluminum mid-market offerings and plastic freshwater recreational models. Pricing pressure stems from REACH-compliant coating upgrades elevating baseline import costs from Guangdong suppliers. Charter operators show lowest price sensitivity due to insurance mandate pass-through, while individual marine enthusiasts in Great Lakes freshwater markets resist saltwater-grade premiums.
Supply Chain Analysis
Inventory lead times for telescopic locking mechanisms extend from Pearl River Delta subassembly clusters through West Marine distribution centers, creating vulnerability to port congestion cascades. Supply concentrates in China for precision extrusions and mechanism components, with secondary sourcing from domestic U.S. fabricators serving military and commercial replacement channels. Raw material dependencies center on primary aluminum ingot, anodizing chemicals, and pultruded fiberglass rod. Single-source vulnerability concentrates in Guangdong's telescopic cam-lock specialist tier. Distribution runs through coast-to-coast marine retail networks and direct-to-slip e-commerce fulfillment bypassing traditional chandleries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as carbon fiber reinforced polymer hybrids displace aluminum in high-load sailing applications. Heritage wood aesthetics and inflatable buoyancy variants further fragment material preference across end-use segments.
For Market Incumbents: Compound ABYC certification depth across telescopic product lines to erect regulatory barriers against Asian mechanism suppliers. Deepen backward integration into marine-grade aluminum extrusion capacity in coastal Florida manufacturing zones. Carbon fiber hybrid entrants threaten premium sailing segment positioning unless incumbents accelerate pultrusion cost parity investments.
For New Entrants and Emerging Players: ABYC fast-track certification programs offer entry acceleration for precision mechanism specialists targeting charter fleet consolidation. White-space concentration sits in Great Lakes freshwater operator conversion from plastic to saltwater-grade hardware. Harbor-based direct-to-slip fulfillment models bypass entrenched chandlery relationships. Target Michigan and Wisconsin marina operators with corrosion-upgrade value propositions.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic production-scale fabricators with captive charter fleet relationships and documented replacement cycle visibility. Long-term viability favors vendors integrated into multi-vessel operator safety equipment packages rather than discrete tool specialists. Watch for insurance underwriter audit protocol tightening as inflection signal converting discretionary to mandated procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive 6061-T6 supply secures margin pools against LME volatility for Florida fleet operators. |
| ABYC Certification Acceleration | Compressed testing timelines capture charter fleet replacement cycles ahead of competitor launches. |
| Direct-to-Slip E-Commerce Fulfillment | Harbor-based logistics bypass West Marine markups and capture emergency replacement demand. |
| Carbon Fiber Hybrid Product Line Extension | Gram-counted specifications penetrate Newport and Annapolis racing programs with premium positioning. |
| Great Lakes Freshwater Market Development | Michigan and Wisconsin operator conversion opens underspent geography to saltwater-grade hardware. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with marine hardware procurement managers, charter fleet operations directors, marina safety auditors, and ABYC certification engineers; and secondary validation through U.S. Coast Guard equipment carriage databases, Florida marina safety audit records, customs import filings for telescopic mechanism components, and SEC filings from publicly traded marine retailers. Bottom-up demand modeling across vessel fleet counts and replacement cycles triangulated against top-down market sizing from distributor revenue disclosures.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, material grade, application intensity, and end-user procurement authority. CAGRs derived from replacement cycle timing, fleet expansion rates, and regulatory mandate phase-in schedules. Specific inputs included charter fleet consolidation patterns, insurance underwriter audit protocol adoption curves, and pultrusion cost reduction trajectories for fiberglass composites.
Decision-makers should treat outputs as directional under sustained aluminum price volatility and Pearl River Delta logistics stability assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Marine Propeller Market
Marine
Marine Stabilizers Market
Marine
Marine Trenchers Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Marine and Marine Management Software Market
Marine
Electric Ship Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Marine Diesel Engine Market
Marine
Sea Skimmer Market
Marine
Marine Chartplotter Market
Marine
Asia-Pacific Electric Boat Market
Marine
Recreational Vessel Battery Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Gas Oil Market
Marine
Hydraulic Marine Cranes Market