
 Marine Gas Oil Market | 2026-2036
Marine Gas Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Gas Oil Market Foresight
Project finance tied to scrubber retrofits and dual-fuel engine conversions is fragmenting capital deployment across the marine fuel supply chain. Shell PLC leverages its integrated refining and bunkering network to sustain volume leadership at major port hubs. BP PLC anchors its position through backward integration into low-sulfur crude processing. ExxonMobil Corporation competes by controlling strategic storage terminals along Asia-Pacific trade lanes.
Marine gas oil denotes a distillate fuel refined to maximum sulfur content of 0.10% by mass under ISO 8217 specifications, engineered for medium- and high-speed diesel engines aboard commercial vessels where residual fuels risk mechanical failure. Its primary purpose is to power auxiliary engines, provide cold-start capability for main engines, and serve as compliance fuel where exhaust gas cleaning systems are absent. Ultra-Low Sulfur Fuel Oil dominates procurement volumes as shipping operators prioritize single-fuel operational simplicity over scrubber investments. Commercial Shipping generates the deepest margin pools due to contract durations and credit structures, while Offshore Exploration exhibits the fastest uptake as drilling contractors face stringent local emissions rules.
The International Maritime Organization enforces sulfur caps through MARPOL Annex VI, compelling fleet operators to burn compliant distillates or install exhaust treatment systems. The EPA regulates U.S. port emissions under the Clean Air Act, restricting fuel sulfur content within Emission Control Areas that extend along coastlines. The EU Green Deal and FuelEU Maritime initiative impose escalating carbon intensity benchmarks that redirect vessel procurement toward lower-carbon distillate blends. Stakeholders must monitor how regional carbon accounting rules reshape the cost calculus between conventional MGO, biofuel blends, and synthetic alternatives.
Market Dynamics
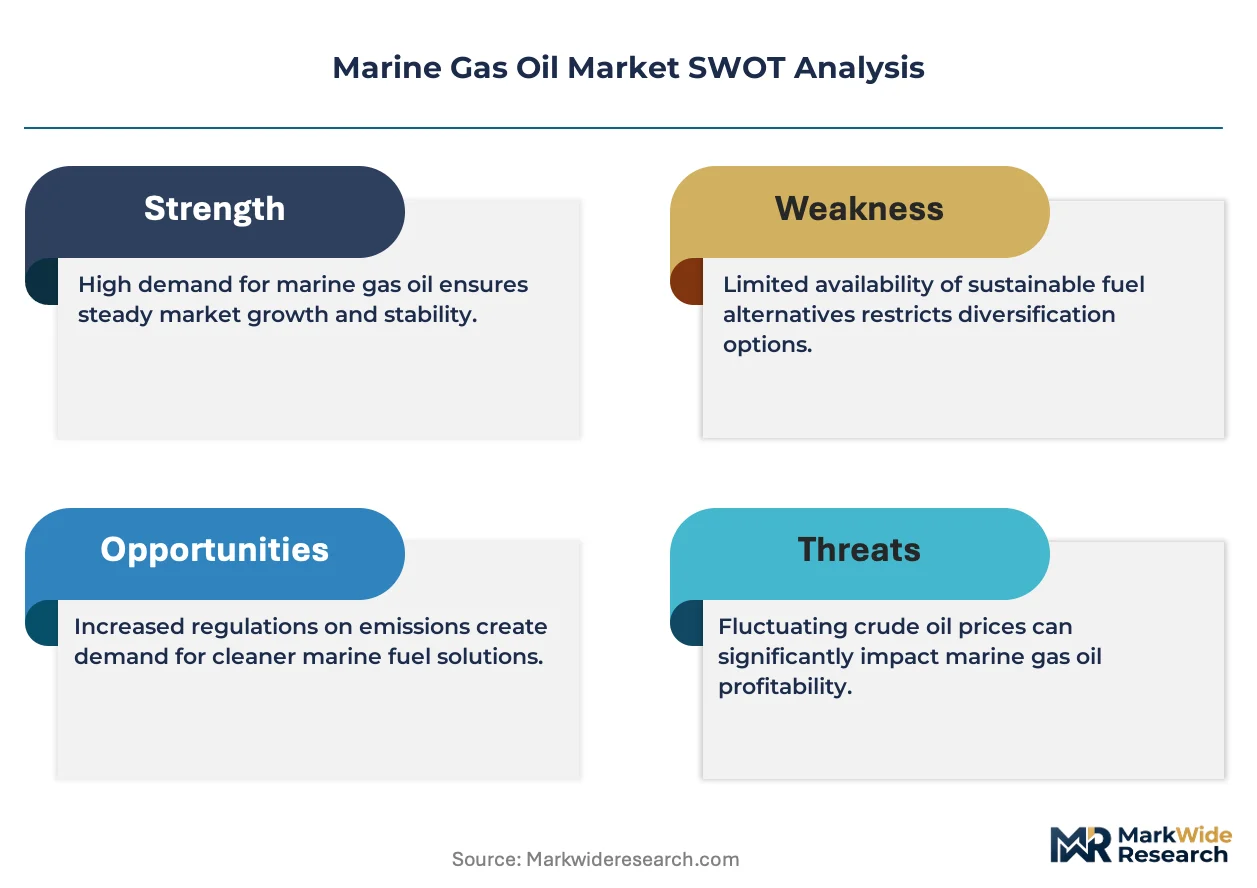
The IMO 2020 sulfur cap enforcement has permanently bifurcated marine fuel procurement, forcing vessel operators into scrubber installation or distillate compliance and reshaping refinery output allocation toward low-sulfur gas oil production.
Growth Catalysts
- ECA Zone Expansion:The EPA's Emission Control Area designations along the US coastline compel coastal shipping operators to burn 0.10% sulfur MGO rather than residual fuels, anchoring demand at Atlantic and Pacific port clusters.
- Offshore Drilling Emissions Rules:North Sea drilling contractors face tightening local sulfur and NOx limits that mandate MGO for platform supply vessels and drilling rigs operating within Norwegian and UK territorial waters.
- Dual-Fuel Engine Proliferation:Wärtsilä and MAN Energy Solutions engine retrofits enable LNG-methanol-MGO flexibility, preserving MGO as pilot fuel and cold-start backup across container and tanker fleets.
Market Restraints
- Crude Price Volatility:Middle East sour crude differentials directly compress MGO refining margins, exposing independent bunkering suppliers to margin erosion when Brent-Dubai spreads widen beyond historical bands.
- Singapore Storage Concentration:Over 60% of Asia-Pacific MGO inventory sits within Jurong Island tank farms, creating single-point vulnerability to tropical weather disruptions or port authority enforcement actions.
- Scrubber Payback Compression:Open-loop scrubber bans in California, China, and Singapore ports have extended capital recovery timelines for shipowners who installed exhaust cleaning systems, freezing MGO substitution rates.
Strategic Opportunities
- Bio-MGO Blending:The EU Green Deal's renewable fuel mandates create certified bio-distillate offtake agreements for Rotterdam and Hamburg suppliers blending FAME and HVO into conventional MGO streams.
- Arctic Route Development:Northern Sea Route ice-class vessel traffic requires ultra-low sulfur distillates for cold-weather operability, opening procurement contracts for Murmansk and Vladivostok bunkering infrastructure.
- Digital Barge Matching:Platform-based spot procurement apps are disintermediating traditional bunker brokers in Singapore and Fujairah, enabling direct vessel-operator-to-supplier contracting with real-time pricing transparency.
Industry Challenges
- ISO 8217 Testing Capacity:Fuel quality disputes require independent laboratory verification of sulfur content, cat fines, and cold filter plugging point, yet accredited testing facilities remain concentrated at major hubs.
- Crew Training Deficits:Engineering officers lack familiarity with dual-fuel engine management and fuel switching protocols, creating operational risk during MGO-LNG transitions in congested traffic separation schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Gas Oil Market |
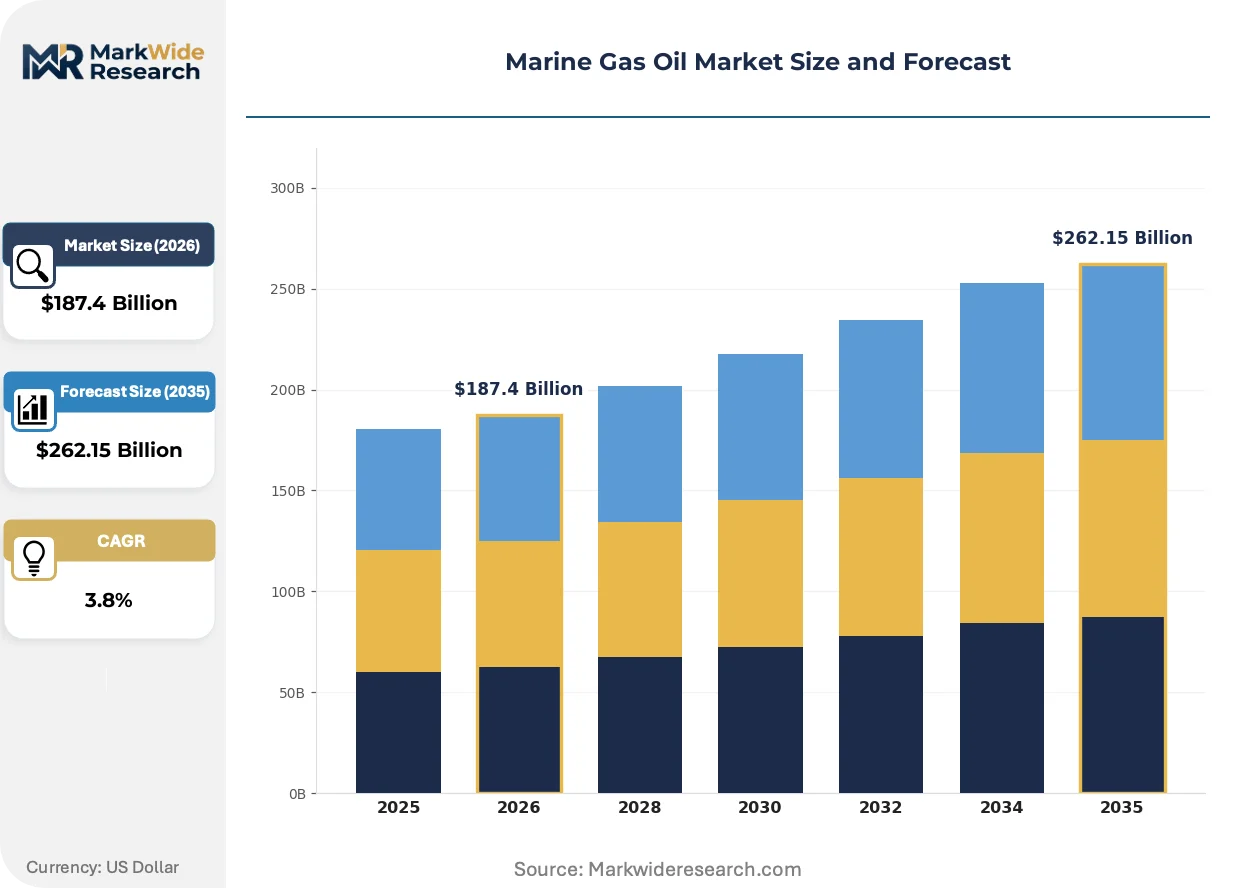
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultra-Low Sulfur Fuel Oil, MGO, DMA, DMB End User: Shipping Companies, Fishing Vessels, Offshore Industry, Yachts Distribution Channel: Direct Sales, Bunkering Services, Online Platforms, Distributors Application: Commercial Shipping, Recreational Boating, Offshore Exploration, Cargo Transport |
| Companies Covered | Shell PLC, BP PLC, TotalEnergies SE, ExxonMobil Corporation, Chevron Corporation, Gazprom Neft PJSC, PJSC Lukoil Oil Company, Bomin Bunker Fuel Holding GMBH & Co. KG, Clipper Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Gas Oil Market Shifts & Advancements
Bunkering operations are converging on real-time fuel quality verification and automated procurement platforms that compress transaction friction and reduce off-specification disputes between suppliers and vessel operators.
Blockchain-based bunker delivery note systems are digitizing the custody transfer process from barge to vessel. Container lines including Maersk and MSC are piloting distributed ledger verification of sulfur content and mass flow meter readings. This technology is digitizing documentation workflows that previously required manual paper trails and port authority stamping, compressing berth turnaround times at Singapore and Rotterdam.
The EU FuelEU Maritime regulation imposes well-to-wake carbon intensity benchmarks on vessel energy consumption starting in 2025. Shipowners operating between EU ports must document greenhouse gas emissions per megajoule, redirecting procurement toward bio-distillate blends and synthetic e-fuels. Deep-sea container routes from Asia to Northern Europe face the steepest compliance cost escalation, accelerating contracting for certified lower-carbon MGO variants.
Long-term offtake agreements are displacing spot bunker purchases among cruise operators and ferry companies. Carnival Corporation and Royal Caribbean have signed multi-year supply contracts with fixed pricing mechanisms and guaranteed sulfur specifications, replacing the traditional port-by-port spot market. Mediterranean and Caribbean cruise homeports exhibit the most pronounced contract concentration, as operators seek budget predictability for fuel expenditure planning.
Marine Gas Oil Market Segmentation
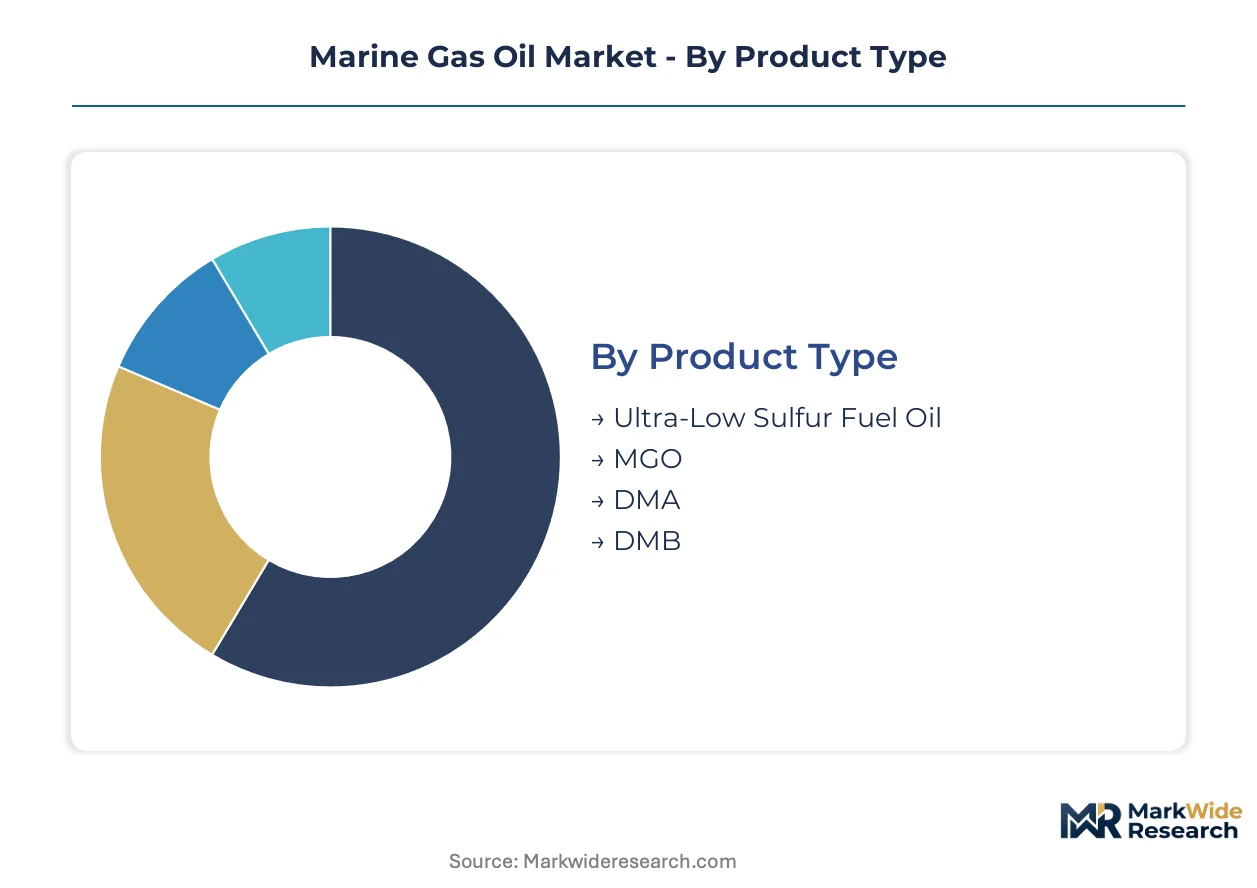
Segmentation in marine gas oil procurement reveals how fuel specification, vessel type, and delivery mechanism each impose distinct margin structures and contract cadences. Understanding these divisions exposes where capital concentrates and where operational complexity creates pricing power.
Product Type:
Cycle times vary sharply across fuel grades, with residual-derived products turning over in bulk arbitrage windows while distillate specifications lock in quarterly contract rhythms.
- Ultra-Low Sulfur Fuel Oil:A residual fuel processed to 0.50% sulfur maximum through vacuum gas oil blending or hydrocracking, supplying bulk carriers and tankers operating without scrubber installations. Demand concentrates at Singapore and Rotterdam where IMO 2020 compliance inventories require deep storage capacity and rapid barge turnaround.
- MGO:The 0.10% sulfur distillate meeting ISO 8217 DMA specifications, refined through hydrotreating middle distillate streams for medium-speed engine compatibility. Ferry operators and cruise lines in the Mediterranean and Baltic ECA zones specify MGO for auxiliary power and cold-start reliability where exhaust treatment systems remain uneconomical.
- DMA:A lighter distillate fraction with stricter density and viscosity limits than standard MGO, specified for high-speed diesel engines in pilot boats and harbor craft. Port authorities in Hamburg and Antwerp mandate DMA for municipal vessel fleets under local air quality ordinances.
- DMB:A marine diesel blend permitting trace residual content up to ISO 8217 limits, bridging cost gaps between pure distillates and ULSFO. Coastal bulk operators in the US Gulf and Indian west coast specify DMB for short-haul routes where engine tolerance allows marginal sulfur elevation.
Ultra-Low Sulfur Fuel Oil dominates installed base. MGO is where expansion concentrates.
End User:
Customer scale determines procurement leverage, with fleet operators commanding volume discounts while fragmented segments absorb spot market volatility.
- Shipping Companies:Container lines and tanker operators negotiating annual offtake agreements with fixed sulfur specifications and credit terms extending 60-90 days. Maersk and MSC anchor demand through integrated procurement desks that bypass traditional bunker brokers.
- Fishing Vessels:Artisanal and industrial fleets operating on thin fuel margins, purchasing MGO through port cooperative associations in Spain, Thailand, and Peru where seasonal catch cycles create lumpy demand patterns.
- Offshore Industry:Drilling contractors and platform supply vessel operators facing strict NOx and sulfur limits in Norwegian and UK North Sea waters. Seadrill and Transocean specify MGO for dynamic positioning systems where fuel interruption risks catastrophic station-keeping failure.
- Yachts:Superyacht captains prioritizing fuel cleanliness and cetane stability over unit cost, sourcing through yacht management agencies in Monaco, Fort Lauderdale, and Palma de Mallorca with white-glove delivery protocols.
Shipping Companies command procurement volume. Offshore Industry is climbing the fastest on regulatory tightening.
Distribution Channel:
Channel selection reflects vessel size and route predictability, with scheduled services consolidating through direct supply while tramp trades fragment across intermediaries.
- Direct Sales:Major container lines contracting refinery-direct supply through Rotterdam, Singapore, and Fujairah storage terminals, eliminating broker margins and securing priority barge allocation during port congestion.
- Bunkering Services:Physical supply operators including fuel barges, shore pipelines, and truck deliveries coordinated through port authority scheduling systems. Singapore's licensed bunker suppliers handle over 90% of the port's MGO volume through just-in-time barge matching.
- Online Platforms:Digital procurement portals enabling spot price discovery and contract execution without voice broker intermediation. Startups in Singapore and Hamburg are disintermediating traditional bunker trading desks for mid-size tramp operators.
- Distributors:Regional fuel resellers aggregating small-lot demand from fishing fleets, coastal ferries, and workboats in secondary ports lacking direct refinery access. Greek and Turkish distributors dominate Eastern Mediterranean MGO wholesaling.
Bunkering Services anchors physical delivery infrastructure. Online Platforms are gaining share fastest on transparency demands.
Application:
Application segmentation tracks voyage profile and regulatory exposure, with deep-sea routes facing fuelEU carbon intensity rules while coastal operations navigate ECA sulfur limits.
- Commercial Shipping:Deep-sea container, bulk, and tanker operations consuming 85% of marine gas oil volumes through main engine combustion and auxiliary power generation. Asia-Europe and Trans-Pacific routes face steepest carbon intensity compliance costs under EU FuelEU Maritime benchmarks.
- Recreational Boating:Marina fueling for pleasure craft and charter fleets, prioritizing low aromatic content and visual clarity over thermal efficiency. Mediterranean and Caribbean homeports specify detergent-additized MGO to prevent injector fouling in intermittently operated engines.
- Offshore Exploration:Drilling rig power generation and platform supply vessel propulsion in frontier basins from Guyana to Mozambique. Local content rules in Brazil and Nigeria mandate domestic fuel sourcing that disrupts integrated supply chain economics.
- Cargo Transport:Short-sea and feeder vessel operations linking deep-sea hubs to regional ports, operating on tight fuel cost margins that favor ULSFO-MGO blending strategies. Baltic and North Sea feeder operators face overlapping ECA and EU ETS compliance layers.
Commercial Shipping dominates installed base. Offshore Exploration is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and FuelEU Maritime initiative redirect procurement toward lower-carbon distillate blends across major bunkering hubs. Singapore, Rotterdam, and Fujairah anchor physical supply infrastructure. Regulatory enforcement varies sharply by coastline.
Singapore
Port Authority licensing requirements enforce strict mass flow meter standards on bunker barges operating within Jurong Island tank farm zones. The Maritime and Port Authority of Singapore mandates real-time fuel quality verification through digital delivery notes. Over 60% of Asia-Pacific MGO inventory concentrates here, creating single-point vulnerability to tropical weather disruptions.
Netherlands
Rotterdam's integrated refining and storage complex processes low-sulfur crude streams for EU ETS compliance. The EU FuelEU Maritime regulation imposes well-to-wake carbon intensity benchmarks starting in 2025. Maasvlakte terminals handle blended bio-distillate offtake agreements with container lines operating Asia-Europe routes.
United States
EPA Emission Control Area designations along Atlantic and Pacific coastlines compel 0.10% sulfur MGO combustion for coastal shipping. The Clean Air Act restricts fuel sulfur content within ECAs extending 200 nautical miles offshore. Los Angeles and Long Beach port clusters face overlapping California Air Resources Board scrubber bans and state-level low-carbon fuel standards.
United Arab Emirates
Fujairah's strategic location outside the Strait of Hormuz attracts very large crude carrier traffic requiring compliant distillate bunkering. The UAE's national oil company controls terminal infrastructure serving Indian Ocean and East African trade lanes. Port authority enforcement actions on fuel quality specifications intensified following IMO 2020 implementation.
Norway
North Sea drilling contractors face tightening local sulfur and NOx limits mandating MGO for platform supply vessels. The Norwegian Maritime Authority enforces stringent emissions rules within territorial waters covering offshore exploration zones. Stavanger and Bergen serve as procurement hubs for drilling rig operations in the Norwegian Continental Shelf.
Marine Gas Oil Market Competitive Landscape
On the supply side, the industry is consolidating around integrated energy majors with captive refining capacity and independent bunkering specialists with hub-specific storage advantages. Strategic archetypes include vertically integrated oil majors controlling upstream crude access, regional bunkering operators with licensed port infrastructure, and digital platform intermediaries disintermediating traditional brokers. Competitive moves center on backward integration into low-sulfur crude processing and strategic terminal acquisitions along high-volume trade lanes.
Within the integrated major tier, Shell PLC and BP PLC exemplify archetypes combining refining scale with bunkering network density. ExxonMobil Corporation anchors the Asia-Pacific storage-terminal vector. These entities represent positioning patterns rather than definitive market shares, with each occupying distinct geographic and functional roles across the marine fuel supply chain.
| Leading Market Players |
|---|
| Shell PLC |
| BP PLC |
| TotalEnergies SE |
| ExxonMobil Corporation |
| Chevron Corporation |
| Gazprom Neft PJSC |
| PJSC Lukoil Oil Company |
| Bomin Bunker Fuel Holding GMBH & Co. KG |
| Clipper Oil |
| Others |
Supply & Pricing Matrix
Asia-Europe container routes anchor marine gas oil cost dynamics, with Singapore-Jurong Island storage concentration amplifying supplier pricing power while Rotterdam's bio-distillate blending capacity creates premium tier differentiation for EU FuelEU Maritime compliance.
Pricing Analysis
ISO 8217 certification grade creates the primary spread between DMA, DMB, and residual-permitted blends, with sulfur content thresholds of 0.10% and 0.50% stratifying contract premiums. Long-term offtake agreements dominate commercial shipping procurement, while spot barge purchases concentrate among fishing fleets and coastal feeders absorbing Brent-Dubai volatility. Price compression runs through the ULSFO tier as scrubber payback timelines extend. Shipping companies exhibit lowest price sensitivity through volume leverage; artisanal fishing cooperatives face highest exposure to Singapore inventory fluctuations.
Supply Chain Analysis
Extended payment terms from integrated majors to independent bunkering operators compress working capital cycles across the supply chain. Refinery capacity concentrates in Singapore, the Netherlands, and the United Arab Emirates, with middle distillate hydrotreating units feeding MGO production. Crude sourcing draws from low-sulfur West African and North Sea grades, with vacuum gas oil blending streams bridging residual-distillate cost gaps. Single-point vulnerability sits with Jurong Island tank farm concentration exposed to tropical weather disruption. Distribution runs through licensed bunker barge fleets coordinated by port authority scheduling systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine gas oil procurement functions as a regulatory-moat business where MARPOL Annex VI enforcement and port authority licensing create entrenched supplier positions with steep switching costs for vessel operators.
For Market Incumbents: Harden terminal infrastructure control through strategic storage acquisitions at Fujairah and Murmansk, insulating against digital platform disintermediation. Deepen backward integration into low-sulfur crude processing capacity to capture refining margin compression when Brent-Dubai spreads widen. Prioritize bio-distillate blending certification for Rotterdam and Hamburg to secure EU Green Deal offtake agreements before 2025 carbon intensity benchmarks activate.
For New Entrants and Emerging Players: Arctic route bunkering infrastructure at Vladivostok and Norwegian North Sea supply bases represents the most penetrable entry point, as ice-class vessel traffic accelerates and incumbent storage networks remain underdeveloped. Digital barge-matching platforms for mid-size tramp operators in secondary Indian Ocean ports offer disintermediation leverage against established broker networks. Pursue certified bio-MGO supply partnerships with Baltic and North Sea ferry operators facing overlapping ECA and EU ETS compliance layers.
For Investors and Strategic Acquirers: Licensed port infrastructure operators with captive Jurong Island or Maasvlakte storage terminals present acquisition targets with irreplaceable regulatory entitlements and physical moats. Long-term viability hinges on FuelEU Maritime carbon intensity benchmark enforcement and bio-distillate blend penetration rates. Monitor IMO MEPC deliberations on well-to-wake accounting rules as the inflection signal for synthetic e-fuel substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Scrubber Retrofit Financing | Project finance structures extend capital recovery timelines as open-loop bans proliferate in California and Singapore ports. |
| Bio-Distillate Blending Certification | FAME and HVO offtake agreements with Rotterdam suppliers secure EU Green Deal compliance positioning. |
| Digital Delivery Note Systems | Blockchain-based sulfur verification compresses berth turnaround times at Singapore and Rotterdam. |
| Arctic Storage Terminal Development | Murmansk and Vladivostok infrastructure captures Northern Sea Route ice-class vessel procurement demand. |
| Dual-Fuel Engine Pilot Fuel Contracts | Wärtsilä and MAN Energy Solutions retrofits preserve MGO demand as LNG-methanol backup fuel. |
Research Methodology
Operator-level perspectives from vessel fleet managers, bunker procurement officers, refinery planning executives, and port authority licensing administrators anchored the qualitative base. Primary interviews triangulated against customs trade data, MARPOL Annex VI enforcement records, SEC 10-K filings from integrated energy majors, and IMO marine fuel quality dispute databases. Bottom-up segmentation modeling across product grades, end-user categories, and distribution channels converged with top-down macroeconomic and regulatory scenario analysis.
Scenario-bracketing around IMO sulfur cap enforcement timelines, EU FuelEU Maritime carbon intensity phase-ins, and scrubber payback compression bounds anchored the projection framework. Segmentation dimensions spanned ISO 8217 fuel specifications, vessel type procurement leverage, and bunkering hub regulatory intensity. CAGRs derived from refinery capacity utilization trends, distillate crack spread elasticity, and ECA zone geographic expansion patterns across the modeling period. Fleet composition shifts toward dual-fuel engine installations and bio-distillate blend penetration rates supplied industry-specific forecast inputs.
Practitioners should monitor IMO MEPC regulatory amendments, EU carbon border adjustment mechanisms, and Singapore port authority enforcement actions for early signals of forecast revision triggers. Projections reflect assumptions on sulfur cap continuity, biofuel certification standardization, and crude slate quality trends. Macroeconomic commodity volatility, unilateral scrubber ban proliferation, or breakthrough synthetic e-fuel cost parity would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Trim Tabs Market
Marine
Marine Propeller Market
Marine
Global Discount-Marine Trenchers Market
Marine
Europe Recreational Boating Market
Marine
Marine Bearings Market
Marine
Japan Marine Composites Market
Marine
Boat Hook Market
Marine
Marine Dynamic Positioning System Market
Marine
Marine VFD Market
Marine
Hydrogen Ships Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Pipes Market
Marine
US Fish Finders Market
Marine
Marine Fasteners Market
Marine
Marine Glass Market
Marine
Marine Transport Refrigeration Unit Market