
 GCC ROV Market | 2026-2036
GCC ROV Market Size, Share, and Industry Trends Forecast 2026-2036
GCC ROV Market Foresight
CE marking under the EU Marine Equipment Directive is decoupling equipment certification from vessel flag states across GCC offshore contracting. TechnipFMC PLC leverages integrated SURF-to-ROV service bundling across Saudi Aramco's megaproject pipeline. Oceaneering International Inc. sustains deepwater intervention capacity through its Middle East base in Dubai. Al Seer Marine anchors local fleet ownership, competing on proximity to Abu Dhabi offshore zones.
A remotely operated vehicle is a tethered underwater robot typically rated for depths exceeding 3,000 meters, equipped with manipulator arms, sonar arrays, and high-definition camera suites for subsea intervention tasks. Its primary purpose is to execute inspection, maintenance, and repair operations on subsea infrastructure without deploying human divers. Work-class ROVs command the largest capital deployment share given their hydraulic power and tooling payload capacity for drilling support. Inspection-class units represent the fastest-growing category as pipeline integrity management intensifies across aging Gulf of Mexico-linked systems and new Saudi fields. Observation-class systems occupy a mature niche, with margin pools compressing amid standardization of mini-ROV platforms.
ADNOC's In-Country Value program and Saudi Aramco's IKTVA framework are tightening local content thresholds for offshore service procurement, forcing foreign ROV operators into joint ventures with Emirati and Saudi entities. The UAE's national oil regulator and Saudi Arabia's Standards, Metrology and Quality Organization are converging on equipment qualification protocols that mirror NORSOK and API standards. Stakeholders must monitor how IKTVA credit weightings evolve for subsea robotics versus vessel chartering, as this determines whether operators deepen local assembly or retain offshore equipment staging in Singapore and Norway.
Market Dynamics
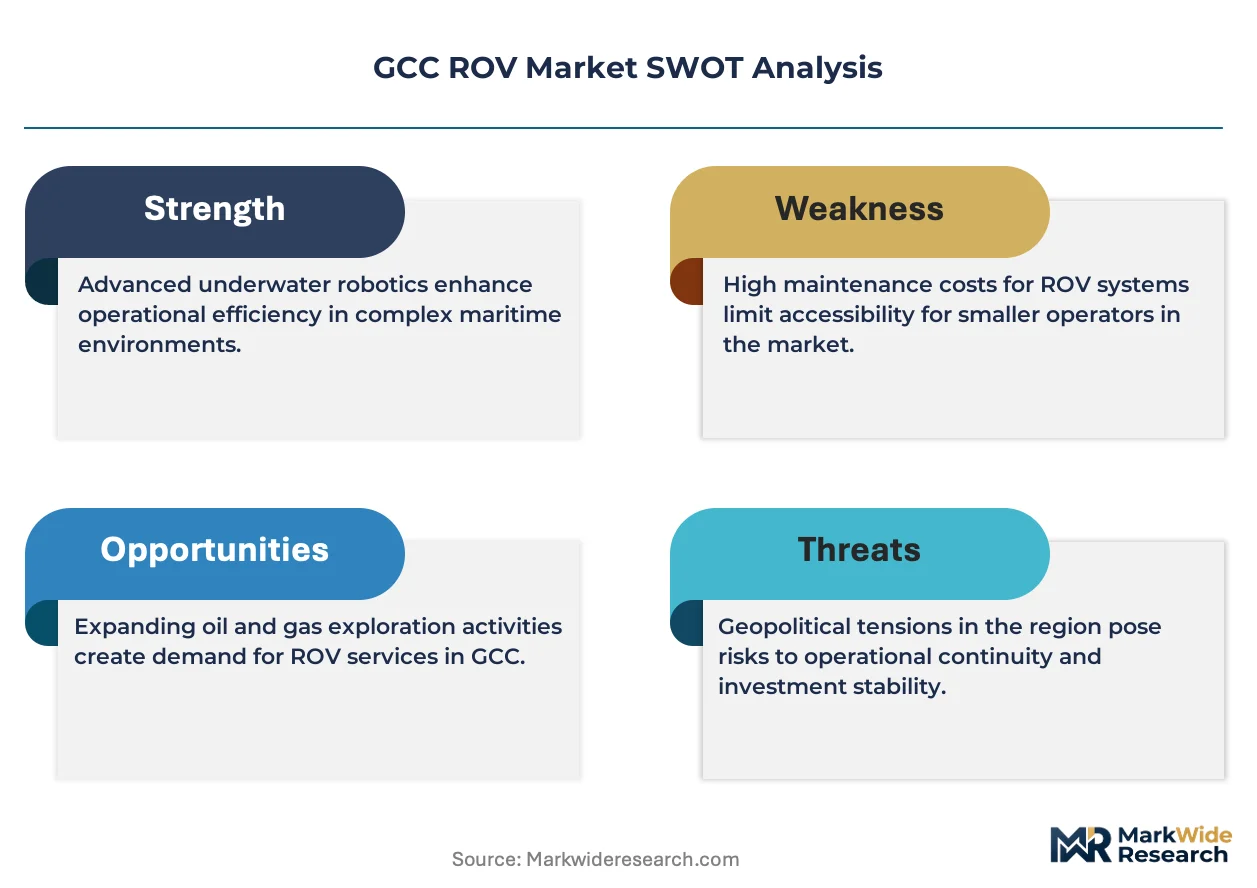
ADNOC's In-Country Value program and Saudi Aramco's IKTVA framework are forcing foreign ROV operators into joint ventures with Emirati and Saudi entities, restructuring procurement from equipment sales toward bundled service contracts.
Growth Catalysts
- Marjan and Zuluf field developments:Saudi Arabia's offshore megaprojects are generating concentrated demand for work-class ROV systems capable of drilling support and subsea construction at depths exceeding 1,500 meters.
- ADNOC In-Country Value mandates:Local content thresholds are redirecting capital toward Emirati joint ventures, creating captive demand for regionally assembled ROV fleets and maintenance infrastructure.
- Electrification of hydraulic power systems:Battery-powered work-class ROVs are reducing topside generator requirements and enabling longer-duration interventions on subsea tiebacks.
Market Restraints
- High-grade steel and titanium alloy costs:Pressure-rated hull materials face volatile pricing from concentrated Asian smelter supply, compressing margins on newbuild ROV fabrication.
- NORWAY-SINGAPORE EQUIPMENT STAGING:Foreign operators retain critical spare inventory outside GCC customs zones, creating logistics friction and extended mobilization timelines for urgent interventions.
- Tether management system complexity:Dynamic positioning of umbilical cables in high-current Gulf waters limits operational windows and increases vessel-day costs.
Strategic Opportunities
- Kuwait and Bahrain offshore zones:These underdeveloped maritime territories lack dedicated ROV service bases, creating first-mover advantage for contractors establishing local staging.
- Autonomous underwater vehicle convergence:Hybrid ROV-AUV architectures are opening inspection missions previously uneconomical for fully tethered systems.
- Saudi Standards, Metrology and Quality Organization alignment:Equipment qualification protocols mirroring API and NORSOK standards are streamlining certification for pre-qualified international suppliers.
Industry Challenges
- Pilot-technician certification pipelines:GCC maritime academies lack ROV-specific training modules, forcing contractors to import certified personnel from Aberdeen and Stavanger at premium rates.
- CE marking transition under EU Marine Equipment Directive:Equipment certification decoupled from vessel flag states is creating dual-track compliance obligations for contractors operating mixed-flag fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC ROV Market |
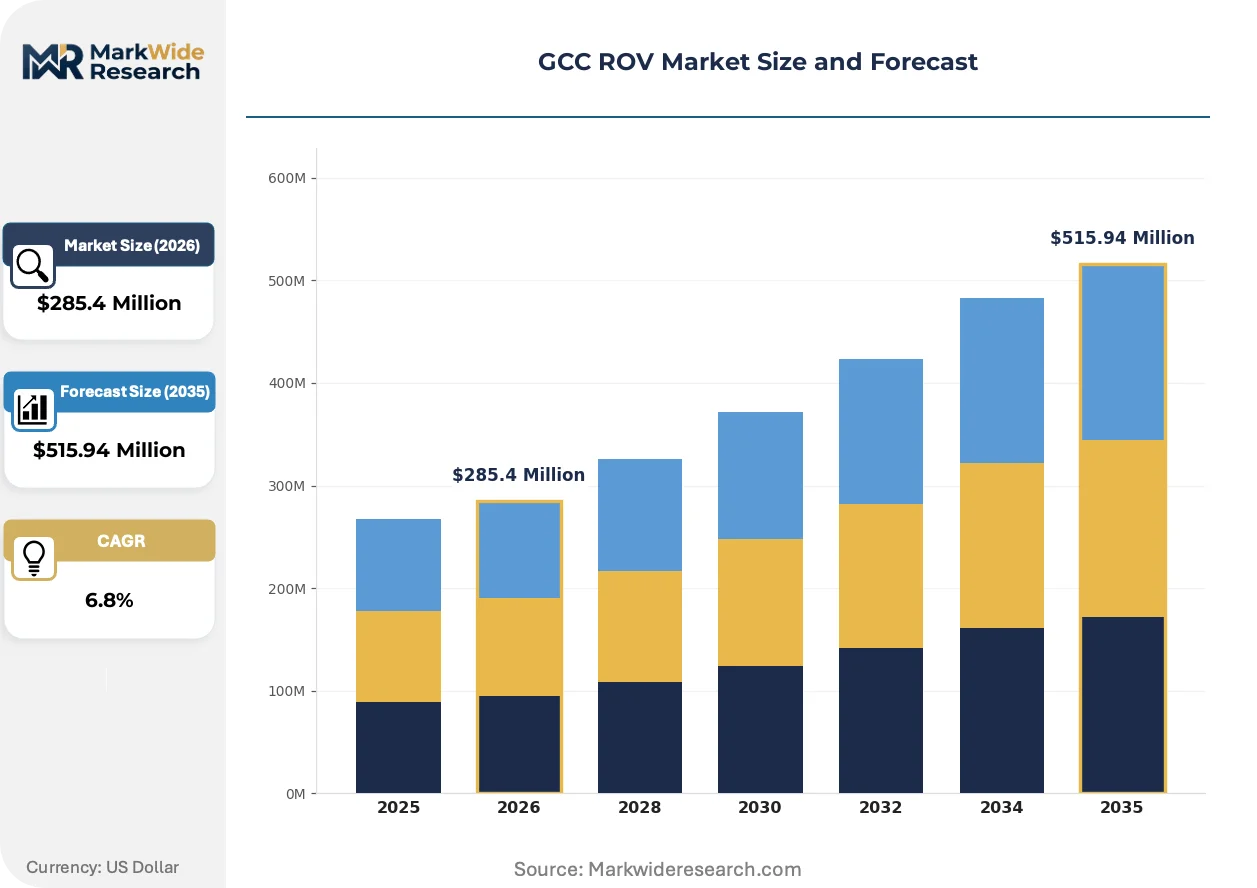
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Work Class, Inspection Class, Observation Class, Heavy Duty, Medium Duty Application: Subsea Inspection, Underwater Construction, Pipeline Maintenance, Environmental Monitoring, Salvage Operations Deployment: Offshore Oilfields, Subsea Installations, Deepwater Exploration, Underwater Research Stations, Marine Conservation Sites End User: Energy Exploration Firms, Marine Research Institutes, Offshore Engineering Contractors, Salvage Companies |
| Companies Covered | Subsea 7 SA, TechnipFMC PLC, ROVOP, Fugro NV, Forum Energy Technologies Inc., Oceaneering International Inc., Saipem S.p.A., Al Seer Marine, DeepOcean, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC ROV Market Shifts & Advancements
Subsea robotics is experiencing rapid capability convergence as electrification, autonomous navigation, and local content mandates simultaneously reshape equipment specifications and contracting structures across Arabian Gulf operations.
Electrification of work-class propulsion is electrifying conventional hydraulic architectures across Saudi Aramco's contractor fleet. Oceaneering and TechnipFMC are retrofitting existing vehicles with battery-electric powertrains to reduce topside footprint and enable all-electric vessel configurations. This shift is electrifying the competitive landscape by favoring contractors with in-house electrical engineering over pure mechanical specialists.
Saudi Arabia's Standards, Metrology and Quality Organization is converging equipment qualification protocols with API and NORSOK standards, eliminating redundant testing for pre-certified international suppliers. The industrial consequence is accelerated equipment import timelines for established players while raising barriers for uncertified entrants. Work-class system manufacturers with existing API Q1 certification are capturing preferred vendor status in Aramco's megaproject pipeline.
Service bundling is compressing standalone equipment rental margins as operators demand integrated SURF-to-ROV packages. Abu Dhabi National Oil Company's procurement teams are consolidating subsea construction, inspection, and intervention under single-contractor accountability, displacing fragmented vendor relationships. This concentration is most visible in UAE offshore zones where ADNOC's local content weightings favor vertically capable service providers over pure ROV operators.
GCC ROV Market Segmentation
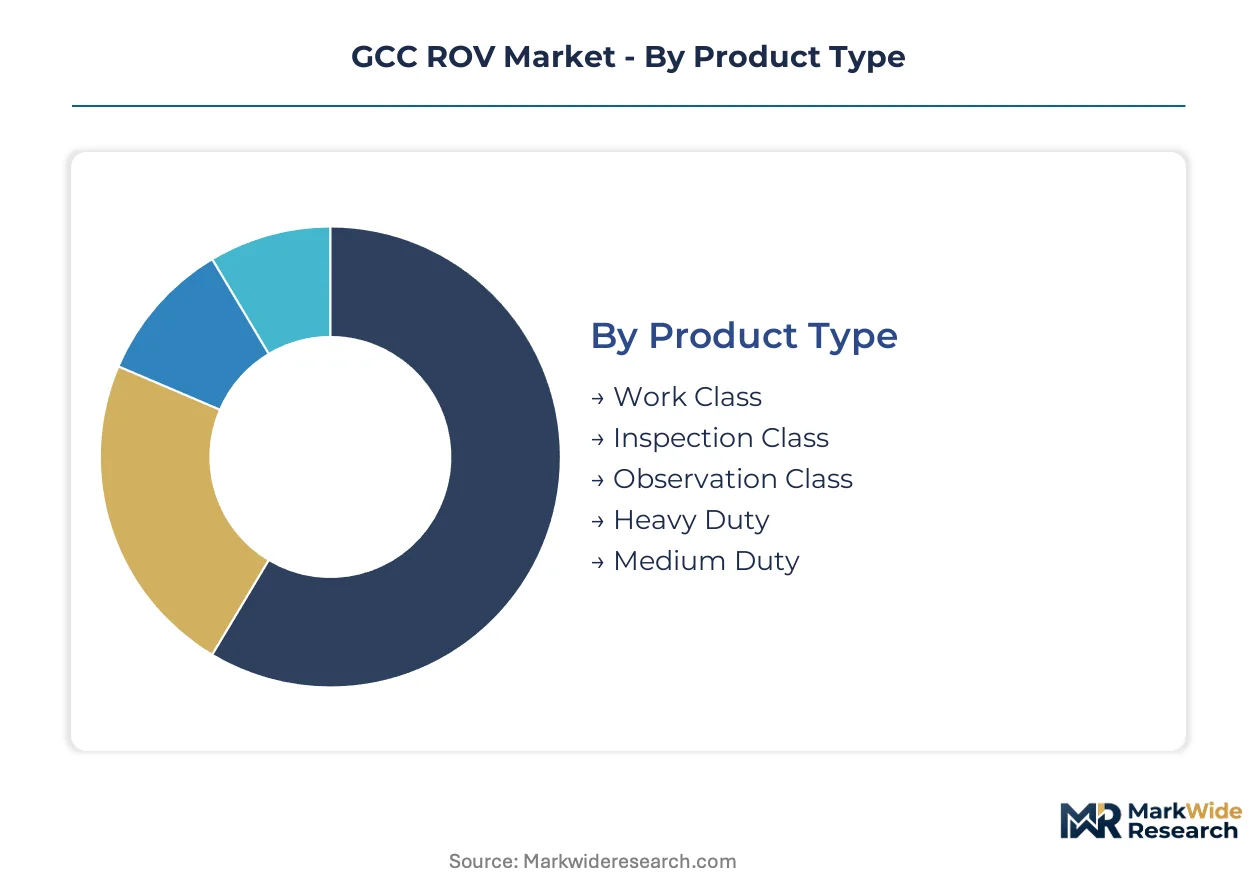
ROV procurement across the GCC divides sharply between capital-heavy work-class systems and lighter inspection platforms, with Saudi Aramco's megaproject pipeline dictating which configurations absorb the majority of regional fleet investment. Understanding these segment boundaries clarifies where contractors must anchor technical capabilities versus where standardization permits equipment pooling.
Product Type:
Work-class systems demand the heaviest upfront capital outlay given hydraulic power trains, pressure-rated hull fabrication, and integrated tooling skids that can exceed several million dollars per unit.
- Work Class:These vehicles deploy hydraulic manipulator arms and heavy-lift tooling for drilling support and subsea construction at depths exceeding 1,500 meters. Saudi Arabia's Marjan and Zuluf field developments are concentrating demand for units with 250+ horsepower propulsion and seven-function manipulators capable of BOP intervention.
- Inspection Class:Battery-electric architectures dominate this category, with reduced topside generator requirements enabling longer-duration pipeline surveys. ADNOC's integrity management mandates across aging Gulf of Mexico-linked infrastructure are accelerating procurement of sensor-rich platforms with multibeam sonar and laser scanning payloads.
- Observation Class:Mini-ROV platforms with miniaturized camera suites and limited tooling capacity serve routine visual surveys where hydraulic power is unnecessary.
- Heavy Duty:Specialized frames accommodate custom tooling for subsea structure installation and decommissioning tasks beyond standard work-class ratings.
- Medium Duty:Intermediate payload capacity fills gaps between inspection-class agility and full work-class power for light intervention work.
Most installed capacity flows through Work Class systems given Saudi megaproject scale. Expansion is steepest in Inspection Class as electrification and autonomous navigation reduce per-survey costs.
Application:
Application segmentation tracks how ROV capabilities map to specific task economics, with bundled service contracts increasingly spanning multiple mission types under single-vendor accountability.
- Subsea Inspection:Pipeline integrity surveys, platform structural assessments, and cathodic protection monitoring constitute the highest-frequency deployment category across UAE and Saudi offshore zones.
- Underwater Construction:Manipulation-intensive tasks including cable lay support, template installation, and subsea tieback connection absorb the greatest vessel-day volumes in Saudi Arabia's field development pipeline.
- Pipeline Maintenance:Repair campaigns on aging infrastructure require work-class intervention capacity with hot tap and clamp installation tooling.
- Environmental Monitoring:Regulatory compliance surveys for marine ecosystem impact assessment deploy observation-class and inspection-class platforms with water quality sensors.
- Salvage Operations:Wreck recovery and debris clearance missions demand heavy-lift configurations with specialized rigging interfaces.
Subsea Inspection commands the largest vessel-day totals. Underwater Construction is climbing fastest as Saudi Aramco's megaproject timeline accelerates.
Deployment:
Deployment settings determine pressure rating requirements, tether management complexity, and logistics infrastructure needs, with deepwater specifications commanding substantial cost premiums.
- Offshore Oilfields:Fixed and floating production facilities across Saudi Arabia's Arabian Gulf and Red Sea zones generate routine inspection and intervention demand with established supply chain corridors.
- Subsea Installations:Manifold, tieback, and riser systems require work-class ROV support for commissioning, maintenance, and emergency response with rapid mobilization protocols.
- Deepwater Exploration:Pre-salt and ultra-deepwater frontiers beyond 1,500 meters impose the most stringent pressure vessel and dynamic positioning requirements.
- Underwater Research Stations:Scientific installations deploy observation-class platforms for marine biology and geology data collection.
- Marine Conservation Sites:Protected area monitoring uses low-disturbance electric vehicles for ecosystem baseline surveys.
Offshore Oilfields anchor regional fleet utilization. Deepwater Exploration is expanding most quickly as ADNOC and Saudi Aramco push into pre-salt frontiers.
End User:
End-user segmentation reveals procurement concentration among integrated energy companies and their tier-one contractors, with research and salvage operators occupying niche volume positions.
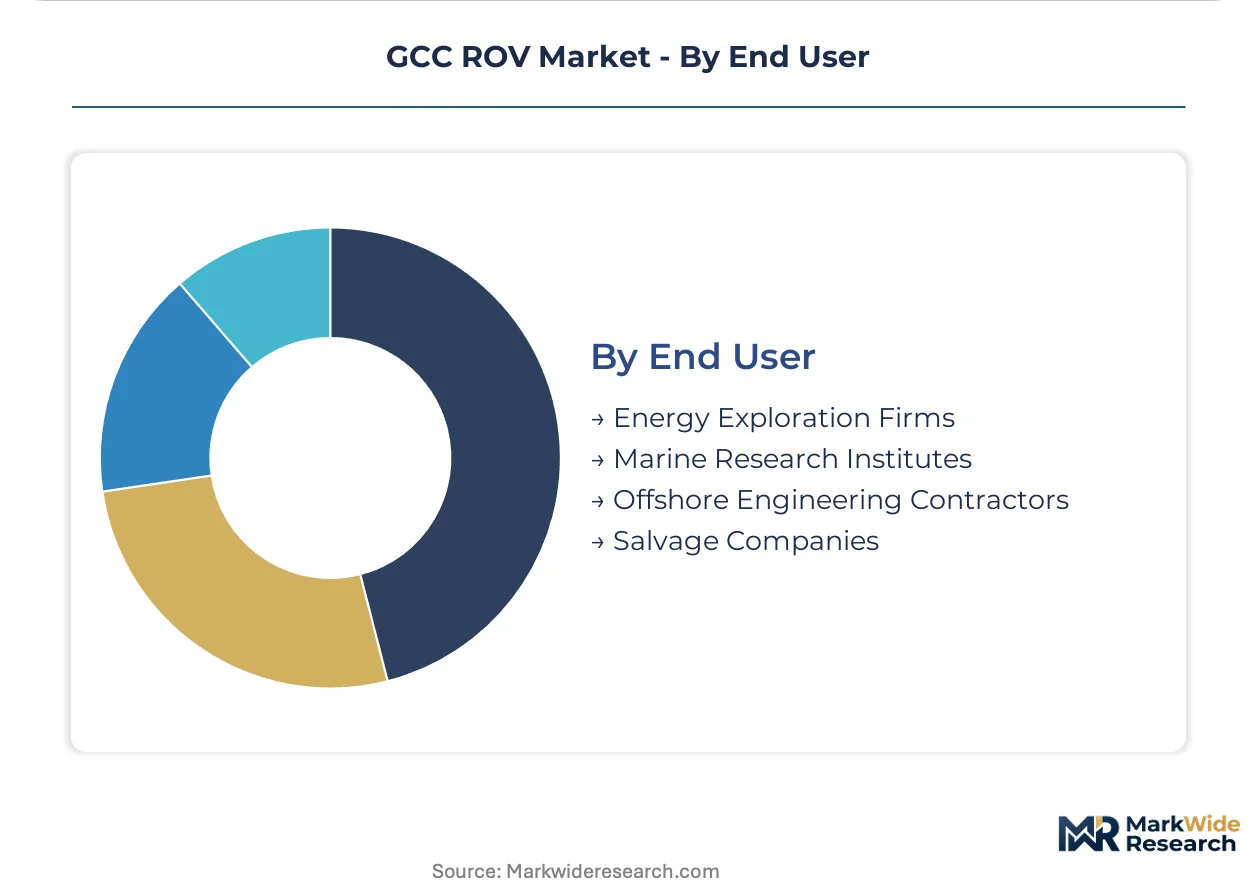
- Energy Exploration Firms:Saudi Aramco and ADNOC directly charter ROV services through long-term agreements that bundle vessels, personnel, and equipment under unified performance metrics.
- Offshore Engineering Contractors:TechnipFMC and similar integrated service providers maintain captive ROV fleets to deliver SURF-to-ROV packages under single-contractor accountability structures.
- Marine Research Institutes:Universities and government oceanographic agencies deploy observation-class systems for benthic habitat mapping and climate research.
- Salvage Companies:Specialized wreck recovery operators maintain heavy-duty configurations for emergency response and contracted clearance missions.
Energy Exploration Firms absorb the dominant share of regional ROV vessel-days. Offshore Engineering Contractors are gaining procurement influence as bundled service models displace fragmented vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ROV pilot-technicians cluster around Aberdeen and Stavanger supply corridors, creating talent pipelines that foreign contractors must tap for Gulf operations. This workforce concentration shapes how Saudi Aramco and ADNOC structure their local content mandates.
Saudi Arabia
Marjan and Zuluf field developments absorb the majority of regional work-class ROV procurement. Saudi Aramco's IKTVA framework mandates joint ventures with Saudi entities for offshore service contracts. Dhahran and Jubail industrial zones host emerging ROV maintenance and assembly facilities serving Red Sea and Arabian Gulf operations.
United Arab Emirates
ADNOC's In-Country Value program redirects capital toward Emirati-controlled joint ventures for subsea construction. MOHAP equipment registration requirements align with API standards for streamlined import. Abu Dhabi and Dubai offshore zones concentrate fleet staging, with Al Seer Marine anchoring local ownership models.
Kuwait
Offshore exploration in the Divided Zone generates nascent demand for inspection-class systems. The country's national oil regulator lacks dedicated ROV service base infrastructure. First-mover contractors establishing local staging capture emerging vessel-day volumes before regional competitors mobilize from UAE bases.
Qatar
North Field expansion projects require deepwater intervention capacity beyond 1,500 meters. Local content thresholds remain less prescriptive than Saudi or Emirati frameworks. Ras Laffan industrial city hosts limited subsea robotics infrastructure, forcing reliance on Doha-based contractors with cross-border UAE supply chains.
Bahrain
Small-scale offshore development creates niche demand for observation-class platforms. The absence of dedicated ROV service infrastructure forces complete reliance on Saudi or UAE-based mobilization. Manama-based engineering consultancies coordinate subcontractor relationships rather than maintaining captive fleet capacity.
GCC ROV Market Competitive Landscape
The competitive structure tilts toward integrated service bundling over standalone equipment rental. Foreign operators face consolidation pressure as ADNOC and Saudi Aramco consolidate procurement under single-contractor accountability. Three archetypes dominate: European engineering conglomerates with SURF-to-ROV integration, Gulf-based local content joint ventures, and specialist deepwater intervention contractors. Capacity expansion and strategic partnerships constitute the primary competitive moves, with electrification retrofitting emerging as a secondary capability differentiator.
Among European-integrated service providers, TechnipFMC PLC and Subsea 7 SA exemplify the bundled contracting archetype that ADNOC procurement teams increasingly favor. Oceaneering International Inc. occupies a position within the specialist tier, anchoring deepwater intervention capacity through its Middle East operational base. These three entities represent how foreign operators navigate local content mandates through joint venture structures rather than direct market entry.
| Leading Market Players |
|---|
| Subsea 7 SA |
| TechnipFMC PLC |
| ROVOP |
| Fugro NV |
| Forum Energy Technologies Inc. |
| Oceaneering International Inc. |
| Saipem S.p.A. |
| Al Seer Marine |
| DeepOcean |
| Others |
Supply & Pricing Matrix
Sovereign-backed national oil companies anchor procurement decisions across GCC offshore zones, compressing margins for foreign contractors while redirecting capital toward joint ventures with Emirati and Saudi entities. Their bundled service mandates reshape how equipment suppliers price work-class systems against inspection-class alternatives.
Pricing Analysis
Bundled SURF-to-ROV service contracts dominate procurement, displacing standalone equipment rental models as ADNOC and Saudi Aramco consolidate vendor accountability. Price differentiation separates API Q1-certified work-class systems from uncertified alternatives, with electrification retrofits commanding modest premiums over hydraulic legacy fleets. Pricing pressure stems from high-grade steel and titanium alloy volatility, squeezing fabrication margins on newbuild pressure-rated hulls. National oil company procurement teams exhibit lowest price sensitivity for deepwater intervention capacity, while observation-class mini-ROV segments face commoditization.
Supply Chain Analysis
Refurbishment flows for tether management systems and hydraulic power units concentrate in Singapore and Norway, creating reverse-logistics dependencies that extend mobilization timelines for urgent Gulf interventions. Critical component fabrication draws from South Korea, Japan, and Germany for pressure-rated hull materials and precision-machined manipulator assemblies. Supply chain risk centers on single-source vulnerability for high-grade titanium alloy from concentrated Asian smelter capacity. Distribution runs through Dubai and Abu Dhabi staging hubs for UAE offshore zones, with Dhahran and Jubail emerging for Saudi Red Sea and Arabian Gulf operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC ROV market compounds returns through regulatory layering, as Saudi Aramco's IKTVA framework and ADNOC's In-Country Value program continuously tighten local content thresholds for offshore service procurement.
For Market Incumbents: To counter electrification disruption from battery-electric retrofit specialists, European engineering conglomerates should deepen captive assembly partnerships in Dhahran industrial zones and accelerate API Q1 certification pipelines for pre-qualified supplier status. Joint venture structures with Al Seer Marine and similar Emirati fleet owners defend procurement access against pure-technology entrants lacking local content credits. For New Entrants and Emerging Players: Battery-electric powertrain retrofits for existing hydraulic work-class fleets offer a technology-first wedge into Saudi Aramco's contractor ecosystem. Kuwait's Divided Zone and Bahrain's undeveloped offshore territories present white-space targets lacking dedicated ROV service infrastructure. A first-mover staging base in Manama or Kuwait City, paired with rapid mobilization protocols from UAE supply chains, captures emerging vessel-day volumes before regional incumbents reposition. For Investors and Strategic Acquirers: Valuations sit cheapest among inspection-class specialists with electrification IP but limited Gulf joint venture coverage, as bundled procurement favors vertically integrated SURF-to-ROV providers. Long-term viability hinges on 5-10 year regulatory trajectory rather than near-term fleet utilization. Watch IKTVA credit weighting shifts for subsea robotics versus vessel chartering as the inflection signal determining whether operators deepen local assembly or retain offshore equipment staging outside GCC customs zones.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation with Local Partners | IKTVA and In-Country Value compliance unlocks Saudi Aramco and ADNOC megaproject access. |
| Battery-Electric Retrofit Program | Electrification reduces topside generator footprint for all-electric vessel configurations. |
| API Q1 Certification Investment | Pre-qualified supplier status accelerates equipment import timelines for Aramco pipeline. |
| Kuwait Service Base Establishment | First-mover staging captures Divided Zone vessel-days before UAE-based competitors mobilize. |
| Pilot-Technician Training Pipeline | GCC maritime academy partnerships reduce premium dependency on Aberdeen and Stavanger talent. |
Research Methodology
Bottom-up offshore engineering contractor modeling reconciled against top-down ROV fleet capacity tracking forms the analytical core of this study. Primary interviews with subsea project managers, procurement leads at national oil companies, ROV pilot-technicians, and vessel chartering specialists combined with secondary validation from customs records, SEC filings of listed service providers, and offshore project development databases. Triangulation across stakeholder inputs and trade data ensures statistical integrity.
Historical trendline analysis of work-class and inspection-class deployment ratios informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, application mission profile, deployment depth specification, and end-user procurement structure. CAGRs derived from equipment import velocity, vessel-day utilization rates, and megaproject commissioning timelines. Forecast inputs incorporate electrification adoption curves and local content mandate enforcement intensity.
The model holds under sustained IKTVA and In-Country Value enforcement; deviation in regulatory credit weightings or titanium alloy supply disruptions would shift equipment staging location preferences and margin structures. Practitioners should monitor Saudi Standards, Metrology and Quality Organization alignment announcements and ADNOC procurement consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sailboat Market
Marine
Ship/Boat Keel Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Electric Ferry Market
Marine
Marine Pipes Market
Marine
Marine Winch Motors Market
Marine
Global Submarine Market
Marine
Autonomous Ships Market
Marine
Europe ROV Market
Marine
Jet Boat Market
Marine
Shipbuilding Market
Marine
Marine Communication Market
Marine
Marine Auxiliary Engine Market
Marine
Flap Rudder Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Turbocharger Market