
 Marine Communication Market | 2026-2036
Marine Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Communication Market Outlook
Copper coaxial cable is decoupling from vessel antenna backhaul as fiber-optic and hybrid RF-over-fiber architectures cut signal loss across superstructures. Iridium Communications leverages its L-band satellite constellation to dominate polar-route shipping lanes where geostationary coverage fails. Cobham SATCOM anchors its position through in-house production of stabilized VSAT terminals for military and commercial hulls. Intellian Technologies differentiates via multi-orbit antenna systems that track both geostationary and low-earth-orbit constellations from a single radome.
Marine communication encompasses the transmission of voice, data, and distress signals between vessels, shore stations, and satellites operating across VHF (156-174 MHz), MF/HF, and Ku/Ka-band satellite frequencies, with equipment engineered to withstand salt corrosion, vibration, and temperature extremes from equatorial to polar environments. Satellite Communication commands the largest revenue pool among product types as fleet operators replace legacy Inmarsat-B terminals with flat-panel electronically steered arrays. Digital Communication technology is displacing analog radio in commercial shipping as SOLAS-mandated GMDSS upgrades force bridge electronics refreshes. Search and Rescue applications attract premium pricing due to regulatory mandates for EPIRB and SART carriage on all cargo vessels over 300 gross tons.
The International Maritime Organization (IMO) shapes equipment demand through SOLAS Chapter IV radiocommunication requirements, while the FCC enforces spectrum licensing for U.S.-flagged vessels and the EU's Radio Equipment Directive (RED) governs CE marking for terminals sold into European waters. National regulators in Japan and South Korea are tightening type-approval timelines for next-generation satellite terminals, compressing product development cycles for manufacturers. Stakeholders must monitor spectrum reallocation decisions at WRC conferences and assess dual-orbit antenna investments before legacy L-band service sunsets accelerate.
Market Dynamics
Copper coaxial backhaul is decoupling from vessel antenna systems as fiber-optic and hybrid RF-over-fiber architectures cut signal loss across superstructures. This infrastructure transition is compressing installation timelines and reshaping procurement specifications for newbuild and retrofit fleets.
Growth Catalysts
- SOLAS Chapter IV mandates:The IMO's radiocommunication requirements force bridge electronics refreshes as GMDSS upgrades displace analog radio systems on commercial shipping.
- Offshore energy fleet expansion:North Sea operators are scaling connectivity requirements for drilling support vessels and floating production units.
- Polar route traffic:L-band satellite coverage gaps in Arctic corridors drive demand for specialized terminals among ice-class tankers and expedition cruise operators.
Market Restraints
- Stabilized VSAT terminal costs:Precision gyroscopic platforms and carbon-fiber radomes command premium pricing that constrains adoption among mid-size fishing fleets.
- Certification timeline compression:Japan and South Korea's national regulators are tightening type-approval windows for next-generation satellite equipment.
- Geostationary coverage limitations:High-latitude shipping lanes beyond orbital inclination limits remain underserved despite L-band alternatives.
Strategic Opportunities
- Multi-orbit antenna convergence:Single-radome systems tracking both geostationary and low-earth-orbit constellations open retrofit markets for legacy Inmarsat-B terminal replacements.
- Search and Rescue premium tiers:SOLAS-mandated EPIRB and SART carriage requirements on cargo vessels over gross tonnage thresholds create regulatory-anchored demand.
- EU Radio Equipment Directive alignment:CE marking harmonization for terminals entering European waters streamlines cross-border certification costs.
Industry Challenges
- Marine electronics technician scarcity:Specialized skills for Ku/Ka-band installation and salt-corrosion mitigation outpace vocational training pipeline output.
- Dual-orbit integration complexity:Antenna systems must synchronize tracking algorithms across constellation types without bridge crew intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Communication Market |
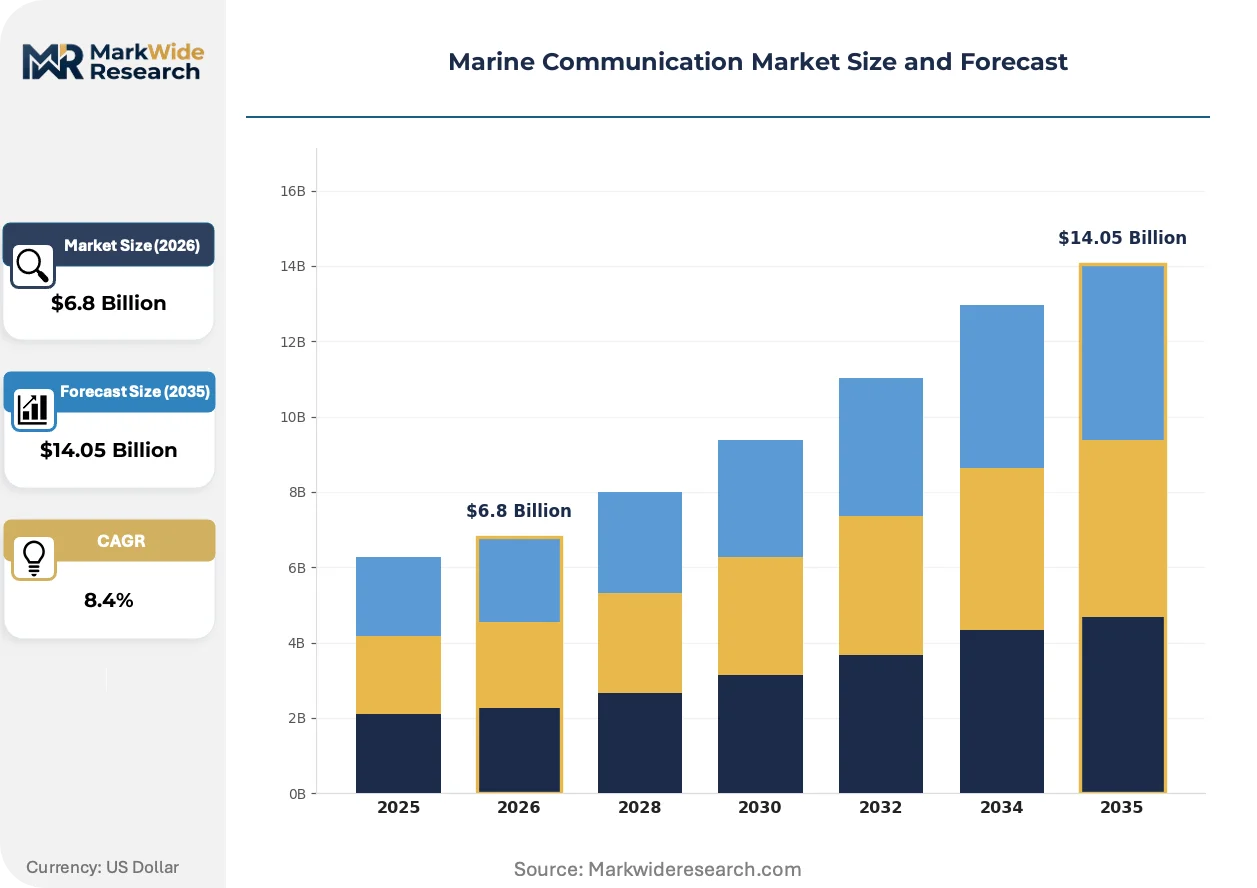
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VHF Radio, Satellite Communication, AIS, Intercom Technology: Radio Communication, Satellite-Based, Digital Communication, VoIP Application: Commercial Shipping, Navigation, Fishing, Search and Rescue End User: Shipping Companies, Fishing Operators, Coast Guard, Marine Services |
| Companies Covered | Iridium Communications, Inmarsat, Cobham SATCOM, Leonardo, Viasat, Intellian Technologies, Garmin Ltd., ST Engineering, KVH Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Communication Market Strategic Shifts
Flat-panel electronically steered arrays are displacing mechanically stabilized dishes across commercial and military hulls. This hardware transition is compressing form factors, reducing maintenance intervals, and enabling integration with bridge navigation systems.
Electronically steered arrays eliminate motorized azimuth-elevation platforms through solid-state beamforming. Container lines and cruise operators are specifying these terminals for newbuild contracts to reduce radar cross-section and eliminate moving parts. The technology is consolidating vendor portfolios around semiconductor-based solutions and marginalizing legacy parabolic suppliers.
The FCC enforces spectrum licensing for flagged vessels while the EU's Radio Equipment Directive governs CE marking for terminals entering European waters. This regulatory layering forces manufacturers to maintain parallel certification tracks. Military and dual-use hulls face additional encryption standards that commercial operators bypass.
Fleet operators are unbundling hardware procurement from airtime contracts. Large container lines now source antennas through separate RFP processes from bandwidth agreements, reversing the bundled model that dominated legacy Inmarsat relationships. This bifurcation is most visible among Asia-Pacific flagged operators with multi-thousand vessel fleets.
Marine Communication Market Segmentation
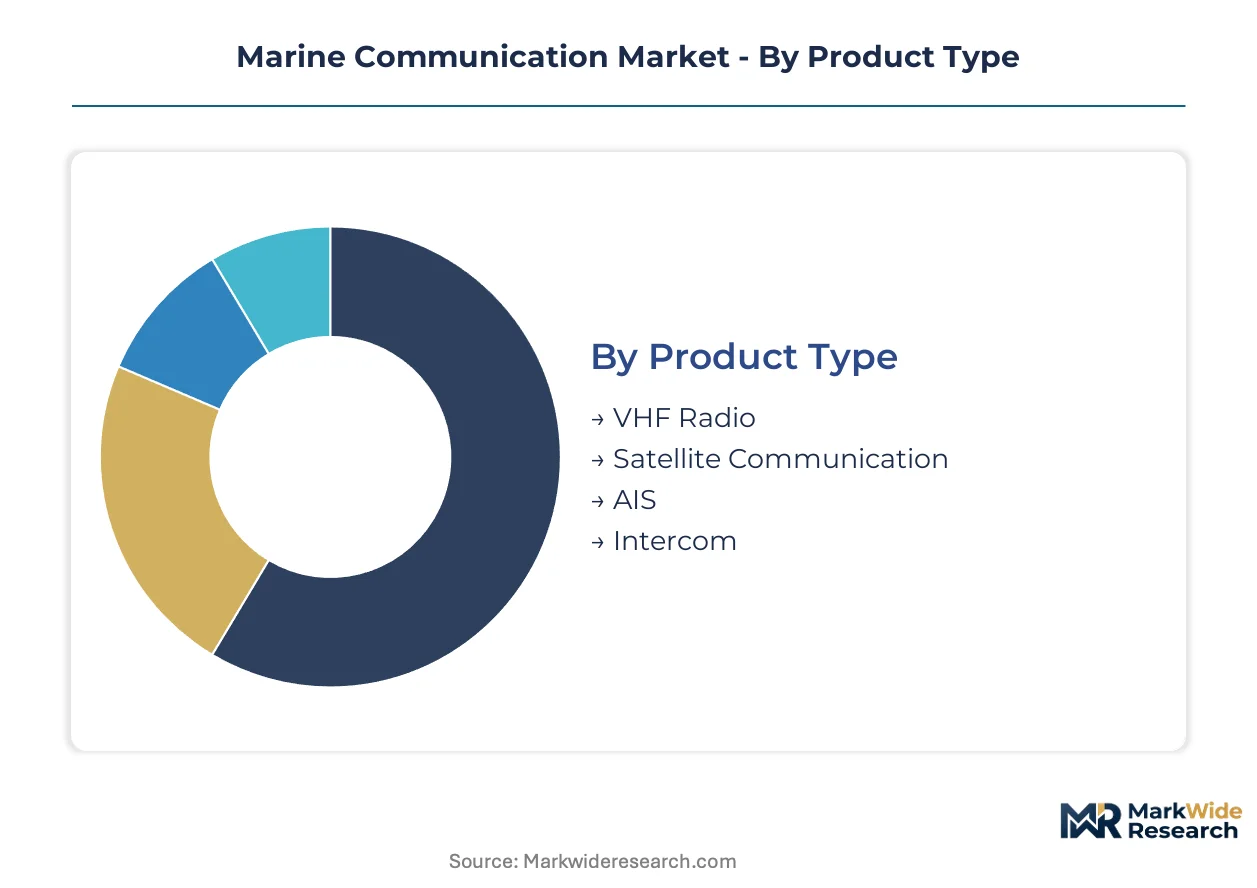
Marine communication procurement splits across four distinct dimensions, each governed by different certification regimes and operational requirements. Fleet operators prioritize SOLAS compliance in product selection while offshore energy contractors weight bandwidth throughput above regulatory minimums.
Product Type:
Supply concentration clusters around terminal manufacturers with in-house stabilized platform production and salt-corrosion testing facilities.
- Satellite Communication:Flat-panel electronically steered arrays and stabilized VSAT terminals deliver Ku/Ka-band connectivity for offshore energy fleets and polar-route vessels. Demand concentrates in Norway's North Sea corridor where floating production units require redundant backhaul. IMO SOLAS Chapter IV mandates are accelerating replacement of legacy Inmarsat-B installations.
- VHF Radio:Bridge-mounted transceivers operating in 156-174 MHz bands handle port maneuvering and collision avoidance. SOLAS-mandated GMDSS upgrades are displacing analog systems on commercial shipping routes through the English Channel and Singapore Strait.
- AIS:Automatic Identification System transponders broadcast vessel position, course, and speed to shore stations and nearby traffic. Coastal states mandate carriage on cargo vessels above gross tonnage thresholds.
- Intercom:Internal vessel communication networks integrate with public address and general alarm systems for crew safety coordination.
Today's leader: Satellite Communication. Tomorrow's challenger: VHF Radio.
Technology:
Cost tier stratification separates military-grade encrypted systems from commercial shipping's regulatory-minimum configurations.
- Satellite-Based:L-band constellations from Iridium Communications cover polar latitudes where geostationary satellites fail, while Ku/Ka-band VSAT delivers broadband for crew welfare and operational data. Offshore drilling contractors in the Barents Sea specify dual-orbit terminals for redundancy.
- Digital Communication:Software-defined radio architectures replace analog signal processing in bridge electronics refreshes. GMDSS modernization mandates from IMO are forcing fleet-wide upgrades across container lines flagged in Panama and Liberia.
- Radio Communication:MF/HF systems maintain distress alerting capability beyond VHF line-of-sight limits for ocean-crossing traffic.
- VoIP:Voice-over-IP integration reduces satellite bandwidth costs for crew calling services on long-haul routes.
Satellite-Based systems anchor current revenue. Digital Communication is climbing the fastest as analog sunset deadlines approach.
Application:
Volume concentration tracks the global fleet composition, with container shipping and fishing vessels representing the installed base majority.
- Commercial Shipping:Container lines, tanker operators, and bulk carriers require continuous connectivity for fleet management, weather routing, and regulatory reporting. Asia-Pacific flagged fleets above five thousand vessels are unbundling hardware procurement from airtime contracts.
- Search and Rescue:EPIRB and SART carriage mandates on cargo vessels above three hundred gross tons create regulatory-anchored demand with premium pricing tiers. Coast guard agencies specify hardened terminals for SAR coordination.
- Navigation:Bridge-integrated systems support collision avoidance, pilotage, and traffic separation scheme compliance.
- Fishing:Mid-size fleets face cost constraints on stabilized VSAT terminals, limiting adoption to larger industrial operators.
Commercial Shipping dominates volume. Search and Rescue commands margin premiums.
End User:
Customer type determines procurement sophistication, with integrated shipping companies operating separate technical departments from owner-managed fishing fleets.
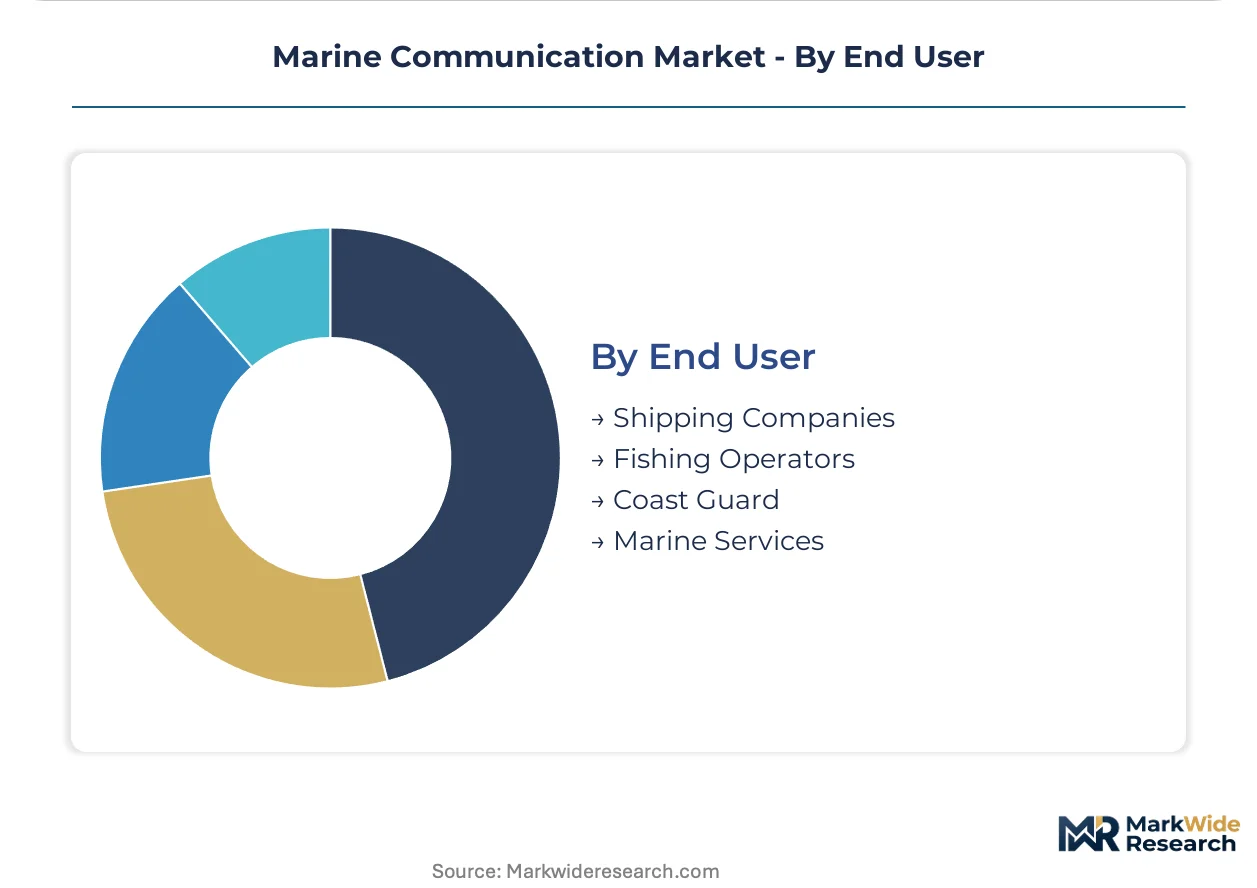
- Shipping Companies:Container lines and tanker operators issue technical specifications for newbuild contracts and coordinate fleet-wide retrofit programs. Procurement teams separate antenna RFPs from bandwidth agreements, reversing legacy bundled models.
- Coast Guard:National maritime agencies specify encrypted, dual-use terminals with military-grade availability requirements. FCC licensing enforcement for U.S.-flagged vessels and EU Radio Equipment Directive compliance shape vendor selection.
- Fishing Operators:Fleet owners prioritize cost minimization on regulatory-minimum VHF and AIS installations, with limited VSAT penetration outside industrial segments.
- Marine Services:Tug operators, pilotage providers, and port authorities maintain localized communication networks for harbor operations.
Shipping Companies drive technology adoption. Coast Guard requirements set performance ceilings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's North Sea shipping corridor anchors procurement concentration for marine communication terminals. Offshore energy operators in the Barents Sea drive demand for redundant Ku/Ka-band VSAT systems. Polar route traffic through Arctic waters intensifies L-band satellite requirements.
United States
Container lines flagged in the United States operate multi-thousand vessel fleets requiring continuous connectivity for regulatory reporting. The FCC enforces spectrum licensing for U.S.-flagged vessels under maritime communication rules. Houston's offshore energy cluster drives procurement for drilling support vessels and floating production units.
Norway
Floating production units in the North Sea require redundant backhaul systems for operational continuity. The Norwegian Maritime Authority enforces strict type-approval timelines for next-generation satellite terminals. Bergen and Stavanger host concentrated procurement teams for offshore energy fleet connectivity upgrades.
Japan
Coastal shipping routes through the Tokyo Bay and Osaka Bay corridors mandate GMDSS-compliant bridge electronics. The country's national telecommunications regulator compresses certification windows for satellite terminal imports. Yokohama's port authority coordinates fleet-wide retrofit programs for domestic container operators.
South Korea
Shipyards in Ulsan and Busan specify integrated communication systems for newbuild contracts across tanker and bulk carrier segments. National regulators tightened type-approval requirements for foreign-manufactured satellite equipment entering Korean waters. Daewoo and Hyundai heavy industries anchor terminal procurement for export vessels.
United Kingdom
Traffic separation schemes in the English Channel drive collision-avoidance communication upgrades for commercial shipping. The Maritime and Coastguard Agency enforces SOLAS Chapter IV compliance through port state control inspections. Southampton and Felixstowe container terminals coordinate fleet management connectivity for Asia-Europe trade lanes.
Marine Communication Market Competitive Environment
Portfolio diversification dominates the current landscape as terminal manufacturers expand beyond hardware into airtime service arrangements. The vendor base splits between satellite constellation operators, stabilized platform specialists, and electronics-integrated defense contractors. Three strategic archetypes prevail: constellation owners controlling orbital infrastructure, terminal fabricators with in-house gyroscopic stabilization, and diversified aerospace groups leveraging dual-use military contracts. M&A activity concentrates on antenna technology acquisitions, while geographic expansion targets polar-route service corridors.
Among constellation-based operators, Iridium Communications occupies a position representing L-band polar coverage infrastructure. Cobham SATCOM exemplifies the stabilized terminal fabrication archetype through its in-house production capabilities. Intellian Technologies anchors the multi-orbit antenna convergence tier with systems tracking geostationary and low-earth-orbit constellations.
| Leading Market Players |
|---|
| Iridium Communications |
| Inmarsat |
| Cobham SATCOM |
| Leonardo |
| Viasat |
| Intellian Technologies |
| Garmin Ltd. |
| ST Engineering |
| KVH Industries |
| Others |
Value Chain & Pricing Dynamics
L-band satellite transponder lease rates cascade through terminal manufacturing into three-tier pricing structure across premium, standard, and economy levels. Fiber-optic component spot prices in Asian electronics hubs compress margins for hybrid RF-over-fiber architectures, forcing procurement teams toward multi-year stabilization platform contracts.
Pricing Analysis
Input-cost pass-through from precision gyroscopic platforms and carbon-fiber radomes stratifies pricing across certification tiers. SOLAS-mandated GMDSS terminals command premium positioning above recreational-grade VHF units, while flat-panel electronically steered arrays extract value from reduced maintenance intervals. Pricing pressure stems from Japan and South Korea's compressed type-approval timelines, which elongate product development cycles. Mid-size fishing fleets exhibit acute price sensitivity, whereas offshore energy contractors prioritize bandwidth throughput over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for stabilized VSAT terminals mandate multi-supplier qualification across Norway, South Korea, and the United States. Semiconductor beamforming chips, precision gyroscopic sensors, and salt-corrosion-resistant radome composites anchor component dependencies. Single-source vulnerability concentrates in L-band satellite constellation access, where Iridium Communications maintains polar coverage exclusivity. Distribution runs through shipyard-integrated procurement channels for newbuild contracts and specialized marine electronics distributors for retrofit fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arctic corridor terminal demand in Norway outpaces Southeast Asian price competition due to stricter IMO SOLAS enforcement and higher certification costs, creating geographic-arbitrage opportunities for dual-orbit antenna specialists.
For Market Incumbents: Anticipate flat-panel electronically steered arrays displacing mechanically stabilized dishes by securing semiconductor foundry partnerships for solid-state beamforming chips. Defend against unbundled hardware-airtime procurement by embedding connectivity management platforms into terminal firmware. Lock shipyard relationships in Ulsan and Busan through multi-year newbuild specification agreements. For New Entrants and Emerging Players: Direct-to-vessel digital sales channels bypass legacy marine electronics distributor markups for mid-size fishing fleet segments. White-space concentrates in polar-route L-band terminal retrofit markets where geostationary coverage fails. Target expedition cruise operators with rental-model VSAT terminals paired with seasonal airtime flexibility. For Investors and Strategic Acquirers: Asymmetric upside sits with multi-orbit antenna convergence specialists holding dual geostationary and low-earth-orbit tracking patents. Five-to-ten year viability hinges on WRC spectrum reallocation outcomes and legacy L-band service sunset timing. Acquisition targets should exhibit in-house gyroscopic stabilization production and salt-corrosion testing facilities. Watch FCC maritime spectrum licensing decisions as inflection indicators for U.S.-flagged fleet upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Orbit Antenna Convergence | Single-radome systems tracking both GEO and LEO constellations open retrofit markets for legacy Inmarsat-B replacements. |
| Shipyard Integration Partnerships | Ulsan and Busan heavy industries anchor terminal procurement specifications for export tanker and bulk carrier newbuilds. |
| SOLAS Certification Fast-Track | Compressed Japan and South Korea type-approval timelines reward pre-positioned regulatory affairs capabilities. |
| Fiber-Optic Backhaul Transition | Hybrid RF-over-fiber architectures cut signal loss across superstructures and compress installation timelines. |
| Unbundled Hardware-Airtime Model | Asia-Pacific container lines separating antenna RFPs from bandwidth agreements reverse legacy bundled procurement. |
Study Parameters
Bottom-up vessel-type modeling reconciled against top-down terminal shipment tracking forms the analytical core. Primary interviews with fleet technical managers, shipyard procurement officers, marine electronics distributors, and coast guard specification engineers combined with secondary validation from IMO SOLAS amendment records, FCC maritime licensing databases, customs trade data, and shipyard order books. Top-down triangulation against satellite operator subscriber disclosures and regional port authority fleet registry data anchored volume estimates.
Historical trendline analysis across vessel deployment patterns and terminal replacement cycles informed projection frameworks. Segmentation dimensions modeled include product type, technology architecture, application severity, and end-user procurement sophistication, with vessel class and regulatory compliance tier as marine-specific overlays. CAGRs derived from fitted trend extrapolation adjusted for IMO mandate implementation schedules and spectrum reallocation conference outcomes. Polar route traffic growth and offshore energy fleet expansion served as industry-specific demand inputs.
The model assumes a particular technology adoption path; alternative pathways for electronically steered array penetration would alter the outlook if flat-panel costs fail to achieve parity with mechanical stabilization. Forecasts reflect assumptions on IMO enforcement consistency, WRC spectrum decisions, and shipyard production schedules. Deviation in Japan or South Korea regulatory timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Maritime Information Market
Marine
Marine Gas Oil Market
Marine
Azimuth Thrusters Market
Marine
Marine Suspension Seat Bases Market
Marine
Electric Ship Market
Marine
Commercial Hovercraft Market
Marine
Marine Electronics Market
Marine
Hydrofoil Market
Marine
Mooring Ropes Market
Marine
Recreational Vessel Battery Market
Marine
Marine Filter Market
Marine
Marine Big Data Market
Marine
Marine Pipes Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Salvage Services Market
Marine
Dynamic Positioning System Market