
 Buoys and Beacon Market | 2026-2036
Buoys and Beacon Market Size, Share, and Industry Trends Forecast 2026-2036
Buoys and Beacon Market Insights
Offshore energy developers are unwinding traditional port-authority dominance in beacon procurement. Sealite Pty Ltd leverages its solar-powered product specialization to compete across Australasian and Middle Eastern installations. James Fisher and Sons plc anchors its position through integrated marine service capabilities that extend beyond hardware into deployment and maintenance contracts.
Buoys and beacons are marine navigation aids engineered to specific IALA visibility ranges, with modern units incorporating photovoltaic cells, radar reflectors, and GPS transponders to mark channels, hazards, and offshore structures for commercial and recreational vessels. Smart beacons and GPS-enabled technology segments lead margin capture as operators replace legacy battery-dependent units with autonomous, remotely monitored systems. Composite materials and radar-reflective configurations represent the fastest-growing structural categories, driven by corrosion resistance requirements and collision-avoidance mandates in high-traffic sealanes.
The International Maritime Organization, IALA, and national maritime safety administrations collectively shape product certification, placement protocols, and energy-efficiency benchmarks that determine market access across coastal jurisdictions. SOLAS convention amendments and local waterway authority specifications force continuous R&D investment in visibility range and structural integrity. Stakeholders must monitor evolving autonomous vessel traffic management requirements, as unmanned shipping corridors will demand next-generation beacon networks with machine-readable signaling capabilities.
Market Dynamics
Offshore wind farm operators now account for a larger share of beacon procurement than traditional port authorities, compressing deployment timelines and demanding GPS-integrated, remotely monitored units that legacy battery systems cannot satisfy.
Growth Catalysts
- China's coastal infrastructure expansion:Massive port modernization and fishery zone demarcation programs under the 14th Five-Year Plan are generating sustained volume demand for composite-hull buoys with radar reflectors.
- SOLAS convention visibility mandates:The International Maritime Organization's updated Aids to Navigation guidelines are forcing replacement cycles for legacy units that fail enhanced durability and luminosity thresholds.
- Photovoltaic cell integration:Solar-powered autonomous beacons eliminate battery replacement logistics, cutting lifecycle operating costs for offshore platform operators managing remote installations.
Market Restraints
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers creates input cost volatility and geopolitical exposure for beacon producers assembling energy storage modules.
- High-grade polymer resin pricing:Specialized corrosion-resistant composites require petrochemical feedstocks subject to energy market fluctuations, squeezing margin on standard product lines.
- IALA certification timelines:Multi-year type-approval processes for new visibility range specifications delay product launches and tie up R&D capital without revenue offset.
Strategic Opportunities
- Autonomous vessel corridor infrastructure:Machine-readable beacon networks for unmanned shipping lanes represent greenfield deployment potential in Singapore, Rotterdam, and Shanghai pilot zones.
- Integrated marine service contracts:Bundling hardware with deployment, maintenance, and remote monitoring creates recurring revenue streams that pure equipment sales cannot match.
- Dual-use defense applications:Naval perimeter marking and submarine channel demarcation programs in Australia, Japan, and the United Kingdom are accelerating procurement of hardened, GPS-enabled units.
Industry Challenges
- Marine electronics technician scarcity:Specialized skills for photovoltaic system diagnostics and GPS transponder calibration are concentrated among aging workforces in established maritime economies.
- Legacy beacon network interoperability:Hybrid installations combining new smart units with existing battery-dependent infrastructure create synchronization failures and visibility range mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buoys and Beacon Market |
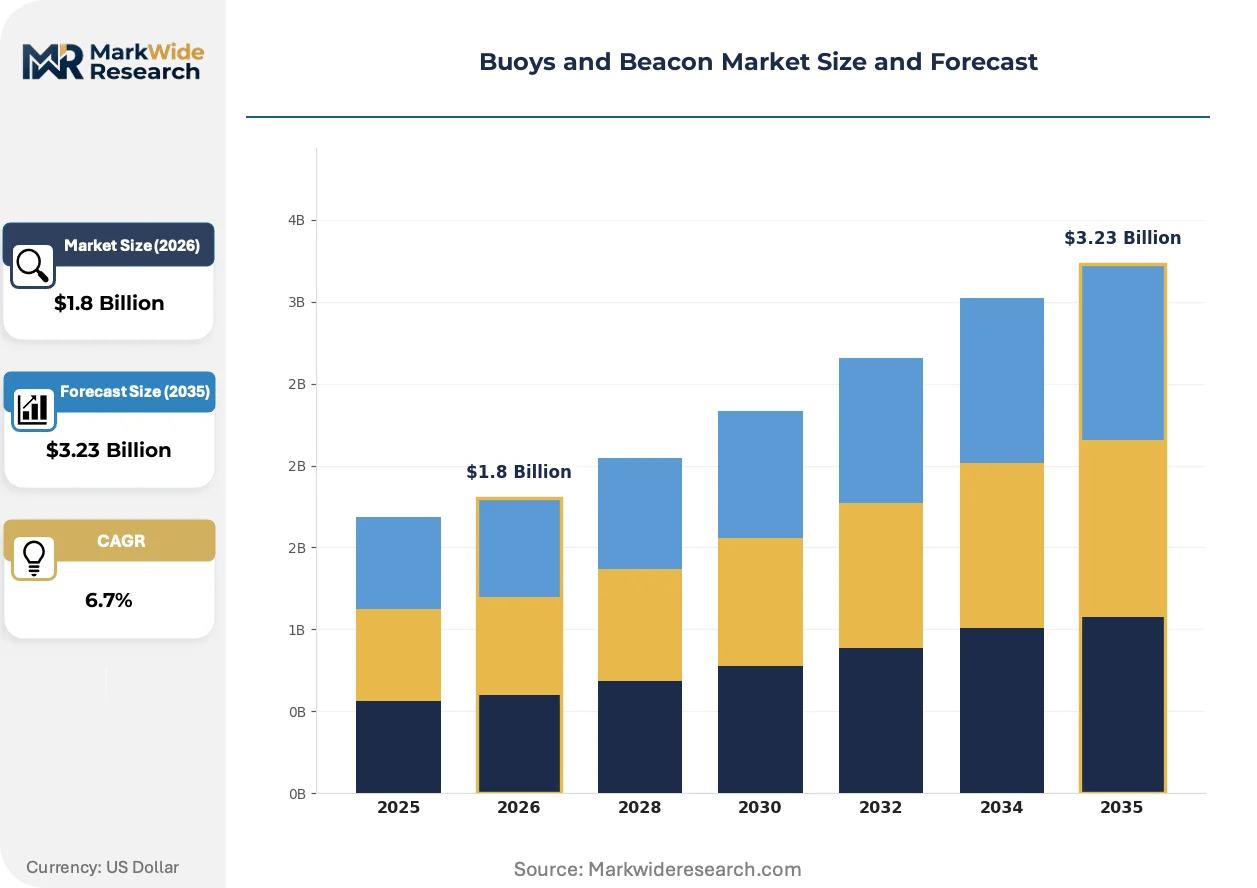
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Buoys, Fixed Buoys, Smart Beacons, Lighted Beacons Application: Navigational Aid, Fishing, Aquaculture, Port Management Material: Polyethylene, Metal, Composite, PVC Technology: Solar Powered, GPS Enabled, Wireless, Radar Reflective |
| Companies Covered | Sealite Pty Ltd, James Fisher and Sons plc, Mobilis, Xylem, Rolyan Buoys, RYOKUSEISHA CORPORATION, Almarin, Carmanah Technologies Corp, Woori Marine Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buoys and Beacon Market Trends and Innovations
Beacon architecture is pivoting from passive marking devices to active data nodes, with photovoltaic autonomy and machine-readable signaling protocols redefining procurement specifications across commercial and defense applications.
Photovoltaic-integrated smart beacons with embedded GPS transponders and radar reflectors are displacing legacy battery-dependent units in offshore wind farm installations. European and Chinese developers now specify autonomous, remotely monitored systems as baseline requirements, compressing replacement cycles from ten-year intervals to five-year technology refresh schedules. This displacement is eroding the installed base of conventional lanterns and forcing incumbent suppliers to reengineer product architectures around solar autonomy.
The International Maritime Organization's SOLAS convention amendments and IALA's updated visibility range standards are tightening structural integrity and luminosity benchmarks for all new installations. Manufacturers must now certify composite hulls for extreme weather endurance and demonstrate GPS accuracy within tighter tolerances to gain type approval. Offshore energy segments in the North Sea and South China Sea are experiencing the steepest compliance cost escalations as operators race to meet accelerated replacement deadlines.
Long-term service contracts bundling hardware, deployment, and predictive maintenance are displacing transactional equipment sales in procurement portfolios. Offshore wind developers and port authorities in Germany, the Netherlands, and the United Kingdom now favor integrated marine service providers over pure manufacturers, shifting margin capture toward lifecycle performance guarantees. This reconfiguration is visible most acutely in North Sea installations where total-cost-of-ownership calculations dominate vendor selection criteria.
Buoys and Beacon Market Segmentation
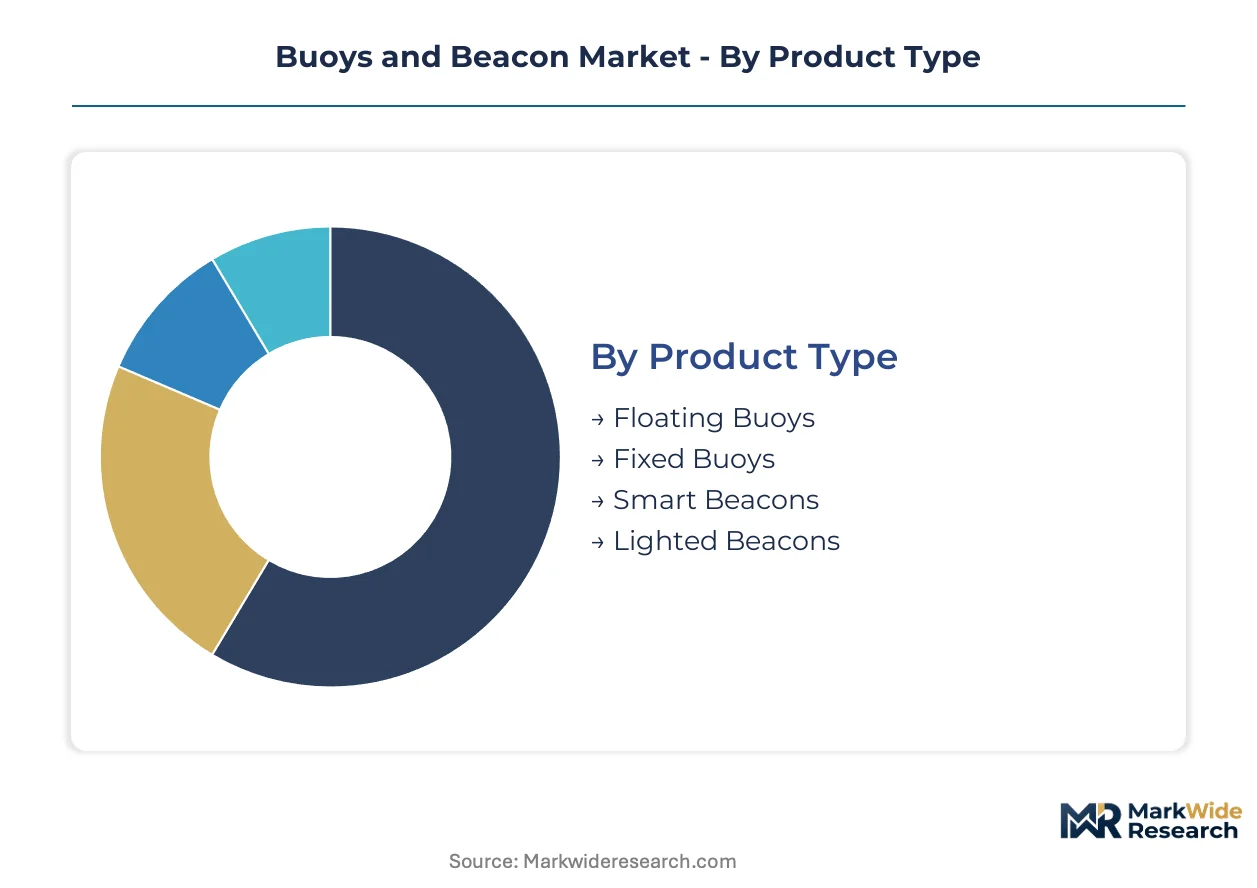
Segmentation in the Buoys and Beacon Market reveals how procurement priorities diverge across marine infrastructure stakeholders. Product architecture, application context, and energy autonomy each create distinct margin pools that suppliers must target with specialized offerings.
Product Type:
Margin concentration tracks toward autonomous, energy-independent units that reduce lifecycle operating costs for remote installations.
- Smart Beacons:Photovoltaic-integrated units with embedded GPS transponders and remote monitoring capability. Offshore wind farm operators in Germany and the Netherlands specify these as baseline requirements, compressing replacement cycles and eliminating battery logistics.
- Floating Buoys:Composite-hull channel markers with radar reflectors and IALA-certified visibility ranges. China's coastal infrastructure expansion and fishery zone demarcation programs under the 14th Five-Year Plan drive sustained volume procurement.
- Fixed Buoys:Moored installations for permanent hazard marking in high-traffic sealanes.
- Lighted Beacons:Traditional lantern-based units serving legacy port authority networks.
The dominant share belongs to Floating Buoys, while Smart Beacons is closing the gap fastest.
Application:
End-use concentration has shifted as offshore energy developers overtake traditional maritime authorities in procurement velocity.
- Navigational Aid:SOLAS-mandated channel marking and hazard identification for commercial vessel traffic. The International Maritime Organization's updated visibility and durability standards force accelerated replacement cycles for legacy installations.
- Port Management:Harbor entrance marking, berth allocation systems, and vessel traffic coordination infrastructure. Rotterdam and Shanghai port authorities specify GPS-integrated, remotely monitored units.
- Fishing:Gear location marking and zone boundary demarcation for licensed operations.
- Aquaculture:Farm perimeter marking and vessel exclusion zone enforcement.
Navigational Aid retains the largest installed base, though Port Management is expanding most quickly as automation investments accelerate.
Material:
Corrosion resistance requirements in saltwater environments drive material selection toward synthetic and engineered alternatives.
- Composite:Fiber-reinforced polymer formulations combining structural strength with UV and chemical degradation resistance. North Sea and South China Sea operators favor these for extreme weather endurance certification.
- Polyethylene:Rotationally molded hulls with impact resistance and low maintenance profiles. China's volume procurement for coastal infrastructure favors this cost-optimized category.
- Metal:Steel and aluminum constructions for heavy-duty permanent installations.
- PVC:Lower-cost options for temporary or shallow-water applications.
Composite materials command premium positioning, while Polyethylene dominates unit volume through standardization.
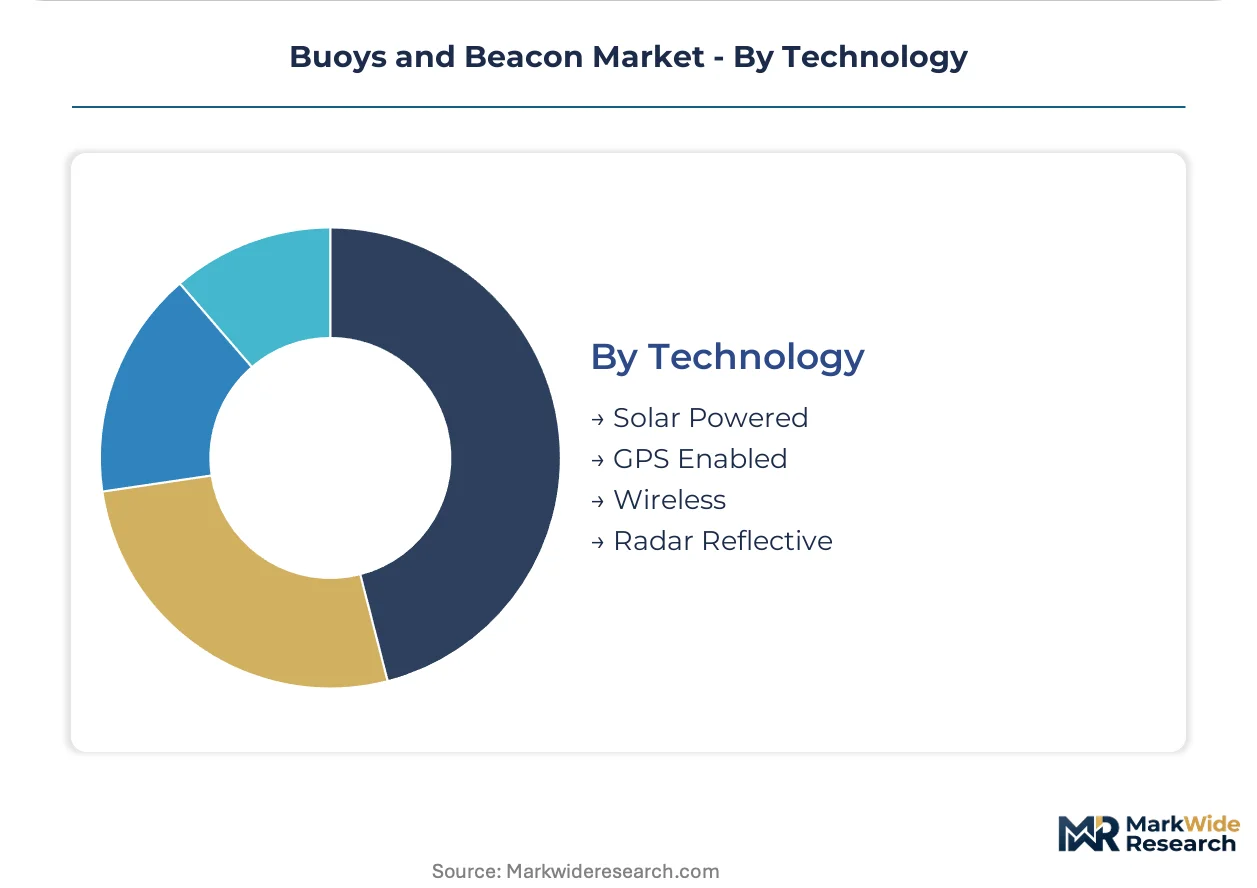
Technology:
Energy autonomy and machine-readable signaling protocols now determine competitive differentiation in procurement specifications.
- Solar Powered:Photovoltaic cell integration eliminating battery replacement logistics and enabling autonomous operation. Offshore platform operators managing remote installations prioritize these for lifecycle cost reduction.
- GPS Enabled:Precision positioning transponders supporting real-time location monitoring and autonomous vessel traffic management. Singapore and Rotterdam pilot zones for unmanned shipping corridors specify machine-readable beacon networks.
- Wireless:Radio-frequency communication links for remote diagnostics and status reporting.
- Radar Reflective:Collision-avoidance configurations enhancing vessel detection in high-traffic sealanes.
Solar Powered technology anchors current procurement, yet GPS Enabled systems are gaining share fastest as autonomous vessel infrastructure mandates crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam Maasvlakte port expansion and North Sea offshore wind interconnectors anchor European procurement velocity, while China's Yangtze River Delta port cluster drives volume concentration in Asia-Pacific.
China
Coastal infrastructure expansion under the 14th Five-Year Plan and fishery zone demarcation programs generate sustained demand for composite-hull buoys. SAMR enforces updated GB standards for marine navigation aid durability. Shanghai's Lingang New Area hosts concentrated manufacturing clusters supplying radar-reflective units for South China Sea installations.
Germany
North Sea offshore wind farm operators specify GPS-integrated, remotely monitored beacons as baseline procurement requirements. The Federal Maritime and Hydrographic Agency implements stringent BSH visibility range certifications. Bremerhaven and Cuxhaven anchor deployment service hubs supporting accelerated replacement cycles.
United States
Port modernization programs along the Gulf Coast and autonomous vessel pilot corridors in California drive smart beacon adoption. The Coast Guard enforces updated Aids to Navigation regulations under 33 CFR. Houston's maritime service cluster concentrates integrated deployment and maintenance contract capacity.
Japan
Dual-use defense applications for naval perimeter marking and commercial channel maintenance expand procurement scope. METI coordinates maritime safety technology standards through JIS certification frameworks. Nagoya's industrial corridor hosts specialized composite material fabrication for extreme weather endurance specifications.
United Kingdom
Offshore wind lease round expansions and Thames estuary port automation accelerate GPS-enabled beacon deployment. The Maritime and Coastguard Agency enforces SOLAS-aligned visibility mandates. Aberdeen's energy service cluster transitions expertise toward offshore renewable navigation infrastructure.
Buoys and Beacon Market Competitive Landscape
Concentration sits with integrated marine service providers and solar-powered product specialists rather than pure hardware manufacturers. The vendor base stratifies across three tiers: full-service contractors bundling deployment with lifecycle maintenance, photovoltaic-integrated beacon specialists, and regional composite hull fabricators serving standardized port authority specifications. Dominant competitive moves include geographic expansion through local deployment partnerships and backward integration into photovoltaic cell supply chains to reduce East Asian battery dependency.
Among Asia-Pacific specialists, RYOKUSEISHA CORPORATION and Woori Marine Co Ltd occupy positions emphasizing regional certification alignment and cost-optimized polyethylene hull production. Sealite Pty Ltd exemplifies the solar-autonomy archetype through its Australasian and Middle Eastern installation focus, while James Fisher and Sons plc anchors the integrated service tier by extending beyond hardware into predictive maintenance contracts. These three represent distinct strategic postures: regional scale fabrication, photovoltaic specialization, and lifecycle service bundling.
| Leading Market Players |
|---|
| Sealite Pty Ltd |
| James Fisher and Sons plc |
| Mobilis |
| Xylem |
| Rolyan Buoys |
| RYOKUSEISHA CORPORATION |
| Almarin |
| Carmanah Technologies Corp |
| Woori Marine Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month photovoltaic cell lead times from East Asian suppliers compress margin buffers for European beacon manufacturers while amplifying pricing power among integrated solar-autonomy specialists. This inventory pressure concentrates procurement leverage with composite hull fabricators that have secured captive photovoltaic supply through backward integration into cell assembly partnerships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IALA-certified smart beacons with GPS integration from radar-reflective composite buoys and basic polyethylene channel markers. Price differentiation hinges on certification grade and after-sales service bundling, with offshore wind developers least sensitive and municipal port authorities most responsive to unit economics. Pricing pressure stems from lithium battery cost volatility, forcing mid-tier suppliers toward solar-powered architectures to defend margin position.
Supply Chain Analysis
China and South Korea anchor photovoltaic cell and lithium battery production for beacon energy modules, while Germany and Japan specialize in GPS transponder calibration equipment. Raw material flows draw from petrochemical feedstocks for composite resins, rare earth elements for radar reflectors, and semiconductor-grade silicon for solar cells. Single-source vulnerability concentrates in East Asian battery cell manufacturing. Distribution runs through marine service contractors that bundle hardware with deployment logistics, displacing direct OEM-to-port-authority transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to offshore wind farm construction waves, with procurement velocity tied to North Sea and South China Sea lease round timing rather than steady-state replacement demand.
For Market Incumbents: Secure photovoltaic supply through upstream partnerships with East Asian cell manufacturers to neutralize lithium battery cost volatility threatening mid-tier margin structures. Deepen deployment service capabilities in Germany and the Netherlands where integrated marine contracts now dominate vendor selection, insulating against pure-hardware competitors.
For New Entrants and Emerging Players: Lead with machine-readable beacon architectures for autonomous vessel pilot corridors in Singapore and Rotterdam, where regulatory mandates for unmanned shipping infrastructure create specification windows unoccupied by legacy port-authority suppliers. Target defense dual-use applications in Australia and Japan through hardened GPS-enabled units for naval perimeter marking.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized composite fabrication capacity and dormant marine navigation aid product lines. Long-term viability favors specialists with captive solar-autonomy technology and recurring service contract revenue exceeding transactional equipment sales. Monitor IALA certification timeline acceleration as the inflection signal for product launch velocity and R&D capital efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Supply Integration | Backward integration into East Asian cell partnerships neutralizes lithium cost volatility for European manufacturers. |
| Machine-Readable Beacon Development | GPS-integrated units with autonomous vessel signaling protocols capture Rotterdam and Singapore pilot corridor specifications. |
| Integrated Service Contract Expansion | Bundling deployment and predictive maintenance with hardware displaces transactional sales in North Sea offshore wind procurement. |
| Dual-Use Defense Certification | Hardened beacon architectures for naval perimeter marking unlock Australia and Japan defense procurement channels. |
| Composite Material R&D Investment | Extreme weather endurance certification for fiber-reinforced hulls meets tightened SOLAS durability mandates in South China Sea installations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with port authority procurement managers, offshore wind farm development executives, marine service contract specialists, and IALA certification engineers. Secondary validation drew from SOLAS convention amendment texts, SAMR GB standard filings, BSH visibility range certifications, and customs trade data for composite hull and photovoltaic cell imports. Bottom-up volume triangulation across product type and application segments was cross-checked against top-down market sizing from energy autonomy technology adoption curves.
Across the analysis window, the forecasting framework modeled beacon procurement through segmentation dimensions spanning product architecture, energy technology, material composition, and end-use application intensity. CAGRs were derived from replacement cycle compression observations and offshore wind installation pipeline tracking. Industry-specific inputs included IALA type-approval timeline distributions and photovoltaic integration cost curves for remote platform applications.
The analysis sits within stated boundaries; outcomes outside sustained offshore wind capital commitment or accelerated autonomous vessel regulatory mandates would require recalibration. Forecasts reflect assumptions around lithium battery supply stability and composite resin pricing continuity. Recalibration cycles align with material shifts in SOLAS convention amendment schedules and offshore energy lease round announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Controllable Pitch Marine Propeller Market
Marine
Azimuth Thrusters Market
Marine
Shipbuilding Market
Marine
Marine Lighting Market
Marine
Marine Fasteners Market
Marine
LNG Bunkering Vessel Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Sea Skimmer Market
Marine
Marine Beacon Market
Marine
Submarine Propulsion Systems Market
Marine
Ship Heat Exchanger Market
Marine
Marine LED Lights Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Marine AIS Monitoring System Market
Marine
Deep-V Boat Market
Marine
India Boat Davits Market